
 NIR and Raman Spectroscopy Market | 2026-2036
NIR and Raman Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
NIR and Raman Spectroscopy Market Foresight
Direct distribution between spectroscopy manufacturers and pharmaceutical quality labs is reconfiguring as instrument vendors build embedded software subscription models. PerkinElmer Inc. leverages its informatics platform to sustain recurring revenue alongside hardware placements. HORIBA Ltd. anchors its position through specialized Raman microscopy systems for semiconductor failure analysis. Bruker Corporation differentiates via high-field NMR-Raman hyphenated configurations for academic research consortia.
NIR and Raman spectroscopy encompass non-destructive analytical techniques that exploit molecular vibrational modes, with NIR operating across 780–2500 nm wavelengths and Raman capturing inelastic light scattering shifts measured in wavenumbers. These methods serve primary industrial purposes in real-time chemical composition verification without sample destruction. Raman systems command premium positioning in pharmaceutical authentication workflows where water-insensitive detection matters. FT-NIR technology dominates food and beverage process monitoring installations due to established calibration transfer protocols. Quality control applications absorb the largest share of replacement demand as manufacturers retire dispersive UV-Vis platforms.
FDA process analytical technology guidelines and EMA's quality-by-design framework both mandate validated spectroscopic methods for continuous manufacturing transitions. EPA methods incorporating field-portable Raman for hazardous site characterization further expand environmental testing procurement. ISO 17025 accreditation requirements shape laboratory instrument purchasing criteria across regulated industries. Stakeholders must monitor evolving pharmacopeial standards for handheld device equivalency to benchtop systems.
Market Dynamics
Portable Raman instrumentation is compressing replacement cycles for benchtop UV-Vis systems as pharmaceutical manufacturers prioritize at-line raw material verification over central laboratory workflows.
Growth Catalysts
- FDA Process Analytical Technology:Mandatory validated spectroscopic methods for continuous manufacturing transitions pull demand from batch-release testing toward real-time release paradigms in oral solid dosage facilities.
- Semiconductor failure analysis:Advanced packaging architectures and 3D NAND stacking geometries require non-destructive chemical mapping at sub-micron resolution, anchoring specialized Raman microscopy placements.
- Food and beverage process monitoring:FT-NIR calibration transfer protocols enable standardized deployment across multi-site production networks without per-instrument model rebuilding.
Market Restraints
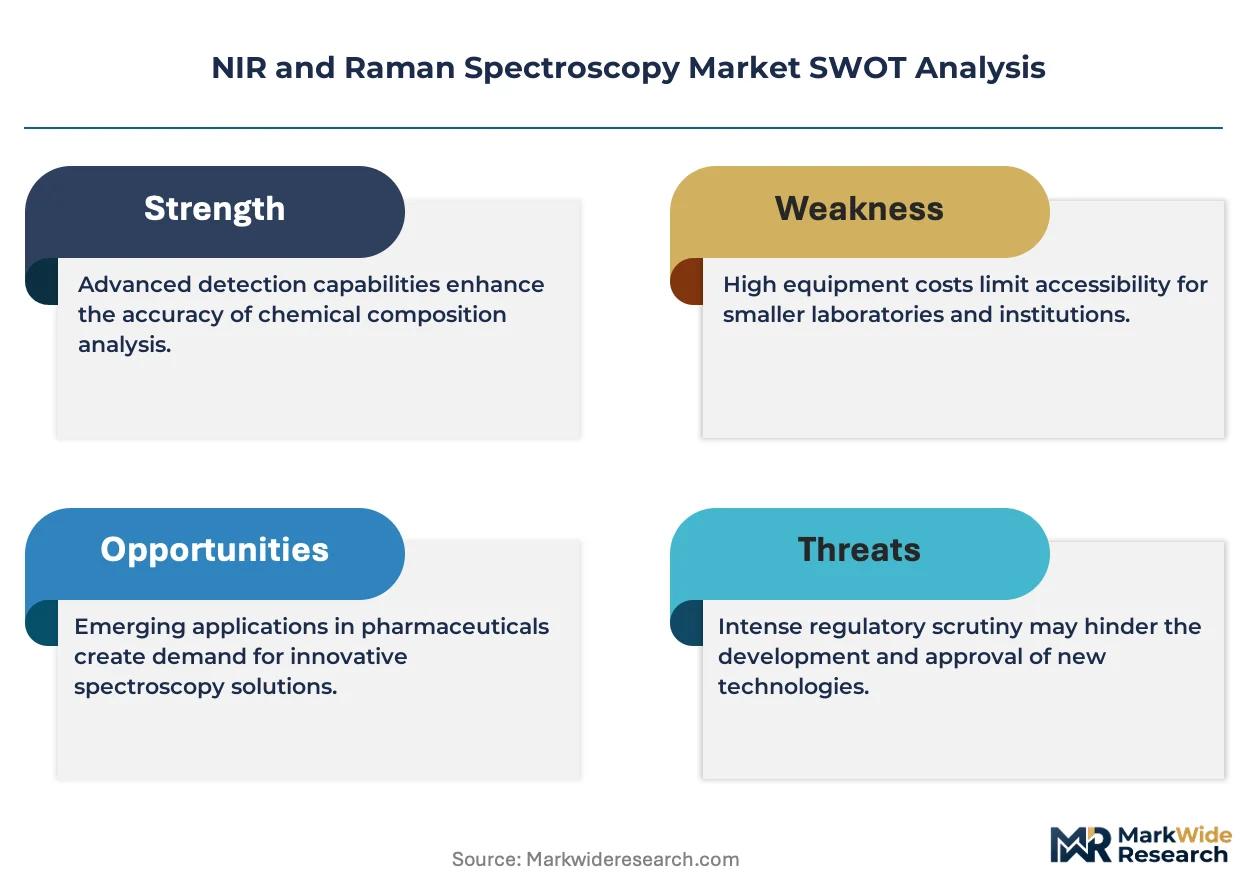
- Indium gallium arsenide detector costs:NIR array detector supply concentrates among Japanese and European component specialists, exposing instrument margins to rare earth price volatility and single-source procurement risk.
- Benchtop equivalency gaps:Handheld Raman devices face pharmacopeial skepticism regarding spectral resolution and signal-to-noise ratios for polymorph discrimination in active pharmaceutical ingredients.
- Laser safety classification:Class 3B and 4 laser requirements trigger facility modification costs and operator certification burdens that slow portable adoption in academic and small contract laboratory settings.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's alignment with ICH Q12 lifecycle management guidelines creates openings for validated spectroscopic methods in generic API export facilities serving regulated markets.
- Carbon fiber composite inspection:Aerospace tier suppliers adopt portable Raman for resin cure verification and defect mapping in thermoset manufacturing, bypassing destructive mechanical testing.
- Cloud-native calibration models:Subscription-based chemometric platforms enable remote model updates and multi-site standardization, converting capital equipment sales into recurring revenue streams.
Industry Challenges
- Chemometric expertise scarcity:Multivariate calibration development and model maintenance require specialized statistical competencies that outpace university analytical chemistry curricula.
- Legacy LIMS integration:Spectroscopy data formats and metadata schemas vary across instrument vendors, forcing custom middleware development for enterprise quality management system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NIR and Raman Spectroscopy Market |
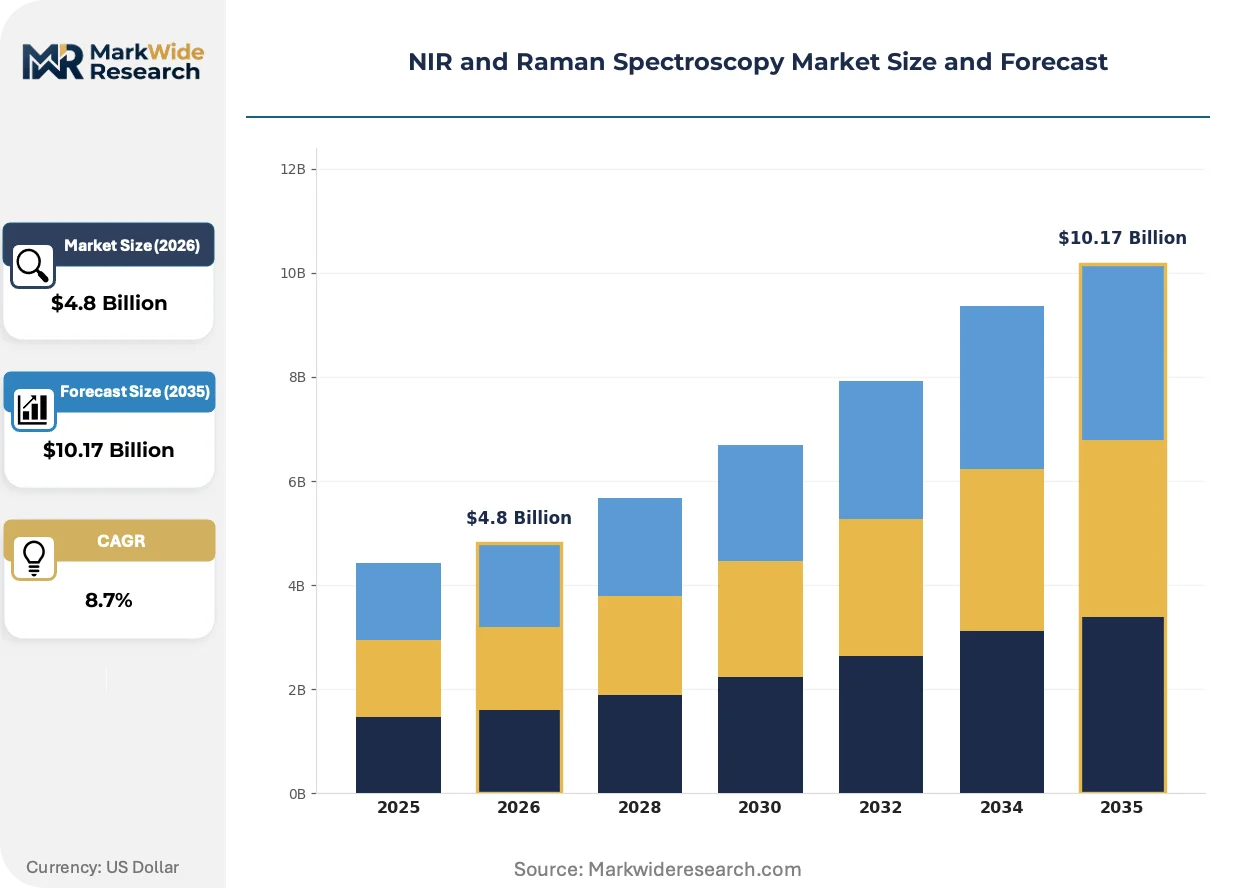
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NIR Systems, Raman Systems, Hyphenated Systems, Accessories Technology: FT-NIR, Dispersive NIR, Near-Infrared, UV-Vis End User: Pharmaceuticals, Food & Beverage, Chemicals, Environmental Testing Application: Quality Control, Process Monitoring, Material Identification, Quantitative Analysis |
| Companies Covered | PerkinElmer Inc., HORIBA Ltd., Thermo Fisher Scientific Inc., Merck KGaA, Danaher Corporation, Agilent Technologies Inc., Shimadzu Corporation, ABB Ltd., Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NIR and Raman Spectroscopy Market Shifts & Advancements
Hyphenated instrumentation and embedded intelligence are compressing the boundary between data acquisition and decision execution, eliminating manual interpretation steps that previously gated throughput in high-volume screening environments.
Spatially offset Raman spectroscopy (SORS) is rendering obsolete destructive sampling protocols for through-container identification of liquids and gels in pharmaceutical incoming goods inspection. Customs and border security agencies in the United States and European Union deploy handheld SORS units for rapid threat detection without package opening. The technology compresses inspection timelines from hours to seconds in high-throughput logistics hubs.
EMA's quality-by-design framework mandates multivariate process understanding and control strategy documentation for marketing authorization applications, elevating spectroscopic PAT from optional efficiency tool to regulatory requirement. Continuous manufacturing facility approvals in Ireland, Belgium, and the Netherlands increasingly specify NIR or Raman as primary analytical control methods. Generic manufacturers retrofit existing batch facilities to demonstrate equivalent process knowledge for abbreviated new drug application pathways.
Service unbundling is fragmenting traditional instrument vendor relationships as pharmaceutical quality laboratories procure validation, training, and application support from third-party analytical service providers. Contract research organizations in the Research Triangle and Boston biopharma corridor build captive spectroscopy capabilities that bypass manufacturer service contracts entirely. This disintermediation pressures instrument vendors to embed remote diagnostics and predictive maintenance as standard features rather than premium add-ons.
NIR and Raman Spectroscopy Market Segmentation
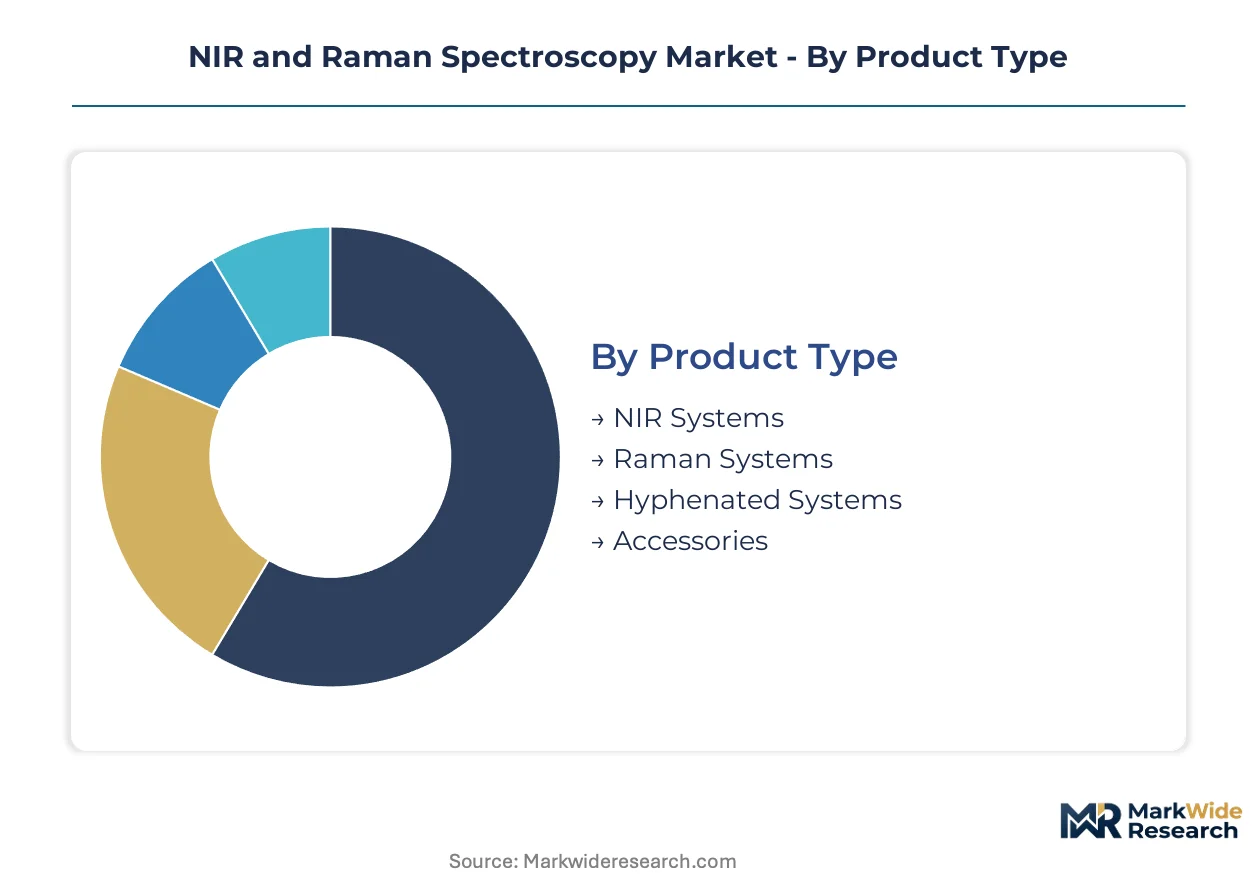
Segmentation reveals how NIR and Raman technologies diverge across industrial workflows, with pharmaceutical quality control demanding benchtop precision while food manufacturing prioritizes calibration portability. The four-dimensional taxonomy below maps where hardware investments concentrate versus where software and service margins expand.
Product Type:
The use-case spectrum spans from laboratory-grade hyphenated configurations to handheld field units, with each product tier commanding distinct service attach rates and replacement cycles.
- Raman Systems:These instruments capture inelastic light scattering shifts measured in wavenumbers, enabling water-insensitive detection critical for polymorph discrimination in active pharmaceutical ingredients. Pharmaceutical manufacturers in Massachusetts and North Carolina deploy portable Raman devices for at-line raw material verification, compressing inspection timelines from central laboratory workflows to dockside decision points.
- NIR Systems:Operating across 780–2500 nm wavelengths, these systems exploit molecular overtone and combination vibrations for real-time chemical composition analysis. FT-NIR technology dominates food and beverage process monitoring installations across multi-site production networks, where established calibration transfer protocols eliminate per-instrument model rebuilding costs.
- Hyphenated Systems:NMR-Raman and other coupled configurations serve academic research consortia requiring correlated structural and chemical information from single sample presentations.
- Accessories:Fiber optic probes, sampling interfaces, and specialized detectors extend instrument utility without full platform replacement.
Established volume favors NIR Systems; emerging adoption favors Raman Systems.
Technology:
Cost tier differentiation separates premium interferometer-based platforms from dispersive alternatives, with detector material costs driving procurement decisions at the component level.
- FT-NIR:Fourier-transform interferometry delivers superior signal-to-noise ratios and wavelength precision for quantitative applications. Food manufacturers in Belgium and Ireland specify FT-NIR as primary analytical control methods for continuous manufacturing facility approvals under EMA quality-by-design frameworks.
- Dispersive NIR:Grating-based systems offer lower capital entry points for routine qualitative screening where extreme precision is not mandated.
- Near-Infrared:Broadband source configurations serve general-purpose laboratory applications with flexible sampling accessories.
- UV-Vis:Legacy dispersive platforms face replacement pressure from portable Raman as manufacturers retire central laboratory workflows.
Margin concentration sits with FT-NIR; volume expansion tracks Dispersive NIR.
End User:
Customer type determines validation burden and service contract structure, with regulated industries absorbing premium pricing for compliance documentation.
- Pharmaceuticals:FDA process analytical technology guidelines mandate validated spectroscopic methods for continuous manufacturing transitions. Generic API export facilities in India align with ICH Q12 lifecycle management guidelines to access regulated markets, creating demand for qualified instrumentation.
- Food & Beverage:FT-NIR calibration transfer protocols enable standardized deployment across production networks, with EPA methods incorporating field-portable verification for supply chain integrity.
- Chemicals:Process analytical technology deployments support real-time release paradigms in continuous flow reactor operations.
- Environmental Testing:Field-portable Raman systems serve hazardous site characterization under EPA methods, expanding procurement beyond laboratory confines.
Regulatory intensity favors Pharmaceuticals; deployment scale favors Food & Beverage.
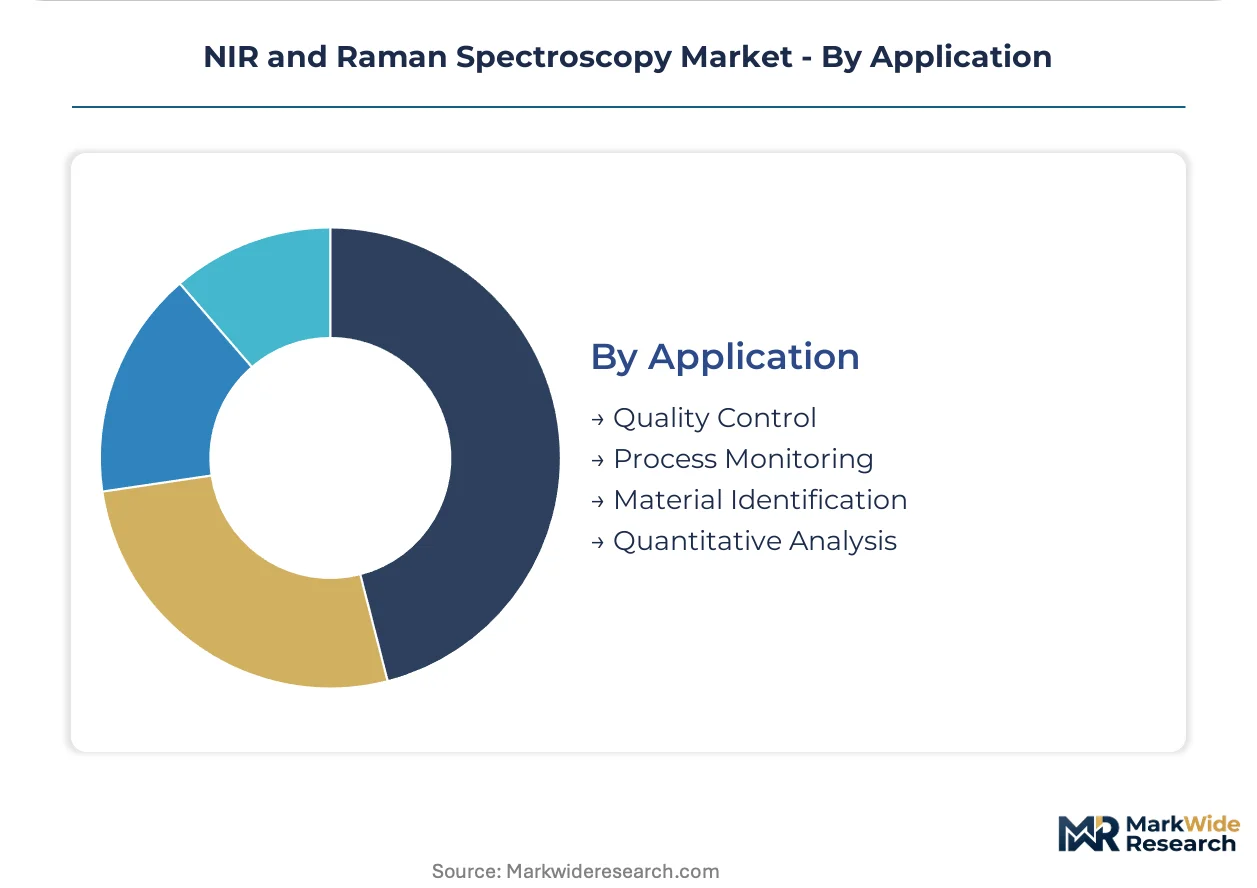
Application:
Maturity gradients separate established quality control routines from emerging process integration opportunities, with data handling requirements escalating across the spectrum.
- Quality Control:Batch-release testing and incoming goods verification absorb the largest share of replacement demand as manufacturers retire legacy UV-Vis platforms. ISO 17025 accreditation requirements shape laboratory instrument purchasing criteria across regulated industries in the United States and European Union.
- Process Monitoring:Real-time analytical control methods gain regulatory acceptance for continuous manufacturing transitions, with NIR and Raman specified in facility approvals across Ireland, Belgium, and the Netherlands.
- Material Identification:Spatially offset Raman spectroscopy enables through-container identification without package opening, deployed by customs agencies for rapid threat detection.
- Quantitative Analysis:Multivariate calibration development requires specialized statistical competencies that outpace university analytical chemistry curricula, creating service opportunities.
Replacement cycles dominate Quality Control; regulatory tailwinds accelerate Process Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where pharmaceutical manufacturers absorb premium instrument costs, while procurement in India and China operates on compressed margins that favor dispersive platforms over interferometer-based systems.
United States
FDA process analytical technology guidelines pull demand toward real-time release paradigms in oral solid dosage facilities. The EPA incorporates field-portable Raman methods for hazardous site characterization, expanding environmental testing procurement. Biopharma clustering around Boston and the Research Triangle anchors specialized Raman microscopy placements for semiconductor failure analysis and pharmaceutical authentication workflows.
Germany
Automotive tier suppliers adopt portable Raman for carbon fiber composite inspection in resin cure verification applications. REACH compliance documentation and CE marking requirements shape laboratory instrument purchasing criteria across regulated chemical and pharmaceutical industries. Industrial concentration in Bavaria and Baden-Württemberg supports FT-NIR deployments for continuous manufacturing transitions in specialty chemical production.
India
Generic API export facilities serving regulated markets create demand for qualified spectroscopic instrumentation. CDSCO alignment with ICH Q12 lifecycle management guidelines mandates validated methods for abbreviated new drug application pathways. Manufacturing concentration in Maharashtra and Gujarat drives procurement of dispersive NIR systems for cost-sensitive quality control environments.
China
NMPA regulatory harmonization with ICH standards elevates spectroscopic process analytical technology from optional efficiency tool to marketing authorization requirement. Dual carbon goals accelerate adoption of non-destructive testing methods that eliminate destructive mechanical testing waste. Yangtze River Delta pharmaceutical and electronics manufacturing clusters anchor demand for benchtop Raman systems in polymorph discrimination applications.
Japan
PMDA quality-by-design framework implementation drives continuous manufacturing facility approvals specifying NIR or Raman as primary analytical control methods. JIS standards for laboratory instrumentation shape procurement criteria across pharmaceutical and food testing industries. Kanto region concentration of analytical instrument manufacturers sustains domestic supply chain integration for detector and laser component sourcing.
NIR and Raman Spectroscopy Market Competitive Landscape
Platform specialists and diversified analytical conglomerates split the market between embedded software subscription models and hardware-centric revenue streams. The vendor base concentrates around three strategic archetypes: informatics-integrated platform vendors, specialized microscopy system builders, and hyphenated configuration providers. M&A activity targets chemometric software capabilities, while geographic expansion focuses on CDSCO-aligned facilities in India and NMPA-registered sites in China.
Among diversified analytical conglomerates, Thermo Fisher Scientific Inc., Danaher Corporation, and Agilent Technologies Inc. exemplify the scale-driven archetype that competes through portfolio breadth and service network density. These entities occupy positions where recurring revenue from consumables and support contracts offsets hardware margin compression. PerkinElmer Inc. and HORIBA Ltd. represent the specialization vector, anchoring differentiated positions through informatics platform integration and Raman microscopy expertise respectively. Bruker Corporation sits within the academic and research consortium tier, where high-field NMR-Raman hyphenated configurations command premium positioning.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| HORIBA Ltd. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Danaher Corporation |
| Agilent Technologies Inc. |
| Shimadzu Corporation |
| ABB Ltd. |
| Bruker Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on indium gallium arsenide detector supply from Japanese and European component specialists compresses instrument margins and amplifies pricing tier spreads between interferometer-based and dispersive platforms. This chokepoint forces manufacturers to absorb rare earth price volatility or pass costs downstream, reshaping procurement strategies across pharmaceutical quality labs and food processing networks.
Pricing Analysis
Configured-to-order pricing for hyphenated NMR-Raman systems commands substantial premiums over standard FT-NIR platforms deployed in food manufacturing. Three-tier pricing structure across premium, standard, and economy levels separates academic research consortia from routine quality control environments. Price differentiation hinges on certification grade for FDA process analytical technology compliance and geographic delivery cost to regulated markets. Cost compression in economy-tier dispersive systems is intensifying because generic API manufacturers in India prioritize capital efficiency over spectral precision. Pharmaceutical manufacturers in Massachusetts exhibit lowest price sensitivity; contract laboratories in emerging markets show highest.
Supply Chain Analysis
Export-control restrictions on high-power laser components and advanced detector arrays limit flows between United States, Japan, and European Union jurisdictions. Component manufacturing concentrates in Japan, Germany, and United States, with final assembly distributed across China and Singapore. Raw material dependencies span indium phosphide substrates, gallium arsenide wafers, and specialized optical coatings. Single-source vulnerability in InGaAs detector supply exposes lead times to disruption from trade policy shifts. Distribution runs through authorized distributor networks for regulated industries and direct vendor relationships for academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as continuous manufacturing transitions elevate spectroscopic process analytical technology from optional efficiency tool to regulatory mandate across oral solid dosage facilities.
For Market Incumbents: Pre-empt portable Raman commoditization by embedding cloud-native calibration platforms that convert hardware sales into recurring revenue streams. Consolidate chemometric software capabilities through targeted acquisitions before contract research organizations in Boston and the Research Triangle build captive expertise that bypasses manufacturer service contracts entirely. Defensive patent filings around spatially offset Raman spectroscopy applications will forestall emerging entrants from eroding pharmaceutical authentication margins. For New Entrants and Emerging Players: Underpenetration in India's generic API export facilities serving regulated markets offers the most penetrable geographic entry point. CDSCO alignment with ICH Q12 lifecycle management guidelines creates demand for validated spectroscopic methods that incumbent vendors have not fully addressed with cost-appropriate configurations. Target carbon fiber composite inspection applications in aerospace tier suppliers, where portable Raman for resin cure verification bypasses destructive mechanical testing protocols. A service-led go-to-market emphasizing chemometric model development and validation support differentiates against hardware-centric incumbents. For Investors and Strategic Acquirers: The market sits at a technology-integration phase that favors informatics-integrated platform vendors over pure hardware manufacturers. Long-term viability across the projection horizon rests on software subscription attach rates and multi-site calibration standardization capabilities. Acquisition targets should demonstrate embedded intelligence development and remote diagnostics infrastructure rather than incremental hardware improvements. Watch FDA continuous manufacturing approval velocity as the inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Calibration Platform Launch | Converts capital equipment sales into recurring revenue streams for pharmaceutical quality labs. |
| Chemometric Software Firm Acquisition | Addresses expertise scarcity that outpaces university analytical chemistry curricula. |
| Spatially Offset Raman Spectroscopy Patent Expansion | Secures through-container identification capabilities for customs and border security agencies. |
| CDSCO-Aligned Validation Service Buildout | Captures generic API export facility demand in Maharashtra and Gujarat manufacturing clusters. |
| Remote Diagnostics Infrastructure Deployment | Counteracts service unbundling by contract research organizations in Boston corridor. |
Research Methodology
A standing panel of pharmaceutical quality directors, analytical instrument procurement managers, regulatory affairs leads, and food manufacturing process engineers provided ongoing calibration across the study period. Primary interviews with instrument vendor product managers and contract research organization laboratory heads combined with secondary validation from FDA guidance documents, EMA quality-by-design framework publications, EPA field-portable method specifications, and ISO 17025 accreditation records. Bottom-up triangulation against top-down market sizing ensured convergence across installation base estimates and replacement cycle assumptions.
Scenario-bracketing around continuous manufacturing adoption rates, laser safety classification enforcement intensity, and indium gallium arsenide detector supply stability bounded projection uncertainty. Segmentation dimensions spanned product type, technology tier, end-use industry, application maturity, and regional regulatory cluster. CAGRs derived from instrument placement trajectories, service contract renewal patterns, and software subscription conversion rates across the analysis window. Industry-specific inputs included pharmacopeial equivalency determination timelines for handheld devices and EMA marketing authorization application specifications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified analytical conglomerates through vertical integration into detector manufacturing would shift outcomes substantially. Cross-checking against FDA continuous manufacturing approval databases and EMA quality-by-design framework implementation tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Spectrometry Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Vapor Pressure Analyzer Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Microplate Instrumentation and Systems Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Air Sampler Market