
 Saas for Spa Management Market | 2026-2036
Saas for Spa Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saas for Spa Management Market Analytics
Medical spa chains is consolidating their position as the fastest-growing end-user vertical within SaaS for spa management, driven by complex scheduling, EMR integration, and compliance documentation needs. MINDBODY, Inc. leverages its established fitness-studio infrastructure to cross-sell into hybrid wellness-spa operators. Zenoti anchors its competitive stance through enterprise-grade multi-location inventory orchestration. Vagaro competes aggressively on price for independent day-spa owners with simplified onboarding workflows.
SaaS for spa management denotes cloud-delivered software platforms that centralize appointment scheduling, payment processing, staff coordination, and client relationship workflows through browser-based and mobile-native interfaces, typically operating on subscription pricing with API connectivity to POS hardware and accounting systems. Deployment through public cloud infrastructure leads segment momentum due to minimal capital expenditure and automatic security patching, while private cloud configurations retain traction among medical spa operators governed by HIPAA data residency requirements. Service type concentration pools around appointment scheduling and payment processing as these modules generate the highest daily user touchpoints and direct revenue impact.
FDA oversight of medical spa procedures indirectly shapes software requirements for documentation and audit trails, while HIPAA mandates from the US Department of Health and Human Services enforce encryption and access-control standards for patient data handling. The EU AI Act and GDPR impose additional constraints on automated recommendation engines and cross-border data flows for European operators. Stakeholders must monitor how emerging state-level biometric privacy laws in Illinois, Texas, and Washington reshape client data retention policies and platform architecture decisions.
Market Dynamics
Cloud-native architectures are displacing legacy on-premises installations across wellness chains, while HIPAA compliance requirements intensify platform consolidation among medical spa operators. This dual pressure is compressing vendor margins and accelerating subscription model standardization.
Growth Catalysts
- HIPAA Enforcement Intensification:The US Department of Health and Human Services mandates encryption and access-control standards for patient data handling, forcing medical spas toward compliant SaaS platforms rather than fragmented point solutions.
- Multi-Location Inventory Orchestration:Enterprise-grade chains require real-time coordination across distributed facilities, driving demand for centralized cloud platforms with API connectivity to POS hardware and accounting systems.
- Biometric Privacy Legislation:State-level laws in Illinois, Texas, and Washington reshape client data retention policies, creating compliance-driven replacement cycles for non-conforming software installations.
Market Restraints
- Data Residency Requirements:HIPAA and EU GDPR impose conflicting geographic constraints on cloud infrastructure placement, fragmenting platform architecture decisions and inflating operational complexity.
- Legacy System Entrenchment:Independent day-spa owners maintain decade-old on-premises scheduling tools, creating high switching costs and elongated sales cycles for SaaS vendors.
- Interoperability Limitations:Proprietary EMR systems in medical spas resist standardized API protocols, forcing expensive custom integration development.
Strategic Opportunities
- Hybrid Wellness-Spa Convergence:Fitness-studio operators expanding into spa services create cross-selling pathways for platforms with existing fitness infrastructure.
- Automated Recommendation Engines:AI-driven treatment personalization faces regulatory headroom under the EU AI Act, creating first-mover advantage for compliant algorithmic platforms.
- Mobile-Native Client Interfaces:Consumer preference for app-based booking and payment is compressing browser-dependent platforms, rewarding vendors with superior iOS and Android experiences.
Industry Challenges
- Technical Talent Scarcity:Cloud security engineering and healthcare compliance expertise command premium compensation, constraining vendor R&D velocity.
- Certification Timeline Compression:ISO 27001 and SOC 2 Type II audits require 12-18 month cycles, delaying market entry for emerging platform providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saas for Spa Management Market |
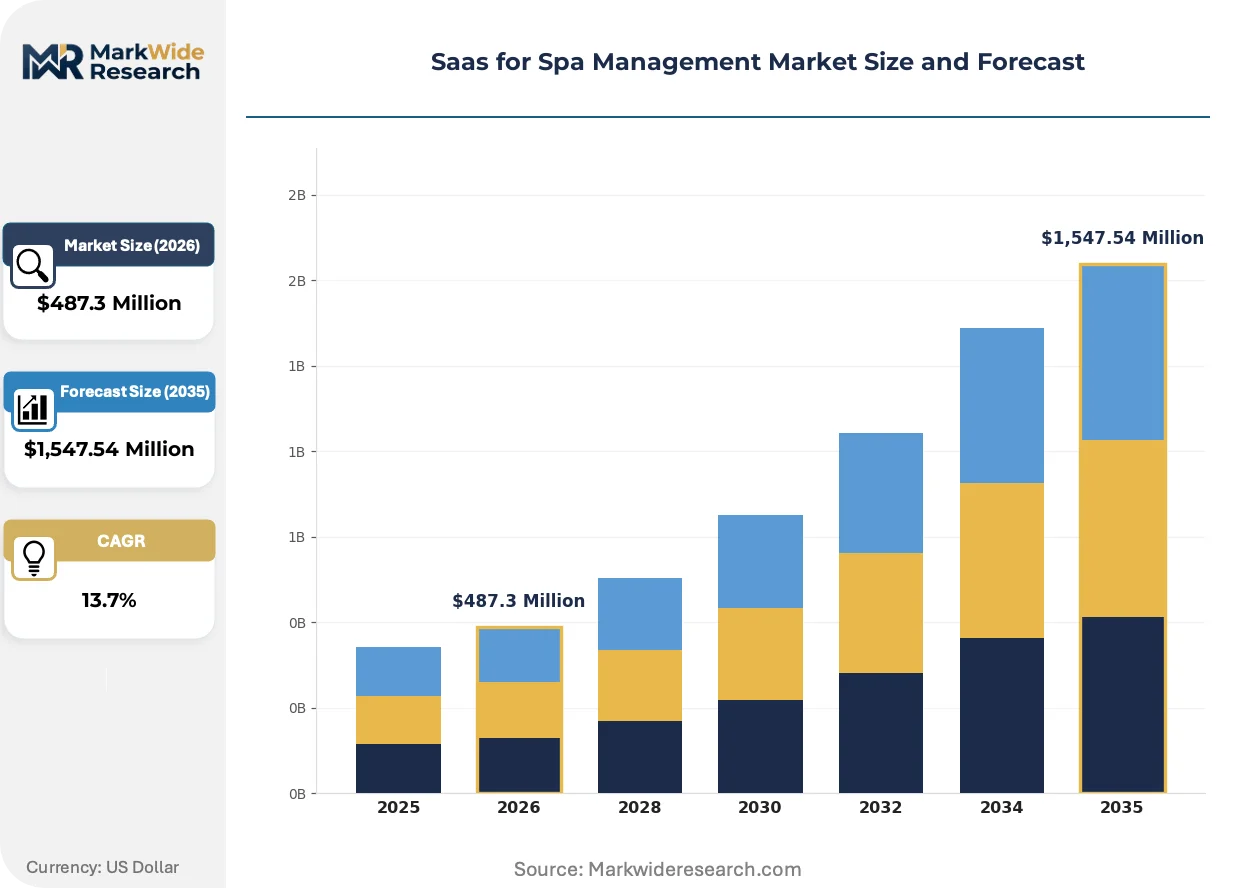
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,547.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Appointment Scheduling, Payment Processing, Customer Relationship Management, Inventory Management End User: Day Spas, Medical Spas, Hotel Spas, Wellness Centers Feature: Mobile Access, Marketing Tools, Reporting Analytics, Staff Management |
| Companies Covered | MINDBODY, Inc., Vagaro, Rosy Salon Software, Zenoti, Fresha.com SV Ltd, Treatwell, AestheticsPro, Mangomint, Meevo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saas for Spa Management Market Evolving Landscape
API-first platform architectures are reshaping competitive positioning by enabling modular service composition rather than monolithic suite delivery. Vendors now compete on integration depth rather than feature breadth alone.
Embedded payment processing is electrifying revenue capture workflows by collapsing transaction friction at the point of service. Medical spa chains adopting integrated payment-native platforms report reduced no-show rates and improved cash flow predictability. This convergence is compressing the addressable market for standalone payment terminals and third-party processor middleware.
The EU AI Act imposes algorithmic transparency requirements on automated treatment recommendation engines deployed in European medical spas. Platforms must now document decision logic and maintain human oversight interfaces, increasing development overhead but creating compliance moats against non-European competitors. German and French operators are accelerating procurement of certified AI modules ahead of enforcement deadlines.
Subscription fatigue among independent spa owners is fragmenting procurement toward usage-based pricing models. Day-spa operators in California and Florida increasingly favor per-appointment fees over fixed monthly commitments, pressuring vendors to restructure revenue recognition. This behavioral shift is most visible among single-location businesses with seasonal demand volatility.
Saas for Spa Management Market Segmentation
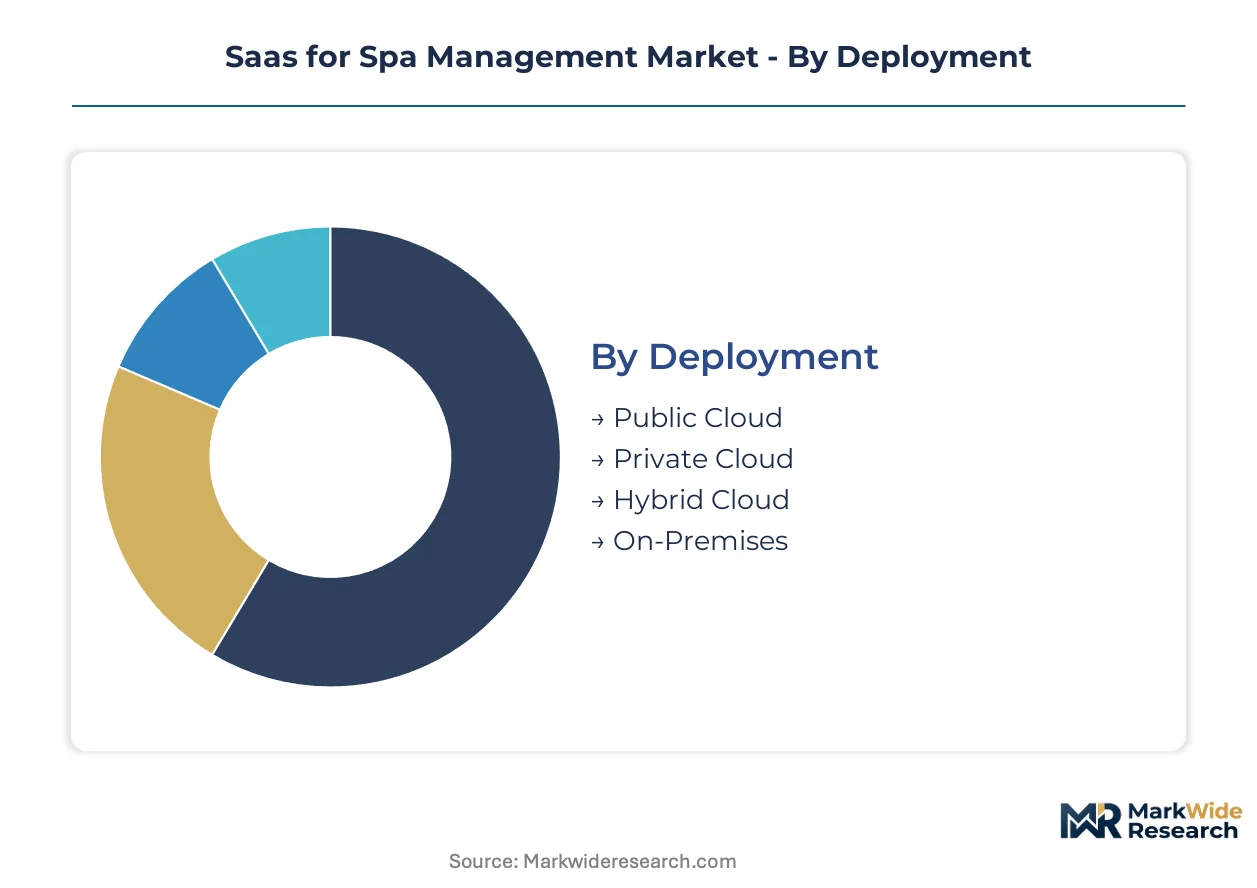
SaaS for spa management platforms serve heterogeneous operational profiles across deployment architectures, service modules, and end-user compliance requirements. Segmentation reveals where capital intensity concentrates and which configurations command premium pricing.
Deployment:
Capital intensity peaks with private cloud configurations due to dedicated infrastructure provisioning and HIPAA-compliant data residency investments.
- Public Cloud:Multi-tenant infrastructure minimizes upfront expenditure through shared resource pooling. Day-spa chains in California and Florida favor this model for automatic security patching and elastic capacity scaling during seasonal demand surges.
- Private Cloud:Single-tenant environments enforce physical and logical isolation for regulated medical spa operators. HIPAA mandates from the US Department of Health and Human Services drive procurement among dermatology and aesthetic surgery chains requiring encrypted patient data handling with documented access controls.
- Hybrid Cloud:Workload-specific partitioning balances cost efficiency with compliance flexibility. Hotel spa operators leverage public cloud for guest-facing booking interfaces while retaining private infrastructure for payment card data environments.
- On-Premises:Legacy server installations persist among independent operators with decade-old capital investments and limited IT staffing.
Public cloud absorbs the bulk of installed capacity; private cloud is expanding most quickly.
Service Type:
Revenue concentration aligns with daily touchpoint frequency rather than module sophistication.
- Appointment Scheduling:Real-time calendar coordination across multiple practitioners and treatment rooms. Medical spa chains prioritize this module for complex procedure sequencing and provider credential matching.
- Payment Processing:Embedded transaction workflows collapse friction at service completion. Integrated platforms reduce no-show rates through automated deposit collection and improve cash flow predictability for wellness center operators.
- Customer Relationship Management:Treatment history tracking and preference profiling enable personalized service recovery. GDPR constraints from European operations limit automated outreach frequency for cross-border data subjects.
- Inventory Management:Multi-location product orchestration supports enterprise-grade spa chains with distributed retail footprints.
Payment processing captures the highest daily engagement; appointment scheduling shows the steepest expansion trajectory.
End User:
Compliance burden and transaction complexity stratify procurement budgets across operator types.
- Medical Spas:FDA-regulated procedure documentation and HIPAA audit trail requirements dominate software specifications. EMR integration and consent management workflows command premium subscription tiers.
- Day Spas:Simplified scheduling and retail POS integration satisfy independent owner-operators. Price-sensitive procurement favors usage-based pricing over fixed monthly commitments.
- Hotel Spas:Property management system connectivity and guest loyalty program integration shape platform selection. Seasonal staffing volatility demands flexible license scaling.
- Wellness Centers:Hybrid fitness-spa operators require cross-functional membership management and class scheduling convergence.
Medical spas deploy the most complex configurations; wellness centers are climbing the fastest.
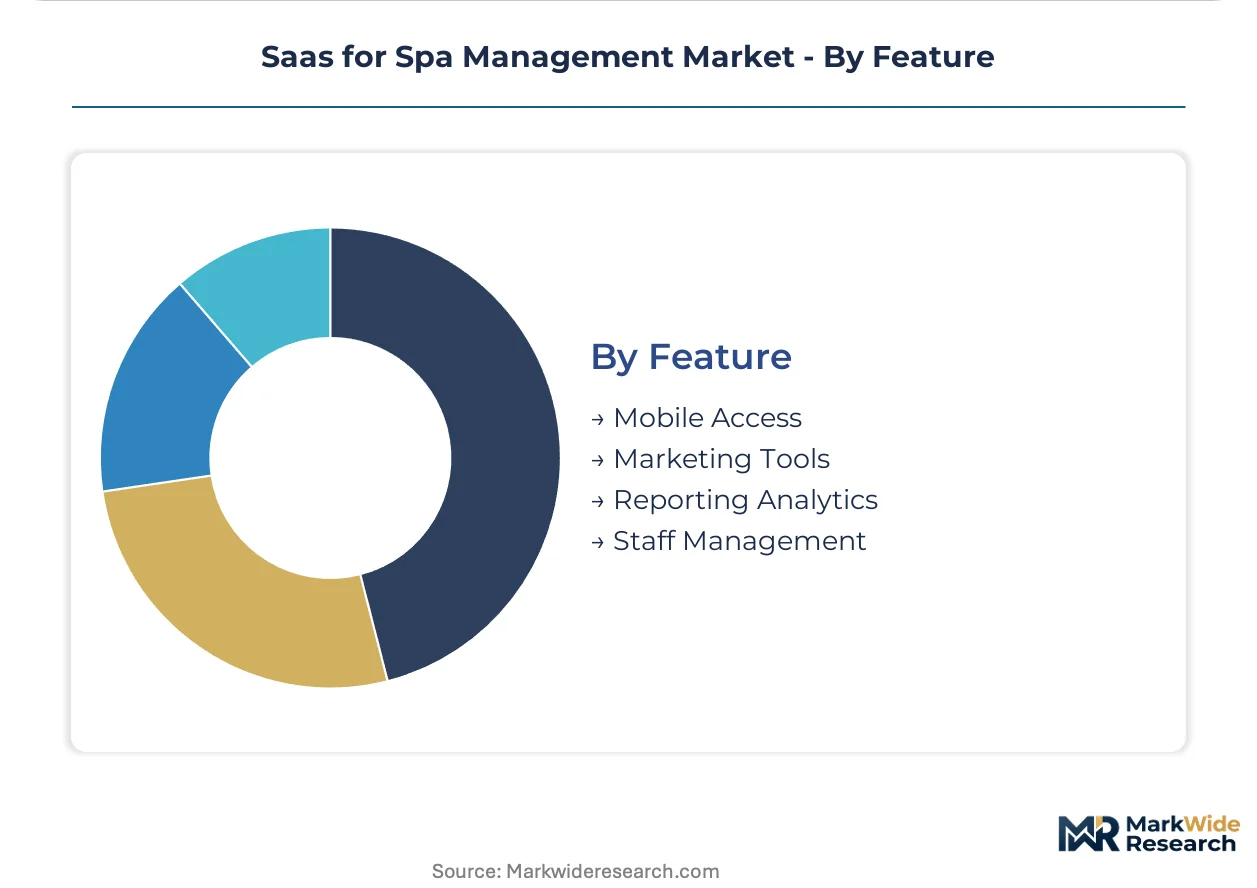
Feature:
Consumer interface expectations and workforce coordination needs determine development prioritization.
- Mobile Access:Native iOS and Android applications compress browser-dependent booking abandonment. Consumer preference for app-based service discovery rewards vendors with superior mobile experience investments.
- Staff Management:Credential tracking, commission calculation, and shift coordination address labor compliance across multi-location chains. California and Washington state biometric privacy laws reshape time-clock and access control implementations.
- Marketing Tools:Automated campaign orchestration and review solicitation engines support customer acquisition for independent operators.
- Reporting Analytics:Treatment profitability and provider productivity dashboards inform pricing strategy adjustments.
Mobile access dominates development roadmaps; staff management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and state-level tax incentives in Florida, Texas, and California concentrate medical spa and wellness chain headquarters, anchoring SaaS procurement clusters around compliance-heavy metropolitan markets.
United States
Medical spa chains in Miami, Los Angeles, and Dallas drive enterprise-grade platform adoption as HIPAA enforcement intensifies. The Department of Health and Human Services mandates encryption standards that fragment legacy system retention. California's biometric privacy laws in Sacramento and San Francisco reshape data retention architecture decisions for cross-state operators.
Germany
EU AI Act compliance deadlines accelerate certified algorithmic platform procurement among Frankfurt and Munich medical aesthetic chains. The Federal Ministry of Health coordinates with BfArM on digital health documentation standards. Bavarian wellness operators in Baden-Baden and Stuttgart lead hybrid cloud deployments balancing GDPR residency with public cloud elasticity.
United Kingdom
London's Harley Street medical aesthetic cluster demands EMR-integrated scheduling with NHS interoperability pathways. The Information Commissioner's Office enforces GDPR-derived data localization for cross-border patient records. Manchester and Birmingham wellness chains favor API-first platforms enabling modular service composition across distributed sites.
Japan
Tokyo's Ginza and Osaka's Umeda districts concentrate luxury hotel spa digitization around mobile-native booking interfaces. METI's digital transformation subsidies reduce cloud migration friction for traditional ryokan operators. Yokohama medical aesthetic chains adopt private cloud configurations under PMDA documentation requirements for laser and injection procedures.
Australia
Sydney and Melbourne medical spa chains navigate TGA device registration overlaps with SaaS documentation modules. The Office of the Australian Information Commissioner enforces Notifiable Data Breaches scheme compliance for patient payment records. Queensland wellness tourism operators in Gold Coast and Noosa favor usage-based pricing models matching seasonal demand volatility.
Saas for Spa Management Market Competitive Landscape
Top-tier vendors anchor enterprise medical spa chains, while mid-market specialists target independent day-spa operators with simplified onboarding workflows. The vendor base stratifies across HIPAA-certified enterprise suites, fitness-crossover platforms, and price-aggressive independents. Three archetypes dominate: compliance-first medical specialists, fitness-studio cross-sellers, and mobile-native independents. Platform consolidation and API-first architecture investments constitute the dominant competitive vectors.
Within the fitness-crossover tier, MINDBODY, Inc. exemplifies infrastructure leverage into hybrid wellness-spa operators. Zenoti occupies a position among enterprise-grade multi-location orchestration specialists. Vagaro represents price-competitive positioning for simplified independent owner workflows. These three anchors illustrate how geographic origin and naming conventions signal strategic archetype alignment without requiring operational specificity.
| Leading Market Players |
|---|
| MINDBODY, Inc. |
| Vagaro |
| Rosy Salon Software |
| Zenoti |
| Fresha.com SV Ltd |
| Treatwell |
| AestheticsPro |
| Mangomint |
| Meevo |
| Others |
Value Network & Pricing Analysis
Medical spa chains with multi-location compliance requirements anchor pricing power toward enterprise-grade subscription tiers, compressing margins for vendors serving price-sensitive independent day-spa operators. Subscription fatigue among single-location owners accelerates migration toward usage-based models that tie fees to appointment volume rather than fixed monthly commitments.
Pricing Analysis
Short lead-time deployment premiums reward vendors with pre-configured HIPAA-compliant infrastructure stacks ready for immediate activation. Three-tier pricing structure across premium, standard, and economy levels segments by compliance certification depth and EMR integration complexity. Cost compression in the independent day-spa tier intensifies because Vagaro and Fresha.com SV Ltd compete aggressively on per-appointment fees. Medical spa chains show lowest price sensitivity due to audit liability exposure from non-compliant legacy systems.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Ireland, and Singapore to satisfy data residency mandates across HIPAA, GDPR, and APAC privacy frameworks. Platform development draws from specialized labor pools in India for engineering talent, Estonia for cybersecurity expertise, and Poland for compliance documentation. Single-source vulnerability concentrates around AWS and Azure hyperscaler dependencies for primary compute. Distribution runs through direct sales teams for enterprise medical chains and self-service onboarding portals for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Vendors are pursuing backward integration into payment processing to capture transaction revenue streams and reduce third-party processor dependencies.
For Market Incumbents: Cement HIPAA certification moats through accelerated SOC 2 Type II and ISO 27001 audit completion ahead of enforcement intensification. Deepen EMR integration partnerships with dermatology and aesthetic surgery chains to raise switching costs against cloud-native challengers. Priority rests on multi-location inventory orchestration capabilities that independent entrants cannot replicate without capital intensity. For New Entrants and Emerging Players: Launch via mobile-native interfaces targeting independent day-spa owners in California and Florida with seasonal demand volatility. White-space concentrates in biometric privacy-compliant staff management modules for Illinois, Texas, and Washington operators. Penetrate through usage-based pricing that aligns vendor revenue with client cash flow patterns. For Investors and Strategic Acquirers: The window for entry favors platforms with existing fitness-studio infrastructure seeking spa vertical expansion. Long-term viability hinges on compliance automation depth rather than feature breadth alone. Watch HIPAA enforcement penalty magnitude as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Compliance Certification | SOC 2 Type II completion opens procurement pathways to medical spa chains facing HHS enforcement. |
| EMR Integration Partnership | Proprietary aesthetic medicine systems resist standard APIs, forcing custom development investment. |
| Payment Processing Embedding | Native transaction workflows reduce no-show rates and improve cash flow predictability for operators. |
| Mobile-Native Interface Launch | Consumer preference for app-based booking compresses browser-dependent platform retention. |
| Biometric Privacy Module Development | Illinois BIPA and Texas CUBI compliance creates differentiation against non-conforming competitors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with spa operations directors, HIPAA compliance officers, and SaaS procurement managers at wellness chains cross-validated platform adoption patterns. HHS enforcement action databases, state-level biometric privacy legislation trackers, and cloud infrastructure capex disclosures supplied quantitative anchors. Bottom-up deployment modeling and top-down market sizing triangulated segment-level estimates.
Data-stream reconciliation across subscription billing disclosures, EMR integration partnership announcements, and multi-location chain expansion timelines shaped the analytical framework. Segmentation dimensions spanned deployment architecture, service module concentration, end-user compliance burden, and regional regulatory cluster intensity. CAGRs derived from installed base growth rates and average revenue per account trajectories across the projection horizon. EU AI Act compliance deadlines and state-level privacy law enactment schedules informed European and North American trajectory assumptions.
Enforcement intensity variance, EMR interoperability breakthroughs, and hyperscaler pricing disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding replacement cycle timing and compliance-driven procurement acceleration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Server Operating System Market
Software & Services
House Cleaning App Market
Software & Services
Global Policy Management Software Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Application Platform As a Service Market
Software & Services
Global Translation Software Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Global Project Software Market
Software & Services
Global App Design Software Market
Software & Services
Global Demand Planning Software Market
Software & Services
Global Club Management Software Market
Software & Services
Board Portal Market
Software & Services
Shift Planning Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Employee Advocacy Software Market