
 Team Collaboration Tools Market | 2026-2036
Team Collaboration Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Team Collaboration Tools Market Outlook
API-first architecture is fragmenting the monolithic collaboration stack into interoperable microservices. Microsoft Corporation leverages its Azure ecosystem to anchor enterprise-grade workflow automation. Google competes through deep integration with Workspace productivity layers. Atlassian Corporation specializes in developer-centric project management that bridges technical and business teams.
Team collaboration tools are software platforms that enable real-time communication, file synchronization, and task coordination across distributed workforces, typically operating through REST APIs and WebSocket protocols for sub-100ms latency. Their primary commercial purpose is to reduce friction in cross-functional workflows and replace email-dependent processes with structured channel-based interaction. Video conferencing solutions within the product type dimension command premium pricing due to bandwidth-intensive infrastructure requirements and enterprise security certifications. Cloud-based deployment leads volume adoption among SMEs seeking zero-capital scalability, while hybrid architectures capture margin pools from regulated industries requiring data residency controls.
FDA scrutiny of clinical communication platforms shapes HIPAA-aligned encryption standards for healthcare deployments. EMA and national EU regulators enforce GDPR data-localization rules that restrict cross-border server architectures. The EU AI Act imposes transparency obligations on generative assistant features embedded in messaging interfaces. Stakeholders must monitor how divergent transatlantic compliance frameworks fragment vendor roadmaps and inflate certification costs for multi-region deployments.
Market Dynamics
API-first architecture is fragmenting monolithic collaboration stacks into interoperable microservices, forcing vendors to rebuild around modular connectivity rather than all-in-one suites.
Growth Catalysts
- HIPAA-aligned encryption mandates:Healthcare delivery networks in the United States face FDA scrutiny of clinical communication platforms, accelerating procurement of certified messaging infrastructure.
- Industrial Mittelstand digitization:German mid-sized manufacturers are deploying cross-functional engineering workflows that integrate technical and business teams through specialized collaboration layers.
- EU AI Act transparency obligations:The European Union's artificial intelligence framework compels vendors to disclose generative assistant training data, reshaping feature roadmaps for workplace messaging interfaces.
Market Restraints
- GDPR data-localization compliance costs:EMA and national EU regulators enforce server residency rules that fragment vendor architectures and inflate multi-region certification expenses.
- Bandwidth-intensive video infrastructure:Enterprise-grade conferencing requires dedicated fiber and edge compute investments that price out smaller competitors.
- Legacy email dependency:Structured channel-based interaction faces institutional resistance from organizations with decades of Outlook-centric workflow inertia.
Strategic Opportunities
- Hybrid deployment architectures:Regulated industries seeking data residency controls present margin pools beyond standard cloud-only offerings.
- Generative assistant convergence:Natural language processing integration with real-time messaging creates white space for workflow automation vendors.
- India's PLI scheme for digital infrastructure:Production-linked incentives for data center expansion lower barriers for regional collaboration platform hosting.
Industry Challenges
- WebSocket protocol engineering talent scarcity:Sub-100ms latency requirements demand specialized full-stack developers that command premium compensation in competitive labor markets.
- Cross-border server reconfiguration timelines:Divergent transatlantic compliance frameworks force vendors to maintain parallel certification tracks, stretching product release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Team Collaboration Tools Market |
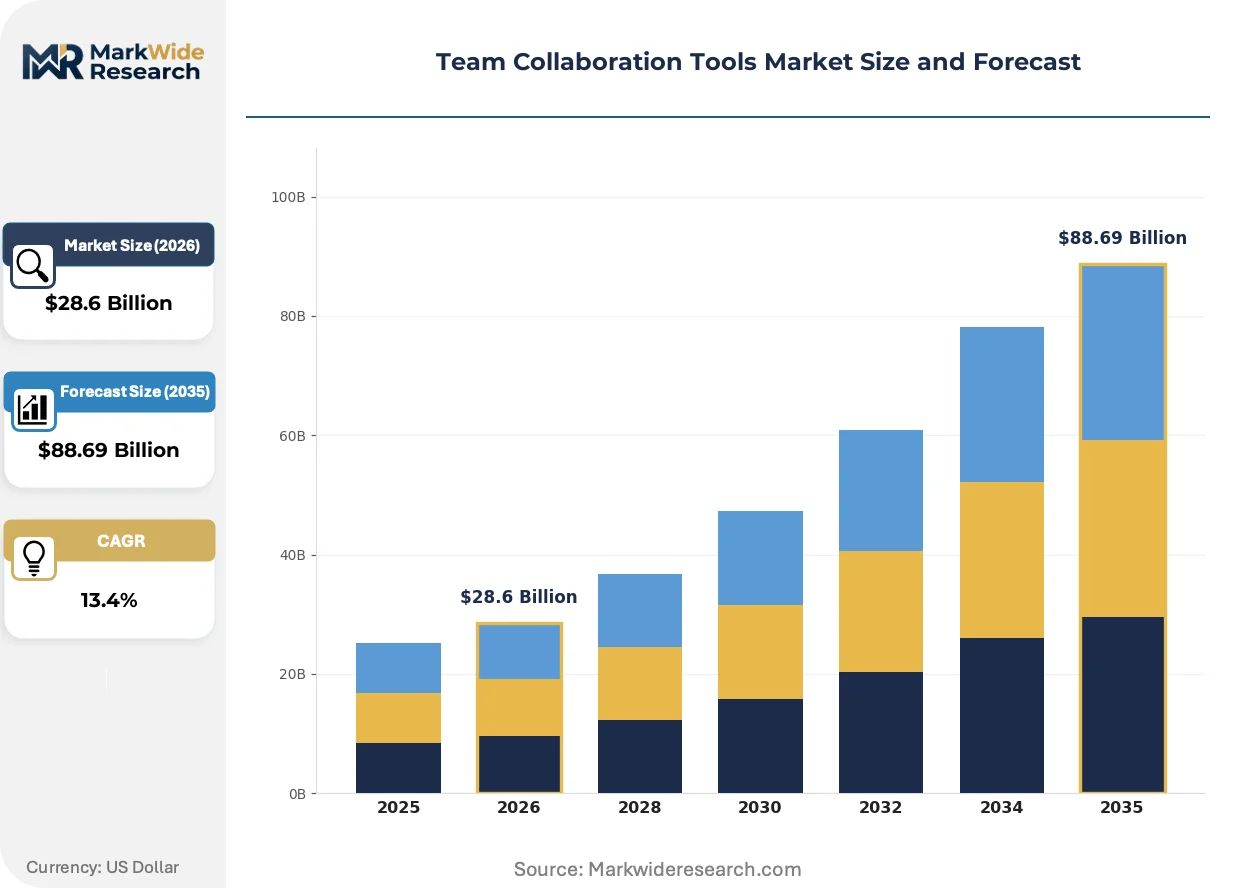
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $88.69 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Messaging Apps, Video Conferencing, Project Management, Document Sharing End User: SMEs, Large Enterprises, Freelancers, Educational Institutions Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Integration Level: API Integration, Single Sign-On, Workflow Automation, Others |
| Companies Covered | Microsoft Corporation, Google, Salesforce (Slack), Zoom Video Communications, Atlassian Corporation, Cisco Systems, Asana, TeamViewer, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Team Collaboration Tools Market Strategic Shifts
Workplace technology is pivoting from communication-centric to workflow-centric platforms that embed task execution within conversational interfaces.
Generative AI copilots embedded in messaging interfaces are digitizing routine documentation and scheduling workflows that previously required dedicated administrative staff. Mid-market professional services firms in the United States and United Kingdom are piloting these capabilities at scale, compressing headcount ratios per revenue dollar. The structural consequence is a redefinition of collaboration ROI from seat-based to outcome-based metrics.
The EU AI Act's transparency obligations are forcing vendors to document training data provenance for generative features before deployment in member states. Industrial consequence includes delayed feature rollouts and partitioned product versions between European and non-European instances. Healthcare and financial services segments are responding by demanding on-premise or sovereign cloud deployments that preclude third-party model training.
Channel-based procurement is displacing traditional enterprise software sales cycles with self-serve trials that convert through usage thresholds rather than RFP processes. Value-added resellers and systems integrators face margin compression as vendors build direct customer success functions. This pattern is most visible in India's technology sector, where SaaS-native buyers expect immediate deployment without implementation services.
Team Collaboration Tools Market Segmentation
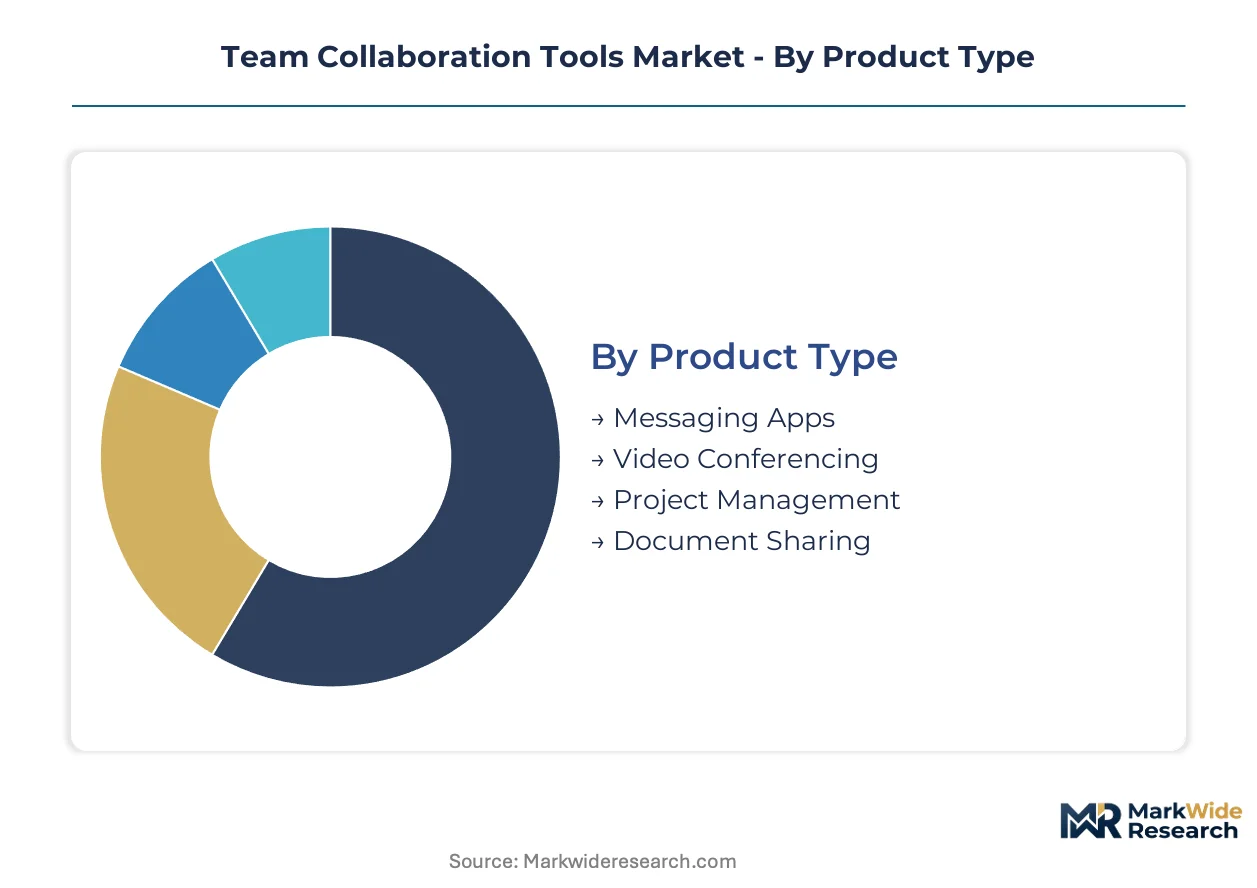
Segmentation in team collaboration tools reveals how procurement patterns diverge across technical requirements, organizational scale, and regulatory exposure. Vendors architect their service models around these fault lines, with support intensity and integration complexity varying dramatically by category.
Product Type:
After-sales service intensity concentrates in video infrastructure, where latency troubleshooting and bandwidth optimization demand dedicated technical account management.
- Video Conferencing:Bandwidth-intensive real-time media pipelines require edge compute distribution and enterprise SLA guarantees. Healthcare delivery networks in the United States drive HIPAA-aligned encryption procurement for clinical consultations. By volume, Messaging Apps leads. By growth pace, Video Conferencing is ahead.
- Messaging Apps:REST API and WebSocket protocol stacks enable sub-100ms channel synchronization across distributed workforces. German Mittelstand manufacturers deploy these for cross-functional engineering workflows. By volume, Messaging Apps leads. By growth pace, Video Conferencing is ahead.
- Project Management:Task dependency engines bridge technical and business team coordination.
- Document Sharing:Version control and real-time co-editing infrastructure with granular permission architectures.
Video Conferencing commands premium service attach rates due to infrastructure complexity, while Messaging Apps scale through automated onboarding.
End User:
Cost tier stratification separates zero-touch self-serve models from white-glove implementation services.
- Large Enterprises:Multi-tenant architectures with custom compliance configurations and dedicated customer success pods. EU AI Act transparency obligations reshape generative feature roadmaps for European deployments. Large Enterprises dominates absolute spend. SMEs expand most quickly.
- SMEs:Cloud-native procurement through usage-based trials without RFP cycles, concentrated in India's technology sector. Large Enterprises dominates absolute spend. SMEs expand most quickly.
- Freelancers:Individual productivity layers with lightweight billing and minimal administrative overhead.
- Educational Institutions:Campus-wide licensing with FERPA-aligned data handling and semester-based contract structures.
Large Enterprises anchor vendor profitability, though SMEs drive net new account velocity.
Deployment:
Margin pools concentrate in architectures that reconcile scalability with data residency controls.
- Cloud-Based:Zero-capital elasticity through multi-tenant SaaS delivery, dominating SME procurement. GDPR data-localization rules fragment vendor architectures for European instances. Cloud-Based leads volume adoption. Hybrid deployment shows steepest expansion trajectory.
- Hybrid:Partitioned workloads with sensitive data on-premise and compute-intensive functions in cloud. Regulated industries in financial services and healthcare demand sovereign cloud configurations. Cloud-Based leads volume adoption. Hybrid deployment shows steepest expansion trajectory.
- On-Premises:Air-gapped installations for classified or critical infrastructure environments.
- Mobile:Native iOS and Android clients with offline synchronization and push notification orchestration.
Cloud-Based deployment captures volume, while Hybrid architectures secure margin expansion in regulated verticals.
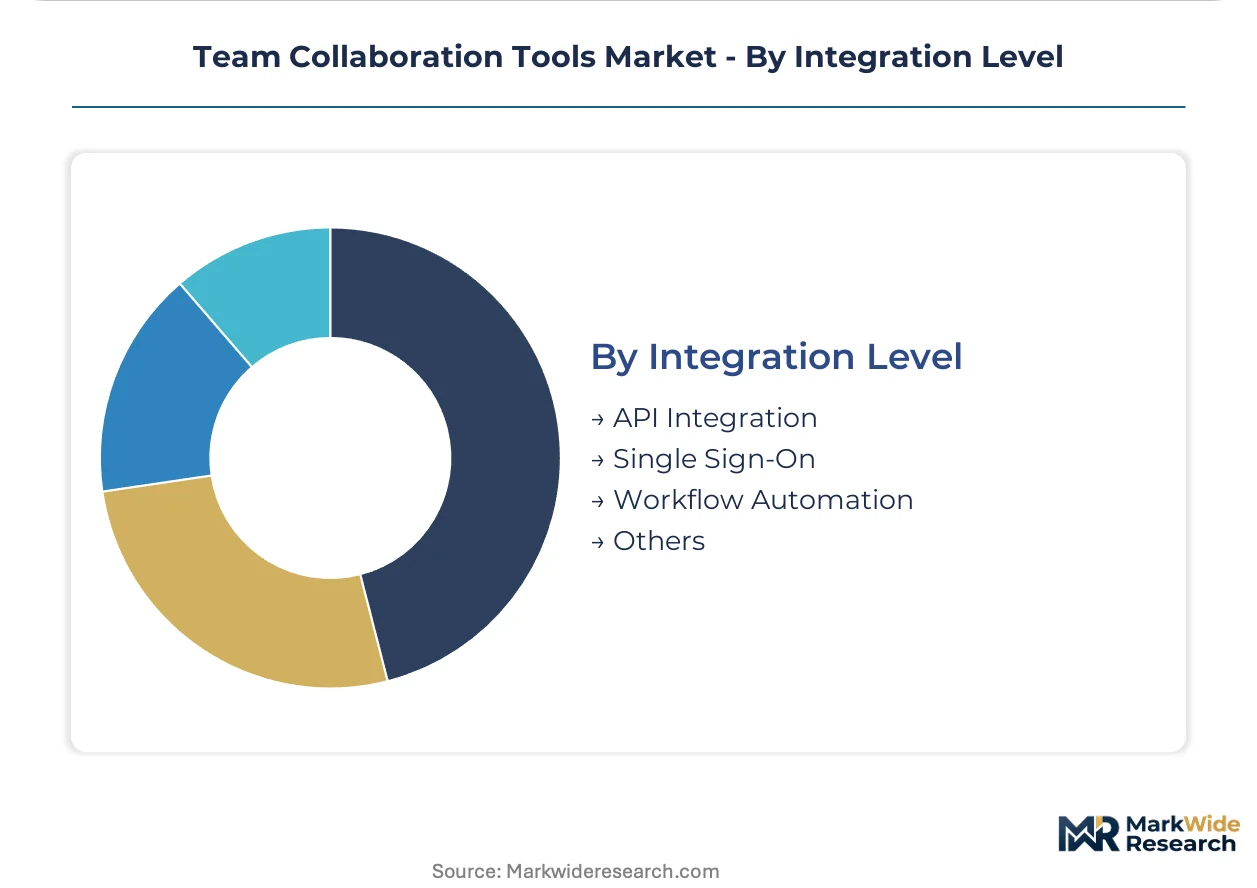
Integration Level:
Customer lifetime value correlates with connectivity depth, as embedded workflows reduce switching probability.
- API Integration:Microservice architectures enabling bespoke connections to ERP, CRM, and vertical-specific systems. WebSocket protocol engineering talent scarcity inflates implementation costs. API Integration leads technical adoption. Workflow Automation gains share fastest.
- Workflow Automation:No-code trigger-action engines that digitize routine documentation and scheduling without dedicated staff. Mid-market professional services firms in the United States and United Kingdom pilot these capabilities at scale. API Integration leads technical adoption. Workflow Automation gains share fastest.
- Single Sign-On:SAML and OIDC federation for identity provider consolidation.
- Others:Legacy connector protocols and custom middleware for non-standard system landscapes.
API Integration anchors enterprise stickiness, though Workflow Automation drives expansion revenue per seat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in economies with dense professional services sectors and stringent data governance requirements. Healthcare systems and industrial manufacturers drive differentiated demand patterns across major markets.
United States
Healthcare delivery networks and mid-market professional services firms dominate procurement volume. FDA scrutiny of clinical communication platforms accelerates HIPAA-aligned encryption certification requirements. Boston's biotech corridor and New York's financial district deploy sovereign cloud configurations for sensitive workflows.
Germany
Industrial Mittelstand manufacturers digitize cross-functional engineering workflows through specialized collaboration layers. EU AI Act transparency obligations reshape generative feature roadmaps for workplace messaging interfaces. Stuttgart and Munich engineering clusters demand hybrid deployment architectures with data residency controls.
United Kingdom
Professional services firms pilot generative assistant capabilities at scale, compressing administrative headcount ratios. GDPR data-localization rules fragment vendor architectures for European instances. London's fintech and legal services corridors drive premium-tier procurement with custom compliance configurations.
India
SaaS-native technology sector buyers expect immediate deployment without implementation services. PLI scheme incentives for data center expansion lower barriers for regional collaboration platform hosting. Bangalore and Hyderabad technology clusters concentrate cloud-native procurement through usage-based trials.
Japan
Large enterprises anchor vendor profitability with multi-tenant architectures and dedicated customer success requirements. METI industrial digitization programs accelerate workflow automation adoption. Tokyo and Osaka manufacturing headquarters integrate collaboration layers with existing ERP system landscapes.
Team Collaboration Tools Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. The vendor base organizes around platform ecosystems, vertical specialists, and regional service providers. Dominant archetypes include cloud-native suite providers, developer-centric workflow vendors, and telecommunications-anchored conferencing specialists. Competitive moves concentrate on API-first architecture investments and hybrid deployment capability expansion.
Within the platform ecosystem tier, Microsoft Corporation and Google exemplify cloud-native suite providers that anchor enterprise-grade workflow automation through productivity layer integration. Salesforce (Slack) occupies a position bridging messaging infrastructure with CRM connectivity. Atlassian Corporation represents the developer-centric archetype specializing in technical-business team coordination. Zoom Video Communications anchors the real-time media pipeline segment with bandwidth-intensive infrastructure investments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Salesforce (Slack) |
| Zoom Video Communications |
| Atlassian Corporation |
| Cisco Systems |
| Asana |
| TeamViewer |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
Trans-Pacific fiber routes connecting Seattle to Tokyo and Singapore carry bandwidth-intensive video conferencing traffic whose cost dynamics concentrate pricing power among hyperscale cloud providers while fragmenting margin pools for regional hosting vendors serving data-residency-sensitive buyers.
Pricing Analysis
Cost-plus contracts with quarterly bandwidth indexation dominate enterprise video infrastructure procurement. Three-tier pricing structure across premium, standard, and economy levels separates HIPAA-certified healthcare deployments from mid-market professional services tiers and self-serve SME offerings. Price differentiation hinges on encryption certification grade and dedicated technical account management intensity. Pricing pressure stems from India's PLI scheme lowering regional data center hosting costs, compressing margins for standard-tier cloud deployments. SMEs exhibit highest price sensitivity, while regulated healthcare networks accept premium tiers for compliance assurance.
Supply Chain Analysis
Upstream feedstock for collaboration infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with edge compute hardware sourcing from Chinese and Vietnamese assembly facilities. Critical inputs include WebSocket protocol optimization chipsets, fiber optic transmission equipment, and sovereign cloud server racks. Supply chain risk centers on single-source vulnerability for sub-100ms latency engineering talent commanding premium compensation. Distribution runs through direct vendor customer success functions displacing traditional value-added reseller channels, particularly acute in India's SaaS-native technology sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Team Collaboration Tools Market represents a high-growth disruption as the EU AI Act's transparency obligations force vendors to rebuild generative feature roadmaps around partitioned product versions, creating structural openings for compliance-native entrants.
For Market Incumbents: Insulate enterprise relationships through hybrid deployment certification investments that preempt sovereign cloud competitors. Deepen API-first architecture moats by acquiring workflow automation specialists before they scale. The EU AI Act's training data disclosure mandates threaten margin pools in European instances unless vendors maintain parallel certification tracks. For New Entrants and Emerging Players: Build out HIPAA-aligned messaging infrastructure targeting United States healthcare delivery networks facing FDA scrutiny of clinical communication platforms. German Mittelstand manufacturers digitizing cross-functional engineering workflows present the most penetrable segment for specialized collaboration layers. Channel-based self-serve trials convert faster than RFP cycles in India's technology sector. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications-anchored conferencing specialists stranded between hyperscale cloud suites and vertical SaaS players. Long-term viability favors vendors with workflow automation depth over pure communication infrastructure. Watch WebSocket protocol engineering compensation inflation as an inflection indicator for talent-constrained scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Certification | Captures margin pools from healthcare networks requiring HIPAA-aligned data residency controls. |
| API-First Architecture Investment | Enables microservice interoperability that fragments monolithic suite dominance. |
| Generative Assistant Integration | Compresses administrative headcount ratios for mid-market professional services firms. |
| Regional Data Center Expansion | Leverages India's PLI scheme incentives to lower hosting barriers for SaaS-native buyers. |
| Workflow Automation Acquisition | Secures expansion revenue per seat through no-code trigger-action engine deployment. |
Study Parameters
A standing panel of CTOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interviews with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie usage data, and hospital procurement databases. Bottom-up deployment model adoption curves were triangulated against top-down professional services sector digitization indices.
Scenario-bracketing framed sensitivity analysis across the projection horizon, modeling product type segments including video conferencing, messaging apps, project management, and document sharing alongside end-user tiers and integration complexity levels. CAGRs were derived from fitted adoption curves incorporating EU AI Act compliance timeline assumptions and India's PLI scheme capacity buildout schedules.
Stress conditions across bandwidth cost inflation, WebSocket engineering talent scarcity, and transatlantic regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about hybrid deployment migration rates and generative feature adoption curves. Cross-checking against hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Packaged Software Market
Software & Services
Solar Rooftop Design Software Market
Software & Services
Software Publishers Market
Software & Services
Courier Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
GCC Human Capital Management Software Market
Software & Services
Warranty Management Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Vacation Rental Software Market
Software & Services
Freight Forwarding Software Market
Software & Services
Category Management Software Market