
 Global Aiops Platform Market | 2026-2036
Global Aiops Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aiops Platform Market Foresight
EU AI Act enforcement is recalibrating the cost-of-entry calculus for AIOps vendors serving European enterprises. IBM leverages its Watson integration to anchor hybrid cloud deployments across regulated industries. Dynatrace competes through AI-driven causal analytics that sustains premium positioning in application performance monitoring. ServiceNow differentiates by embedding AIOps into enterprise service management workflows.
An AIOps platform synthesizes machine learning algorithms, streaming telemetry ingestion, and automated remediation engines to transform raw IT operational data into predictive intelligence, typically processing millions of events per minute through distributed correlation architectures. The platform's primary commercial purpose is to replace reactive incident management with self-healing infrastructure that minimizes mean time to resolution. Cloud-based deployment dominates solution delivery, though hybrid configurations are capturing fastest-growing demand as enterprises retain sensitive workloads on-premises while bursting analytics to public cloud. Predictive analytics and root cause analysis command concentrated R&D investment because these solution layers directly reduce operational expenditure for telecommunications and financial services end users.
FDA scrutiny of AI-enabled diagnostic tools, HIPAA requirements for healthcare IT infrastructure, and SEC cybersecurity disclosure rules collectively elevate audit-grade observability standards across US-deployed platforms. EMA's parallel emphasis on algorithmic traceability in pharmaceutical manufacturing systems creates comparable compliance pull in Europe. Stakeholders must weigh sovereign cloud mandates against multi-cloud interoperability when selecting deployment architectures for the next operational transformation cycle.
Market Dynamics
Hybrid cloud telemetry architectures are fragmenting vendor control over AIOps data pipelines, forcing platform providers to rebuild ingestion layers around Kubernetes-native observability standards while financial services and telecommunications buyers demand sovereign data residency guarantees.
Growth Catalysts
- EU AI Act algorithmic traceability mandates:European enterprises must deploy auditable decision trails for automated IT operations, creating procurement pull for platforms with embedded governance modules.
- Telecommunications 5G network slicing complexity:Mobile operators require real-time correlation across millions of ephemeral virtual network functions, driving subscription growth for event-stream processing capabilities.
- India's RBI operational resilience guidelines:The central bank's mandate for sub-second incident detection in digital payment infrastructure is accelerating AIOps deployment across the country's banking sector.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for causal AI models depend on NVIDIA H100 supply concentration, compressing vendor margins during allocation shortages.
- Data sovereignty compliance fragmentation:Divergent national cloud localization laws in Germany, France, and Saudi Arabia force redundant infrastructure deployment, raising total cost of ownership.
- Legacy mainframe telemetry gaps:Core banking and insurance systems on IBM z/OS platforms emit unstructured logs that resist standard OpenTelemetry ingestion without costly adapter development.
Strategic Opportunities
- Brazil ANVISA pharmaceutical manufacturing digitization:The regulator's push for continuous process verification creates demand for AIOps platforms that correlate batch records with environmental sensor data.
- Edge-to-cloud AI convergence:Federated learning architectures enabling on-device anomaly detection at manufacturing plants are opening subscription models for lightweight inference agents.
- US SEC cybersecurity disclosure rules:Public companies must demonstrate board-level visibility into material IT incidents, creating advisory service attach rates for governance dashboards.
Industry Challenges
- Site reliability engineering talent scarcity:Platform vendors and enterprise buyers compete for practitioners capable of tuning Bayesian belief networks for root cause analysis.
- ISO/IEC 42001 AI management system certification timelines:Eighteen-month audit cycles delay market entry for startups lacking documented risk management procedures.
- Multi-cloud data egress cost engineering:Correlating events across AWS, Azure, and GCP environments incurs unpredictable transfer fees that erode SaaS unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aiops Platform Market |
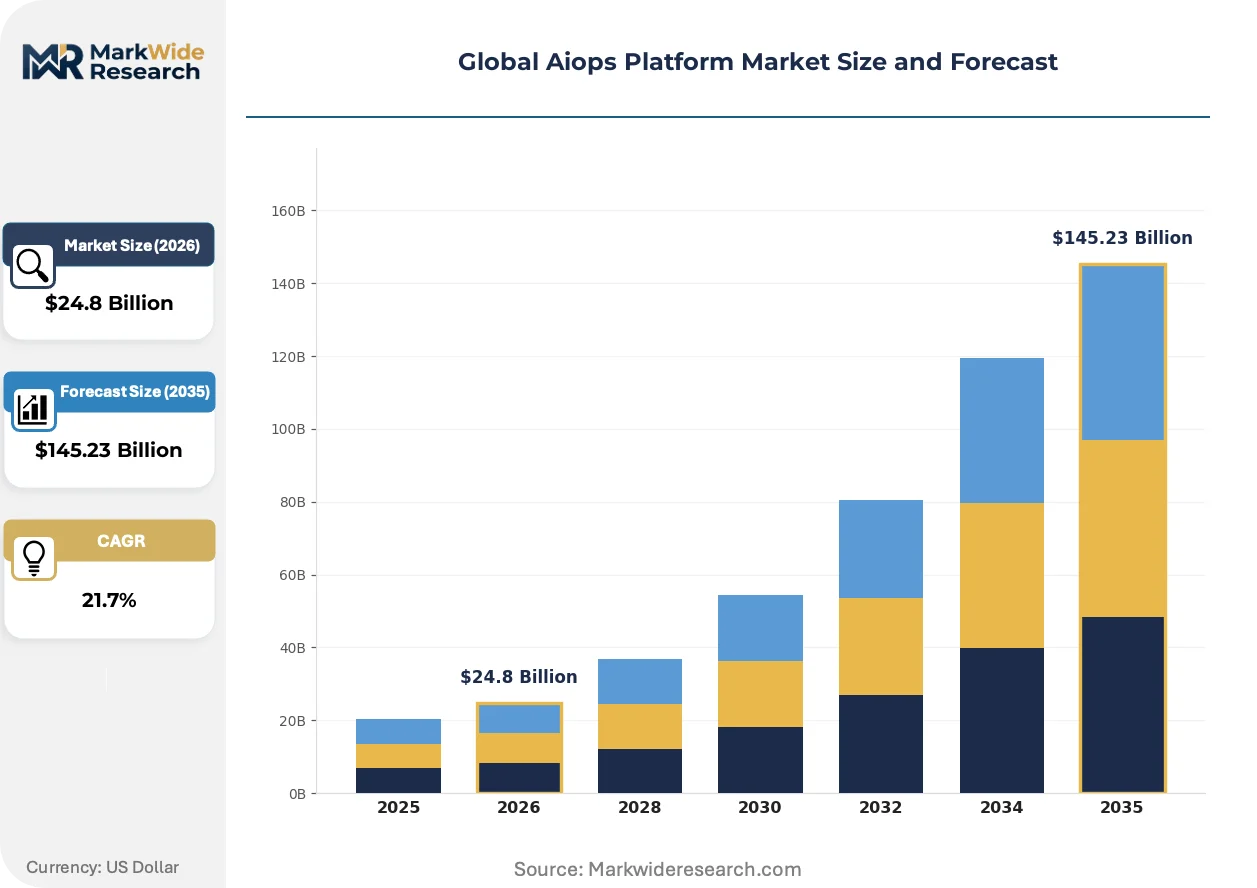
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $145.23 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Multi-cloud Solution: Event Correlation, Anomaly Detection, Predictive Analytics, Root Cause Analysis, Performance Monitoring Application: IT Operations Management, Network Monitoring, Security Analytics, Application Performance Monitoring, Customer Experience Management End User: Telecommunications, Financial Services, Manufacturing, Government, Technology Providers |
| Companies Covered | IBM, Splunk, Broadcom, Dynatrace, ServiceNow, Cisco Systems, Datadog, BMC Software, VMware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aiops Platform Market Shifts & Advancements
Foundation model architectures trained on operational telemetry are compressing the traditional rules-engine layer in AIOps platforms, enabling natural language incident investigation and automated runbook generation without explicit feature engineering.
Large language model integration is electrifying the diagnostic workflow layer. These systems parse unstructured incident descriptions and correlate them against historical resolution patterns. Financial services operations teams in Singapore and London are piloting conversational interfaces that slash mean time to detection. The technology is compressing tier-1 support staffing ratios while elevating human operators toward architectural remediation.
REACH chemical data governance is reshaping observability retention policies. The regulation's substance traceability requirements extend to IT infrastructure supporting manufacturing execution systems. Pharmaceutical companies operating European plants must now maintain seven-year audit trails for algorithmic decisions affecting batch release. Vendors are embedding immutable ledger storage into their data lake architectures to satisfy ECHA inspection protocols.
Consumption-based pricing is displacing seat-license models across mid-market accounts. Platform providers now meter event ingestion volume and automated remediation actions rather than charging per monitored host. This shift aligns vendor revenue with demonstrated operational value. Healthcare IT departments in the United States are negotiating contracts tied to reductions in patient-facing system downtime rather than fixed annual fees.
Global Aiops Platform Market Segmentation
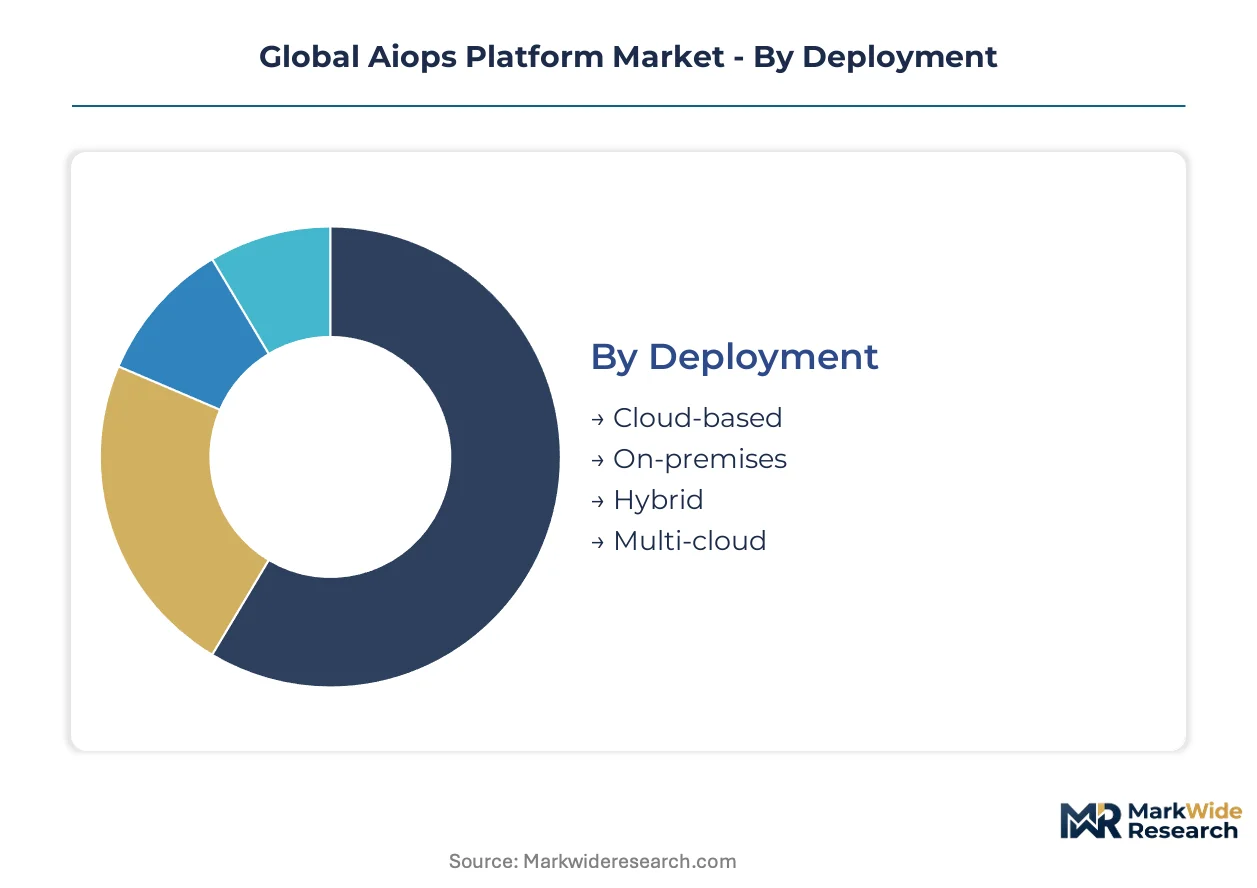
AIOps platforms segment across deployment architectures, solution capabilities, application domains, and end-user verticals. Each dimension carries distinct procurement criteria, integration complexity, and margin profiles that reshape vendor positioning.
Deployment:
Supply concentration in hyperscale cloud infrastructure is fragmenting vendor control over data pipelines, forcing platform rebuilds around Kubernetes-native observability standards.
- Cloud-based:Fully managed SaaS delivery eliminates infrastructure overhead for mid-market enterprises. Financial services institutions in Singapore and London prioritize this model for rapid deployment of event correlation capabilities without capital expenditure.
- On-premises:Air-gapped installations satisfy sovereign data residency mandates in defense and classified government environments. German automotive manufacturers deploy these configurations to retain telemetry within facility boundaries under BSI compliance frameworks.
- Hybrid:Bursting analytics workloads to public cloud while retaining sensitive ingestion on-site. Indian banks under RBI operational resilience guidelines favor this architecture for sub-second payment infrastructure monitoring.
- Multi-cloud:Correlation across AWS, Azure, and GCP environments with unified control planes. Technology providers managing distributed SaaS portfolios absorb unpredictable data egress costs for operational continuity.
Cloud-based deployments absorb the bulk of installed capacity; hybrid configurations are expanding most quickly.
Solution:
Cost tier differentiation separates premium causal AI modules from standardized anomaly detection, with R&D investment concentrating where operational expenditure reduction is most measurable.
- Event Correlation:Distributed architectures processing millions of events per minute through streaming telemetry ingestion. Telecommunications operators managing 5G network slicing complexity drive subscription growth for real-time correlation across ephemeral virtual network functions.
- Anomaly Detection:Bayesian belief networks and unsupervised learning identifying deviation patterns without explicit thresholds. Manufacturing execution systems in pharmaceutical plants under EMA algorithmic traceability mandates require these capabilities for continuous process verification.
- Predictive Analytics:Forecasting infrastructure degradation before service impact. US healthcare IT departments negotiate outcome-based contracts tied to reductions in patient-facing system downtime.
- Root Cause Analysis:Automated topological mapping of dependency relationships across hybrid infrastructure. Site reliability engineering talent scarcity elevates pricing for platforms with mature causal inference engines.
- Performance Monitoring:Real-time latency and throughput tracking across application tiers. Technology providers operating multi-tenant SaaS environments depend on these modules for SLA enforcement.
Event Correlation commands the greatest installed base; Root Cause Analysis is climbing the fastest as enterprises prioritize mean time to resolution compression.
Application:
Volume concentration in IT Operations Management is diverting platform engineering resources, while specialized applications command premium pricing through vertical-specific compliance integration.
- IT Operations Management:Unified control planes replacing fragmented monitoring toolchains. Government agencies across Australia and Canada consolidate legacy point solutions under single-pane observability.
- Network Monitoring:Deep packet inspection and flow analysis for telecommunications infrastructure. Brazilian mobile operators expanding 5G coverage deploy these capabilities for real-time quality of service assurance.
- Security Analytics:Correlating IT operational telemetry with threat intelligence feeds. US SEC cybersecurity disclosure rules mandate board-level visibility into material incidents, elevating governance dashboard attach rates.
- Application Performance Monitoring:End-user experience tracking through distributed tracing. Financial services institutions in Switzerland optimize high-frequency trading platforms using sub-millisecond latency analytics.
- Customer Experience Management:Bridging infrastructure telemetry with business outcome metrics. Retail technology providers in South Korea correlate checkout system performance with conversion rate impact.
IT Operations Management retains the deepest penetration; Security Analytics is gaining share fastest through regulatory compliance pull.
End User:
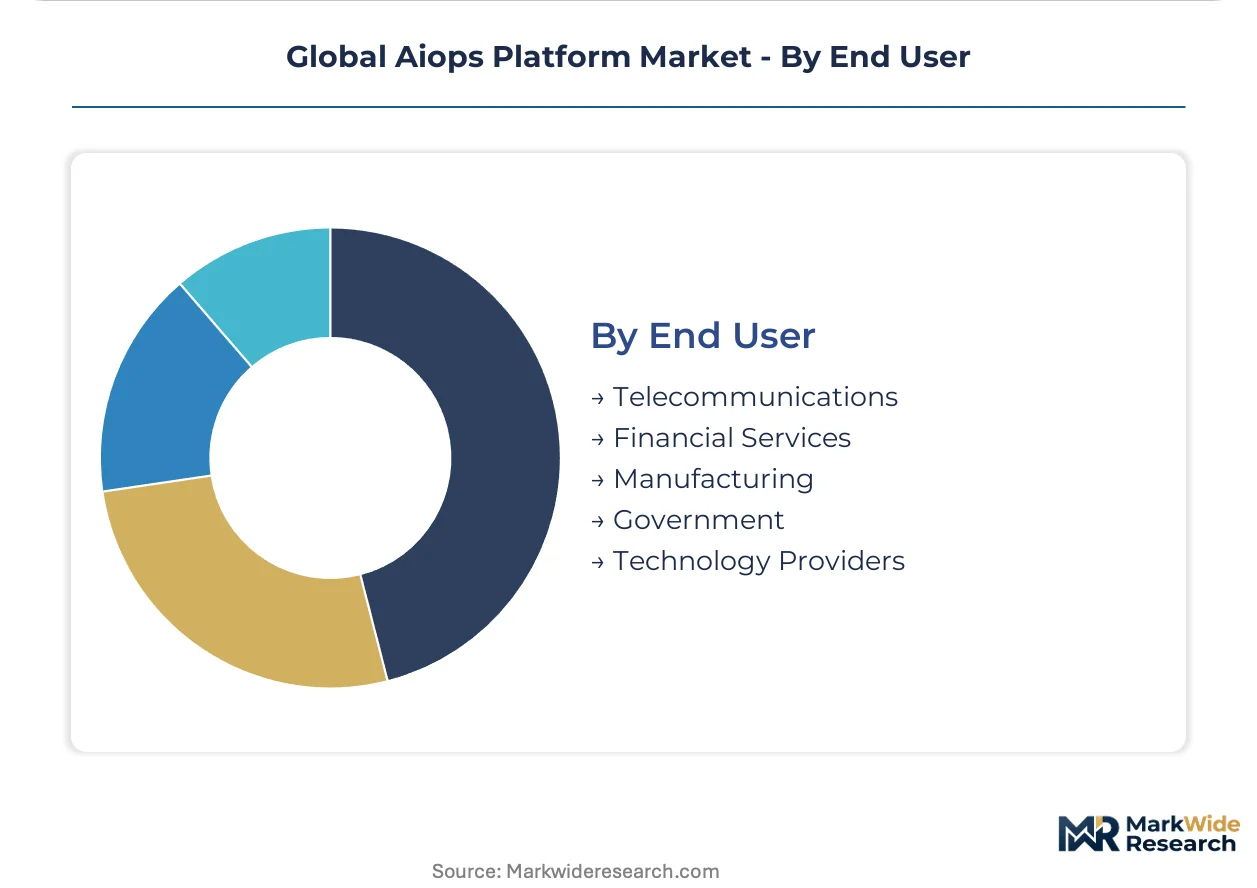
Customer type stratification separates regulated industries with procurement complexity from technology providers with technical sophistication, reshaping sales motion and implementation support models.
- Telecommunications:5G network slicing and edge computing infrastructure generate massive telemetry volumes. Mobile operators in Japan under METI digital transformation mandates prioritize platforms with native support for containerized network functions.
- Financial Services:Hybrid cloud complexity and algorithmic trading infrastructure demand sub-second anomaly detection. Saudi Arabian banks under SAMR operational resilience guidelines accelerate deployment for digital payment protection.
- Manufacturing:Correlating operational technology with IT infrastructure for predictive maintenance. Pharmaceutical companies in Brazil under ANVISA continuous process verification requirements integrate batch record systems with environmental sensor data.
- Government:Classified workloads and sovereign cloud mandates drive on-premises preference. Defense agencies in the United Kingdom specify NCSC-approved platforms with immutable audit trails.
- Technology Providers:Multi-tenant SaaS operations requiring elastic scaling of observability infrastructure. Cloud-native software companies in Israel optimize unit economics through consumption-based pricing alignment.
Financial Services represents the largest revenue pool; Manufacturing is expanding most quickly through industrial digitization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Singapore and Dubai concentrate AIOps deployment for financial services, while sovereign cloud mandates in Frankfurt and Riyadh reshape data residency architectures. Tax incentives for digital infrastructure in Bangalore and São Paulo accelerate platform adoption among telecommunications operators and pharmaceutical manufacturers.
United States
Cloud migration and federal cybersecurity mandates drive procurement across financial services and healthcare. SEC disclosure rules and HIPAA requirements elevate audit-grade observability standards. New York and San Francisco anchor hybrid cloud deployments for algorithmic trading infrastructure.
Germany
Automotive manufacturing digitization and BSI compliance frameworks sustain on-premises preference. EU AI Act algorithmic traceability mandates reshape procurement for pharmaceutical batch release systems. Bavaria hosts sovereign cloud deployments for automotive predictive maintenance platforms.
India
RBI operational resilience guidelines mandate sub-second incident detection across digital payment infrastructure. Mumbai and Bangalore concentrate banking sector deployments under central bank supervision. Telangana's Hyderabad cluster attracts technology provider SaaS operations.
Singapore
Financial services regulatory sandbox programs accelerate conversational AI pilots for incident investigation. MAS technology risk management guidelines elevate governance dashboard requirements. The city-state anchors Asia-Pacific headquarters for multi-tenant observability providers.
Brazil
ANVISA pharmaceutical manufacturing digitization creates demand for batch record correlation with environmental sensors. São Paulo concentrates industrial IoT deployments under continuous process verification mandates. The country's central bank operational resilience guidelines mirror RBI frameworks.
Global Aiops Platform Market Competitive Landscape
United States producers anchor the scale tier; European specialists hold compliance-integrated positions. The market structures around three tiers: hyperscale cloud-native platforms, legacy infrastructure vendors with AI overlays, and vertical-specific challengers. Consolidation pressure intensifies as event-stream processing capabilities become table stakes. Strategic moves concentrate on Kubernetes-native observability rebuilds and sovereign cloud partnership architectures.
Within the enterprise software tier, IBM and ServiceNow exemplify archetypes diverging on workflow integration depth. Dynatrace occupies a position emphasizing causal analytics for application performance monitoring. Splunk represents the data platform vector, anchoring security-operations convergence. These three illustrate how vendor origin—Armonk-based systems integrator, Santa Clara cloud-native specialist, and San Francisco data platform—maps to distinct procurement channels across financial services and telecommunications verticals.
| Leading Market Players |
|---|
| IBM |
| Splunk |
| Broadcom |
| Dynatrace |
| ServiceNow |
| Cisco Systems |
| Datadog |
| BMC Software |
| VMware |
| Others |
Supply & Pricing Matrix
Certification-grade platform divergence separates premium AIOps vendors with ISO/IEC 42001 AI management system credentials from commodity anomaly detection providers, compressing margins in the standard tier while sovereign cloud partnerships and GPU compute access anchor premium pricing power and reshape supplier selection criteria across European and Middle Eastern procurement cycles.
Pricing Analysis
Short lead-time deployment premiums dominate AIOps procurement, with fully managed SaaS configurations commanding substantial markups over six-month implementation timelines for air-gapped on-premises installations. Consumption-based pricing models metering event ingestion volume and automated remediation actions are displacing per-seat licensing across mid-market accounts, while outcome-based contracts tied to patient-facing system downtime reductions signal the least price-sensitive segment in US healthcare IT. Cost compression in the standard tier intensifies as open-source telemetry standards commoditize basic anomaly detection, though root cause analysis modules with embedded causal AI sustain pricing power through site reliability engineering talent scarcity.
Supply Chain Analysis
Cross-border data transfer costs from hyperscale cloud regions in the United States, Ireland, and Singapore directly inflate total cost of ownership for multi-cloud correlation architectures, forcing vendors to optimize ingress routing through sovereign cloud partnerships in Frankfurt and Riyadh. NVIDIA H100 GPU supply concentration from Taiwan and South Korea creates single-source vulnerability for training and inference workloads, while OpenTelemetry standardization and Kubernetes-native observability tooling reduce adapter development dependencies. Distribution runs through direct enterprise sales teams for regulated financial services and telecommunications accounts, with channel partners handling mid-market technology provider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as event-stream processing capabilities become table stakes, forcing subscale vendors toward acquisition or exit as hyperscale cloud-native platforms and legacy infrastructure vendors with AI overlays capture procurement decisions in financial services and telecommunications.
For Market Incumbents: Deepen vertical integration into sovereign cloud infrastructure through partnerships with national data residency providers in Germany, Saudi Arabia, and India, defending against emerging challengers with compliance-integrated positioning. Expand ISO/IEC 42001 certification coverage across product modules to maintain procurement eligibility under EU AI Act algorithmic traceability mandates, while embedding governance dashboards to capture advisory service attach rates from US SEC cybersecurity disclosure compliance.
For New Entrants and Emerging Players: Launch via consumption-based pricing models targeting Brazilian pharmaceutical manufacturers under ANVISA continuous process verification mandates, where incumbent platform complexity creates white-space opportunity for lightweight inference agents. Target India's RBI-regulated banking sector through hybrid deployment architectures enabling sub-second payment infrastructure monitoring, leveraging the country's technology provider cluster in Hyderabad for implementation support density.
For Investors and Strategic Acquirers: Re-rating potential sits with vertical-specific challengers possessing EMA-validated algorithmic traceability modules given EU AI Act enforcement recalibrating European enterprise procurement criteria. Acquisition targets should demonstrate documented risk management procedures compressing ISO/IEC 42001 audit cycles below eighteen-month timelines, with long-term viability hinging on federated learning architectures enabling edge-to-cloud AI convergence. Monitor GPU allocation priority agreements with NVIDIA as the critical inflection signal distinguishing scalable inference capacity from margin-compressed commodity positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding AIOps into ServiceNow enterprise service management workflows captures financial services renewal cycles. |
| Strategic Partnership | Sovereign cloud alliances with BSI-compliant German providers satisfy automotive telemetry residency mandates. |
| Acquisition of Specialist Firm | Causal analytics capabilities address site reliability engineering talent scarcity compressing mean time to resolution. |
| Geographic Expansion | Hyderabad cluster presence accelerates Indian banking sector deployment under RBI operational resilience guidelines. |
| Product Launch | Conversational AI interfaces for natural language incident investigation slash tier-1 support staffing ratios in Singapore. |
Research Methodology
SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory guidance documents formed the secondary backbone, supplemented by customs records tracking GPU import flows and formulary databases mapping healthcare IT procurement patterns. Primary interviews with platform engineers, IT procurement officers at financial services institutions, and integration specialists validated deployment architecture preferences across cloud-native and hybrid configurations. Bottom-up and top-down triangulation combined vendor revenue disclosures with end-user spending surveys across telecommunications and banking verticals.
Bottom-up modeling aggregated individual deployment contracts by organization size, vertical, and integration complexity, while top-down analysis cross-referenced aggregate AIOps spending against IT operations management software market totals. Segmentation dimensions included deployment model, solution capability tier, application domain, and end-user vertical, with CAGRs derived from curve-fitting historical adoption rates against regulatory mandate timelines. Forecast inputs incorporated RBI operational resilience guideline implementation schedules and EU AI Act enforcement phase transitions.
GPU supply allocation disruptions, divergent national cloud localization law implementations, and foundation model architecture shifts are the dominant revision risks to projection assumptions. Stakeholders should weight assumptions against their own operating context and sovereign data residency requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Law Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
AI Orchestration Market