
 E-Commerce in Nigeria Market | 2026-2036
E-Commerce in Nigeria Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce in Nigeria Market Insights
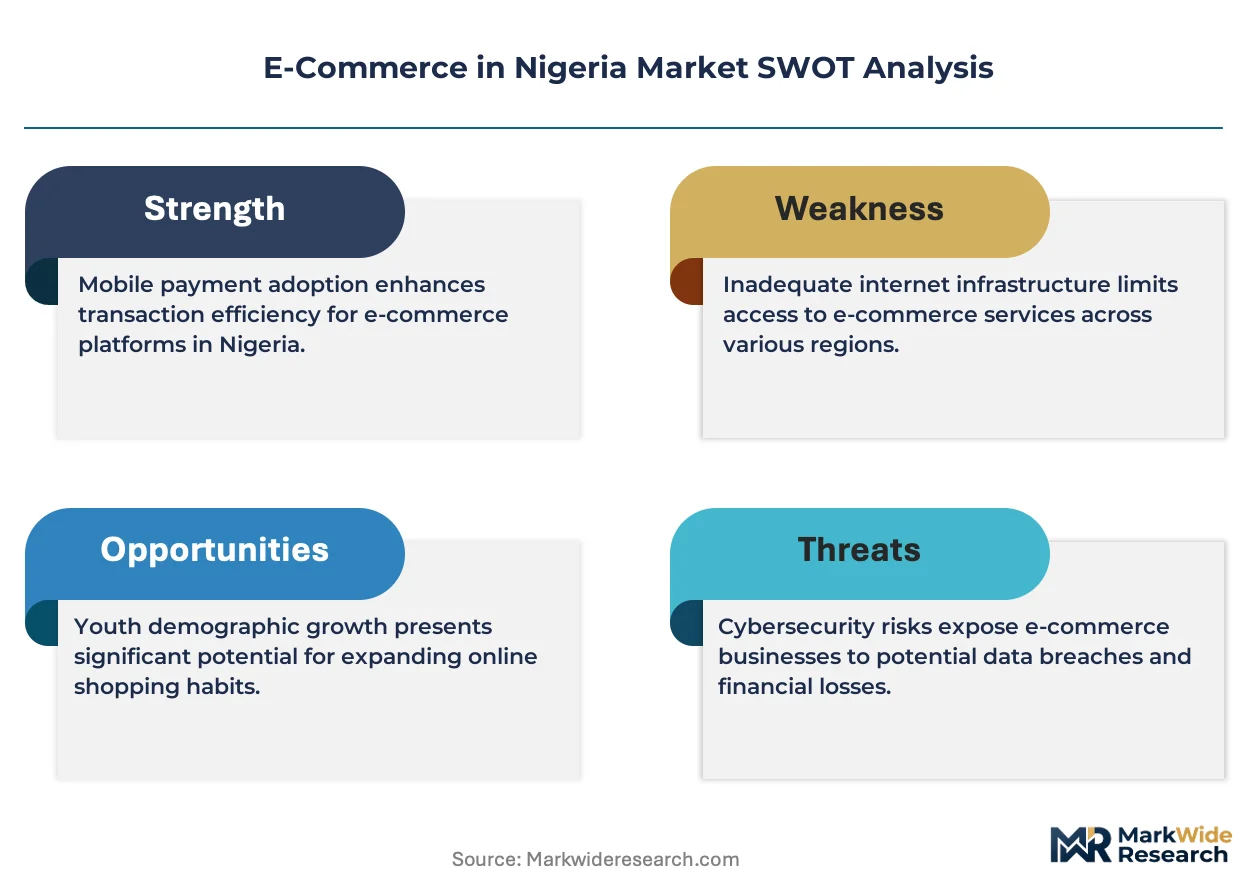
PCIDSS certification is rotating as the decisive gating standard for payment processors and marketplace operators seeking direct integration with Nigerian banking rails. Jumia Technologies AG leverages its proprietary logistics network to sustain next-day delivery promises in Lagos and Abuja. Konga Online Shopping Limited anchors its competitiveness through hybrid online-offline presence with physical experience centers. Jiji Africa B.V. differentiates via classified-listing economics that eliminate inventory risk for informal sellers.
E-commerce in Nigeria denotes digitally mediated commercial transactions where goods exchange through web interfaces, mobile applications, or social commerce layers, with order fulfillment dependent on third-party logistics or captive delivery fleets operating across infrastructure-variable terrain. The primary commercial purpose centers on reducing friction between dispersed consumer demand and fragmented retail supply, substituting physical storefront capital with digital customer acquisition and warehouse consolidation. Electronics commands the largest transaction value within product category segmentation, though groceries is recording the fastest velocity expansion as quick-commerce models compress delivery windows. Mobile payment methods within the payment method dimension now dominate transaction mix, displacing cash on delivery as fintech infrastructure deepens, while marketplace sales channels absorb the highest customer acquisition spend relative to owned online platforms.
The Central Bank of Nigeria governs electronic payment licensing and settlement system access, while the Federal Competition and Consumer Protection Commission monitors platform conduct and seller-buyer dispute resolution. Nigeria Data Protection Regulation compliance requirements impose data localization and consent management burdens that elevate operating costs for cross-border platform operators. Stakeholders must weigh captive logistics investment against third-party aggregator reliance as infrastructure quality diverges across state-level markets.
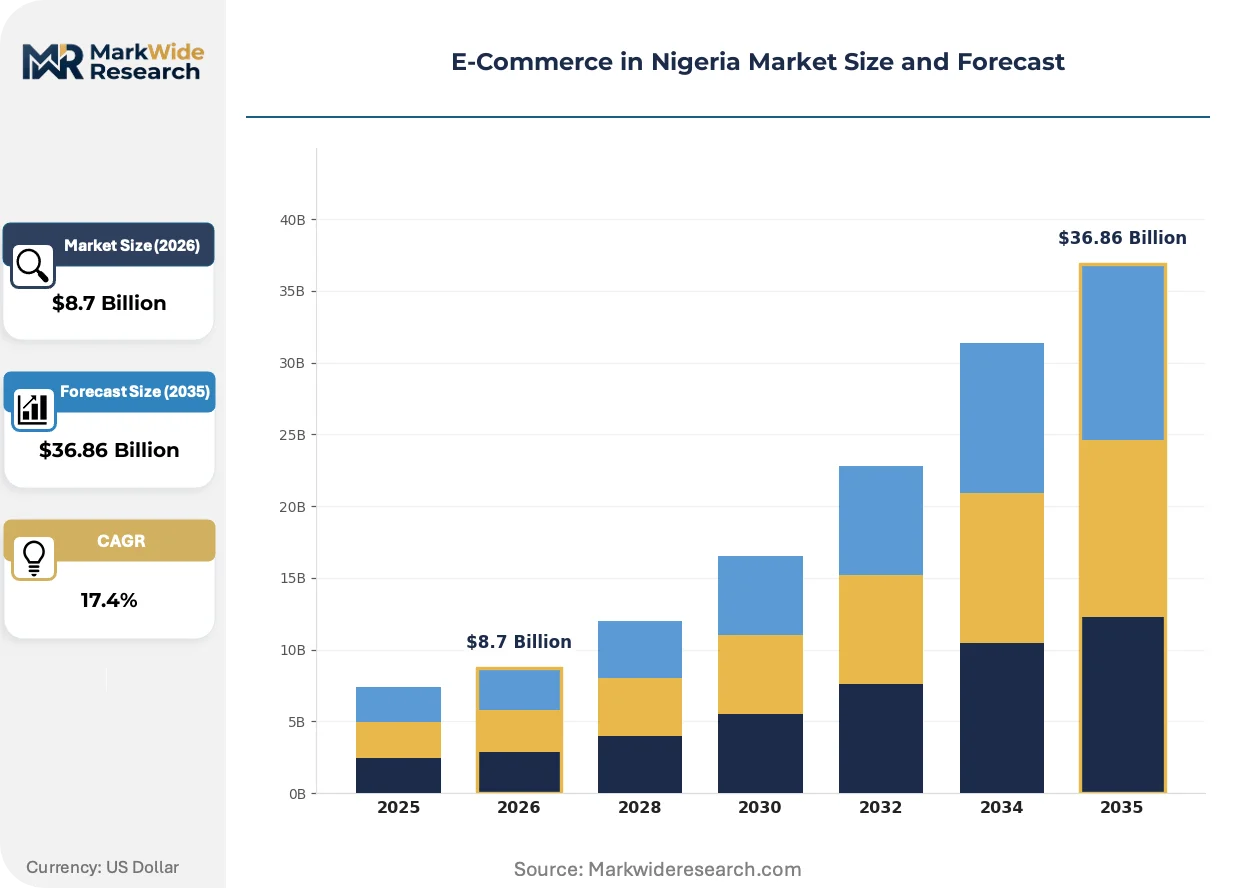
Market Dynamics
The Central Bank of Nigeria's cashless policy is compressing transaction settlement windows and forcing platform operators to migrate from cash-on-delivery toward instant payment rails. This regulatory pressure is reshaping capital requirements for marketplace liquidity management.
Growth Catalysts
- NIBSS Instant Payment Infrastructure:The Nigeria Inter-Bank Settlement System enables real-time fund transfers that reduce payment friction for digital commerce transactions.
- Smartphone Penetration in Lagos:Dense urban device ownership creates addressable audiences for mobile-first shopping interfaces and app-based loyalty programs.
- Quick-Commerce Models:Compressed delivery windows for groceries and essentials are expanding order frequency among time-constrained urban households.
Market Restraints
- Fuel Cost Volatility:Diesel and petrol price instability directly inflates last-mile delivery costs for third-party logistics providers operating outside Lagos.
- Data Localization Mandates:Nigeria Data Protection Regulation compliance imposes server infrastructure requirements that elevate operating costs for cross-border platforms.
- Road Infrastructure Deficits:Poor highway conditions between state capitals extend transit times and damage rates for electronics shipments.
Strategic Opportunities
- Abuja Federal Capital Territory:Underpenetrated relative to Lagos, this market offers superior income demographics with less competitive density for fulfillment network expansion.
- Social Commerce Layers:WhatsApp and Instagram-integrated checkout tools unlock informal seller participation without dedicated app development.
- PCIDSS Certification Tailwinds:Payment processor licensing requirements create competitive moats for compliant domestic fintech aggregators.
Industry Challenges
- Warehousing Skill Shortages:Inventory management and cold-chain operations expertise remains scarce outside Lagos and Port Harcourt logistics clusters.
- Legacy ERP Integration:Marketplace operators face friction connecting modern front-end stacks to seller accounting systems prevalent in informal retail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce in Nigeria Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Groceries, Health & Beauty Sales Channel: Online Platform, Mobile App, Social Media, Marketplace Customer Type: Retail Consumers, SMEs, Corporates, Businesses Payment Method: Credit Card, Bank Transfer, Mobile Payment, Cash on Delivery |
| Companies Covered | Jumia Technologies AG, Konga Online Shopping Limited, Jiji Africa B.V., SLOT Systems Limited, Omniretail Technologies Limited, PayPorte Global Systems Limited, Chrisvicmall, Ajebomarket Limited, Mall for Africa Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce in Nigeria Market Trends and Innovations
Platform economics in Nigerian e-commerce are pivoting toward captive infrastructure control and regulatory compliance as primary differentiation vectors. Three forces are compressing competitive timelines.
Artificial intelligence-driven demand forecasting is bifurcating inventory management approaches between large platforms with proprietary data lakes and smaller operators dependent on supplier estimates. Jumia Technologies AG deploys machine learning models to predict Lagos neighborhood-level demand patterns for electronics. This capability compresses working capital cycles and reduces stockout rates in high-velocity categories.
The Central Bank of Nigeria's PCIDSS certification mandate is elevating technical barriers for payment gateway operators seeking direct banking rail access. Non-compliant processors must route through licensed intermediaries, increasing transaction cost bases. Marketplace operators with captive fintech licenses capture margin that aggregators forfeit to third-party payment service providers.
Urban millennial buyers are consolidating purchase decisions around next-day delivery promises rather than price comparison across platforms. This behavioral shift elevates logistics network density as the decisive competitive variable. Lagos State concentration of fulfillment centers enables superior unit economics that platforms struggle to replicate in Kano or Ibadan.
E-Commerce in Nigeria Market Segmentation
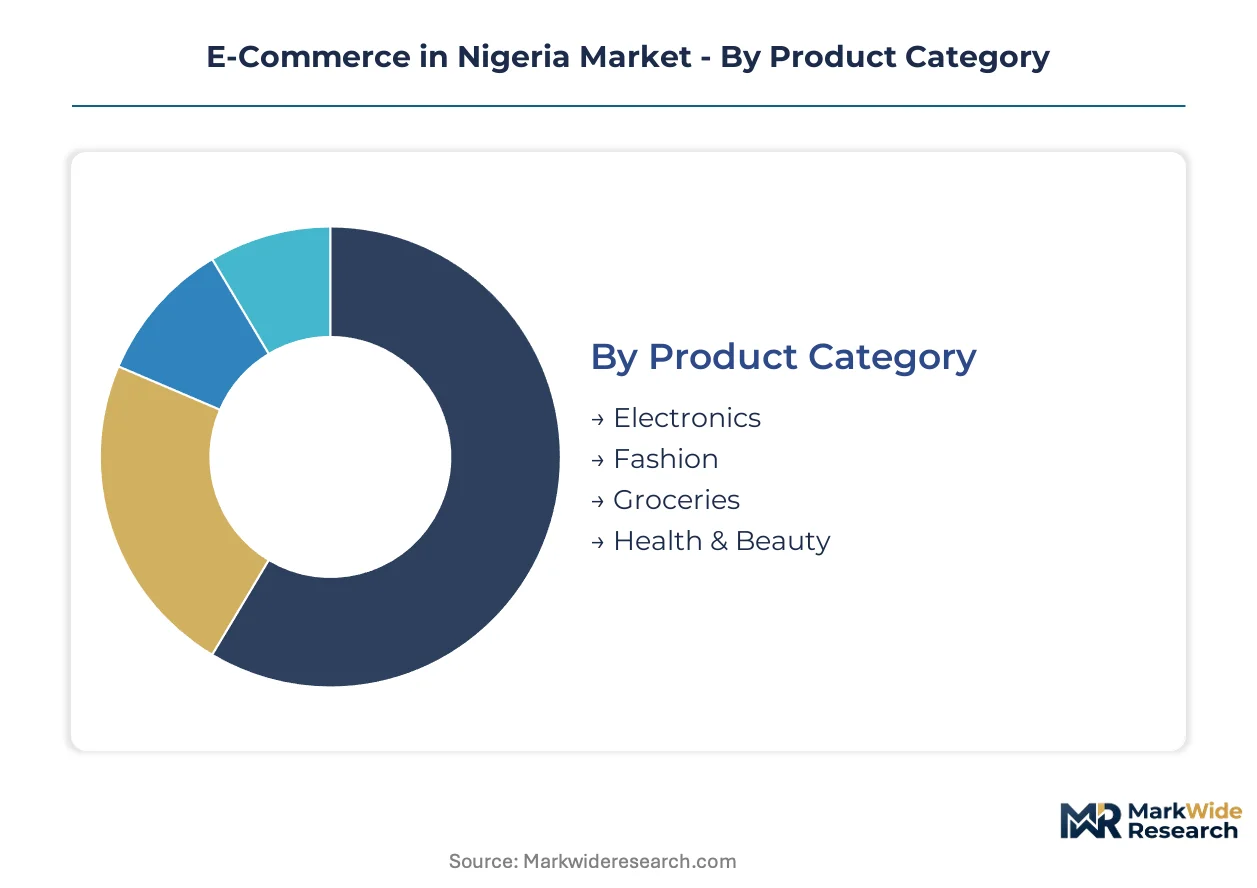
E-commerce segmentation in Nigeria reveals how platform economics diverge across transaction layers. Channel configuration determines fulfillment cost structures, while payment method mix shapes working capital intensity for marketplace operators.
Product Category:
Channel-mix patterns vary sharply across product types, with high-value electronics flowing through owned platforms while groceries penetrate via quick-commerce mobile interfaces.
- Electronics:Smartphones, laptops, and consumer appliances command the highest average order values. Demand clusters in Lagos and Abuja urban corridors where device financing partnerships with commercial banks expand addressable wallets.
- Fashion:Apparel and accessories leverage social commerce discovery layers. Instagram-integrated checkout tools dominate acquisition for informal sellers in Kano and Ibadan textile trading clusters.
- Groceries:Food staples and household essentials are compressing delivery windows toward two-hour fulfillment. Quick-commerce models concentrate in Lagos State where cold-chain warehouse density supports perishables.
- Health & Beauty:Pharmaceuticals and personal care products face regulatory scrutiny from the National Agency for Food and Drug Administration and Control. Prescription verification requirements favor established pharmacy chains with licensed logistics partnerships.
Electronics dominates installed base. Groceries is where expansion concentrates.
Sales Channel:
Cost tier differentiation separates capital-intensive captive platforms from asset-light intermediary models.
- Online Platform:Proprietary websites with integrated checkout and fulfillment tracking absorb the highest customer acquisition spend. Jumia and Konga deploy Lagos-based data centers to reduce latency for image-heavy product catalogs.
- Mobile App:Native applications capture superior retention through push-notification loyalty programs. Smartphone penetration in Lagos State exceeds other Nigerian markets, creating addressable audience concentration.
- Social Media:WhatsApp Business and Instagram Shopping eliminate app development costs for informal sellers. Payment settlement occurs through mobile money wallets rather than direct banking integration.
- Marketplace:Third-party seller aggregation generates commission revenue without inventory risk. The Federal Competition and Consumer Protection Commission monitors dispute resolution and platform fee transparency.
Marketplace channels dominate seller participation volume. Mobile App is climbing the fastest for repeat purchase frequency.
Customer Type:
Application intensity varies by procurement sophistication and order aggregation scale.
- Retail Consumers:Individual buyers drive frequency through mobile-first interfaces. Cash-on-delivery preference persists outside Lagos where mobile payment penetration remains uneven.
- SMEs:Small enterprises procure inventory and supplies through B2B marketplace verticals. Bulk order negotiation tools differentiate dedicated procurement platforms from consumer-facing sites.
- Corporates:Large organizations require invoice-based settlement and vendor onboarding compliance. Enterprise procurement contracts favor platforms with ISO 27001 certification and audited fulfillment SLAs.
- Businesses:Mid-sized entities blend retail and wholesale purchasing patterns. Hybrid customer segments strain platform taxonomy and pricing architecture.
Retail Consumers anchor transaction volume. SMEs are gaining share fastest as B2B marketplace infrastructure matures.
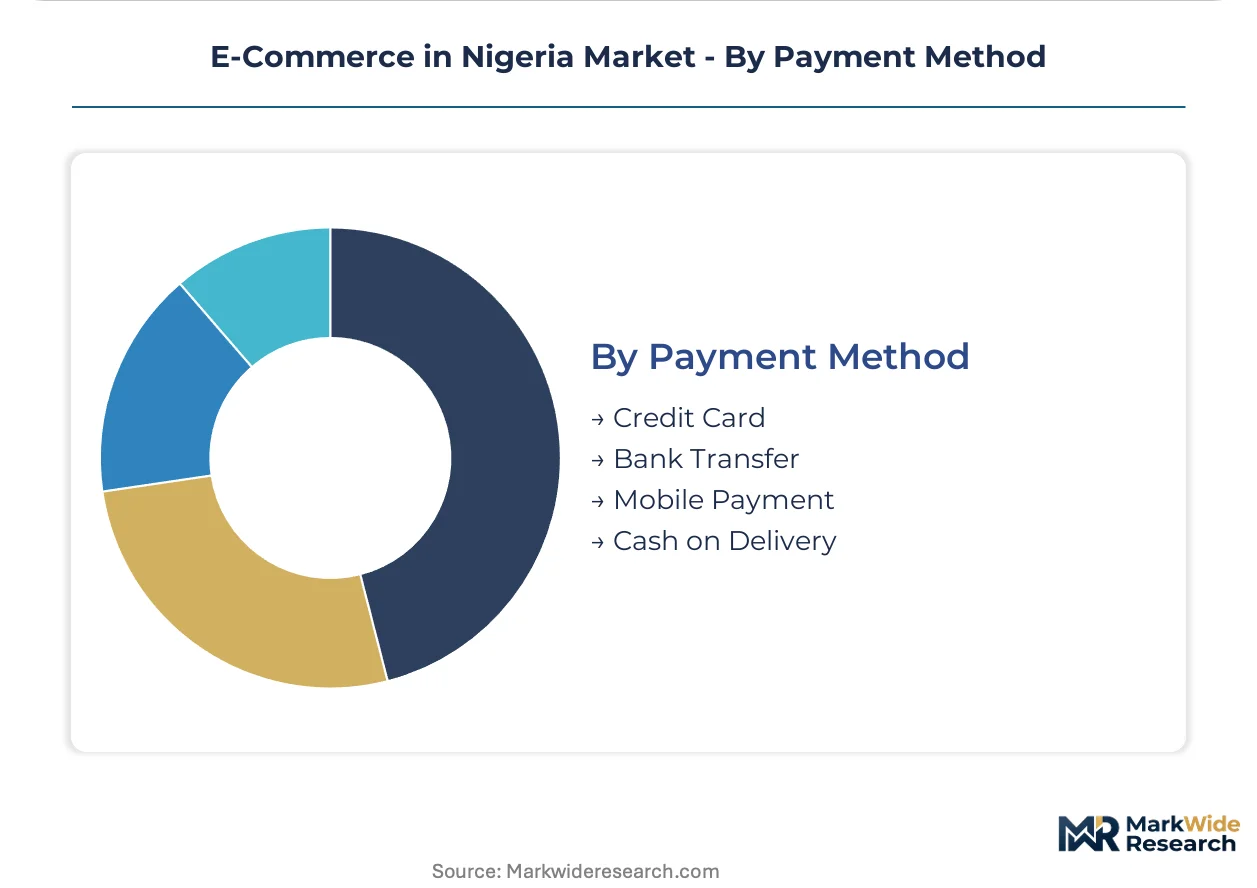
Payment Method:
Margin structure hinges on settlement speed and intermediary fee stacking.
- Credit Card:Card penetration remains limited to upper-income Lagos demographics. International scheme fees elevate transaction costs for cross-border platform operators.
- Bank Transfer:NIBSS instant payment rails enable real-time settlement without card network intermediation. Direct bank integration reduces working capital cycles for marketplace liquidity management.
- Mobile Payment:OPay, PalmPay, and similar fintech wallets dominate transaction mix. Central Bank of Nigeria licensing requirements create competitive moats for compliant domestic aggregators.
- Cash on Delivery:Legacy payment mode faces regulatory compression under cashless policy mandates. Fraud rates and return logistics costs erode platform economics in secondary cities.
Mobile Payment dominates new transaction origination. Bank Transfer is where infrastructure investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial buyers concentrate transaction volume in Lagos State, where smartphone penetration and logistics density create superior unit economics for platform operators targeting Nigeria's most addressable digital commerce audience.
Lagos State
Lagos State absorbs the highest e-commerce transaction density through its concentration of fulfillment centers and payment infrastructure. The Central Bank of Nigeria's cashless policy accelerates mobile wallet adoption among the state's banked population. Ikeja and Lekki logistics clusters enable next-day delivery promises that platforms struggle to replicate elsewhere.
Federal Capital Territory
Abuja offers underpenetrated income demographics with less competitive density for fulfillment network expansion. The Federal Competition and Consumer Protection Commission monitors platform conduct disputes in this administrative hub. Wuse and Garki districts concentrate mid-income households with rising quick-commerce demand for groceries.
Kano State
Kano's textile trading clusters drive fashion commerce through social media discovery layers rather than dedicated apps. The National Agency for Food and Drug Administration and Control regulates pharmaceutical shipments entering the northern corridor. Sabon Gari market operators increasingly adopt WhatsApp Business for inventory display and order negotiation.
Rivers State
Port Harcourt anchors petroleum industry procurement demand for B2B marketplace verticals serving energy sector SMEs. Nigeria Data Protection Regulation compliance requirements elevate server infrastructure costs for platforms operating in this region. Trans Amadi industrial zone concentrates warehousing skill shortages that constrain cold-chain expansion.
Oyo State
Ibadan's emerging middle class generates growing order frequency for electronics and household appliances through mobile-first interfaces. Fuel cost volatility directly inflates last-mile delivery costs for third-party logistics providers serving this secondary city. Ring Road commercial districts host informal sellers transitioning from physical stalls to Instagram-integrated checkout tools.
E-Commerce in Nigeria Market Competitive Landscape
Player mix skews toward integrated marketplace operators with captive logistics networks and classified-listing platforms eliminating inventory risk. Market structure concentrates around three archetypes: full-stack platforms with proprietary fulfillment, hybrid online-offline retailers with physical experience centers, and asset-light intermediaries aggregating third-party sellers. Dominant competitive moves include geographic expansion into underpenetrated state capitals and technology licensing for social commerce checkout integration.
Within the full-stack platform tier, Jumia Technologies AG and Konga Online Shopping Limited represent integrated operators sustaining delivery promises through captive infrastructure. Jiji Africa B.V. occupies a position exemplifying the classified-listing archetype that removes inventory exposure for informal sellers. SLOT Systems Limited anchors the electronics-specialist segment with hybrid physical-digital presence.
| Leading Market Players |
|---|
| Jumia Technologies AG |
| Konga Online Shopping Limited |
| Jiji Africa B.V. |
| SLOT Systems Limited |
| Omniretail Technologies Limited |
| PayPorte Global Systems Limited |
| Chrisvicmall |
| Ajebomarket Limited |
| Mall for Africa Inc. |
| Others |
Pricing and Supply Chain Analysis
Take-or-pay warehousing contracts with third-party logistics providers lock in both fulfillment capacity and last-mile cost visibility for Nigerian e-commerce platforms operating outside Lagos State. These arrangements tether pricing power to diesel price indexation, exposing margin structures to fuel volatility that third-party providers pass through without absorption.
Pricing Analysis
Cost-plus contracts with diesel indexation dominate third-party logistics pricing, embedding fuel volatility directly into fulfillment economics. Three-tier pricing structure across premium next-day, standard 3-5 day, and economy 7-14 day delivery tiers separates Jumia's captive network from aggregator-dependent competitors. Cost compression in the economy tier is intensifying because informal sellers on social commerce layers absorb delivery fees to maintain price parity. SME bulk purchasers exhibit highest price sensitivity, while corporate procurement contracts with invoice-based settlement show lowest elasticity.
Supply Chain Analysis
Apapa port congestion and container availability constraints on the China-Nigeria trade lane inflate inbound electronics procurement costs for marketplace operators. Manufacturing concentration in China, South Korea, and Vietnam feeds smartphone and consumer appliance inventory into Lagos fulfillment centers. Single-source vulnerability rests on Ningbo-Shenzhen shipping corridors where piracy risk and customs delays compound lead time uncertainty. Distribution runs through Lagos-based bonded warehouses before state-level hub-and-spoke deployment to Abuja, Kano, and Port Harcourt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nigerian e-commerce represents an early-cycle expansion story where cashless policy tailwinds and NIBSS infrastructure penetration are compressing payment friction faster than logistics costs can adapt.
For Market Incumbents: Fortify captive logistics density in Lagos through cold-chain warehouse additions that sustain next-day delivery promises against quick-commerce entrants. Deepen backward integration into payment processing by securing PCIDSS certification to capture margin forfeited to third-party aggregators under Central Bank licensing requirements. For New Entrants and Emerging Players: Lead with social commerce checkout tools targeting Kano and Ibadan textile clusters where Instagram-integrated discovery layers bypass app development costs. Abuja Federal Capital Territory offers the most penetrable geography given superior income demographics against sparse fulfillment network coverage from established platforms. For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors vertically integrated platforms with captive logistics networks over asset-light marketplace models. Long-term viability hinges on warehousing skill acquisition and state-level license navigation. Watch NIBSS transaction volume growth as the inflection signal for mobile payment penetration tipping points outside Lagos.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Logistics Network Expansion | Warehouse density in Lagos State enables next-day delivery promises that competitors cannot replicate. |
| PCIDSS Certification Investment | Direct banking rail access reduces transaction cost bases versus aggregator-dependent processors. |
| Quick-Commerce Model Launch | Two-hour grocery delivery captures frequency among time-constrained urban millennial households. |
| Social Commerce Checkout Integration | WhatsApp Business tools unlock informal seller participation without dedicated application development. |
| Abuja Fulfillment Hub Establishment | Underpenetrated federal capital offers superior income demographics with less competitive density. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with e-commerce platform executives, third-party logistics fleet managers, fintech payment gateway engineers, and informal seller network coordinators. Secondary validation drew from Central Bank of Nigeria payment system reports, NIBSS transaction volume disclosures, Federal Competition and Consumer Protection Commission enforcement records, and customs import data for electronics categories. Bottom-up seller enumeration and top-down payment flow triangulation anchored market sizing.
Across the analysis window, volume and value outputs reflect segmentation modeling across product category, sales channel, customer type, and payment method dimensions with state-level geographic disaggregation. CAGRs were derived from trend extrapolation of NIBSS instant payment adoption curves, smartphone penetration trajectories, and logistics cost inflation assumptions. Forecast inputs incorporated diesel price volatility scenarios and cashless policy implementation pace.
The analysis sits within stated boundaries; outcomes outside sustained NIBSS infrastructure investment and manageable fuel cost environments would require recalibration. Forecasts reflect assumptions about regulatory continuity for data localization mandates and PCIDSS certification requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
Belgium E-Commerce Market
E-Commerce Solutions
United Arab Emirates E-Commerce Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
Serbia E-Commerce Market
E-Commerce Solutions
Global Online Book Services Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Iceland E-Commerce Market