
 Wireless Handheld Spectrometer Market | 2026-2036
Wireless Handheld Spectrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Handheld Spectrometer Market Analytics
Germany's precision optics manufacturing corridor is reshaping supply dynamics for compact spectral devices. Thermo Fisher Scientific leverages its deep life sciences channel to dominate pharmaceutical end-user placements. Bruker Corporation anchors European demand through specialized Raman and NIR handheld platforms. Agilent Technologies competes on wireless connectivity integration, differentiating its field-deployable units for environmental monitoring applications.
A wireless handheld spectrometer integrates a compact diffraction grating or interferometer with a solid-state detector, Bluetooth or Wi-Fi module, and embedded microprocessor to deliver real-time spectral analysis outside laboratory confines. These devices typically operate across 200-2500 nm wavelength ranges with resolution down to 4-10 cm⁻¹, serving on-site material identification and compositional verification. Raman product types command premium positioning due to minimal sample preparation requirements and fingerprint-level specificity for pharmaceutical authentication. UV-Vis segments occupy stable volume tiers in agricultural nutrient testing, while wireless connectivity technology layers are attracting disproportionate R&D investment as OEMs race to enable cloud-linked spectral databases for field technicians.
FDA 21 CFR Part 11 compliance requirements and EU MDR traceability mandates are elevating demand for validated handheld units with audit-ready data logging. EMA's intensified scrutiny of pharmaceutical supply chain integrity is pushing manufacturers toward portable verification tools at receiving docks. REACH substance restrictions are simultaneously constraining certain detector materials, forcing redesign cycles among component suppliers. Stakeholders must weigh calibration protocol standardization against the fragmentation of cloud platform ecosystems before committing to multi-unit fleet deployments.
Market Dynamics
Cloud-linked spectral databases are compressing calibration cycles and forcing OEMs to choose between proprietary platforms and open interoperability standards. This technology shift is redrawing competitive boundaries around data ownership rather than hardware performance alone.
Growth Catalysts
- FDA 21 CFR Part 11:Pharmaceutical manufacturers face escalating audit requirements for raw material verification at receiving docks, mandating validated handheld units with tamper-evident data logging.
- Raman spectroscopy:Fingerprint-level specificity for active pharmaceutical ingredient authentication eliminates extensive sample preparation, accelerating on-site deployment by quality control teams.
- Munich-Berlin precision corridor:Germany's concentrated optics manufacturing ecosystem supplies compact diffraction gratings and solid-state detectors at scale, reducing component lead times for device assemblers.
Market Restraints
- Indium gallium arsenide detector costs:NIR-capable detector materials face price volatility tied to rare earth supply constraints, compressing margins on mid-tier handheld units.
- REACH substance restrictions:ECHA constraints on mercury-cadmium-telluride compounds force redesign cycles among infrared detector suppliers, extending qualification timelines.
- Benchtop laboratory systems:Centralized laboratory spectrometers retain cost-per-test advantages for high-throughput pharmaceutical release testing, limiting handheld penetration in large-batch manufacturing.
Strategic Opportunities
- Environmental field monitoring:Agilent's wireless connectivity integration demonstrates demand for cloud-linked units among EPA-contracted soil and water assessment teams operating outside laboratory infrastructure.
- EU MDR traceability mandates:Medical device manufacturers must implement portable verification tools for polymer and additive identification, opening fleet deployment contracts with sterilization service providers.
- AI-driven spectral interpretation:Machine learning algorithms embedded at the edge are enabling technician-grade users to perform complex mixture analysis previously requiring PhD-level chemometric expertise.
Industry Challenges
- Chemometric model validation:Pharmaceutical manufacturers struggle to transfer laboratory-developed calibration models to handheld platforms while maintaining FDA-compliant accuracy thresholds across varying ambient conditions.
- Cloud platform fragmentation:Field technicians face incompatible data formats between Thermo Fisher, Bruker, and Agilent cloud ecosystems, complicating multi-vendor fleet standardization at enterprise accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Handheld Spectrometer Market |
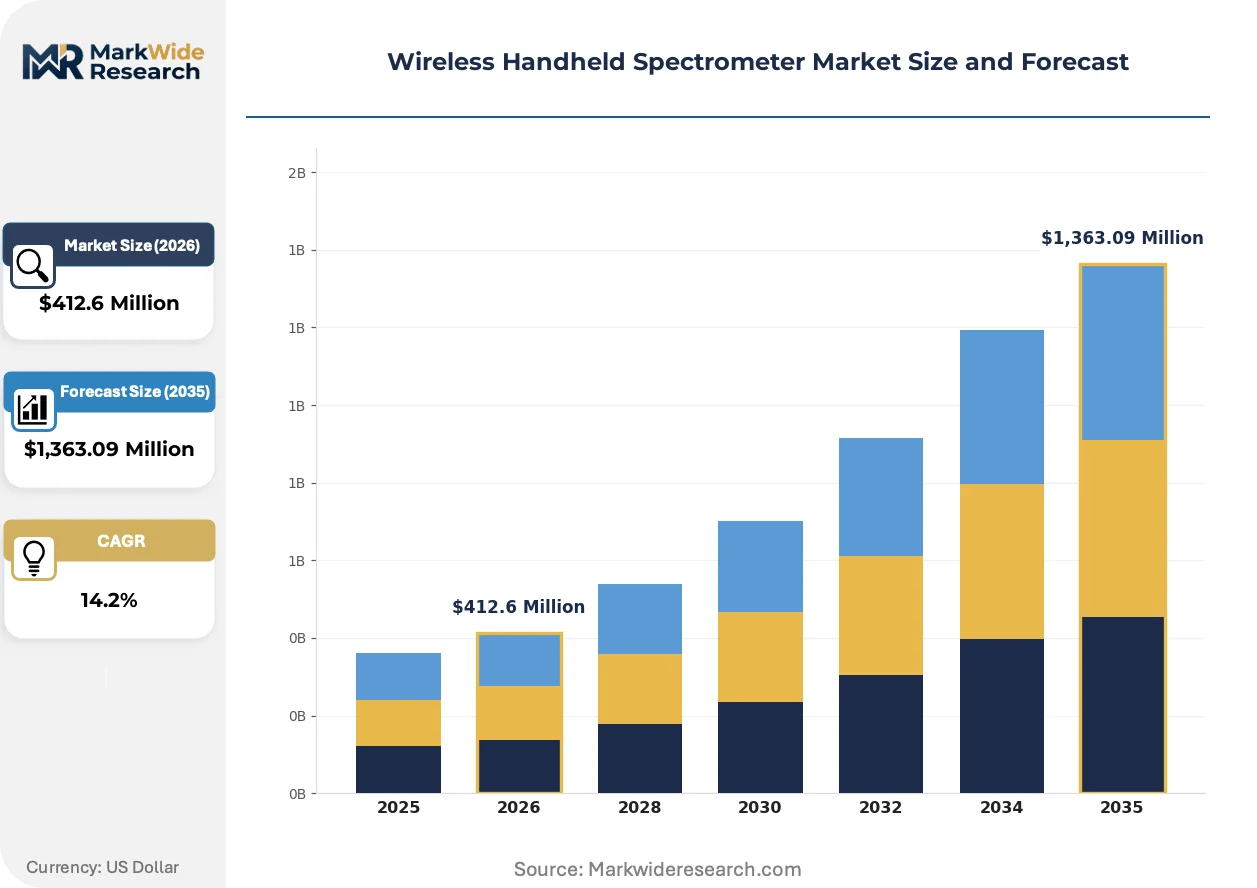
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,363.09 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Near-Infrared, UV-Vis, Raman, Fluorescence Application: Agriculture, Food Safety, Pharmaceuticals, Environmental Monitoring Technology: Optical Fiber, Photonic Crystal, Microprocessor, Wireless Connectivity End User: Research Laboratories, Quality Control, Field Testing, Educational Institutions |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Bruker Corporation, PerkinElmer, Hitachi High-Tech Analytical Science, ABB, Texas Instruments, Oxford Instruments, Renishaw, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Handheld Spectrometer Market Evolving Landscape
Spectral analysis is migrating from centralized laboratories to point-of-need environments, driven by compressed decision timelines and distributed manufacturing footprints. This displacement demands fundamental re-engineering of optical engines, connectivity layers, and data architectures.
Interferometer-on-chip architectures are virtualizing traditional benchtop Fourier-transform infrared capabilities into palm-sized form factors. Pharmaceutical raw material inspectors at receiving docks now deploy these units for immediate polymorph identification without sample transport delays. The technology is virtualizing the boundary between field screening and laboratory-grade quantitative analysis, collapsing the two-tier verification workflow into single-point inspection.
EMA's intensified scrutiny of pharmaceutical supply chain integrity is mandating point-of-receipt testing for excipients and APIs sourced from high-risk jurisdictions. Manufacturers must now document spectral fingerprints at the dock before releasing materials to production floors. Contract manufacturing organizations across Ireland and the Netherlands are responding by standardizing on validated handheld units with embedded compliance reporting modules.
Pharmaceutical procurement teams are unbundling hardware acquisition from chemometric service contracts, treating spectral library development as a recurring subscription rather than capital expenditure. Device vendors face pressure to demonstrate model update velocity and cloud uptime guarantees alongside optical specifications. This behavior shift is most pronounced among mid-sized generic manufacturers in India and Eastern Europe seeking to avoid dedicated spectroscopy staffing costs.
Wireless Handheld Spectrometer Market Segmentation
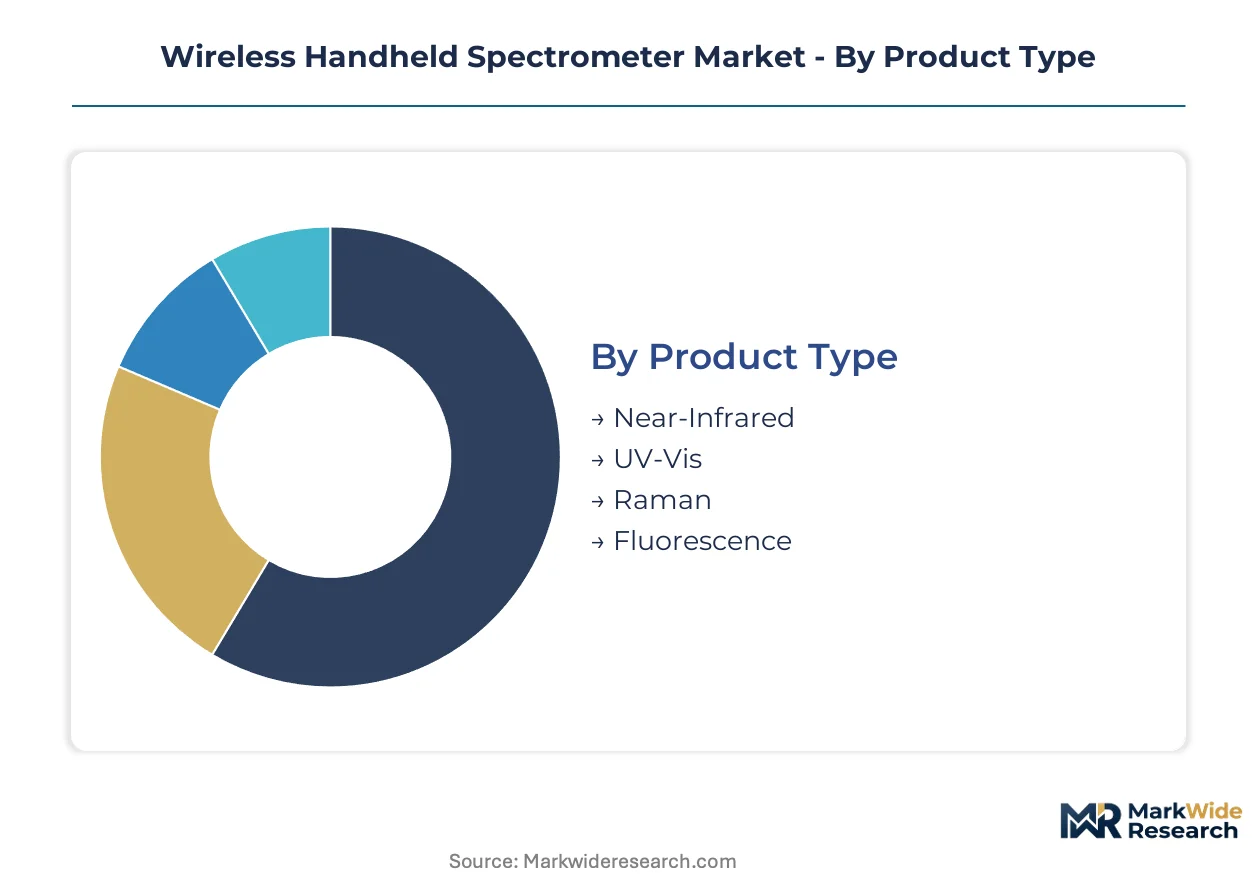
Wireless handheld spectrometers fragment across four distinct dimensions that reshape procurement patterns and vendor positioning. Product type determines optical engine complexity and price positioning. Application verticals impose divergent regulatory compliance burdens. Technology layers separate connectivity-enabled premium units from basic field tools. End-user categories dictate calibration support requirements and fleet deployment economics.
Product Type:
Cost tier stratification across optical engine architectures separates premium fingerprint-level identification from volume screening applications.
- Near-Infrared:Solid-state detector arrays operating across 780-2500 nm penetrate intact packaging for bulk constituent analysis. Food safety inspectors at grain elevators deploy NIR units for protein and moisture quantification without sample destruction. Indium gallium arsenide detector costs constrain margin expansion at mid-tier price points.
- Raman:Laser-excited vibrational spectroscopy delivers molecular fingerprint specificity with minimal preparation. Pharmaceutical quality control teams at receiving docks authenticate active pharmaceutical ingredients through polymorph-sensitive scattering signatures. FDA 21 CFR Part 11 compliance requirements elevate validated Raman units above commodity pricing tiers.
- UV-Vis:Silicon photodiode arrays cover 200-800 nm for chromophore quantification in liquid matrices. Agricultural cooperatives in the Netherlands utilize UV-Vis handhelds for nutrient runoff assessment in drainage canal monitoring programs.
- Fluorescence:Pulsed excitation sources with time-gated detection enable trace-level analyte detection in complex backgrounds. Environmental field teams employ fluorescence units for petroleum hydrocarbon fingerprinting in soil remediation verification.
Raman holds installed capacity. Near-Infrared is rotating up the share rankings.
Application:
Customer type concentration varies sharply across verticals, with pharmaceutical procurement consolidating through validated fleet contracts while agriculture fragments across independent testing cooperatives.
- Pharmaceuticals:Raw material verification at receiving docks demands tamper-evident data logging and audit-ready spectral libraries. EMA supply chain integrity mandates compress decision timelines, eliminating laboratory transport delays for excipient authentication. Generic manufacturers in India unbundle hardware from chemometric subscriptions to avoid dedicated spectroscopy staffing.
- Environmental Monitoring:EPA-contracted soil and water assessment teams operate outside laboratory infrastructure, requiring cloud-linked units with GPS-tagged sampling coordinates. Agilent's wireless connectivity integration demonstrates demand for field-deployable platforms with real-time database synchronization.
- Food Safety:Rapid contaminant screening at processing facilities drives adoption of multi-modal units combining NIR bulk analysis with targeted Raman confirmation for adulterant detection.
- Agriculture:On-farm nutrient management and crop quality assessment at harvest points utilize simplified UV-Vis and NIR units with grower-friendly interpretation interfaces.
Pharmaceuticals concentrates procurement volume. Environmental Monitoring is gaining share fastest through federal contracting expansion.
Technology:
Supply concentration in German precision optics manufacturing corridors around Munich and Berlin shapes component availability for compact diffraction gratings and solid-state detectors.
- Wireless Connectivity:Bluetooth and Wi-Fi modules enable cloud-linked spectral databases with real-time model updates. OEMs race between proprietary platforms and open interoperability standards, redrawing competitive boundaries around data ownership rather than hardware performance alone.
- Microprocessor:Embedded edge computing architectures support AI-driven spectral interpretation, enabling technician-grade users to perform complex mixture analysis previously requiring PhD-level chemometric expertise.
- Optical Fiber:Flexible light delivery permits remote sampling probe configurations for hazardous or confined-space measurements in industrial safety applications.
- Photonic Crystal:Nanostructured resonant cavities miniaturize wavelength selection functions, supporting interferometer-on-chip architectures that virtualize traditional benchtop Fourier-transform capabilities into palm-sized form factors.
Microprocessor holds installed capacity. Wireless Connectivity is rotating up the share rankings.
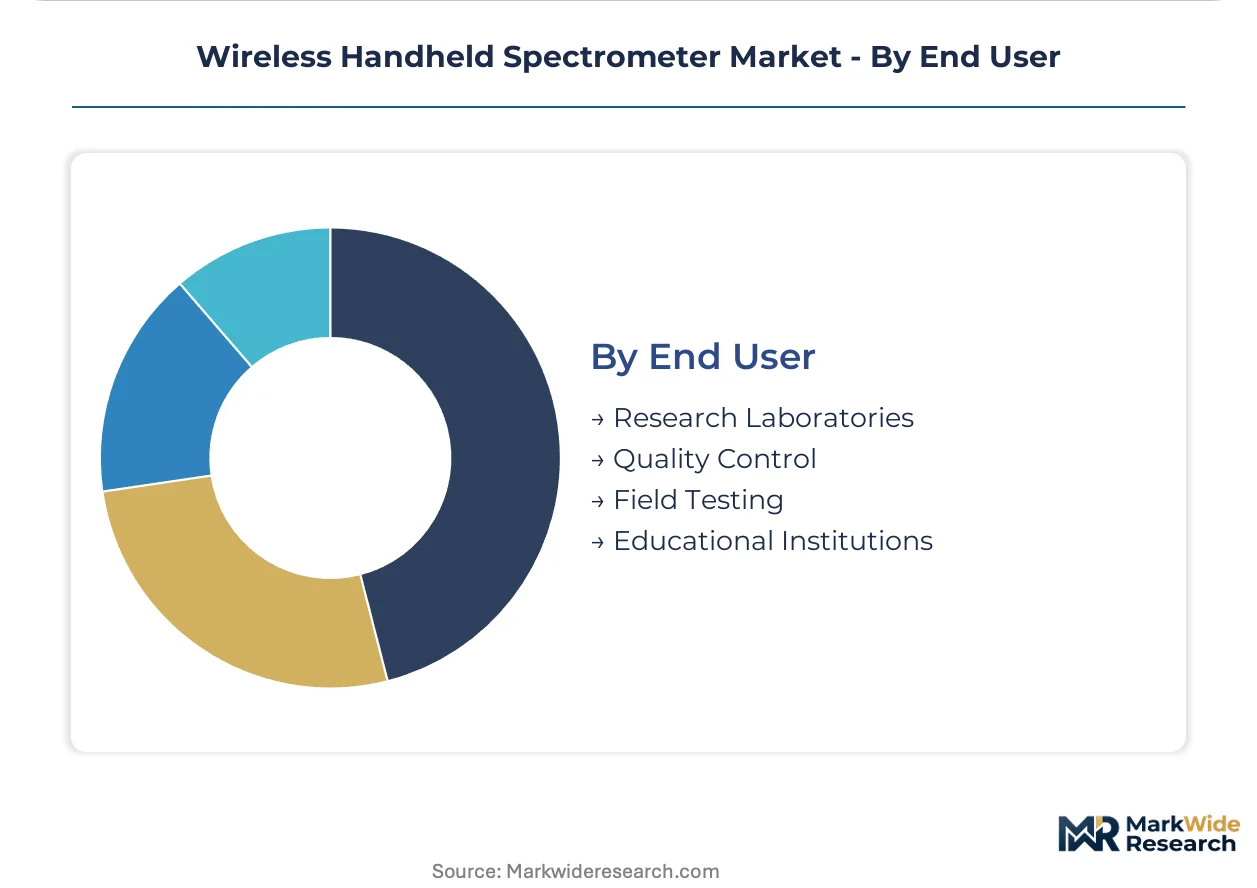
End User:
Margin structure varies across customer sophistication tiers, with research laboratories accepting premium pricing for configurability while field testing demands ruggedized units at compressed price points.
- Quality Control:Pharmaceutical manufacturing floors require validated units with embedded compliance reporting modules for immediate release decisions. Contract manufacturing organizations across Ireland and the Netherlands standardize on fleet deployments with centralized model management.
- Field Testing:Distributed environmental and agricultural assessment teams prioritize battery endurance, ingress protection, and simplified operation over analytical flexibility. Cloud platform fragmentation between vendor ecosystems complicates multi-unit enterprise standardization.
- Research Laboratories:Academic and industrial R&D groups demand configurable optical benches with interchangeable excitation sources and detector modules for method development.
- Educational Institutions:Undergraduate chemistry programs utilize entry-level units for spectroscopy curriculum delivery, with procurement concentrated through multi-year academic licensing agreements.
Quality Control holds installed capacity. Field Testing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturing corridors around Munich and Berlin anchor component supply for compact diffraction gratings and solid-state detectors. Device assemblers source critical subsystems from this concentrated industrial belt before final integration.
United States
Pharmaceutical quality control teams at receiving docks deploy validated handheld units for raw material verification. FDA 21 CFR Part 11 compliance mandates tamper-evident data logging for audit-ready spectral libraries. Boston's life sciences corridor concentrates demand from contract manufacturing organizations standardizing on fleet deployments.
Germany
Precision instrumentation clusters supply compact optical engines at scale to device manufacturers worldwide. EMA supply chain integrity mandates accelerate point-of-receipt testing for excipients sourced from high-risk jurisdictions. Munich-Berlin manufacturing corridors reduce component lead times through concentrated diffraction grating production.
China
Domestic pharmaceutical manufacturers expand portable verification capabilities for generic active ingredient authentication. NMPA intensifies manufacturing oversight requirements for in-situ analytical tools at production facilities. Yangtze River Delta industrial zones concentrate final assembly operations for export-oriented device OEMs.
India
Generic pharmaceutical manufacturers unbundle hardware acquisition from chemometric service subscriptions to avoid dedicated spectroscopy staffing. CDSCO tightens raw material verification requirements for export-oriented production facilities. Gujarat and Maharashtra pharmaceutical clusters drive fleet deployment contracts for validated handheld units.
Japan
Environmental monitoring agencies contract cloud-linked field units for soil and water assessment outside laboratory infrastructure. METI promotes distributed analytical capabilities for industrial safety applications. Kanto region precision electronics manufacturers supply microprocessor and detector modules to regional device integrators.
Wireless Handheld Spectrometer Market Competitive Landscape
Life sciences conglomerates and specialized analytical instrument firms split the market between channel dominance and technical differentiation. The vendor base concentrates around three strategic archetypes: diversified conglomerates leveraging distribution scale, focused spectroscopy specialists commanding premium positioning, and semiconductor-originated entrants integrating component supply. Competitive moves center on chemometric service unbundling and cloud platform ecosystem construction.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies exemplify channel-anchored positioning through life sciences and environmental monitoring verticals respectively. Bruker Corporation occupies the specialized spectroscopy archetype with European-focused Raman and NIR platform development. These three entities represent distinct strategic vectors: pharmaceutical end-user penetration, wireless connectivity integration, and fingerprint-level analytical specificity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bruker Corporation |
| PerkinElmer |
| Hitachi High-Tech Analytical Science |
| ABB |
| Texas Instruments |
| Oxford Instruments |
| Renishaw |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container rates directly compress margins on German-sourced optical subsystems, amplifying cost differentials between Munich-Berlin precision clusters and Asian assembly alternatives while forcing buyers into certification-grade price tiers.
Pricing Analysis
FDA 21 CFR Part 11 dictates the pricing tier structure across pharmaceutical end-user segments. Three-tier pricing structure across premium, standard, and economy levels separates validated Raman units with audit-ready data logging from basic field-screening tools. Cost compression in mid-tier NIR segments stems from indium gallium arsenide detector price volatility. Generic manufacturers in India exhibit highest price sensitivity through unbundled hardware-chemometric subscription preferences, while quality control teams at contract manufacturing organizations accept premium positioning for compliance-embedded fleets.
Supply Chain Analysis
Export controls on indium phosphide substrates and advanced lithography equipment constrain detector material flows from designated technology jurisdictions. Component supply draws from Germany's precision optics corridor, Japan's microprocessor and detector module manufacturers, and China's Yangtze River Delta final assembly zones. Indium gallium arsenide wafers, compact diffraction gratings, and solid-state laser diodes anchor bill-of-materials exposure. Single-source vulnerability concentrates in Munich-Berlin diffraction grating production. Distribution runs through life sciences channel partners for pharmaceutical placements and direct federal contracting for environmental monitoring deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat environment where FDA and EMA validation requirements create switching costs that entrench incumbent positions against hardware commoditization.
For Market Incumbents: Insulate validated product lines through captive control over cloud platform ecosystems, preventing chemometric model portability that would erode recurring subscription revenue. Deepen backward integration into indium gallium arsenide detector supply through long-term offtake agreements with Japanese substrate manufacturers. Prioritize certification investment for EU MDR traceability modules ahead of competitor qualification timelines.
For New Entrants and Emerging Players: Build out AI-driven spectral interpretation capabilities targeting technician-grade users in environmental field testing segments, where cloud platform fragmentation creates white-space for interoperability-focused offerings. Agricultural cooperatives in the Netherlands and EPA-contracted soil assessment teams represent most penetrable demand clusters. Pursue direct-to-end-user digital channels bypassing established life sciences distribution.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized analytical instrument divisions lacking dedicated spectroscopy service infrastructure. Long-term viability hinges on recurring chemometric subscription attach rates rather than hardware shipment volumes. Watch for inflection when pharmaceutical procurement teams consolidate multi-vendor fleets onto single cloud platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Ecosystem Construction | Proprietary spectral database access locks pharmaceutical quality control teams into recurring chemometric subscriptions. |
| Interferometer-on-Chip Manufacturing Scale-Up | Palm-sized form factors collapse laboratory-field verification boundaries for raw material inspectors. |
| AI-Driven Spectral Interpretation Development | Edge-embedded algorithms displace PhD-level chemometric expertise for technician-grade mixture analysis. |
| EU MDR Traceability Module Certification | Embedded compliance reporting opens fleet deployment contracts with Ireland-Netherlands sterilization providers. |
| Indium Gallium Arsenide Supply Agreement | Long-term detector material offtake insulates margins against rare earth price volatility. |
Research Methodology
A standing panel of pharmaceutical quality control directors, environmental field assessment team leaders, biomedical equipment procurement managers, and precision optics manufacturing executives provided ongoing calibration against market dynamics. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EMA regulatory submission databases, EPA contract award records, and customs trade data for optical component flows. Bottom-up unit deployment estimates triangulated against top-down analytical instrument market sizing.
Scenario-bracketing framed projections across the analysis window, modeling technology adoption curves and regulatory enforcement intensity variations. Segmentation dimensions spanned product type, application vertical, connectivity technology layer, and end-user sophistication tier. CAGRs derived from installed base replacement cycles and fleet expansion patterns at contract manufacturing organizations. Forecast inputs incorporated cloud platform subscription attach rate trajectories and REACH substance restriction implementation timelines.
Stress conditions across indium gallium arsenide price volatility, FDA audit enforcement intensity, and cloud platform interoperability standards were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory mandate adoption curves and pharmaceutical supply chain verification standardization. Material shifts in EMA supply chain integrity enforcement scope or export control designation changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
High Purity Gas Flow Meter Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Contact Angle Measuring Instrument Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
North America Analytical Instrumentation Market