
 Latin America Cybersecurity Market | 2026-2036
Latin America Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Cybersecurity Market Outlook
ISO 27001 certification cycles are redrawing competitive access across the Latin America Cybersecurity Market. Palo Alto Networks leverages its cloud-native platform architecture to anchor enterprise accounts in Mexico and Colombia. Softtek sustains regional delivery capabilities through nearshore security operations centers. Check Point Software differentiates via unified threat management appliances tailored to mid-market banking infrastructure.
Latin America cybersecurity encompasses technologies, services, and practices protecting digital assets from unauthorized access, disruption, or extraction across network, endpoint, and cloud layers. Solutions integrate encryption protocols, behavioral analytics engines, and zero-trust access architectures to defend transactional systems, operational technology networks, and citizen data repositories. Cloud security and managed security services represent the fastest-expanding margin pools as Latin American enterprises migrate workloads to distributed environments and outsource threat monitoring. Network security retains dominant spend share among regulated sectors, particularly BFSI and government end users with legacy perimeter-dependent architectures. Endpoint security growth accelerates through remote workforce expansion and mobile banking proliferation across the region.
Brazil's LGPD enforcement through its national data protection authority shapes product compliance requirements for foreign vendors seeking market entry. Mexico's fintech law and central bank cybersecurity provisions mandate incident reporting standards that drive managed security services procurement. ANPD, CNBV, and Colombia's Superintendencia de Industria y Comercio collectively tighten the regulatory perimeter around personal data handling and critical infrastructure protection. Stakeholders must monitor evolving cross-border data localization requirements and certification reciprocity agreements that will determine vendor eligibility and service delivery models.
Market Dynamics
Cloud migration across Latin American financial services is compressing procurement cycles and forcing vendors to rearchitect delivery models around distributed infrastructure.
Growth Catalysts
- LGPD Enforcement:Brazil's data protection authority mandates breach notification timelines, compelling enterprises to upgrade incident response capabilities and managed detection services.
- Fintech Licensing:Mexico's central bank cybersecurity provisions require licensed institutions to maintain 24/7 security operations, driving continuous monitoring procurement.
- Remote Workforce Expansion:Endpoint protection demand accelerates as distributed banking and insurance workforces require zero-trust access architectures.
Market Restraints
- Specialized Talent Scarcity:Certified security architects command premiums exceeding 40% above general IT salaries in São Paulo and Mexico City markets.
- Import Dependency:Hardware security modules and advanced firewall appliances concentrate sourcing from Asian manufacturing clusters, exposing buyers to extended lead times.
- Legacy Integration Friction:Core banking systems running on decades-old COBOL infrastructure resist API-based security overlay deployment without substantial reengineering.
Strategic Opportunities
- Colombia's Regulatory Momentum:Superintendencia de Industria y Comercio data protection rulings create compliance-driven demand for privacy-enhancing technologies in Bogotá's services sector.
- OT-IT Convergence:Energy and mining operators in Chile and Peru require unified threat management spanning operational technology networks and enterprise IT.
- Channel Partner Ecosystems:Value-added distributors in Argentina and Uruguay enable foreign vendors to bypass direct sales infrastructure investments.
Industry Challenges
- ISO 27001 Certification Bottlenecks:Accredited auditors face 6-9 month backlogs, delaying market entry for SaaS providers seeking enterprise contracts.
- Cross-Border Data Localization:Conflicting requirements between Brazilian LGPD, Mexican fintech law, and Colombian commerce regulations fragment cloud architecture strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Cybersecurity Market |
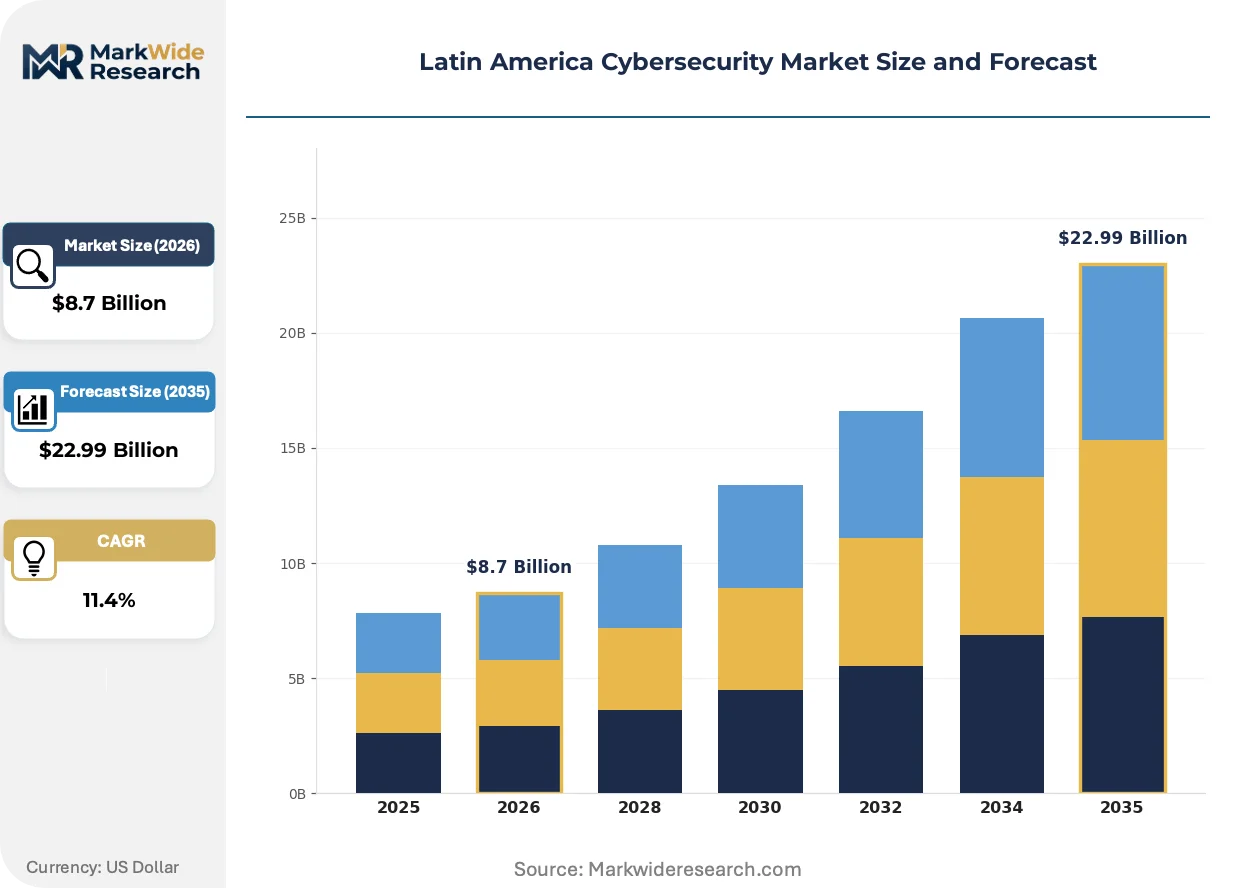
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endpoint Security, Network Security, Cloud Security, Application Security Deployment Model: On-premises, Cloud-based, Hybrid, Managed Services End User: Government, Healthcare, BFSI, Retail Service Type: Consulting, Support & Maintenance, Managed Security Services, Risk Assessment |
| Companies Covered | Palo Alto Networks, Trend Micro, IBM, Softtek, Broadcom, Cisco Systems, Check Point Software, Módulo, Fortinet, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Cybersecurity Market Strategic Shifts
Security delivery models across Latin America are pivoting from perimeter defense to identity-centric architectures, with artificial intelligence reshaping threat detection economics.
Extended detection and response platforms aggregate telemetry across endpoints, networks, and cloud workloads into unified analyst consoles. Mid-market banks in Mexico and Chile are adopting these consolidated tools faster than large institutions burdened by vendor consolidation complexity. Native XDR is supplanting standalone SIEM deployments by embedding automated correlation engines that reduce mean-time-to-detect without proportional staffing increases.
Brazil's ANPD has issued binding guidance on international data transfers following EU adequacy negotiations, forcing multinationals to implement supplementary measures for EU-Brazil data flows. Financial services and healthcare verticals face the steepest compliance burdens under these cross-border restrictions. Enterprises are responding by negotiating regional cloud residency clauses with hyperscale providers and establishing São Paulo-based data processing enclaves.
Managed security services procurement now favors consumption-based pricing tied to monitored asset volumes rather than fixed-fee retainers. Brazilian insurers and Colombian telecommunications operators lead this shift, replacing three-year outsourcing contracts with month-to-month elasticity. Chilean mining conglomerates demonstrate the most aggressive adoption, treating security operations as variable operational expenditure aligned to production facility activation cycles.
Latin America Cybersecurity Market Segmentation
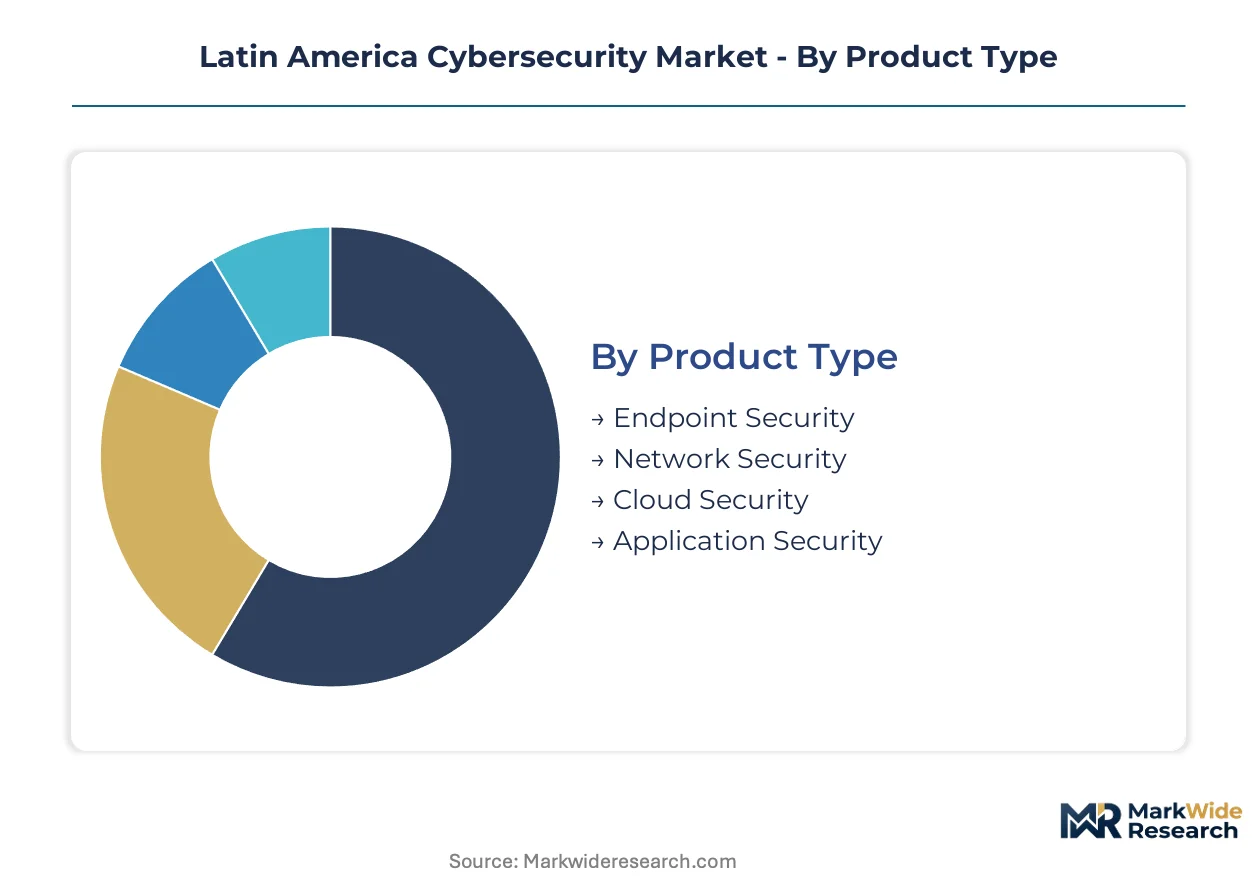
Segmentation across the Latin America Cybersecurity Market reveals how regulatory pressure and infrastructure maturity reshape procurement priorities. Buyers in São Paulo and Mexico City financial districts select solutions based on compliance mandates, cloud migration status, and legacy system constraints rather than feature sets alone.
Product Type:
Cloud Security faces the most acute substitution pressure as XDR platforms absorb standalone cloud workload protection functions into unified consoles.
- Network Security:Perimeter defense appliances and next-generation firewalls dominate spend among Brazilian banks and Mexican government agencies maintaining legacy hub-and-spoke architectures. Demand concentrates in regulated BFSI verticals where COBOL-era core systems resist cloud-native overlay deployment without substantial middleware investment.
- Cloud Security:Workload protection platforms, cloud access security brokers, and container security tools defend distributed infrastructure across AWS, Azure, and regional providers like Oi and Claro cloud. São Paulo financial districts and Mexico City fintech clusters drive procurement as LGPD and CNBV mandates force data residency compliance.
- Endpoint Security:EDR agents and mobile threat defense protect remote banking workforces and insurance claims processors across Brazil's expanded home-office arrangements.
- Application Security:SAST/DAST tools and API security gateways secure digital banking channels and open finance interfaces proliferating under Mexico's fintech licensing regime.
Network Security anchors the volume base while Cloud Security gains share at the steepest rate.
Deployment Model:
Cost tier stratification separates enterprise buyers with capital budgets from mid-market adopters seeking operational expenditure flexibility.
- Managed Services:24/7 security operations delivered from nearshore centers in Monterrey and Campinas replace in-house SOC investments for resource-constrained institutions. Colombian telecommunications operators and Brazilian insurers favor consumption-based pricing tied to monitored asset volumes rather than fixed retainers.
- Cloud-based:SaaS-delivered security controls enable rapid deployment without data center expansion, appealing to Mexican fintech startups facing CNBV cybersecurity provisioning deadlines.
- Hybrid:Split architectures maintain sensitive data on-premises while bursting analytics workloads to regional cloud regions, common among Chilean mining conglomerates with OT-IT convergence requirements.
- On-premises:Appliance-based deployment persists where data sovereignty concerns or latency requirements preclude off-premise processing, notably in Argentine government and defense sectors.
On-premises deployment retains the largest installed base though Managed Services expands most quickly as talent scarcity drives outsourcing decisions.
End User:
Application context determines solution architecture more than organizational size, with transaction volume and regulatory exposure shaping procurement specifications.
- BFSI:Banks, insurers, and payment processors deploy the most comprehensive security stacks spanning fraud detection, encryption key management, and zero-trust access. Brazil's LGPD enforcement and Mexico's fintech law impose breach notification timelines that compel continuous monitoring investment across Itaú, BBVA México, and Nubank infrastructure.
- Government:Federal and state agencies across Brazil, Mexico, and Colombia prioritize network segmentation and citizen data protection amid election security concerns and public service digitization.
- Healthcare:Hospitals and health insurers in São Paulo and Mexico City implement medical device security and patient record encryption as ANPD and national health regulators tighten data handling standards.
- Retail:E-commerce platforms and point-of-sale networks adopt payment card industry compliance tools and bot mitigation as digital transaction volumes accelerate across Mercado Libre and regional marketplace ecosystems.
BFSI commands the deepest security investment per organization while Retail climbs fastest as marketplace fraud drives merchant protection procurement.
Service Type:
Margin concentration favors recurring revenue streams over project-based engagements, with vendor business models pivoting toward annuity relationships.
- Managed Security Services:Continuous threat monitoring, incident response retainers, and vulnerability management delivered from regional SOCs generate predictable revenue. Chilean mining operators treat security operations as variable opex aligned to production facility activation cycles.
- Consulting:Advisory engagements for security architecture design, LGPD compliance roadmapping, and zero-trust transformation support enterprise digital migration programs.
- Support & Maintenance:Hardware and software maintenance contracts sustain legacy firewall and SIEM installations across government and utility infrastructure with extended replacement cycles.
- Risk Assessment:Penetration testing, red team exercises, and compliance audit preparation address CNBV, ANPD, and Superintendencia de Industria y Comercio examination requirements.
Support & Maintenance represents the largest revenue pool by volume while Managed Security Services shows the steepest expansion trajectory as outsourcing preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANPD enforcement actions and CNBV licensing mandates are redrawing procurement priorities across Latin American cybersecurity markets. Brazil's data protection authority levied fines exceeding regulatory thresholds against financial institutions in 2024, accelerating compliance investment. Mexico's central bank provisions now require licensed fintechs to maintain 24/7 security operations, creating immediate service demand.
Brazil
LGPD breach notification timelines compel Itaú and Nubank to upgrade incident response capabilities. ANPD's binding guidance on international data transfers forces multinationals to implement supplementary measures for EU-Brazil flows. São Paulo financial districts concentrate cloud security procurement as enterprises negotiate regional residency clauses with hyperscale providers.
Mexico
Fintech licensing requirements tighten data protection mandates for digital banks and payment processors. CNBV cybersecurity provisions mandate 24/7 security operations, driving continuous monitoring procurement from licensed institutions. Mexico City fintech clusters adopt SaaS-delivered security controls to meet provisioning deadlines without data center expansion.
Colombia
Superintendencia de Industria y Comercio data protection rulings create compliance-driven demand for privacy-enhancing technologies. Bogotá's services sector implements encryption protocols and behavioral analytics engines to defend transactional systems. Regional delivery capabilities expand through nearshore security operations centers serving Andean markets.
Chile
OT-IT convergence requirements in energy and mining drive unified threat management spanning operational technology networks. Mining conglomerates treat security operations as variable operational expenditure aligned to production facility activation cycles. Santiago-based enterprises adopt hybrid architectures maintaining sensitive data on-premises while bursting analytics workloads to regional cloud regions.
Argentina
Value-added distributors enable foreign vendors to bypass direct sales infrastructure investments through channel partner ecosystems. Buenos Aires technology corridors concentrate application security procurement for digital banking channels. Government and defense sectors maintain on-premises appliance deployment where data sovereignty concerns preclude off-premise processing.
Latin America Cybersecurity Market Competitive Environment
Listed leaders compete with private specialists across delivery model architectures in Latin American cybersecurity markets. Consolidation pressures intensify as cloud-native platforms absorb standalone workload protection functions into unified consoles. Three archetypes dominate: global platform vendors with regional cloud instances, nearshore managed security providers with local language capabilities, and specialized compliance consultancies navigating ANPD and CNBV requirements. Dominant competitive moves include strategic partnerships with value-added distributors and portfolio diversification into XDR and zero-trust architectures.
Within the global platform tier, Palo Alto Networks and Check Point Software occupy positions anchoring enterprise accounts across Mexico and Colombia. Softtek exemplifies the nearshore delivery archetype, sustaining regional security operations centers that serve financial institutions requiring Portuguese and Spanish language support. Trend Micro represents specialists in endpoint protection, addressing remote workforce expansion across Brazilian banking and insurance sectors.
| Leading Market Players |
|---|
| Palo Alto Networks |
| Trend Micro |
| IBM |
| Softtek |
| Broadcom |
| Cisco Systems |
| Check Point Software |
| Módulo |
| Fortinet |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for hardware security modules from Asian manufacturing clusters concentrate pricing power among distributors holding regional inventory buffers, while SaaS-native vendors bypass physical supply constraints entirely. This bifurcation splits procurement economics between appliance-dependent Brazilian banks and cloud-first Mexican fintechs.
Pricing Analysis
Certification level creates the primary spread between ISO 27001-audited managed security services and uncertified alternatives. Consumption-based pricing tied to monitored asset volumes displaces fixed-fee retainers as Brazilian insurers and Colombian telecom operators seek operational expenditure flexibility. Cost compression in mid-market endpoint protection intensifies as XDR platforms absorb standalone EDR functions. Large financial institutions show least price sensitivity due to regulatory non-compliance penalties, while Argentine SMEs face acute budget constraints.
Supply Chain Analysis
Ninety-day hardware security module lead times from Taiwan and South Korea expose Brazilian buyers to inventory risk during demand surges. Semiconductor components for next-generation firewalls and encryption appliances feed from East Asian foundries, while cloud security software distribution runs through hyperscaler regional instances in São Paulo and Mexico City. Single-source vulnerability concentrates in advanced threat intelligence feeds anchored to US and Israeli research clusters. Value-added distributors in Buenos Aires and Monterrey bridge foreign vendors to mid-market accounts without direct sales infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security services attach rates expand faster than hardware procurement as Latin American enterprises outsource 24/7 security operations to nearshore providers. This service-layer acceleration restructures vendor economics toward recurring revenue streams.
For Market Incumbents: Consolidate regional delivery capabilities through Monterrey and Campinas security operations center expansion to defend against pure-play XDR entrants. Deepen ISO 27001 certification reciprocity investments to accelerate enterprise sales cycles amid auditor backlogs. Channel control through exclusive value-added distributor agreements in Argentina and Uruguay preserves pricing power against direct-sales challengers.
For New Entrants and Emerging Players: ANPD fast-track compliance pathways open white-space access among Brazilian mid-market banks facing LGPD enforcement deadlines. Colombia's Superintendencia de Industria y Comercio rulings create privacy-enhancing technology demand in Bogotá's underpenetrated services sector. SaaS-delivered consumption models bypass incumbent appliance lock-in without data center expansion requirements.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate IT services divisions with captive cybersecurity practices lacking standalone scale. Nearshore managed security providers with Portuguese-Spanish bilingual delivery capabilities offer five-to-ten-year viability as regional outsourcing preferences harden. Monitor ANPD fine issuance velocity as inflection indicator for compliance-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | XDR consolidation absorbs standalone cloud workload protection into unified analyst consoles for Mexican mid-market banks. |
| Geographic Expansion | Campinas and Monterrey security operations centers capture Brazilian and Mexican managed services demand with local language support. |
| Strategic Partnership | Value-added distributor alliances in Argentina and Uruguay bypass direct sales infrastructure investments for foreign vendors. |
| Acquisition of Specialist Firm | ISO 27001 consultancy practices accelerate certification timelines for SaaS providers facing enterprise procurement gates. |
| Product Launch | Zero-trust access architectures address remote workforce expansion across Brazilian banking and insurance sectors. |
Study Parameters
Cross-validation between primary interviews with CISOs at Itaú, BBVA México, and Nubank and secondary validation against ANPD enforcement records, CNBV licensing databases, and hyperscaler regional capex disclosures anchors the qualitative findings. Conversations with value-added distributors in Buenos Aires, Bogotá channel partners, and Softtek delivery executives complement bottom-up and top-down triangulation across the analysis window.
Sensitivity analysis around cloud migration velocity and LGPD enforcement intensity shapes the analytical framework across deployment model, organization size, vertical regulatory exposure, and regional adoption pattern dimensions. CAGRs derive from segment-level bottom-up builds validated against macroeconomic aggregates. Threat intelligence feed pricing trends and certified security architect salary premiums inform cybersecurity-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained regulatory enforcement and cloud migration assumptions; material deviation in ANPD fine velocity or cross-border data localization rulings would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Container-based Firewall Market
Cybersecurity
Cyber Warfare Market
Cybersecurity
Secure Socket Layer (SSL) Certification Market
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
India Network Security and Cyber Risk Management Market
Cybersecurity
Anti-Malware Market
Cybersecurity
Global Mobile Anti Malware Market
Cybersecurity
Middle East Cybersecurity Market
Cybersecurity
Denmark Cybersecurity Market
Cybersecurity
Cloud DLP Market
Cybersecurity
Mobile Encryption Market
Cybersecurity
Open RAN Security Market
Cybersecurity
Digital Forensics Market
Cybersecurity
Africa Cybersecurity Market
Cybersecurity
Virtualization Security Tools Market