
 Canada Ransomware Protection Market | 2026-2036
Canada Ransomware Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Ransomware Protection Market Insights
Managed detection and response subscription tiers is rebalancing how Canadian enterprises procure ransomware defense, shifting capital expenditure into recurring operational contracts. Arctic Wolf leverages its native SOAR platform to anchor mid-market accounts across Ontario and British Columbia. eSentire sustains 24/7 coverage through Canadian-staffed security operations centers. Telus Security competes by bundling ransomware protection with fiber connectivity and cloud infrastructure contracts.
Canada ransomware protection encompasses endpoint agents, network segmentation tools, encrypted backup systems, and threat intelligence feeds engineered to intercept encryption payloads before data exfiltration occurs. The primary commercial purpose centers on preserving operational continuity for organizations facing financially motivated criminal campaigns. Endpoint Protection dominates current procurement volumes as healthcare and finance sectors harden workstations and medical devices against initial access vectors. Cloud Backup represents the fastest-growing solution type as provincial governments mandate immutable recovery architectures for critical infrastructure operators. Managed Services deployment models capture expanding margin pools by transferring incident liability from internal IT staff to specialized Canadian providers.
Health Canada, the Office of the Privacy Commissioner of Canada, and provincial health information protection statutes collectively shape product standards by mandating encryption, access logging, and breach disclosure timelines. The Personal Information Protection and Electronic Documents Act creates baseline civil liability that drives demand for demonstrable prevention capabilities rather than reactive insurance products. Stakeholders must monitor evolving provincial critical infrastructure designation rules that could trigger mandatory ransomware reporting well ahead of federal harmonization.
Market Dynamics
Provincial breach notification mandates from Health Canada and privacy commissioners are compressing procurement cycles, forcing healthcare networks and financial institutions to accelerate security architecture upgrades ahead of federal harmonization.
Growth Catalysts
- Health Canada Enforcement:Mandatory breach disclosure timelines under federal privacy statutes compel healthcare operators to deploy prevention-first architectures rather than reactive insurance products.
- Medical Device Hardening:Hospital networks across Ontario and Quebec are expanding endpoint agent deployments to protect imaging systems and patient monitoring equipment from initial access vectors.
- Immutable Backup Mandates:Provincial critical infrastructure designations for municipal water and energy utilities are accelerating demand for air-gapped recovery systems with cryptographic verification.
Market Restraints
- Specialized Talent Scarcity:Canadian security operations centers face acute shortages of incident responders with ransomware-specific forensics expertise, inflating managed service contract premiums.
- Legacy Infrastructure Debt:Small and mid-sized municipalities in Atlantic Canada operate unsupported Windows Server environments that resist modern endpoint detection and response agent deployment.
- Vendor Concentration Risk:Cloud backup infrastructure for Prairie provinces relies heavily on hyperscale providers with limited Canadian data residency guarantees.
Strategic Opportunities
- Atlantic Canada Expansion:Underpenetrated provincial health authorities in Nova Scotia and New Brunswick present first-mover advantages for managed detection and response providers establishing regional security operations centers.
- Zero Trust Convergence:Integration of network segmentation tools with identity governance platforms creates bundled procurement opportunities for financial services firms modernizing branch infrastructure.
- Critical Infrastructure Reporting:Anticipated federal mandatory ransomware incident reporting legislation will generate compliance-driven demand for automated threat intelligence ingestion and disclosure workflow tools.
Industry Challenges
- Forensics Certification Bottlenecks:Canadian incident response firms struggle to staff 24/7 coverage with personnel holding GIAC or equivalent digital forensics credentials, constraining service expansion.
- Interoperability Friction:Provincial health information exchanges operate fragmented electronic medical record systems that resist standardized security information and event management integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Ransomware Protection Market |
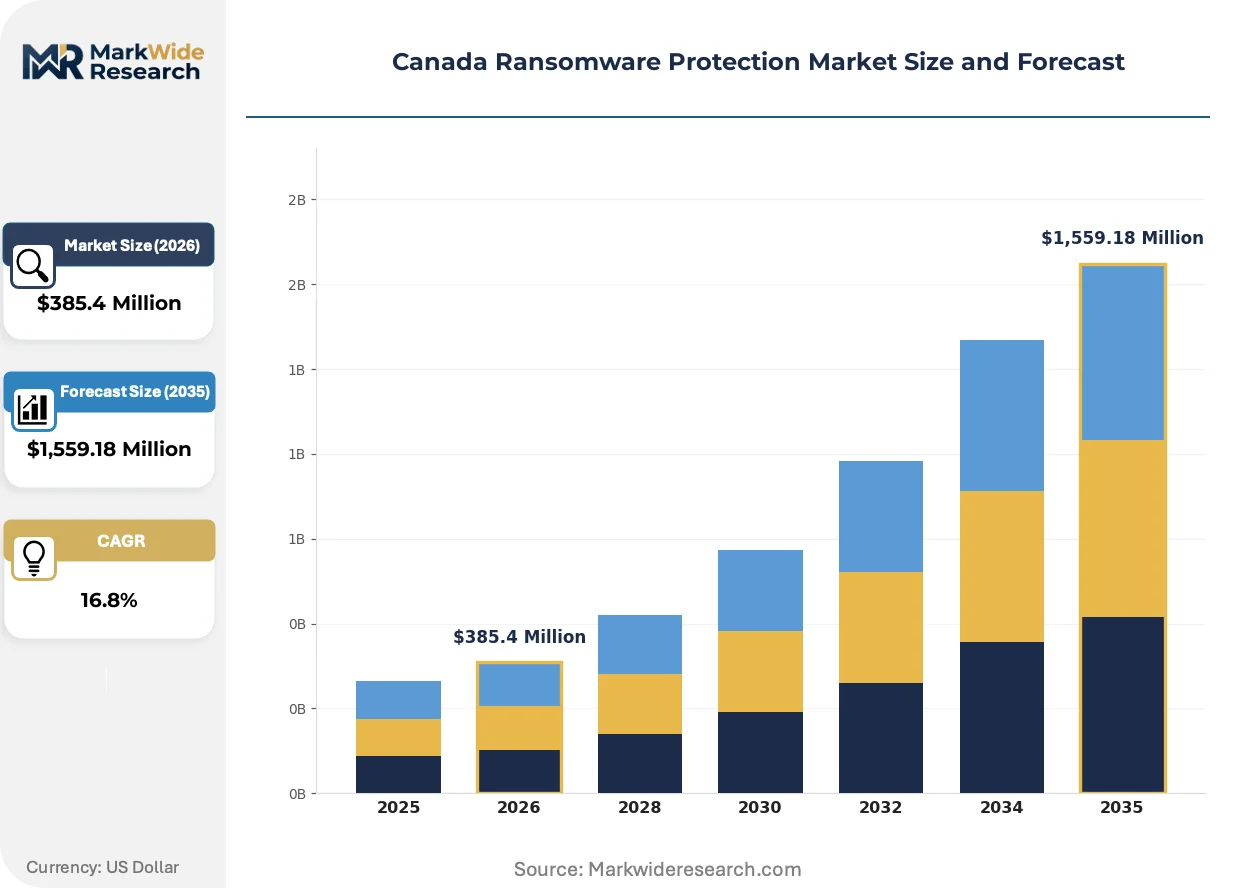
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,559.18 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Endpoint Protection, Network Security, Cloud Backup, Threat Intelligence Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Healthcare, Finance, Education, Government Service Type: Consulting, Incident Response, Training, Support |
| Companies Covered | Herjavec Group, Arctic Wolf, Telus Security, eSentire, GoSecure, Vumetric, Microsoft Canada, McAfee, Bitdefender, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Ransomware Protection Market Trends and Innovations
Canadian ransomware defense is pivoting from signature-based prevention toward continuous behavioral monitoring and automated containment, reshaping how security vendors architect subscription platforms and how buyers evaluate total cost of ownership.
Extended detection and response platforms with native SOAR orchestration are absorbing incident triage workflows previously handled by tier-one security analysts. Mid-market manufacturers in Ontario are adopting these platforms at accelerated rates to compensate for internal staffing gaps. The technology is absorbing lower-complexity alert investigation tasks, compressing headcount requirements for in-house security operations centers.
Health Canada guidance on medical device cybersecurity is tightening pre-market submission requirements for networked diagnostic equipment. Manufacturers must now demonstrate encryption capabilities and vulnerability disclosure programs before provincial procurement approval. Hospital capital committees in Quebec and British Columbia are rewriting vendor evaluation scorecards to prioritize these attestations over legacy price-performance metrics.
Security procurement committees are consolidating vendor relationships around outcome-based service level agreements that transfer breach liability to managed security providers. Financial institutions in Toronto and Montreal are displacing point-product licensing with comprehensive subscription bundles spanning endpoint, network, and cloud workload protection. This consolidation is most visible among tier-two banks seeking to reduce cyber insurance deductibles through demonstrable prevention controls.
Canada Ransomware Protection Market Segmentation
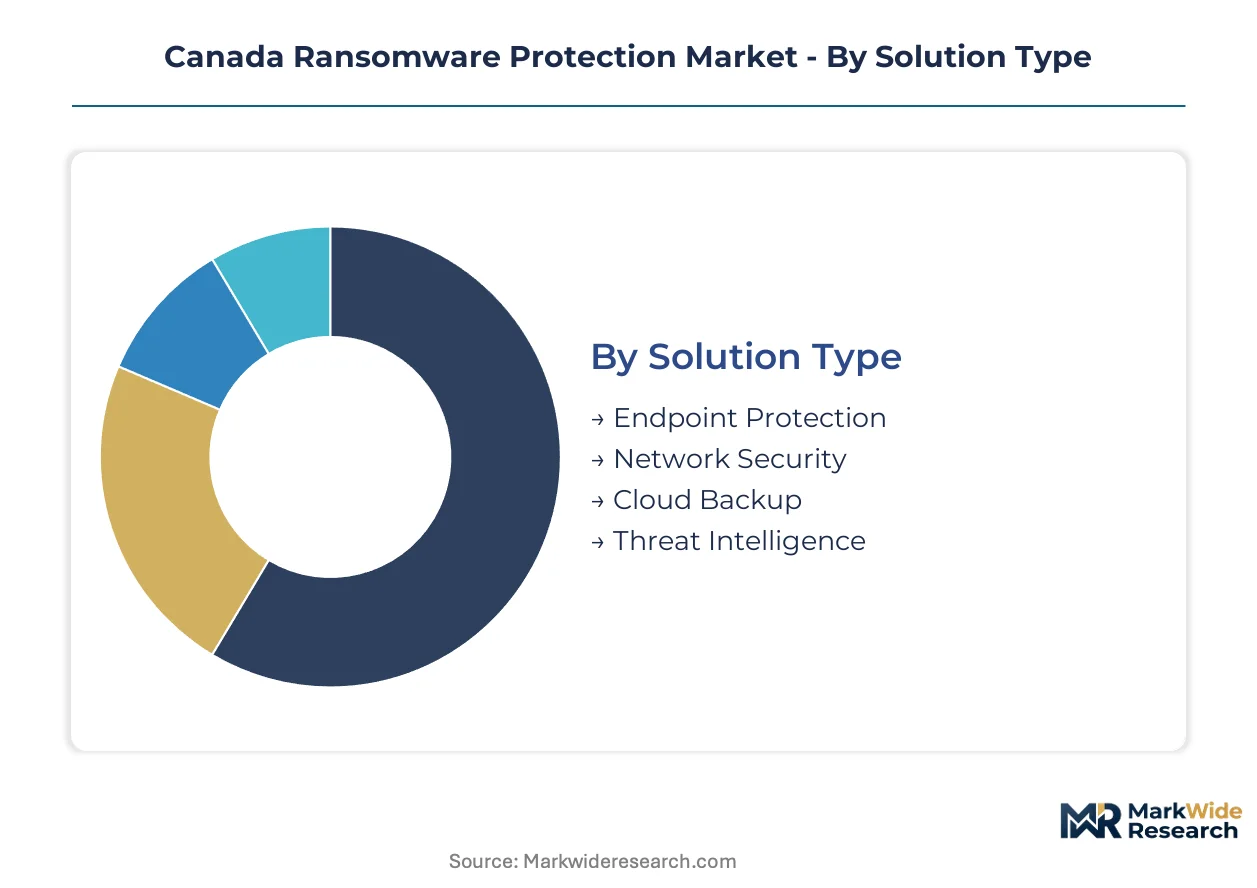
Canadian ransomware protection procurement varies sharply by organizational scale, regulatory exposure, and legacy infrastructure maturity. Buyers select solution architectures based on internal security operations capacity and provincial breach notification obligations.
Solution Type:
Healthcare networks in Ontario and Quebec prioritize prevention technologies that intercept encryption before patient data exfiltration occurs.
- Endpoint Protection:Agent-based monitoring deploys across workstations, medical devices, and imaging systems to block initial access vectors. Hospital procurement committees in Toronto and Montreal dominate current volumes as they harden diagnostic equipment against commodity ransomware strains.
- Cloud Backup:Immutable recovery architectures with cryptographic verification satisfy provincial critical infrastructure mandates for municipal utilities. British Columbia and Alberta energy operators are accelerating adoption of air-gapped storage to meet immutable backup requirements.
- Network Security:Segmentation tools isolate lateral movement paths within flat hospital networks and manufacturing environments.
- Threat Intelligence:Automated feeds ingest indicators of compromise specific to financially motivated criminal campaigns targeting Canadian entities.
Endpoint Protection leads volumes today; Cloud Backup is gaining share fastest.
Deployment Model:
Capital expenditure constraints and specialized talent scarcity push mid-market buyers toward operational expenditure models.
- Managed Services:24/7 security operations center coverage transfers incident liability from internal IT staff to specialized Canadian providers. Atlantic Canada health authorities and Prairie province municipalities favor this model to compensate for forensics certification bottlenecks in local labor markets.
- Cloud-Based:Native SaaS platforms eliminate hardware refresh cycles and accelerate deployment timelines for resource-constrained organizations. Vancouver and Calgary mid-market manufacturers are displacing on-premises appliances with subscription orchestration platforms.
- Hybrid:Split architectures preserve sensitive data processing on-premises while leveraging cloud analytics for threat detection.
- On-Premises:Air-gapped installations persist in defense and classified government environments with data sovereignty requirements.
Managed Services commands premium pricing; Cloud-Based deployment is expanding most quickly among new buyers.
End User:
Sector-specific regulatory deadlines compress procurement cycles unevenly across Canadian industries.
- Healthcare:Provincial privacy commissioners enforce breach notification timelines that compel prevention-first architectures. Hospital networks across Ontario and Quebec maintain the largest IT security budgets as they protect electronic medical record systems and networked diagnostic equipment.
- Finance:Tier-two banks in Toronto and Montreal consolidate vendor relationships around outcome-based service level agreements to reduce cyber insurance deductibles. Demonstrable prevention controls displace point-product licensing in procurement evaluations.
- Government:Federal and provincial agencies face anticipated mandatory ransomware incident reporting legislation.
- Education:Universities and research institutions protect intellectual property and student records with constrained operational budgets.
Healthcare dominates current spending; Government procurement is climbing the fastest ahead of regulatory harmonization.
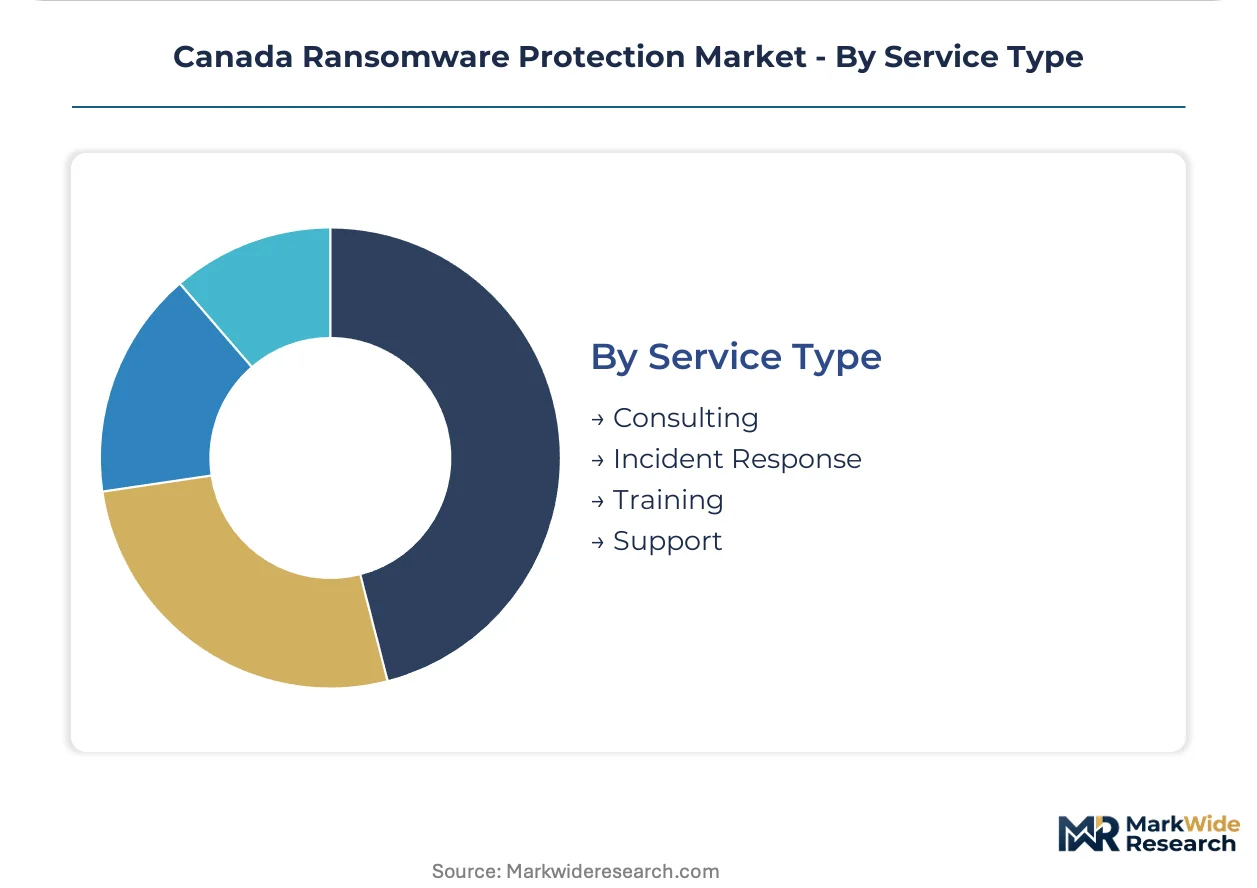
Service Type:
Post-incident capabilities command premium pricing as organizations prioritize response readiness over theoretical prevention.
- Incident Response:Retainer-based forensics and containment services address acute shortages of GIAC-credentialed personnel in Canadian security operations centers. Financial institutions and critical infrastructure operators in Toronto and Vancouver maintain standing agreements to guarantee 24/7 coverage.
- Consulting:Architecture assessments and zero trust roadmaps guide security modernization for legacy infrastructure debt in Atlantic Canada municipalities.
- Training:Phishing simulation and security awareness programs reduce human error vectors in healthcare and education sectors.
- Support:Tiered technical assistance maintains endpoint agent and backup system operability across distributed provincial networks.
Incident Response captures the highest contract values; Consulting revenue is accelerating fastest among mid-market manufacturers modernizing branch infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada outpaces Mexico in ransomware protection spending intensity, while both trail the United States in absolute procurement volumes. Provincial regulatory fragmentation creates uneven security investment patterns across Canadian sub-regions.
Ontario
Toronto's financial services corridor and provincial hospital networks drive concentrated demand for managed detection and response services. Health Canada breach notification mandates compress procurement cycles for healthcare operators protecting electronic medical record systems. The Waterloo-Toronto tech corridor anchors domestic cybersecurity vendor development and talent recruitment.
Quebec
Montreal's banking sector and provincial health authorities prioritize endpoint protection for French-language compliance requirements. Quebec's privacy commissioner enforces stricter breach disclosure timelines than federal baselines, accelerating prevention-first architecture adoption. Quebec City government clusters are expanding cloud backup procurement for critical infrastructure operators.
British Columbia
Vancouver's mid-market manufacturers displace on-premises appliances with cloud-native security platforms to address staffing gaps. Provincial critical infrastructure designations for energy utilities mandate immutable recovery architectures with cryptographic verification. Victoria government agencies pilot zero trust network segmentation for inter-agency data sharing.
Alberta
Calgary energy sector operators invest heavily in air-gapped backup systems following provincial critical infrastructure security directives. Oil and gas headquarters maintain standing incident response retainers to guarantee 24/7 forensics coverage. Edmonton municipal utilities lead Prairie province adoption of managed security services.
Atlantic Canada
Nova Scotia and New Brunswick health authorities present underpenetrated opportunities for regional security operations center establishment. Atlantic provinces face acute shortages of GIAC-credentialed incident responders, inflating managed service premiums. Small municipalities operate legacy Windows Server environments that resist modern endpoint agent deployment.
Canada Ransomware Protection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with managed security providers capturing premium pricing in healthcare and finance verticals. The vendor base concentrates around three tiers: domestic Canadian specialists with native SOAR platforms, telecommunications carriers bundling security with connectivity, and global endpoint software vendors. Strategic archetypes include outcome-based liability transfer specialists, regional security operations center operators, and integrated telecommunications-security bundlers. Competitive dynamics center on M&A activity consolidating mid-market managed services capabilities and strategic partnerships embedding ransomware protection into broader IT infrastructure contracts.
Within the domestic specialist tier, Herjavec Group and Arctic Wolf exemplify Canadian-headquartered providers leveraging native security orchestration platforms to anchor mid-market accounts. eSentire occupies a position as a pure-play managed detection and response operator with Canadian-staffed security operations centers. Telus Security represents the telecommunications bundling archetype, integrating ransomware protection with fiber connectivity and cloud infrastructure contracts to capture multi-service procurement committees.
| Leading Market Players |
|---|
| Herjavec Group |
| Arctic Wolf |
| Telus Security |
| eSentire |
| GoSecure |
| Vumetric |
| Microsoft Canada |
| McAfee |
| Bitdefender |
| Others |
Pricing and Supply Chain Analysis
Canadian cloud infrastructure spot pricing indices cascade through managed security service margins, compressing subscription tiers as hyperscale compute costs reset baseline expectations for ransomware protection procurement committees.
Pricing Analysis
Capacity additions in Ontario and Quebec are reshaping price floors for endpoint protection agents as domestic vendors expand security operations center headcount. Three-tier pricing structure across premium, standard, and economy levels segments buyers by incident response SLA guarantees and forensic certification tiers. Pricing pressure stems from telecommunications carriers bundling ransomware protection with connectivity contracts at negative marginal cost. Municipal utilities in Prairie provinces exhibit highest price sensitivity; Toronto financial institutions prioritize liability transfer over unit cost.
Supply Chain Analysis
Direct-to-enterprise channels handle healthcare network demand while managed service providers aggregate mid-market buyers through subscription platforms. Software development concentrates in Canada, USA, and Israel; threat intelligence feeds draw from Estonia, UK, and Singapore nodes. Raw material dependencies span cryptographic hardware modules, SOC-as-a-service labor pools, and cloud storage infrastructure. Single-source vulnerability runs through hyperscale backup providers with limited Canadian data residency guarantees. Distribution runs through value-added resellers anchored in Toronto, Montreal, and Vancouver.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as healthcare procurement committees rewrite vendor scorecards to prioritize Health Canada medical device cybersecurity attestations over legacy price-performance metrics.
For Market Incumbents: Lock in regional security operations center coverage across Atlantic Canada before forensics certification bottlenecks inflate competitor staffing costs. Deepen backward integration into native SOAR platform development to defend against telecommunications carriers bundling security with infrastructure contracts. Anchor hospital network relationships through immutable backup architecture mandates. For New Entrants and Emerging Players: Launch via managed detection and response subscriptions targeting Nova Scotia and New Brunswick health authorities where GIAC-credentialed talent scarcity creates service gaps. Exploit zero trust convergence opportunities among Ontario mid-market manufacturers modernizing branch infrastructure. Differentiate through Canadian-staffed 24/7 coverage with provincial privacy law expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play managed detection and response operators possessing Canadian security operations center footprints and healthcare vertical specialization. Long-term viability hinges on regulatory compliance automation capabilities as federal mandatory ransomware reporting legislation materializes. Monitor Health Canada pre-market submission guidance tightening as inflection signal for medical device security vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Security Operations Center Expansion | Atlantic Canada health authorities lack GIAC-credentialed coverage, creating first-mover positioning for regional facilities. |
| Native SOAR Platform Development | Mid-market manufacturers in Ontario prioritize automated incident triage to compensate for internal staffing gaps. |
| Telecommunications Bundling Partnership | Fiber connectivity contracts with embedded ransomware protection capture multi-service procurement committees in Prairie provinces. |
| Zero Trust Architecture Integration | Financial institutions in Toronto consolidate vendor relationships around network segmentation with identity governance bundles. |
| Medical Device Cybersecurity Certification | Health Canada pre-market requirements for networked diagnostic equipment create compliance-driven procurement windows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs at Ontario hospital networks, procurement officers at Quebec financial institutions, managed security service executives, and Health Canada regulatory affairs specialists with secondary validation against provincial breach notification filings, hyperscaler capex disclosures, and Canadian cybersecurity labor market data. Bottom-up deployment model sizing and top-down regulatory mandate impact assessment were triangulated for consistency.
Historical reference periods anchored the forecast window to observed procurement cycle compression following provincial privacy commissioner enforcement actions. Segmentation dimensions modeled span solution type, deployment model, end user vertical, and service tier across the projection horizon. CAGRs were derived from elasticity estimates linking regulatory fine structures to prevention technology spending, with inputs including healthcare IT security budget trajectories and critical infrastructure designation expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated federal ransomware reporting legislation or abrupt hyperscale provider data residency policy shifts. Forecasts reflect assumptions about regulatory harmonization velocity and talent pipeline expansion that stress-testing should periodically revisit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Ddos Protection and Mitigation Security Market
Cybersecurity
Benelux Cybersecurity Market
Cybersecurity
Global Content Disarm and Reconstruction Market
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Operational Technology Security Market
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Morocco Cybersecurity Market
Cybersecurity
Content Delivery Network (CDN) Security Market
Cybersecurity
Cyber Security Market
Cybersecurity
Europe Mobile Security Market
Cybersecurity
Finland Cybersecurity Market
Cybersecurity
Network Detection and Response Market
Cybersecurity
Greece Cybersecurity Market
Cybersecurity
Data Protection Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Data-Centric Security Market