
 HERG Screening Market | 2026-2036
HERG Screening Market Size, Share, and Industry Trends Forecast 2026-2036
HERG Screening Market Analysis
Biotech firm demand is shifting toward outsourced electrophysiology services as pipeline complexity rises. Charles River Laboratories leverages its integrated safety pharmacology footprint to anchor multi-site cardiac risk programs. Eurofins Scientific competes through distributed laboratory networks that reduce turnaround times for patch clamp studies. Merck KGaA differentiates with in-house ion channel expertise that supports both client services and internal drug discovery.
HERG screening evaluates the inhibitory potential of drug candidates against the human ether-a-go-go related gene potassium channel, a critical predictor of cardiac arrhythmia risk, using automated patch clamp systems that measure current amplitude at physiological temperatures with throughputs exceeding 10,000 data points daily. The technology dimension shows patch clamp electrophysiology sustaining premium pricing due to regulatory acceptance by FDA and EMA, while cellular assays gain share in early-stage triage where speed outweighs definitive hERG liability quantification. The end user structure reveals contract research organizations capturing the fastest expansion as pharmaceutical companies outsource cardiac safety liabilities to specialized providers with GLP-certified infrastructure.
FDA ICH S7B guidelines and EMA nonclinical safety pharmacology requirements mandate hERG evaluation before first-in-human dosing, creating compliance-driven demand for validated platforms. The EU AI Act and FDA's emerging computational toxicology frameworks are beginning to shape acceptance criteria for in silico hERG prediction tools alongside traditional electrophysiology. Stakeholders must monitor regulatory convergence between manual patch clamp gold standards and high-throughput automated alternatives to anticipate which platform investments will satisfy future submission requirements.
Market Dynamics
Automated patch clamp platforms are compressing study timelines from weeks to days, forcing contract research organizations to restructure their electrophysiology service models around throughput guarantees rather than per-compound pricing.
Growth Catalysts
- FDA ICH S7B mandates:Pre-first-in-human hERG evaluation requirements create compliance-driven procurement of validated automated platforms by pharmaceutical sponsors.
- Biotech pipeline complexity:Small-molecule and biologic candidates with polypharmacology profiles demand higher-resolution cardiac risk characterization earlier in discovery.
- Japan's PMDA alignment:Convergence with ICH guidelines accelerates platform standardization across Tokyo-Osaka biotech clusters.
Market Restraints
- Platform capital intensity:Automated patch clamp instruments require substantial upfront investment, limiting adoption to well-capitalized CROs and large pharmaceutical houses.
- Specialized operator scarcity:Qualified electrophysiologists capable of interpreting ion channel kinetics remain concentrated in Boston, Basel, and Cambridge UK corridors.
- Manual patch clamp persistence:Regulatory agencies continue to treat manual recordings as arbitration standards, slowing full displacement of labor-intensive methods.
Strategic Opportunities
- India's CDSCO pathway expansion:Domestic generic and biosimilar developers are building internal safety pharmacology capabilities to support ANDA filings and export registrations.
- In silico hERG prediction integration:Machine learning models trained on large electrophysiology datasets are converging with automated patch clamp workflows to prioritize compound libraries before wet-lab confirmation.
- Modular service bundling:CROs can package hERG screening with cardiovascular telemetry and histopathology under single-study master service agreements.
Industry Challenges
- GLP certification maintenance:Facilities must sustain OECD-compliant quality systems across multiple sites while harmonizing data formats for regulatory submission.
- Legacy LIMS integration:Automated patch clamp data streams often require custom middleware to connect with established pharmaceutical electronic data capture architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HERG Screening Market |
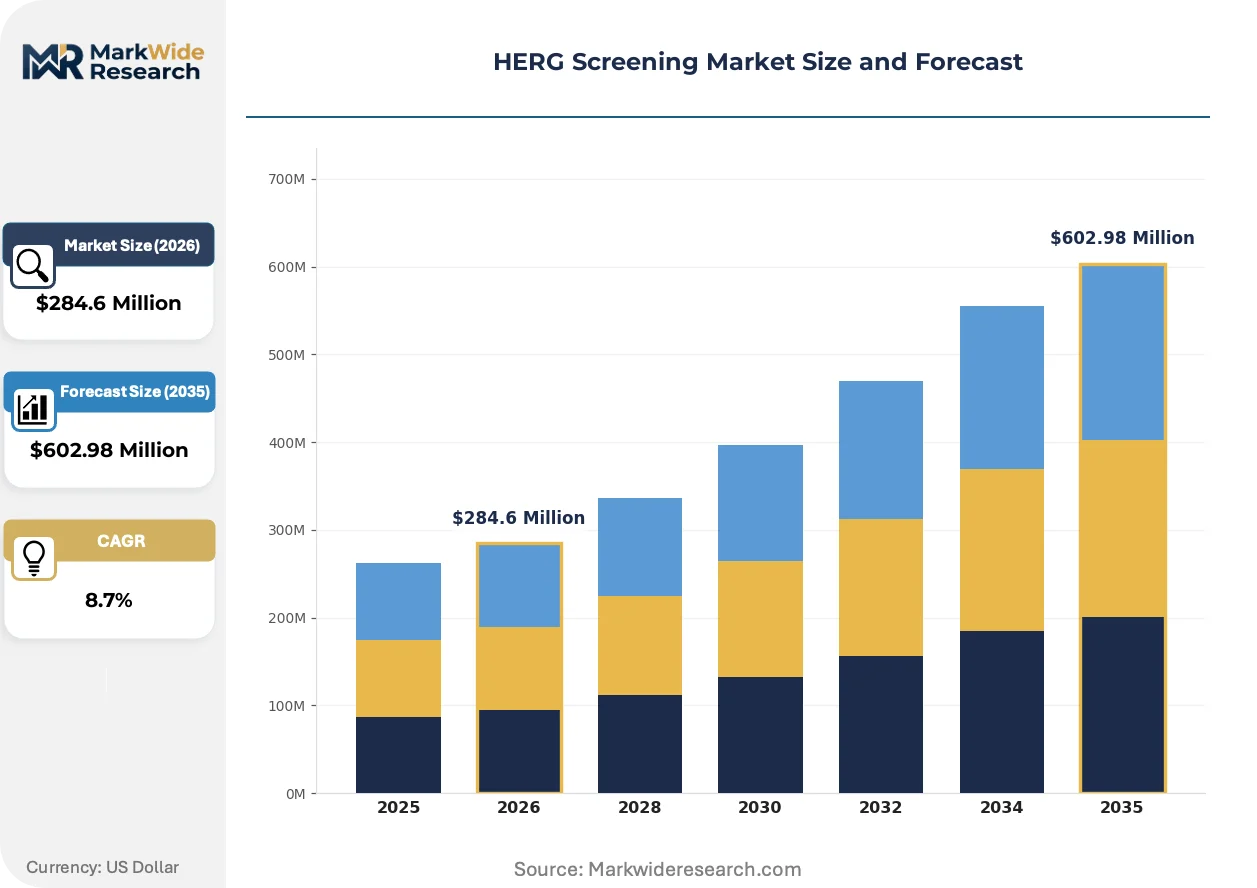
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $602.98 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cardiotoxicity Testing, Drug Development, Toxicology Studies, Safety Pharmacology Technology: Patch Clamp, Electrophysiology, Cellular Assays, Biosensors End User: Pharmaceutical Companies, Research Institutions, Contract Research Organizations, Biotech Firms Solution: In-house Testing, Outsourced Services, Automated Platforms, Software Solutions |
| Companies Covered | Cyprotex Limited, Metrion Biosciences, Charles River Laboratories, Thermo Fisher Scientific, Aurora Biomed, Eurofins Scientific, BSYS GmbH, ChanTest, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HERG Screening Market Emerging Trajectories
Cardiac safety assessment is bifurcating into high-throughput triage platforms and definitive regulatory-grade electrophysiology, with artificial intelligence beginning to bridge the gap between speed and evidentiary weight.
Automated patch clamp systems from vendors such as Molecular Devices and Sophion Bioscience are automating the entire experimental workflow from cell preparation to data analysis. Mid-tier pharmaceutical companies are adopting these platforms at accelerating pace to retain compound screening in-house rather than outsourcing to CROs. This automation is compressing the cost-per-data-point by an order of magnitude while maintaining the voltage-clamp precision required for regulatory submissions.
EMA's evolving stance on nonclinical safety pharmacology is tightening the evidentiary standard for hERG liability documentation in marketing authorization applications. The agency now expects mechanistic understanding of ion channel inhibition kinetics, not simply binary IC50 thresholds. Small-molecule developers targeting European markets are responding by investing in temperature-controlled automated platforms that replicate physiological conditions more faithfully than ambient assays.
Pharmaceutical procurement teams are consolidating cardiac safety spending with fewer preferred CRO partners capable of delivering integrated ion channel, telemetry, and histopathology packages. This concentration is displacing single-service electrophysiology boutiques that cannot offer the full nonclinical safety portfolio. The shift is most visible among mid-cap biotech firms in the San Francisco Bay Area and Research Triangle Park, where venture capital constraints demand operational efficiency across outsourced functions.
HERG Screening Market Segmentation
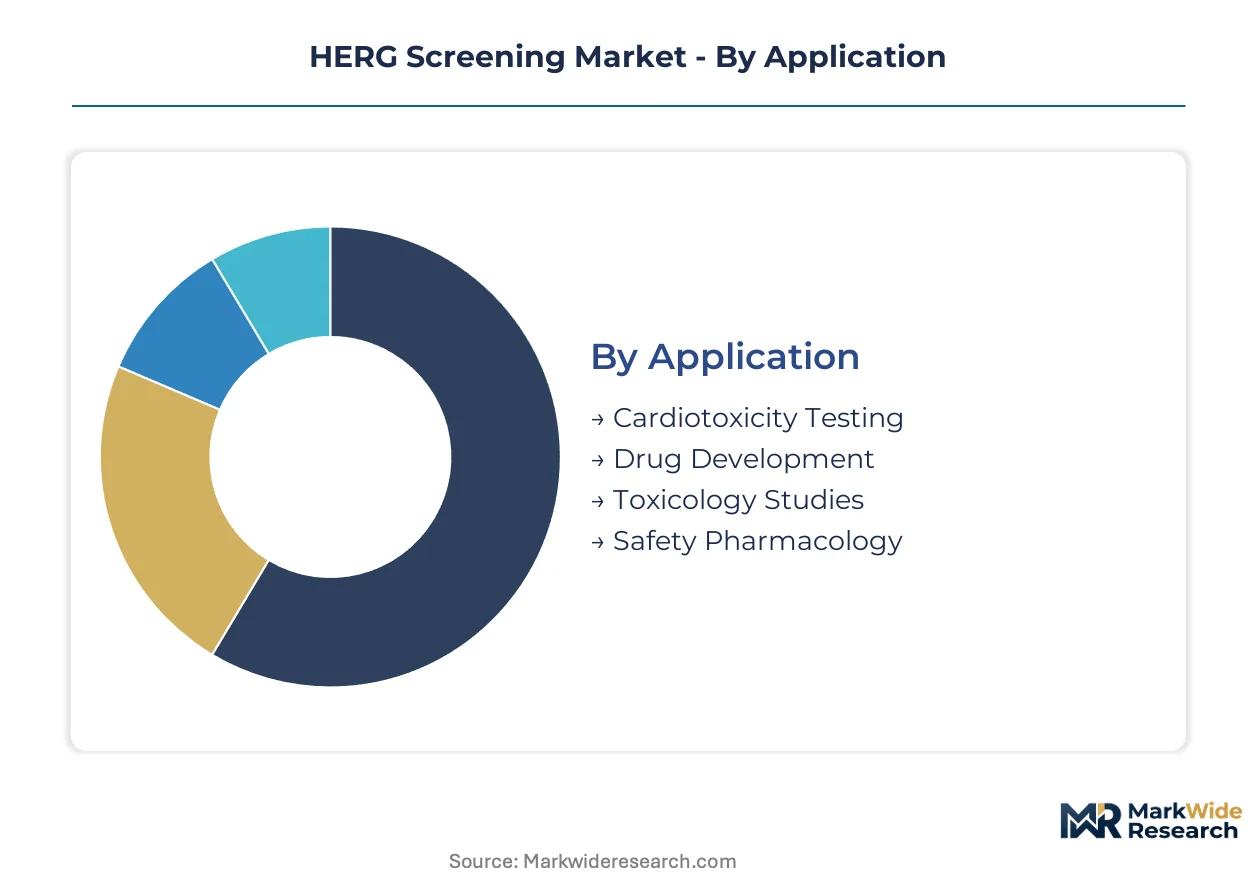
HERG screening segmentation reflects divergent risk tolerance across the drug development pipeline. Early discovery prioritizes speed and cost containment, while regulatory submission phases demand evidentiary rigor that only specific technologies can satisfy. Procurement patterns increasingly favor bundled solutions that span multiple application stages rather than point solutions.
Application:
Customization intensity varies sharply across this category, with regulatory-grade applications demanding protocol standardization while exploratory studies permit methodological flexibility.
- Cardiotoxicity Testing:Automated patch clamp systems measure hERG channel inhibition kinetics at physiological temperatures to predict QT prolongation risk. Demand concentrates among large pharmaceutical sponsors in Germany and Japan preparing IND submissions under FDA ICH S7B and PMDA guidelines, where GLP-compliant data packages are mandatory before first-in-human dosing.
- Drug Development:Integration of hERG screening into lead optimization cycles requires high-throughput platforms capable of processing 10,000+ compounds weekly. Mid-cap biotech firms in the San Francisco Bay Area are internalizing these capabilities to preserve intellectual property around candidate selection, compressing outsourcing reliance for early-stage portfolios.
- Toxicology Studies:Secondary pharmacology assessments evaluate off-target ion channel effects beyond hERG alone. Contract research organizations in Basel and Boston anchor this segment with integrated safety pharmacology offerings.
- Safety Pharmacology:Core battery testing under ICH S7B and ICH E14 mandates hERG evaluation alongside telemetry and histopathology. Large sponsors consolidate spending with full-service CROs capable of single-study master service agreements.
Most installed capacity flows through Cardiotoxicity Testing. Expansion is steepest in Drug Development.
Technology:
Cost tiers separate definitive regulatory electrophysiology from rapid triage methods, with pricing differentials exceeding an order of magnitude per data point.
- Patch Clamp:Voltage-clamp and current-clamp configurations deliver gold-standard ion channel kinetic measurements required for FDA and EMA submissions. Automated platforms from Sophion Bioscience and Molecular Devices now replicate manual precision at throughputs previously unattainable, driving adoption among CROs serving European and Japanese pharmaceutical markets where mechanistic understanding of inhibition is increasingly expected.
- Electrophysiology:Multi-channel platforms assess cardiac action potential duration and conduction velocity in isolated tissues or stem cell-derived cardiomyocytes. Research institutions in Cambridge UK and Basel leverage these systems for mechanistic safety studies beyond hERG alone.
- Cellular Assays:Binding and flux-based methods provide binary liability flags at ambient temperatures, sacrificing kinetic resolution for speed and cost. Early-stage triage in Boston and Research Triangle Park biotech clusters favors these approaches.
- Biosensors:Emerging label-free technologies detect ion channel activity through impedance or optical readouts. Development-stage deployment remains concentrated among platform vendors validating correlation with patch clamp reference standards.
Patch Clamp retains the premium tier by regulatory mandate. Cellular Assays are gaining share fastest in discovery-phase outsourcing.
End User:
Customer type determines procurement structure, with capital availability and pipeline scale dictating in-house versus outsourced model selection.
- Pharmaceutical Companies:Large sponsors maintain captive electrophysiology capabilities at headquarters sites while outsourcing overflow and specialized studies. Merck KGaA and similar integrated houses leverage internal expertise to accelerate candidate progression.
- Research Institutions:Academic centers focus on mechanistic ion channel biology rather than regulatory-compliant screening. Funding constraints limit automated platform adoption to shared core facilities.
- Contract Research Organizations:Charles River Laboratories and Eurofins Scientific compete on turnaround time and geographic coverage, with GLP certification as table stakes. CROs are expanding most quickly as biotech firms outsource cardiac safety liabilities.
- Biotech Firms:Venture-backed developers in Tokyo-Osaka clusters and the San Francisco Bay Area prioritize speed-to-IND over capital intensity, driving demand for outsourced electrophysiology services with guaranteed throughput.
Contract Research Organizations capture the majority of externalized spending. Biotech Firms are expanding their screening budgets most rapidly.
Solution:
Maturity gradients separate established service models from emerging platform and software offerings still proving regulatory acceptance.
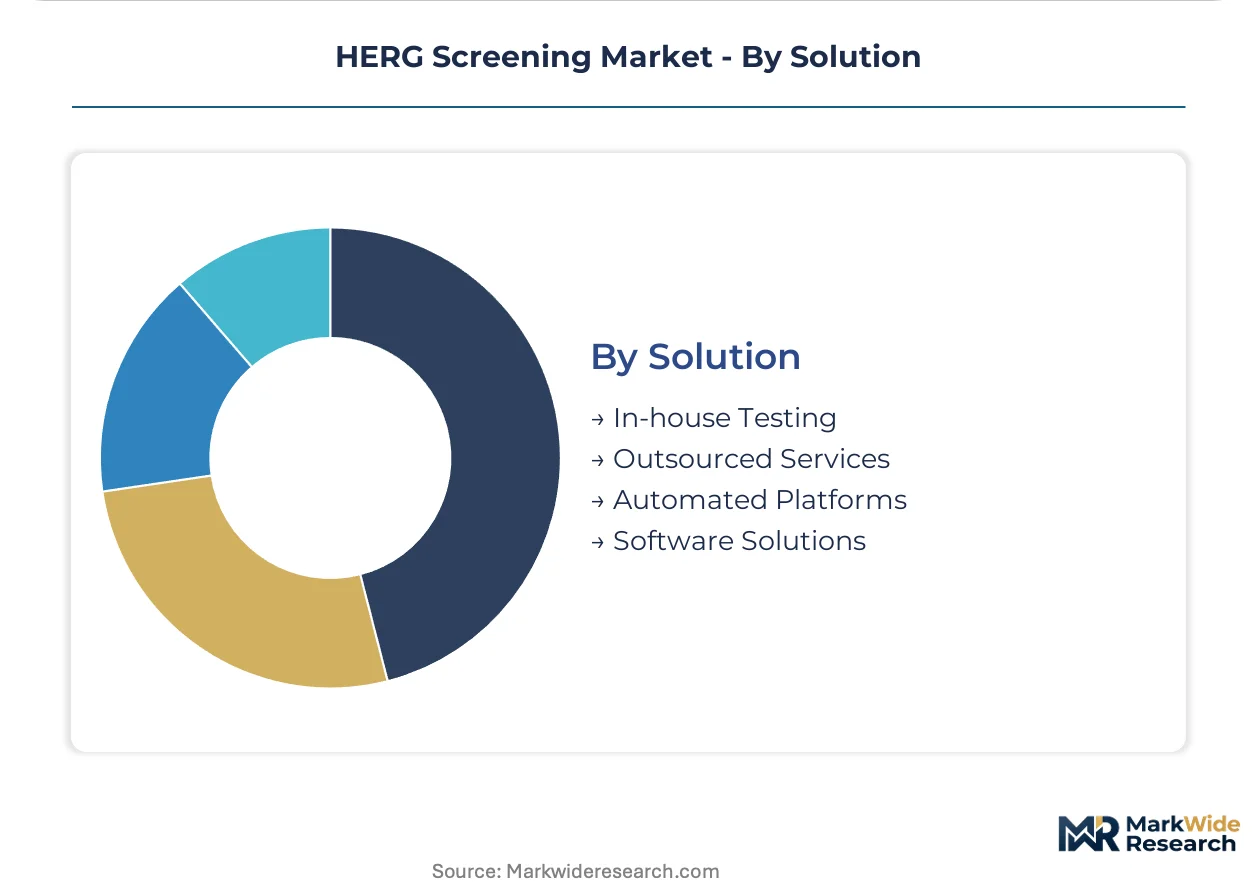
- In-house Testing:Captive laboratories at pharmaceutical headquarters sites retain strategic control over candidate selection and intellectual property. Large sponsors in Basel and Boston maintain these capabilities despite high fixed costs.
- Outsourced Services:Fee-for-study arrangements dominate, with CROs competing on turnaround guarantees and integrated safety pharmacology bundling. Eurofins Scientific's distributed laboratory network reduces logistics friction for European sponsors.
- Automated Platforms:Capital equipment sales to mid-tier pharmaceutical companies enable retention of screening in-house without manual patch clamp labor intensity. Sophion Bioscience and Molecular Devices anchor this segment.
- Software Solutions:In silico hERG prediction tools trained on large electrophysiology datasets are converging with automated workflows. EU AI Act and FDA computational toxicology frameworks are shaping acceptance criteria for these emerging offerings.
Outsourced Services handle the largest compound volumes. Automated Platforms are climbing the fastest as mid-cap sponsors internalize capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors biotech-driven demand for outsourced electrophysiology services, with venture capital constraints compressing timelines for cardiac safety outsourcing decisions across the United States, Germany, and Japan.
United States
FDA ICH S7B compliance mandates drive procurement of automated patch clamp platforms by pharmaceutical sponsors preparing IND submissions. The agency's computational toxicology frameworks are beginning to shape acceptance criteria for in silico prediction tools alongside traditional electrophysiology. Boston's biotech corridor concentrates demand for GLP-certified CRO services with guaranteed throughput.
Germany
EMA's tightening evidentiary standards for hERG liability documentation in marketing authorization applications accelerate investment in temperature-controlled automated platforms. The EU AI Act shapes regulatory acceptance for machine learning models trained on electrophysiology datasets. Basel's pharmaceutical cluster sustains captive electrophysiology capabilities at headquarters sites.
Japan
PMDA alignment with ICH guidelines standardizes platform requirements across Tokyo-Osaka biotech clusters. Domestic generic and biosimilar developers are building internal safety pharmacology capabilities to support export registrations. The Kanto region concentrates automated platform adoption among mid-cap firms prioritizing speed-to-IND.
India
CDSCO pathway expansion drives domestic generic developers to establish internal safety pharmacology capabilities for ANDA filings. Regulatory stringency for cardiac risk assessment is converging with ICH standards. Hyderabad and Mumbai pharmaceutical clusters are investing in GLP-compliant infrastructure for electrophysiology services.
United Kingdom
Research institutions in Cambridge leverage multi-channel electrophysiology platforms for mechanistic safety studies beyond hERG alone. Funding constraints limit automated platform adoption to shared core facilities. The city's ion channel biology expertise sustains academic demand for high-resolution kinetic measurements.
HERG Screening Market Vendor Landscape
Consolidation of cardiac safety spending with fewer preferred partners dominates the current landscape, displacing single-service electrophysiology boutiques that cannot offer integrated ion channel, telemetry, and histopathology packages. The vendor base organizes around three strategic archetypes: full-service CROs with GLP-certified infrastructure, integrated pharmaceutical houses with captive capabilities, and specialized platform vendors. M&A activity and geographic expansion represent the primary competitive moves as firms seek multi-site coverage and bundled service capabilities.
Within the full-service CRO tier, Charles River Laboratories and Eurofins Scientific exemplify geographic coverage strategies, with the former leveraging integrated safety pharmacology footprints and the latter competing through distributed laboratory networks that reduce logistics friction. Merck KGaA occupies a distinct position as an integrated pharmaceutical house that maintains in-house ion channel expertise supporting both client services and internal drug discovery. These three entities represent the dominant competitive anchors across outsourced and captive service models.
| Leading Market Players |
|---|
| Cyprotex Limited |
| Metrion Biosciences |
| Charles River Laboratories |
| Thermo Fisher Scientific |
| Aurora Biomed |
| Eurofins Scientific |
| BSYS GmbH |
| ChanTest |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Automated patch clamp platform standardization across FDA ICH S7B and EMA jurisdictions is compressing cost-per-data-point economics while concentrating supply leverage among Sophion Bioscience and Molecular Devices in Germany and Japan. This technology transition simultaneously erodes legacy manual patch clamp margins and rewards CROs with GLP-certified throughput guarantees.
Pricing Analysis
Consumable costs for patch clamp chips and validated cell lines pass through directly to study sponsors, with temperature-controlled platforms commanding premium positioning against ambient cellular assays. Three-tier pricing structure across premium, standard, and economy levels separates GLP-compliant regulatory packages from exploratory screening tiers. Pricing pressure stems from mid-cap biotech procurement consolidation with fewer preferred CRO partners. Early-stage discovery teams exhibit highest price sensitivity, while large pharmaceutical sponsors prioritize turnaround guarantees over per-compound economics.
Supply Chain Analysis
Freight costs for temperature-sensitive reagents and live cell shipments anchor supply chain economics, with distribution runs through regional hubs in Basel, Boston, and Tokyo-Osaka corridors. Manufacturing concentrates in Germany, the United States, and Denmark for automated platform hardware, while cell line production draws from specialized bioreactor facilities in Singapore and the Netherlands. Single-source vulnerability persists for high-fidelity hERG-expressing cell lines. Direct instrument sales and CRO service contracts constitute the dominant downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HERG screening has matured into a quality-tiered service market where EMA's mechanistic kinetic requirements and FDA computational toxicology frameworks favor providers with validated automated infrastructure over manual patch clamp boutiques.
For Market Incumbents: Deploy throughput-guarantee contracting to lock in pharmaceutical sponsor relationships before in silico prediction tools achieve regulatory parity. Charles River Laboratories and Eurofins Scientific should expand temperature-controlled platform footprints in Japan's Kanto region to capture PMDA-aligned demand. Consolidation pressure from integrated safety pharmacology bundling threatens single-service electrophysiology boutiques.
For New Entrants and Emerging Players: India's CDSCO-registered generic developers represent an underserved buyer archetype with accelerating internal safety pharmacology buildouts. Hyderabad and Mumbai pharmaceutical clusters offer white-space entry for GLP-certified CRO partnerships supporting ANDA filings. A modular service bundling approach—combining hERG screening with cardiovascular telemetry—differentiates against established European and North American incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for regional CROs with GLP infrastructure because pharmaceutical procurement consolidation demands multi-site geographic coverage and integrated safety pharmacology capabilities. Target mid-tier automated platform operators in Germany and Japan with established EMA and PMDA submission track records. Monitor FDA computational toxicology framework evolution as an inflection signal for in silico prediction tool acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Platform Integration | Sophion Bioscience and Molecular Devices compress study timelines from weeks to days for CRO clients. |
| GLP Certification Expansion | Multi-site OECD-compliant quality systems satisfy FDA ICH S7B and EMA submission requirements. |
| In Silico Prediction Convergence | Machine learning models trained on electrophysiology datasets prioritize compound libraries before wet-lab confirmation. |
| Geographic Hub Consolidation | Basel, Boston, and Tokyo-Osaka corridors concentrate qualified electrophysiologist talent pools. |
| Regulatory Framework Alignment | PMDA convergence with ICH guidelines standardizes platform investments across Japanese biotech clusters. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market informing demand modeling. The analysis combines structured interviews with drug development executives, regulatory affairs leads at pharmaceutical sponsors, CRO operations directors, and ion channel biology specialists with secondary validation against FDA filings, EMA marketing authorization applications, ClinicalTrials.gov records, and PMDA consultation minutes. Bottom-up automated platform installation counts and top-down pharmaceutical R&D spending patterns were triangulated to anchor market sizing.
Granularity extends to technology tier, application stage, end-user archetype, and regional regulatory cluster across the projection horizon. Segment-level CAGRs were derived from installed base expansion rates, outsourcing penetration trends, and sponsor internalization decisions. Forecast inputs incorporated ICH S7B compliance mandate evolution, EMA mechanistic kinetic documentation tightening, and PMDA guideline convergence timelines.
Underlying measurement precision varies by segment; automated platform sales and CRO service revenues carry tighter precision than emerging in silico prediction tool adoption. Forecasts reflect documented assumptions about regulatory acceptance timelines and sponsor outsourcing elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Global Fluorescence Spectrophotometer Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Global Gel Documentation Systems Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Global Spectroscopy Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Battery Testers and Analyzers Market