
 High Purity Gas Flow Meter Market | 2026-2036
High Purity Gas Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Gas Flow Meter Market Insights
Semiconductor-grade calibration is rotating the High Purity Gas Flow Meter market toward tighter traceability requirements. Bronkhorst leverages its MEMS sensor platform to dominate low-flow precision applications. Emerson Electric anchors its position through integrated gas handling systems that bundle metering with pressure control. Brooks Instrument differentiates via vertical integration into sapphire tube manufacturing for corrosive gas compatibility.
A high purity gas flow meter measures ultraclean process gases with contamination thresholds below one part per billion, employing thermal, coriolis, or ultrasonic sensing principles to maintain flow accuracy within fractions of a percent across chemically aggressive media. Coriolis flow meters capture expanding margin pools in pharmaceutical processing where batch integrity demands direct mass measurement. Thermal mass flow meters sustain volume leadership in semiconductor manufacturing due to their absence of moving parts and compatibility with reactive precursor gases. Differential pressure variants occupy a mature niche in bulk gas distribution where cost sensitivity outweighs precision requirements.
SEMI standards govern particulate and moisture limits in process gas delivery systems, compelling meter manufacturers to certify surface finish and material outgassing properties. The EPA regulates fluorinated greenhouse gas emissions from semiconductor etching processes, indirectly mandating leak-tight metering infrastructure. FDA cGMP requirements for drug production plants extend to gas flow validation in sterile manufacturing environments. Stakeholders must weigh R&D allocation between next-generation optical sensing and incremental advances in established thermal platforms as process node transitions accelerate gas chemistry complexity.
Market Dynamics
Advanced node semiconductor manufacturing is compressing contamination thresholds below one part per billion, forcing meter suppliers to recertify surface finishes and material outgassing properties for each process chemistry transition. This pressure cascades through supply chains as foundry expansion in Taiwan and South Korea accelerates qualification timelines.
Growth Catalysts
- SEMI F57-0301 Standards:Tightened particulate specifications for ultrahigh-purity gas distribution systems mandate upgraded metering infrastructure in new fab construction across East Asian manufacturing corridors.
- Pharmaceutical Sterile Manufacturing:FDA cGMP validation requirements for biologics production extend to gas flow verification, creating dedicated demand for corrosion-resistant thermal mass meters in single-use facility expansions.
- Fluorinated Gas Regulation:EPA emissions controls on etching process gases indirectly require leak-tight metering architectures with enhanced traceability documentation for semiconductor operations.
Market Restraints
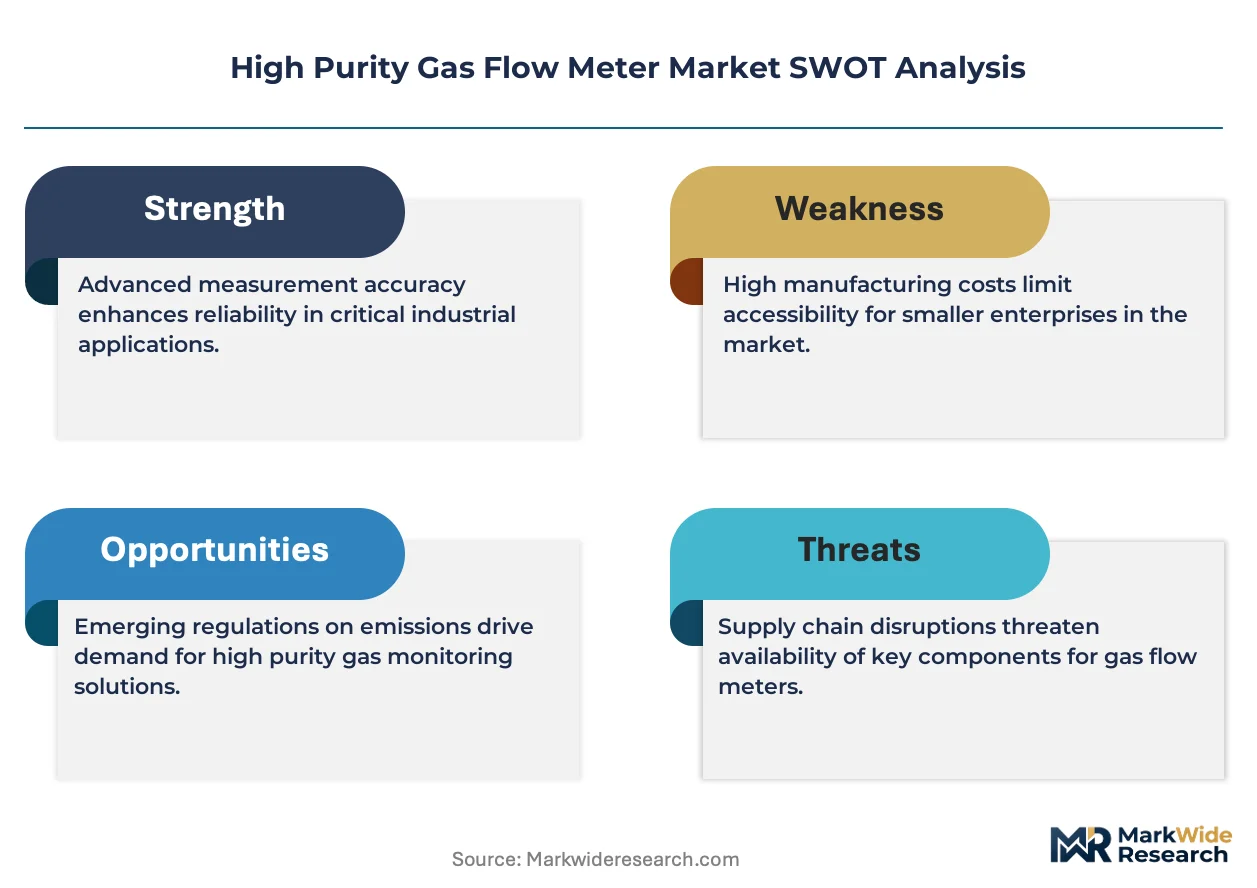
- Sapphire Tube Supply Concentration:Captive production of corrosion-resistant sensor housings clusters with three specialized ceramic suppliers, creating input bottlenecks for meters handling chlorine trifluoride and tungsten hexafluoride.
- MEMS Fabrication Cost Structure:Cleanroom-grade silicon wafer processing for thermal sensor chips carries fixed overhead that compresses margins on sub-$500 meter categories.
- REACH Substance Restrictions:European chemical registration requirements delay material approvals for new elastomer seals, extending product development cycles by 8-14 months for EU-bound equipment.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for semiconductor packaging and display manufacturing are attracting foundry investments that require localized gas handling infrastructure.
- Optical Sensing Convergence:Interferometric flow measurement combined with fiber-optic telemetry eliminates electrical components from corrosive gas paths, opening pharmaceutical and specialty chemical applications.
- Service Contract Unbundling:Meter-as-a-subscription models separate hardware ownership from calibration and certification services, penetrating mid-tier biotech facilities with constrained capex budgets.
Industry Challenges
- Metrology Talent Scarcity:Qualified technicians for NIST-traceable calibration of sub-1% accuracy thermal meters are concentrated with a handful of national standards laboratories and specialized service providers.
- Legacy System Integration:Retrofitting digital flow meters into existing analog SCADA architectures at operating semiconductor fabs requires custom protocol gateways that extend commissioning timelines.
- Multi-Standard Certification:Simultaneous SEMI, FDA, and ATEX compliance for meters serving both chip and pharmaceutical sectors demands redundant testing documentation that inflates engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Gas Flow Meter Market |
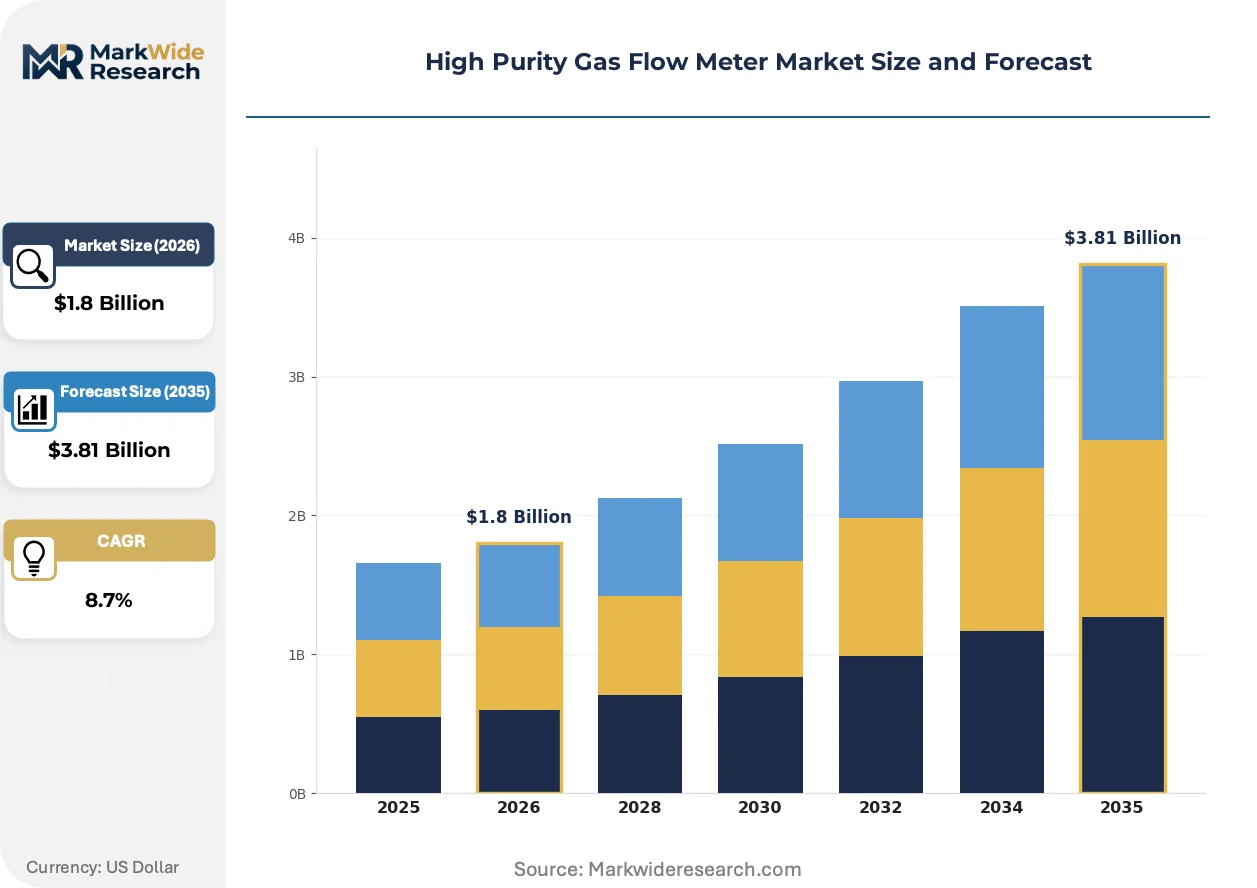
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Mass Flow Meter, Coriolis Flow Meter, Ultrasonic Flow Meter, Differential Pressure Flow Meter, Positive Displacement Flow Meter Technology: Electromagnetic, Vortex Shedding, Variable Area, Turbine, Optical Application: Semiconductor Manufacturing, Pharmaceutical Processing, Chemical Synthesis, Research Laboratories, Aerospace Engineering End User: Microelectronics Facilities, Drug Production Plants, Specialty Chemical Producers, Scientific Institutions, Aviation Component Makers |
| Companies Covered | Brooks Instrument, Emerson Electric, Bronkhorst, Azbil, Yokogawa Electric, Horiba, Endress+Hauser, Sensirion, Sierra Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Gas Flow Meter Market Trends and Innovations
Process gas chemistry complexity at 3nm and below process nodes is fragmenting meter architectures, with thermal, coriolis, and ultrasonic platforms each capturing distinct contamination-risk tiers rather than competing head-to-head.
MEMS-based thermal mass sensors with platinum resistance temperature detectors are displacing traditional capillary thermal designs in low-flow precursor delivery applications. Leading-edge foundries in Taiwan and South Korea have adopted these solid-state architectures for 90% of new ALD tool installations. The shift is displacing mechanical bypass configurations and compressing the addressable market for differential pressure variants below 50 sccm ranges.
EU F-Gas Regulation amendments tighten reporting thresholds for perfluorinated compound emissions from semiconductor etch chambers. Industrial consequence includes mandatory mass-balance verification for process gas consumption, forcing meter suppliers to embed tamper-evident data logging. Memory chip manufacturers in Ireland and Germany are responding by specifying coriolis meters with onboard density compensation for direct mass measurement of NF3 and CF4.
Consolidated procurement through integrated gas system vendors is fragmenting direct OEM relationships. Equipment buyers at multi-fab operators now contract for bundled gas handling skids rather than discrete meters, compressing vendor lists to suppliers with captive pressure-control and filtration capabilities. This pattern is most visible in South Korean memory sector expansions where Hyundai Engineering and Samsung C&T specify turnkey subsystems.
High Purity Gas Flow Meter Market Segmentation
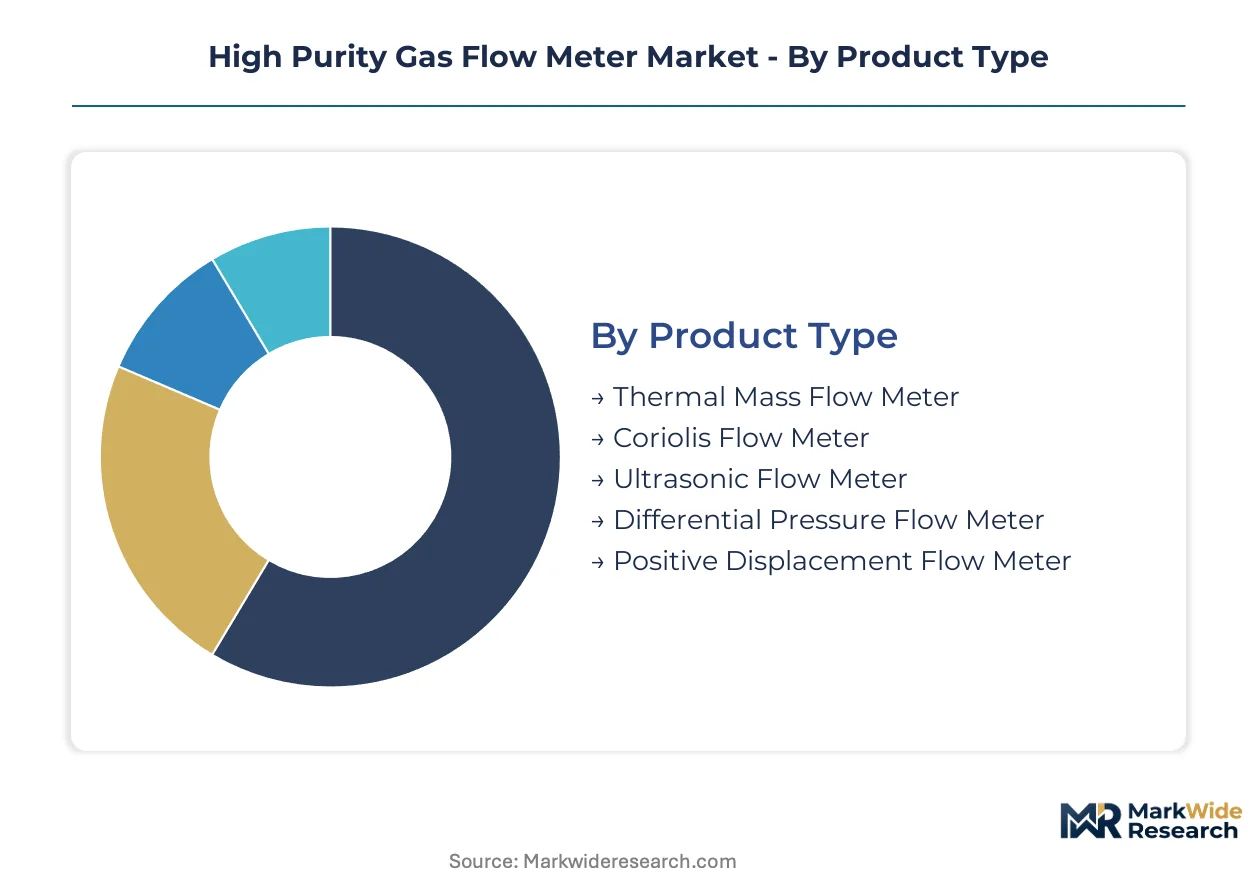
High purity gas flow meter segmentation reflects divergent contamination tolerance thresholds across process nodes. Meter architectures fragment by chemistry aggressiveness rather than competing directly, with each configuration capturing distinct margin tiers.
Product Type:
Margin pools concentrate in platforms eliminating wetted moving parts from ultraclean gas paths.
- Thermal Mass Flow Meter:Platinum resistance temperature detectors measure heat dissipation from resistive elements exposed to laminar gas flow. Taiwan and South Korea foundries specify these solid-state designs for atomic layer deposition tool retrofits, displacing mechanical bypass configurations below 50 sccm ranges. Thermal Mass Flow Meter holds installed capacity. Coriolis Flow Meter is rotating up the share rankings.
- Coriolis Flow Meter:Vibrating U-tube sensors detect phase shifts proportional to mass flow rate, enabling direct density-compensated measurement without calibration gas dependencies. Pharmaceutical batch processors in Ireland and Germany mandate these for perfluorinated compound mass-balance reporting under EU F-Gas Regulation amendments.
- Ultrasonic Flow Meter:Transit-time differential measurement across pipe diameters eliminates wetted components entirely, serving corrosive halogen chemistry at specialty chemical producers.
- Differential Pressure Flow Meter:Orifice-plate configurations with capacitive transmitters occupy mature bulk gas distribution where cost sensitivity outweighs precision requirements.
- Positive Displacement Flow Meter:Piston or oval-gear mechanisms handle viscous precursor liquids in research laboratory calibration standards.
Thermal designs dominate semiconductor retrofit activity. Coriolis architectures are climbing fastest in pharmaceutical validation workflows.
Technology:
Technology selection tracks the trade-off between electrical component isolation and measurement responsiveness.
- Electromagnetic:Faraday induction across conductive process fluids requires ionic gas species, limiting relevance to plasma etch byproduct monitoring rather than pristine feedstock measurement.
- Vortex Shedding:Piezoelectric detection of von Karman vortices suits high-velocity nitrogen purge lines in microelectronics facility bulk distribution headers.
- Variable Area:Float-position indicators with sapphire guide tubes provide visual flow confirmation for chlorine trifluoride service at specialty chemical producers.
- Turbine:Axial rotor designs with magnetic pickup coils retain niche applications in aviation component maker helium leak test stands where response speed trumps contamination risk.
- Optical:Laser Doppler velocimetry and interferometric techniques eliminate electrical components from corrosive gas paths entirely, opening biologics sterile manufacturing where FDA cGMP validation demands fiber-optic telemetry isolation.
Established electrical sensing modalities retain semiconductor fab share. Optical platforms are expanding most quickly in pharmaceutical containment applications.
Application:
Application segmentation maps directly to regulatory stringency tiers governing process gas documentation.
- Semiconductor Manufacturing:Advanced node production below 3nm compresses particulate thresholds below one part per billion, forcing SEMI F57-0301 recertification of surface finishes and material outgassing properties for each chemistry transition.
- Pharmaceutical Processing:FDA cGMP requirements for sterile biologics production extend to gas flow validation, creating dedicated demand for corrosion-resistant thermal mass meters in single-use facility expansions.
- Chemical Synthesis:Halogen and organometallic precursor handling at specialty chemical producers drives sapphire tube specifications for tungsten hexafluoride compatibility.
- Research Laboratories:NIST-traceable calibration requirements concentrate metrology talent scarcity with national standards laboratories and specialized service providers.
- Aerospace Engineering:Propulsion system testing and satellite thruster qualification demand ultrahigh-purity xenon and krypton metering for electric propulsion development.
Semiconductor Manufacturing anchors volume demand. Pharmaceutical Processing is gaining share fastest on biologics facility investment.
End User:
End user procurement patterns diverge between bundled subsystem contracting and discrete meter specification.
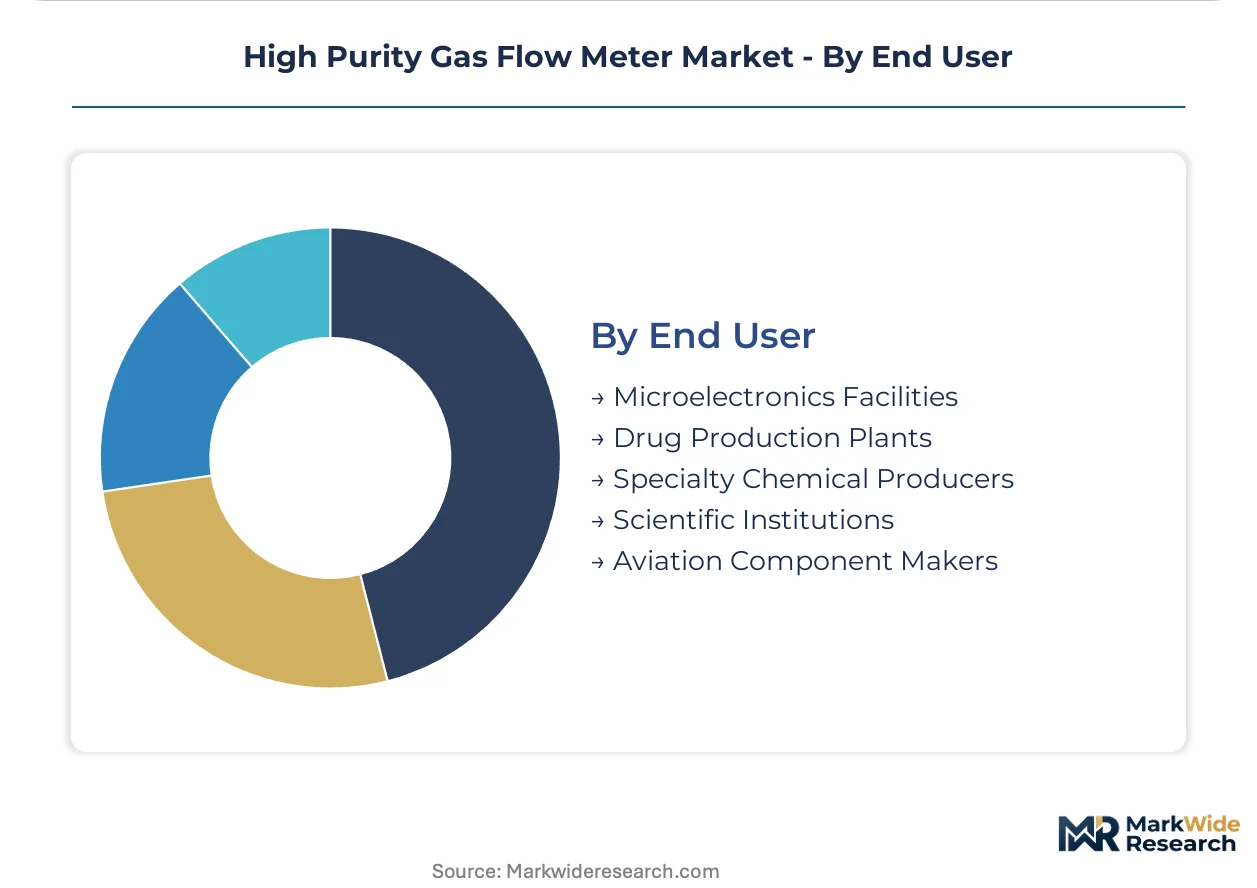
- Microelectronics Facilities:Multi-fab operators in South Korea now contract for turnkey gas handling skids through integrated system vendors, compressing direct OEM relationships to suppliers with captive pressure-control capabilities.
- Drug Production Plants:Constrained capex budgets at mid-tier biotech facilities are penetrating meter-as-a-subscription models separating hardware ownership from calibration services.
- Specialty Chemical Producers:REACH substance restrictions delay elastomer seal approvals, extending product development cycles for EU-bound equipment.
- Scientific Institutions:Legacy analog SCADA architectures at operating research facilities require custom protocol gateways that extend digital flow meter commissioning timelines.
- Aviation Component Makers:Precision welding and thermal spray operations specify thermal mass meters for argon and helium shield gas delivery.
Microelectronics Facilities concentrate procurement volume. Drug Production Plants are rotating fastest toward service-based acquisition models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering houses export calibration-grade instrumentation to Taiwanese foundry clusters, establishing the dominant trade corridor in advanced node metrology.
United States
EPA fluorinated gas emissions controls tighten mass-balance documentation requirements for semiconductor etch operations. The CHIPS and Science Act funds domestic fab construction in Arizona and Texas. Intel's Ohio campus and TSMC's Phoenix expansion drive demand for NIST-traceable thermal mass meters in precursor delivery systems.
Germany
EU F-Gas Regulation amendments mandate tamper-evident data logging for perfluorinated compound consumption. Memory chip manufacturers in Dresden and Frankfurt specify coriolis meters with onboard density compensation. BASF and Merck KGaA specialty chemical facilities anchor sapphire tube demand for tungsten hexafluoride service.
China
MIIT domestic semiconductor self-sufficiency targets accelerate local gas handling infrastructure procurement. Yangtze Memory Technologies and SMIC expand capacity in Wuhan and Shanghai. GB standards for ultrahigh-purity gas distribution drive recertification of surface finish specifications for imported metering equipment.
South Korea
Samsung and SK Hynix foundry investments concentrate procurement through integrated gas system vendors. Seoul Capital Area fabs specify bundled subsystems combining metering with pressure control. Hyundai Engineering turnkey contracts compress direct OEM relationships to captive capability suppliers.
Japan
METI semiconductor supply chain resilience initiatives diversify gas handling equipment sourcing. Tokyo Electron and Shin-Etsu Chemical anchor demand in the Chubu industrial corridor. Yokogawa and Horiba domestic sensor platforms compete with European thermal mass architectures in legacy fab retrofits.
High Purity Gas Flow Meter Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and chemistry-specific customization. The vendor base stratifies into three capability tiers: integrated system houses with captive pressure control, precision sensor specialists with MEMS platforms, and regional fabricators serving mature bulk gas distribution. Consolidation pressure intensifies as foundry procurement shifts toward bundled subsystem contracting. Dominant competitive moves include backward integration into sapphire ceramic supply and geographic licensing partnerships for local calibration services.
Among precision instrumentation specialists, Bronkhorst, Brooks Instrument, and Emerson Electric exemplify distinct archetype positioning. Bronkhorst represents the MEMS-native sensor platform model with cleanroom-grade silicon wafer processing. Brooks Instrument anchors the vertical manufacturing approach through in-house sapphire tube production. Emerson Electric occupies the integrated systems tier with bundled gas handling architectures. Each archetype captures discrete margin pools across contamination-risk tiers rather than competing head-to-head on identical specifications.
| Leading Market Players |
|---|
| Brooks Instrument |
| Emerson Electric |
| Bronkhorst |
| Azbil |
| Yokogawa Electric |
| Horiba |
| Endress+Hauser |
| Sensirion |
| Sierra Instruments |
| Others |
Pricing and Supply Chain Analysis
Ninety-day sapphire tube lead times from specialized ceramic suppliers concentrate pricing power with meter manufacturers handling chlorine trifluoride chemistry, compressing margins for sub-$500 thermal sensor categories while elevating premium Coriolis configurations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture SEMI F57-0301 certified meters with NIST-traceable calibration documentation, while economy segments serve bulk nitrogen distribution with differential pressure variants. Cost compression in standard tiers intensifies because MEMS fabrication fixed overhead spreads poorly across low-volume orders. Mid-tier biotech facilities exhibit highest price sensitivity, whereas advanced node foundries prioritize contamination thresholds over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, drawing sapphire sensor housings from German precision ceramic suppliers and platinum resistance elements from Japanese metal refiners. Supply chain risk centers on single-source vulnerability for corrosion-resistant sensor substrates qualified under tungsten hexafluoride exposure protocols. Distribution runs through integrated gas system vendors in Seoul and Hsinchu, compressing direct OEM relationships to suppliers with captive pressure-control capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SEMI F57-0301 recertification cycles at 3nm process nodes compress supplier qualification timelines, creating high-growth disruption for meter architectures eliminating wetted electrical components from ultraclean gas paths.
For Market Incumbents: Secure backward integration into sapphire ceramic supply to defend against input bottlenecks for corrosive halogen service. Anchor capacity expansion in South Korea through Hyundai Engineering turnkey partnerships, insulating against procurement fragmentation as multi-fab operators consolidate vendor lists.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for semiconductor packaging, where localized gas handling infrastructure lacks established supplier relationships. Target mid-tier biotech facilities with meter-as-a-subscription models, penetrating constrained capex budgets through unbundled calibration services rather than hardware ownership.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized MEMS cleanroom capacity applicable to thermal sensor platforms. Long-term viability hinges on optical sensing convergence eliminating electrical components from corrosive paths. Watch EU F-Gas Regulation enforcement intensity as inflection indicator for Coriolis meter demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Supply | Captive ceramic production secures corrosion-resistant sensor housing availability for chlorine trifluoride service. |
| Optical Sensing Platform Development | Interferometric techniques with fiber-optic telemetry penetrate FDA cGMP biologics manufacturing requiring electrical isolation. |
| India Manufacturing Localization | PLI scheme incentives attract foundry investments requiring domestic gas handling infrastructure certification. |
| Subscription Service Unbundling | Meter-as-a-service models penetrate mid-tier biotech capex constraints through separated calibration ownership. |
| Multi-Standard Certification Investment | Simultaneous SEMI, FDA, and ATEX compliance captures cross-sector pharmaceutical and semiconductor demand. |
Research Methodology
Desk research of customs trade databases, SEMI technical standards documentation, and EPA regulatory filings preceded structured interviews with fab engineering directors, gas handling system procurement managers, and NIST-traceable calibration service technicians. Primary fieldwork across Taiwan, South Korea, and Germany validated secondary findings through bottom-up and top-down triangulation against foundry capital expenditure disclosures and integrated gas system vendor order pipelines.
Variance decomposition across the projection horizon isolates volume drivers by product architecture, contamination-risk tier, and end-use regulatory stringency. Segmentation dimensions modeled include meter technology, application chemistry aggressiveness, and geographic manufacturing corridor. CAGRs derive from installed base expansion rates and replacement cycle compression at advanced process nodes, incorporating fluorinated gas emission reporting thresholds and pharmaceutical sterile manufacturing validation requirements as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued East Asian foundry investment concentration and stable EPA fluorinated gas enforcement posture; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in process node transitions and EU F-Gas Regulation amendment trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Microplate Absorbance Reader Market
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Analytical Ultracentrifuge Systems Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Spatial Mass Spectrometry Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Visualization Instruments for MIS Market