
 Handheld Laser Measuring Instrument Market | 2026-2036
Handheld Laser Measuring Instrument Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Laser Measuring Instrument Market Insights
Specialty tool distribution is fragmenting as e-commerce platforms and direct-to-contractor channels erode traditional hardware retail dominance. Robert Bosch GmbH leverages its multi-brand power tool portfolio to sustain shelf presence across fragmented European and North American channels. Leica Geosystems anchors premium positioning through geomatics heritage and survey-grade accuracy credentials. Hilti Corporation competes via fleet management and direct sales relationships with large construction accounts, bypassing conventional retail entirely.
Handheld laser measuring instruments emit modulated laser beams to calculate distance, area, or volume through time-of-flight or phase-shift detection, typically achieving ±1.5 mm accuracy over 50-120 meter ranges for construction layout and dimensional verification tasks. Bluetooth laser measure units are capturing expanding share as contractors integrate mobile workflow apps for real-time documentation and cloud-based project management. Phase shift technology dominates mid-range indoor applications where speed and power efficiency matter, while time-of-flight architectures lead outdoor measurement segments requiring extended range performance.
FCC certification governs radio-frequency emissions for Bluetooth-equipped units in the United States, while CE marking and REACH substance restrictions regulate product safety and material composition across European markets. ISO 16331-1 establishes standardized testing protocols for laser distance meter range and accuracy claims, shaping comparative purchasing decisions among professional users. Stakeholders must monitor evolving interoperability standards between measurement hardware and building information modeling platforms as digital twin adoption reshapes specification requirements.
Market Dynamics
Bluetooth-enabled workflow integration is compressing replacement cycles as contractors retire analog tape measures and basic laser units for connected devices that feed directly into building information modeling platforms. This connectivity imperative is restructuring procurement priorities across residential and commercial construction segments.
Growth Catalysts
- CE Marking and EU AI Act Compliance:Tightened accuracy certification protocols in Europe are forcing professional-grade upgrades as contractors replace uncertified legacy units to meet site access requirements.
- 3D-Capable Measurement:Point-cloud generation and spatial mapping functions are penetrating renovation workflows where dimensional as-built documentation drives change-order accuracy.
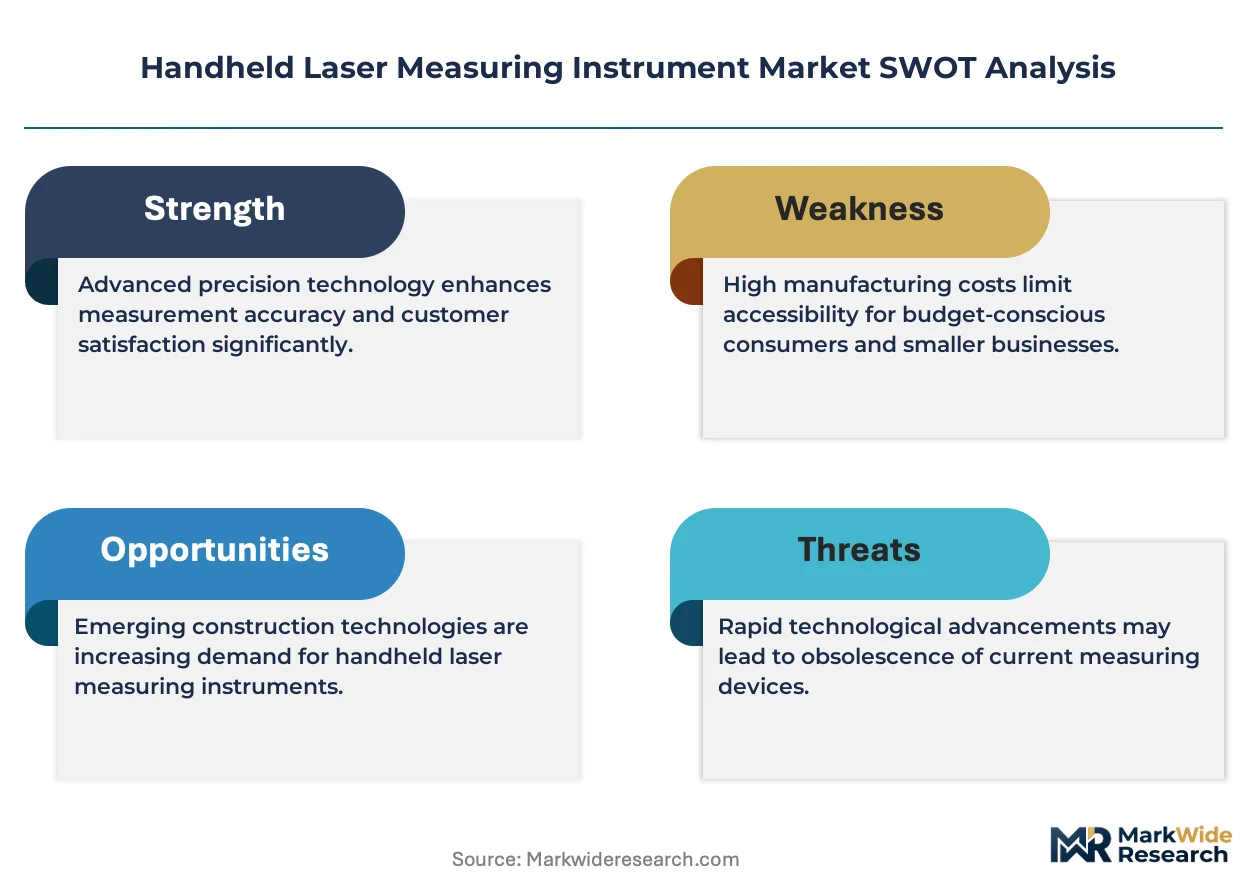
- German Building Renovation Density:Dense refurbishment activity in residential and heritage structures sustains premium product uptake where ±1.5 mm tolerance justifies higher equipment spend.
Market Restraints
- ISO 16331-1 Testing Burden:Standardized range and accuracy verification protocols add certification cost layers that disadvantage smaller regional manufacturers lacking in-house metrology labs.
- Smartphone LiDAR Substitution:Apple and Android device-integrated depth sensing is capturing basic measurement tasks under 10 meters, eroding entry-level laser measure volume.
- Semiconductor Component Concentration:Laser diode and time-of-flight sensor supply concentrates in East Asian foundries, exposing lead time vulnerability to foundry allocation decisions.
Strategic Opportunities
- India Infrastructure Build-Out:Metro rail, smart city, and highway corridor projects are creating first-time professional measurement tool demand among domestic contractors previously reliant on manual methods.
- Digital Twin Convergence:Laser measure-to-BIM interoperability standards are opening specification channels with architecture and engineering firms embedding hardware into design-build contracts.
- Direct-to-Contractor Fleet Models:Tool-as-a-service subscriptions bypassing traditional hardware retail are capturing large construction accounts seeking predictable OpEx structures and maintenance bundling.
Industry Challenges
- Calibration Technician Scarcity:Phase-shift and time-of-flight sensor recalibration requires specialized metrology expertise that distributor service networks struggle to staff at sufficient density.
- FCC Certification Timeline:Bluetooth-equipped units face 12-16 week radio-frequency emission approval cycles that delay product launches and compress competitive response windows.
- Legacy Workflow Integration:Established contractors running paper-based site documentation resist mobile app dependency, creating sales cycle friction for connected product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Laser Measuring Instrument Market |
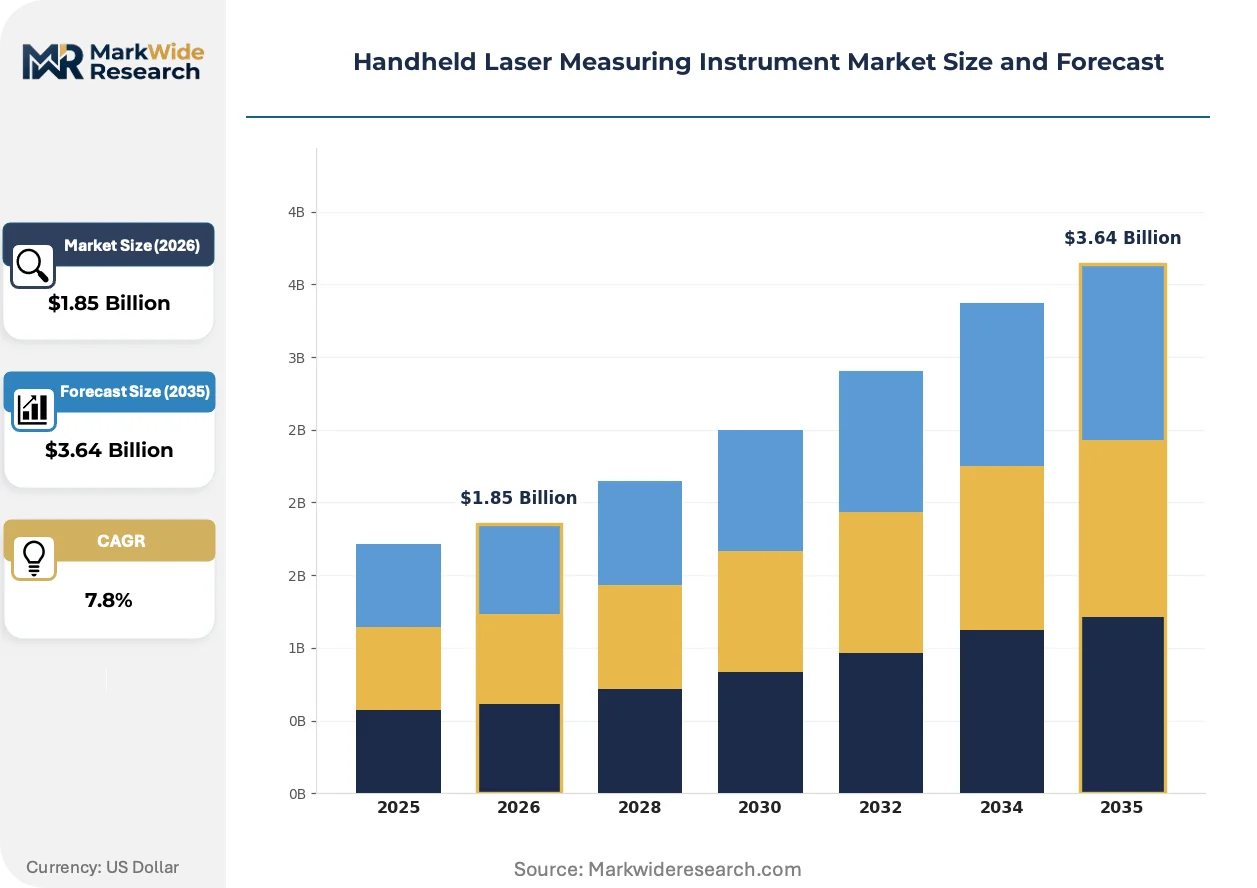
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Laser Measure, Bluetooth Laser Measure, 3D Laser Measure, Digital Tape Measure Technology: Time-of-Flight, Phase Shift, Triangulation, Ultrasonic End User: Construction, Interior Design, Surveying, Real Estate Application: Outdoor Measurement, Indoor Measurement, Wall Layout, Distance Calculation |
| Companies Covered | Robert Bosch GmbH, Leica Geosystems, Fluke Corporation, Hilti Corporation, Trimble Inc., Stanley Black & Decker, Makita Corporation, Hexagon AB, Spectra Precision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Laser Measuring Instrument Market Trends and Innovations
Measurement hardware is converging with software-defined workflow platforms, collapsing traditional boundaries between field data capture and office-based project management systems. This integration is redefining how accuracy specifications translate into purchasing decisions.
Multi-line laser projection combined with integrated inclinometers is collapsing the distinction between point measurement and full layout functions. Commercial contractors adopting slab-on-grade and ceiling grid installation are specifying these hybrid units to eliminate separate rotary laser purchases. The technology is compressing equipment count on job sites and shifting vendor relationships toward integrated solution providers.
EU AI Act algorithmic transparency requirements are mandating documentation of automated measurement error correction routines in connected devices. Manufacturers serving European professional markets must now disclose machine-learning-assisted accuracy adjustments in firmware. Survey-grade instrument divisions are responding fastest, leveraging existing calibration traceability systems to satisfy audit requirements.
Construction procurement departments are consolidating vendor relationships around integrated tool fleet programs that bundle laser measures with power tools and dust extraction systems. Large general contractors in Germany and the United States are negotiating enterprise pricing that locks out fragmented retail purchases. Channel power is rotating toward direct manufacturer relationships and away from independent hardware distributors.
Handheld Laser Measuring Instrument Market Segmentation
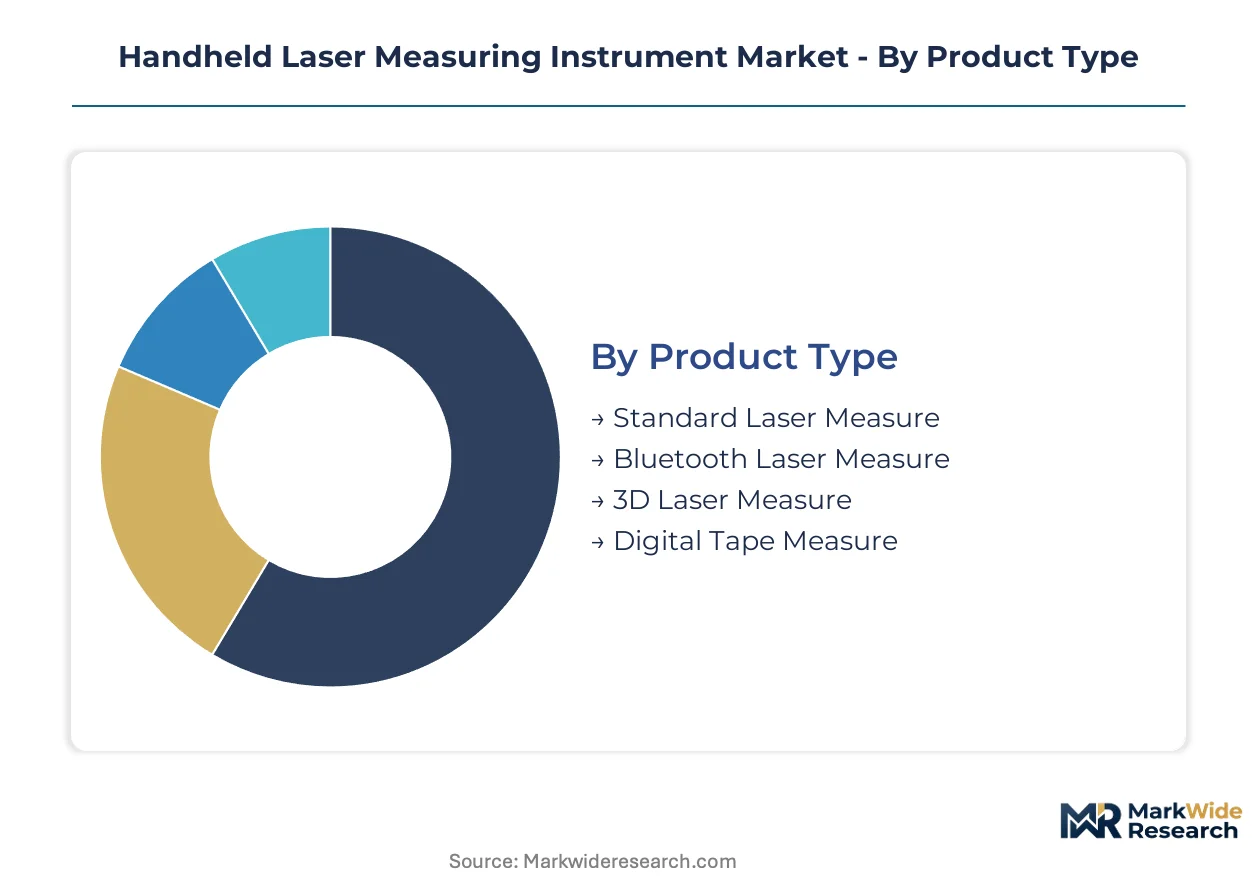
Segmentation reveals how procurement cycles vary dramatically across product tiers in the handheld laser measuring instrument market. Bluetooth-enabled and 3D-capable units compress replacement timelines through firmware-dependent obsolescence, while basic laser measures endure until physical failure. Understanding these velocity differences shapes inventory planning and service revenue models for distributors.
Product Type:
Replacement cycles diverge sharply: connected units turn over every 3-4 years as contractors chase app compatibility, while basic laser measures persist 8-10 years in field use.
- Bluetooth Laser Measure:These units integrate wireless data transmission with mobile workflow platforms for real-time project documentation. Demand clusters with commercial contractors in Germany and the United States who specify connected devices for building information modeling integration. FCC certification timelines and EU AI Act compliance documentation extend procurement lead times.
- 3D Laser Measure:Point-cloud generation capability enables spatial mapping and as-built documentation for renovation workflows. Interior designers and heritage building contractors in German urban centers drive uptake where ±1.5 mm tolerance justifies premium positioning. Machine-learning-assisted error correction routines now require algorithmic transparency disclosure under EU AI Act mandates.
- Standard Laser Measure:Basic distance, area, and volume calculation without connectivity features dominates residential construction in price-sensitive segments. ISO 16331-1 certification remains the primary purchasing filter.
- Digital Tape Measure:Hybrid mechanical-digital devices appeal to traditional contractors resisting full digital transition. Real estate appraisers and small residential builders represent core demand.
Standard laser measures dominate installed base. Bluetooth laser measures are where expansion concentrates most steeply.
Technology:
Cost tier structures separate outdoor-capable time-of-flight architectures from indoor-optimized phase shift designs, with triangulation and ultrasonic occupying economy niches.
- Time-of-Flight:Laser pulse emission and reflection timing enables 120-meter range performance for outdoor construction layout. German commercial contractors and United States infrastructure projects specify these units for earthwork and structural steel verification. Semiconductor component concentration in East Asian foundries creates supply vulnerability.
- Phase Shift:Continuous wave modulation delivers speed and power efficiency for indoor measurement tasks under 50 meters. European renovation specialists and interior design firms drive volume where rapid sequential measurements matter. Calibration technician scarcity constrains service network density for recertification.
- Triangulation:Structured light geometry suits short-range precision tasks under 10 meters. Hobbyist and light commercial segments absorb volume.
- Ultrasonic:Sound-wave reflection enables lowest-cost distance estimation with reduced accuracy. Entry-level residential applications and educational markets sustain minimal demand.
Phase shift technology commands the largest active fleet. Time-of-flight architectures are climbing the fastest as outdoor commercial construction expands.
End User:
Customer type determines specification intensity: construction demands certified accuracy and connectivity, while real estate tolerates lower precision for portability.
- Construction:General and specialty contractors specify ISO 16331-1 certified units with Bluetooth or 3D capability for dimensional verification and layout. German building renovation density and United States commercial ground-up activity sustain premium procurement. Fleet management subscriptions from direct manufacturer relationships are displacing retail purchases.
- Surveying:Geomatics professionals require survey-grade accuracy traceable to national standards. Leica Geosystems heritage and calibration documentation satisfy audit requirements for boundary and topographic work.
- Interior Design:Space planning and finish specification drives demand for compact, rapid-measurement units. Residential renovation markets in Germany and North American urban centers concentrate activity.
- Real Estate:Property measurement for listing documentation tolerates lower accuracy in exchange for pocket-sized portability. Smartphone LiDAR substitution threatens this segment most directly.
Construction commands the deepest specification requirements. Interior design is gaining share fastest as residential renovation accelerates.
Application:
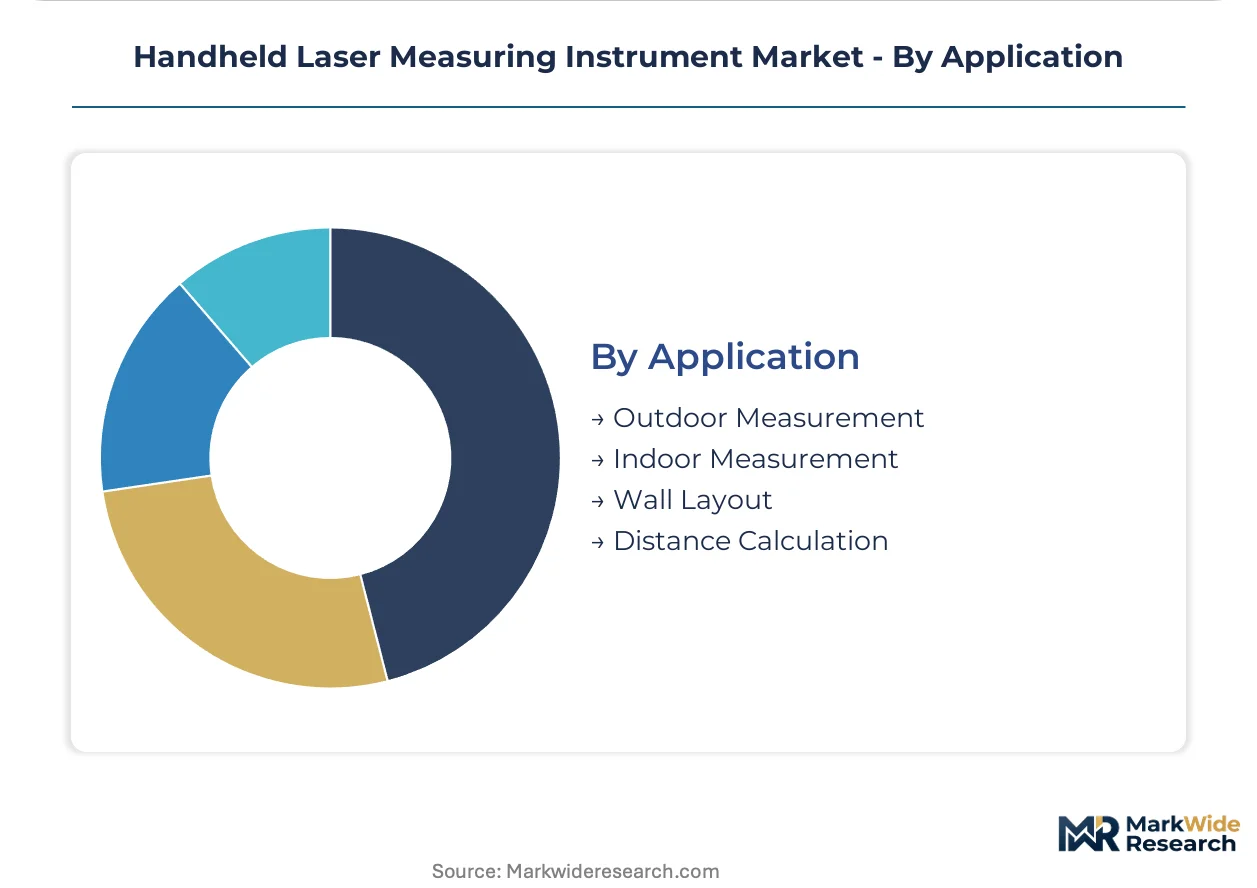
Volume concentration splits between outdoor range requirements and indoor workflow integration, with layout functions commanding premium positioning.
- Outdoor Measurement:Extended range and bright-light visibility specifications dominate infrastructure and commercial building projects. Time-of-flight technology and protective IP ratings prove mandatory. India metro rail and highway corridor projects are creating first-time professional demand.
- Indoor Measurement:Speed, compactness, and Bluetooth documentation integration prioritize renovation and interior finish workflows. Phase shift technology and mobile app compatibility shape purchasing.
- Wall Layout:Multi-line laser projection with integrated inclinometers collapses point measurement and full layout functions. Commercial ceiling grid and slab-on-grade contractors specify hybrid units to eliminate separate rotary laser purchases.
- Distance Calculation:Basic linear measurement persists in legacy analog replacement cycles. Smartphone substitution pressure concentrates here.
Indoor measurement holds the largest active installed base. Wall layout applications are expanding most quickly as hybrid units displace separate equipment purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CE marking and EU AI Act compliance requirements in Germany are tightening accuracy certification protocols across the European professional tool sector, reshaping procurement standards for connected measurement devices.
Germany
Dense building renovation activity in residential and heritage structures sustains premium product uptake where ±1.5 mm tolerance justifies higher equipment spend. REACH substance restrictions and EU AI Act algorithmic transparency mandates force professional-grade upgrades. Munich and Stuttgart manufacturing clusters anchor precision instrument production serving domestic and export markets.
United States
Commercial ground-up construction and infrastructure rehabilitation drive specification of Bluetooth-enabled units for building information modeling integration. FCC certification governs 12-16 week radio-frequency emission approval cycles for connected devices. Texas and California metropolitan construction corridors concentrate fleet management subscription adoption among large general contractors.
India
Metro rail, smart city, and highway corridor projects create first-time professional measurement tool demand among domestic contractors previously reliant on manual methods. BIS certification requirements and PLI scheme incentives shape import substitution dynamics. Mumbai and Delhi-NCR urban infrastructure build-outs absorb volume for time-of-flight outdoor measurement units.
China
Domestic construction machinery OEMs integrate laser measurement modules into equipment control systems, creating captive demand for time-of-flight sensors and laser diodes. GB standards and MIIT radio equipment regulations govern product certification. Yangtze River Delta electronics manufacturing clusters concentrate semiconductor component supply for foundry allocation.
Japan
Precision manufacturing heritage and automated construction site adoption sustain demand for phase-shift indoor measurement systems. METI industrial standards and JIS certification protocols maintain quality barriers. Nagoya and Osaka industrial corridors concentrate distribution networks serving renovation specialists and interior design firms.
Handheld Laser Measuring Instrument Market Competitive Landscape
Multi-brand power tool conglomerates and geomatics heritage specialists split the market into distinct specification tiers. Consolidation pressure concentrates around fleet management subscriptions and direct-to-contractor channels that bypass traditional hardware retail. Three archetypes dominate: integrated tool portfolio vendors, survey-grade accuracy specialists, and direct-sales fleet operators. Competitive moves center on BIM interoperability partnerships and calibration service network density expansion.
Within the integrated portfolio tier, Robert Bosch GmbH and Stanley Black & Decker exemplify multi-brand strategies leveraging power tool distribution infrastructure. Leica Geosystems occupies a position representing geomatics heritage and survey-grade accuracy credentials. Hilti Corporation anchors the direct-sales fleet management archetype, bypassing conventional retail through large construction account relationships. These three patterns illustrate how channel strategy and accuracy positioning separate competitive positions more than hardware specifications alone.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Leica Geosystems |
| Fluke Corporation |
| Hilti Corporation |
| Trimble Inc. |
| Stanley Black & Decker |
| Makita Corporation |
| Hexagon AB |
| Spectra Precision |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta electronics manufacturing clusters anchor global laser diode and time-of-flight sensor capacity, concentrating upstream pricing power among East Asian foundries while European and North American OEMs absorb downstream margin compression. This geographic asymmetry shapes three-tier pricing structures across premium, standard, and economy levels, with certification-grade units commanding substantial premiums over uncertified alternatives.
Pricing Analysis
German commercial contractors pay 40-60% premiums over Indian infrastructure buyers for identical hardware specifications, reflecting REACH compliance documentation, EU AI Act algorithmic transparency mandates, and embedded calibration traceability. Pricing stratifies across premium, standard, and economy tiers based on ISO 16331-1 certification grade and Bluetooth connectivity integration. Price erosion runs through entry-level segments as smartphone LiDAR substitution intensifies. Residential real estate appraisers exhibit highest price sensitivity, while German heritage renovation specialists tolerate premium positioning for ±1.5 mm accuracy guarantees.
Supply Chain Analysis
Supplier-financing facilities from Yangtze River Delta foundries extend 90-120 day payment terms to secure allocation priority for laser diode and sensor components. Manufacturing concentration in China, Taiwan, and South Korea creates single-source vulnerability for time-of-flight architectures. Raw material dependencies center on gallium arsenide substrates, precision optical glass, and rare-earth doped laser crystals. Tariff exposure on semiconductor components threatens margin stability for European and North American assembly operations. Distribution runs through direct-to-contractor fleet programs and specialty tool distributors, bypassing traditional hardware retail for professional-grade procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration service subscriptions and firmware-dependent replacement cycles are expanding faster than hardware unit sales, transforming this market into a service-attach opportunity where recurring revenue streams eclipse transactional equipment margins.
For Market Incumbents: Entrench calibration service network density to defend against smartphone LiDAR substitution threatening entry-level volume. Lock large construction accounts through fleet management subscriptions that bundle laser measures with power tools and dust extraction systems. Deepen backward integration into laser diode supply through captive partnerships with Yangtze River Delta foundries to secure allocation priority during capacity constraints. For New Entrants and Emerging Players: Establish a beachhead in India's metro rail and smart city infrastructure build-outs where first-time professional measurement tool demand outpaces established supply relationships. Target domestic contractors previously reliant on manual methods with simplified time-of-flight units priced below ISO 16331-1 certified alternatives. Pursue BIS certification pathways and PLI scheme incentives to neutralize import cost disadvantages against incumbent brands. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors survey-grade accuracy specialists with existing calibration traceability infrastructure capable of satisfying EU AI Act algorithmic transparency mandates. Long-term viability hinges on BIM interoperability partnerships and digital twin convergence specifications embedding hardware into design-build contracts. Watch fleet management subscription penetration rates among top-20 global general contractors as the inflection indicator for channel power rotation.| Strategic Initiative | Industry Significance |
|---|---|
| BIM Interoperability Partnership | Secures specification channels with architecture and engineering firms embedding measurement hardware into design-build contracts. |
| Calibration Service Network Expansion | Addresses technician scarcity constraining distributor service density for phase-shift and time-of-flight sensor recertification. |
| Direct-to-Contractor Fleet Program | Captures large construction accounts seeking predictable OpEx structures and maintenance bundling away from retail. |
| EU AI Act Compliance Documentation | Mandates algorithmic transparency for machine-learning-assisted error correction routines in connected devices serving European markets. |
| India BIS Certification Pathway | Enables import substitution positioning for metro rail, smart city, and highway corridor project procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with construction procurement directors, calibration service technicians, distributor inventory managers, and BIM platform engineers; and secondary validation through ISO 16331-1 certification registries, FCC equipment authorization databases, EU AI Act implementation guidance, and customs trade data for laser distance meter component flows. Bottom-up unit economics triangulated against top-down construction spending allocation models to anchor volume estimates.
Forecast inputs considered technology replacement cycles, regulatory compliance phase-in schedules, and infrastructure project pipelines across the analysis window. Segmentation dimensions modeled include product connectivity tier, measurement technology architecture, end-user specification intensity, application environment, and regional certification regime. CAGRs derived from logistic diffusion curves fitted to professional tool adoption patterns and smartphone substitution elasticity estimates for entry-level segments.
Sensitivities concentrate around semiconductor foundry allocation decisions, EU AI Act enforcement timing, and India infrastructure disbursement velocity. Forecasts reflect documented assumptions on technology substitution thresholds and regulatory compliance cost pass-through rates. Macroeconomic construction cycle downturn, accelerated smartphone LiDAR performance improvement, or East Asian supply chain disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Atomic Force Microscopes (AFM) Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Laser Scanning Microscopes Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Laser Probe Market