
 Brazil Telecom Tower Market | 2026-2036
Brazil Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Telecom Tower Market Insights
The Brazil telecom tower landscape is restructuring around a sharp split between premium 5G-ready steel structures and legacy commodity towers serving rural 4G networks. American Tower Corporation leverages its nationwide footprint to dominate high-density urban corridors where fiber backhaul integration commands premium lease rates. IHS Towers anchors its position through specialized monopole designs that accelerate site permitting in environmentally restricted zones. V.tal competes by controlling strategic co-location hubs that aggregate multiple mobile operators on single structures.
A telecom tower is a steel or concrete structure engineered to support antennas, transmission equipment, and power systems at heights typically ranging from 30 to 120 meters, designed to withstand wind loads exceeding 150 km/h and seismic stresses per Brazilian technical standards. Its primary commercial purpose is to host wireless communication infrastructure for mobile operators, internet service providers, and private network operators seeking geographic coverage. Monopole installations lead in urban deployments where zoning restrictions limit ground footprints, while lattice structures sustain demand in rural expanses where cost-per-meter and load-bearing capacity outweigh aesthetic constraints. Service-type revenue pools concentrate in upgradation and maintenance as operators retrofit existing sites for 5G massive MIMO configurations rather than greenfield construction.
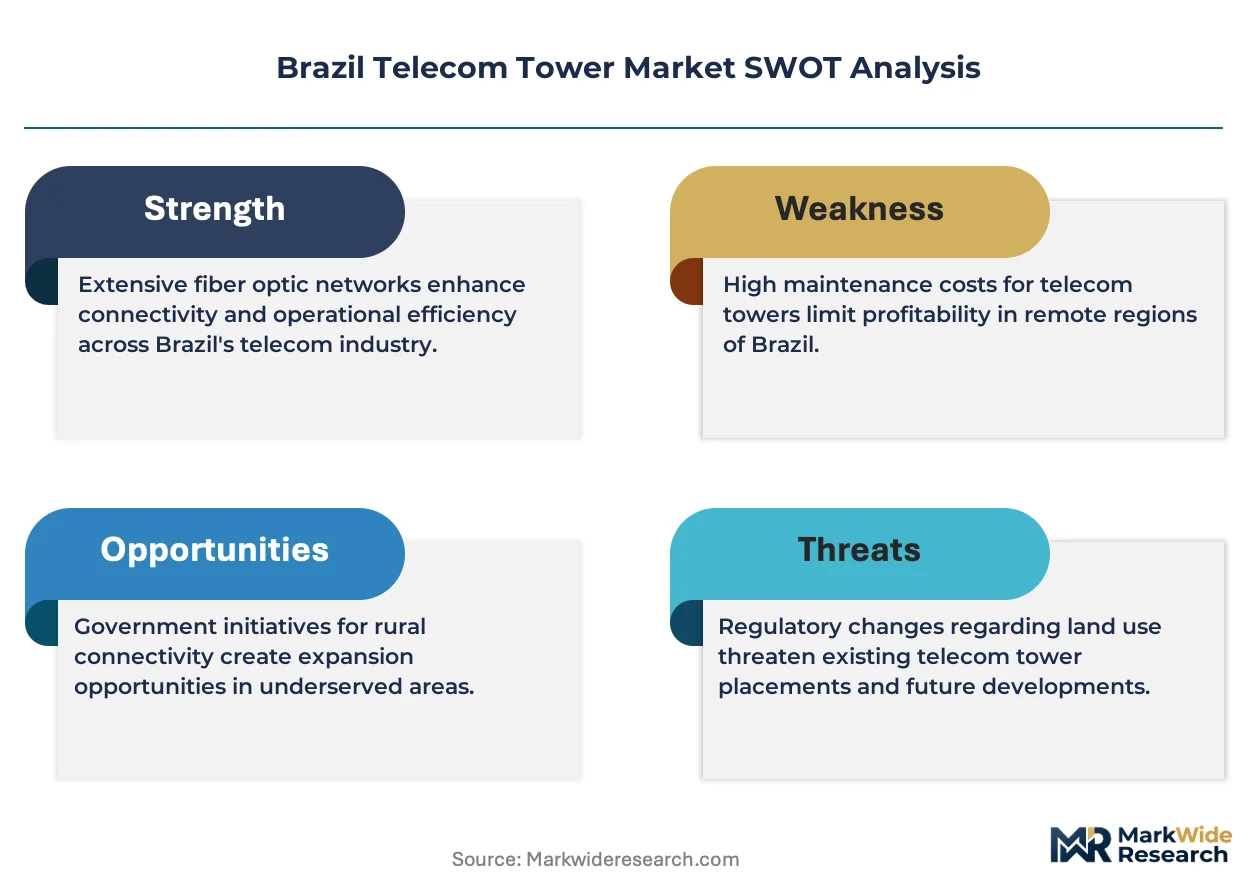
ANATEL's infrastructure sharing mandates and electromagnetic field exposure limits shape tower design standards and co-location economics across Brazil. The national telecom regulator enforces universal service obligations that direct investment toward underserved northern and northeastern states, while municipal zoning codes in São Paulo and Rio de Janeiro impose height and setback restrictions that favor monopole over guyed structures. Stakeholders must monitor ANATEL's pending spectrum reallocation proceedings and evolving municipal antenna laws to anticipate site densification requirements and permitting timeline shifts.
Market Dynamics
The Brazil telecom tower market is reconfiguring around ANATEL's infrastructure sharing mandates, which force mobile operators to consolidate site footprints and accelerate co-location economics across metropolitan corridors.
Growth Catalysts
- 5G spectrum deployment:ANATEL's 3.5 GHz and 26 GHz auction conditions require densified site grids in São Paulo and Rio de Janeiro, pulling tower demand toward urban infill locations.
- Universal service obligations:Northern and northeastern state mandates redirect capital toward underserved municipalities, expanding addressable geography for lattice and guyed mast installations.
- Fiber backhaul integration:Mobile operators prioritize tower assets with existing fiber proximity, concentrating lease premiums on sites meeting sub-100-meter latency requirements.
Market Restraints
- Steel price volatility:Galvanized structural steel input costs fluctuate with global commodity cycles, compressing margin predictability for domestic tower fabricators.
- Municipal zoning friction:São Paulo and Rio de Janeiro height restrictions and setback codes delay permitting timelines by months, elevating carrying costs for speculative site development.
- Electromagnetic field exposure limits:ANATEL's RF emission thresholds constrain antenna placement density per structure, capping revenue-per-tower potential in high-traffic zones.
Strategic Opportunities
- Amazon basin coverage gaps:Pará and Amazonas states present greenfield deployment potential where satellite backhaul hybridization can substitute for absent fiber infrastructure.
- Edge computing co-location:Tower operators can lease equipment shelter space to cloud providers seeking sub-10 millisecond latency positioning for industrial IoT applications.
- Renewable energy retrofit:Solar-diesel hybrid power systems align with ANATEL's sustainability guidelines while reducing opex in off-grid northern installations.
Industry Challenges
- Structural engineering talent scarcity:Specialized seismic and wind-load certification for Brazilian technical standards limits qualified design firm capacity, extending project timelines.
- Legacy 2G/3G decommissioning coordination:Operators face complex antenna swap logistics while maintaining service continuity, requiring staged equipment removal protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Telecom Tower Market |
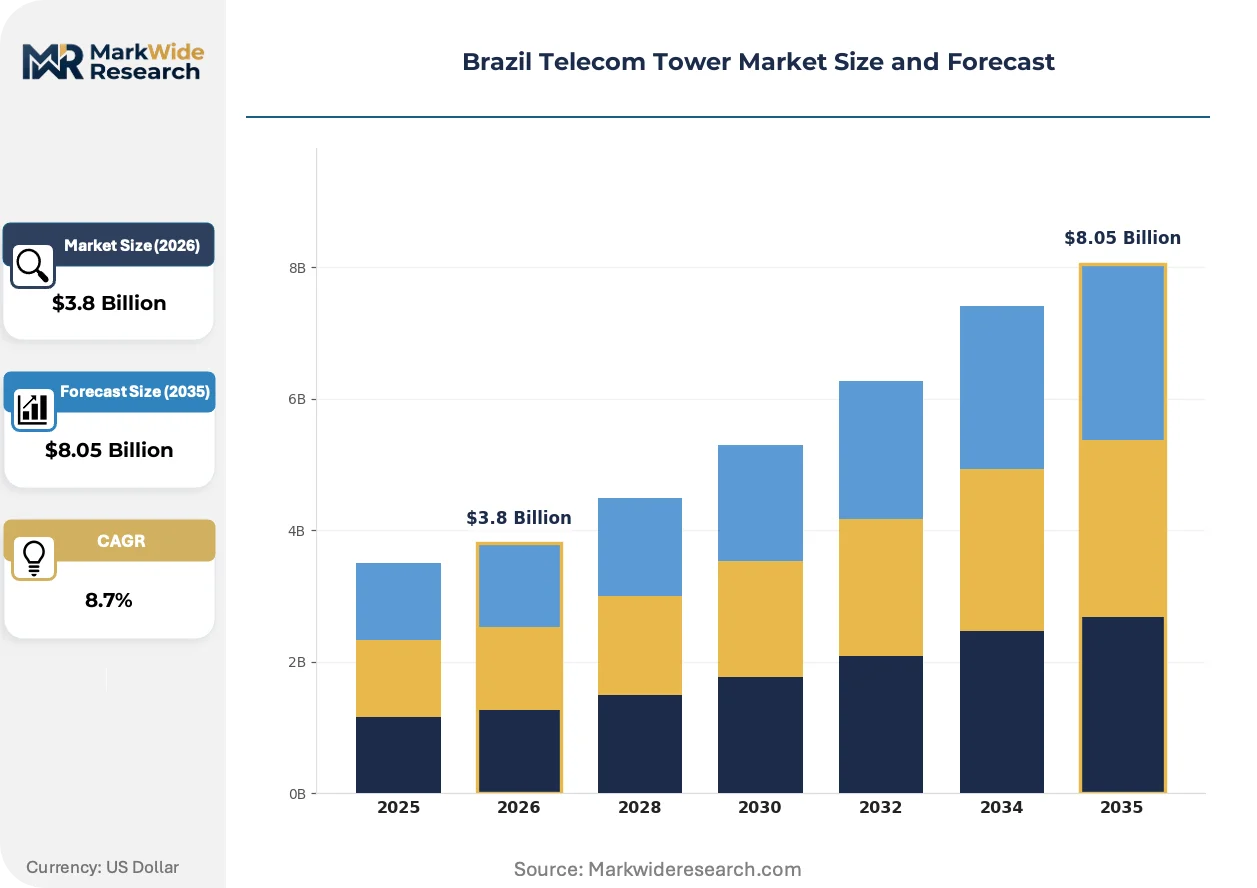
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice, Guyed, Coaxial Service Type: Maintenance, Installation, Design, Upgradation End User: Mobile Operators, ISPs, Private Networks, Enterprises Technology: 4G, 5G, LTE, Wi-Fi |
| Companies Covered | American Tower Corporation, SBA Communications, IHS Towers, V.tal, Highline do Brasil, Brazil Tower Company, Brazil Infrastructure Company, QMC Telecom, Telxius, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Telecom Tower Market Trends and Innovations
Tower architecture is pivoting toward multi-tenant flexibility and rapid deployment modularity as 5G site densification compresses installation windows and elevates co-location premiums.
Massive MIMO antenna arrays are converging with existing monopole structures through reinforced foundation retrofits rather than greenfield construction. Mobile operators in São Paulo's metropolitan belt are accelerating these upgrades to meet 3.5 GHz propagation requirements. The structural reinforcement approach is converging with modular shelter designs that slash site preparation from weeks to days, compressing time-to-revenue for tower owners.
ANATEL's pending electromagnetic field reclassification proceedings are tightening RF exposure thresholds near schools and hospitals. Tower operators must relocate or reorient antennas in affected zones, elevating structural modification costs. The regulatory pressure is concentrating co-location demand on compliant structures in São Paulo and Rio de Janeiro where pre-certified sites command lease premiums.
Mobile network operators are unbundling tower maintenance from capital leases, shifting toward performance-based service agreements with uptime guarantees. Tower companies respond by consolidating regional maintenance fleets and predictive analytics platforms. The operational model change is most visible in Minas Gerais and Paraná states where operator procurement teams centralize vendor selection through outcome-based contracting frameworks.
Brazil Telecom Tower Market Segmentation
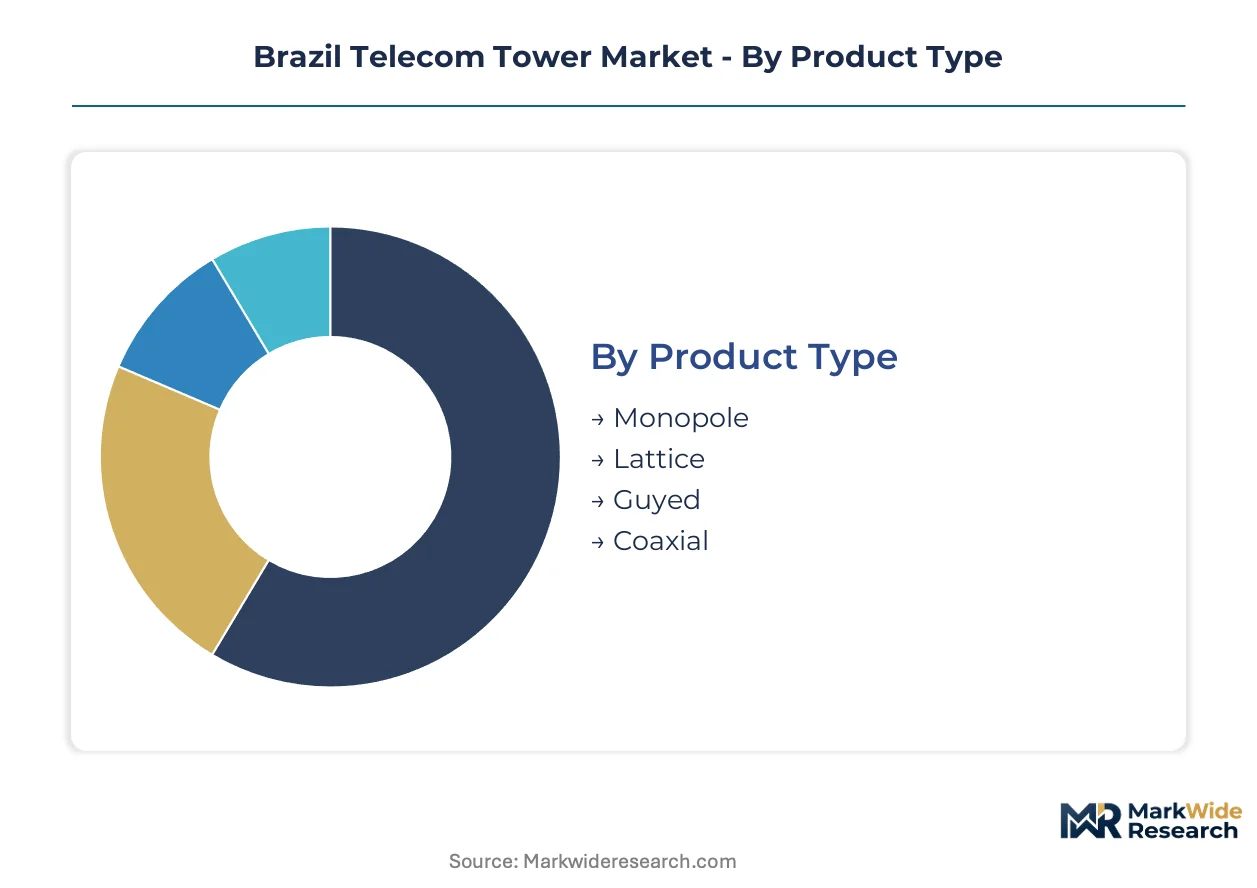
Brazil's tower market segments around infrastructure lifecycle stages rather than static product categories. Upgrade cycles for 5G densification and legacy network decommissioning create overlapping demand patterns across product, service, and technology dimensions.
Product Type:
Replacement cycles favor structures that minimize permitting friction in São Paulo and Rio de Janeiro's constrained urban corridors.
- Monopole:Single-stem steel or concrete structures with minimal ground footprints. São Paulo's municipal zoning codes restrict tower base diameters, concentrating monopole demand in metropolitan infill zones where height restrictions apply.
- Lattice:Triangular or square truss configurations built from angled steel members. Northern and northeastern states under ANATEL universal service obligations deploy lattice structures for cost efficiency across rural expanses where load-bearing capacity outweighs aesthetic constraints.
- Guyed:Masts stabilized by tensioned cable arrays anchored at ground level. These structures serve temporary coverage requirements in Amazon basin deployment scenarios where permanent foundations prove impractical.
- Coaxial:Integrated antenna-support systems with embedded transmission lines. Coaxial configurations address specialized industrial IoT applications requiring shielded signal paths in electromagnetic-sensitive zones.
Lattice sits at the top of the volume ranking, with monopole climbing the fastest.
Service Type:
Margin concentration follows the shift from capital-heavy greenfield construction to recurring operational expenditure models.
- Maintenance:Predictive upkeep protocols and emergency repair services. Mobile operators in Minas Gerais and Paraná states unbundle maintenance from capital leases, driving outcome-based contracting with uptime guarantees.
- Installation:Site preparation, foundation work, and structural erection. ANATEL's infrastructure sharing mandates compress installation windows as multiple operators coordinate simultaneous equipment deployment on single structures.
- Design:Seismic and wind-load engineering per Brazilian technical standards. Specialized certification requirements limit qualified design firm capacity, extending project timelines for complex retrofit scenarios.
- Upgradation:Structural reinforcement and equipment swaps for 5G migration. Massive MIMO antenna convergence with existing monopoles through foundation retrofits dominates São Paulo's metropolitan belt.
Upgradation commands the highest margin tier, with maintenance expanding most quickly.
End User:
Customer concentration patterns reflect Brazil's telecommunications ownership structure and regulatory access rules.
- Mobile Operators:Tier-1 and regional carriers leasing antenna space. These customers drive co-location economics through ANATEL-mandated infrastructure sharing, consolidating multiple tenants per structure.
- ISPs:Fixed wireless access providers seeking geographic coverage. ISPs prioritize tower assets with existing fiber proximity, concentrating lease premiums on sites meeting sub-100-meter latency requirements.
- Private Networks:Industrial and logistics operators deploying captive infrastructure. Mining and agribusiness consortia in Pará and Mato Grosso states commission dedicated structures for remote operational connectivity.
- Enterprises:Corporate campus and facility-specific installations. Edge computing co-location demand from cloud providers seeking sub-10 millisecond latency positioning reshapes enterprise contracting frameworks.
Mobile operators anchor the revenue base, with private networks gaining share fastest.
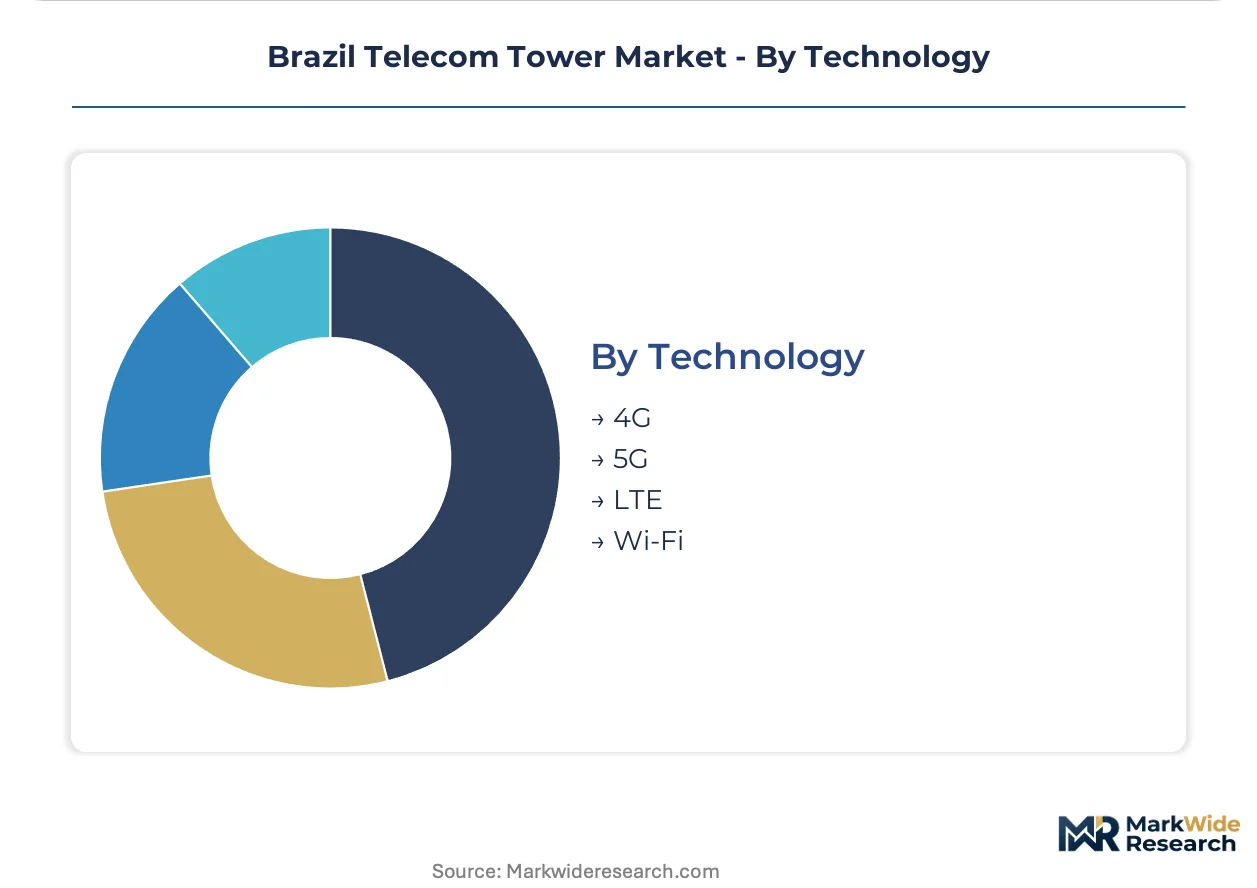
Technology:
Technology segmentation tracks spectrum allocation decisions and propagation physics across Brazil's varied topography.
- 4G:Legacy LTE infrastructure serving established coverage footprints. Rural networks in northeastern states sustain 4G lattice demand as universal service obligations prioritize basic connectivity over next-generation upgrades.
- 5G:3.5 GHz and 26 GHz deployments requiring densified site grids. ANATEL's auction conditions pull tower demand toward urban infill locations in São Paulo and Rio de Janeiro where propagation characteristics mandate shorter inter-site distances.
- LTE:Evolved packet core systems bridging 4G and 5G architectures. LTE equipment sustains demand in transition markets where operators stage antenna swaps to maintain service continuity.
- Wi-Fi:Unlicensed spectrum access points for hotspot and enterprise applications. Wi-Fi backhaul integration concentrates in co-location hubs where multiple wireless technologies converge on single structures.
4G structures still dominate the installed base, with 5G deployment showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural engineering talent clusters in São Paulo's metropolitan corridor anchor Brazil's tower design capacity. Specialized seismic certification expertise concentrates in southeastern engineering consultancies serving ANATEL's technical standards. This workforce distribution shapes where complex 5G retrofit projects secure qualified design partners.
São Paulo
Metropolitan zoning restrictions and fiber backhaul density drive monopole demand across São Paulo's urban infill zones. ANATEL's 3.5 GHz propagation requirements compress site spacing below 500 meters in central business districts. American Tower Corporation and V.tal dominate co-location hubs in Pinheiros and Berrini corridor where lease premiums attach to sub-100-meter fiber latency.
Rio de Janeiro
Coastal topography and municipal height codes elevate engineering complexity for tower deployments across Rio's metropolitan belt. ANATEL's electromagnetic field exposure limits tighten near schools in Barra da Tijuca and Recreio zones. IHS Towers anchors positions through specialized monopole designs that accelerate permitting in environmentally restricted coastal districts.
Minas Gerais
Industrial IoT demand from mining and logistics operators pulls private network tower installations toward Belo Horizonte's peripheral industrial zones. Outcome-based maintenance contracting concentrates procurement decisions in state capital engineering departments. Regional maintenance fleets consolidate around predictive analytics platforms serving multi-tenant uptime guarantees.
Pará
Amazon basin coverage gaps and absent fiber infrastructure position satellite backhaul hybridization as the dominant deployment model across Pará's remote municipalities. ANATEL's universal service obligations redirect capital toward lattice structures in rural expanses where load-bearing capacity outweighs aesthetic constraints. Solar-diesel hybrid power systems reduce operational expenditure in off-grid northern installations.
Rio Grande do Sul
Legacy 2G/3G decommissioning coordination creates staged antenna swap logistics across Porto Alegre's established coverage footprints. Wind-load engineering per Brazilian technical standards limits qualified design firm capacity for complex retrofit scenarios. Regional operators prioritize upgradation services over greenfield construction as 5G migration timelines compress.
Brazil Telecom Tower Market Competitive Landscape
Capital-heavy tower owners compete with asset-light site management specialists across Brazil's infrastructure layer. The market structure concentrates around three national-scale operators controlling metropolitan co-location economics while mid-tier regional fabricators serve universal service obligation zones. Strategic archetypes separate nationwide footprint holders from monopole engineering specialists and from fiber-integrated hub operators. Dominant competitive moves include portfolio densification through municipal permitting acceleration and vertical integration into power system retrofits.
Within the nationwide footprint tier, American Tower Corporation exemplifies scale-driven positioning across high-density urban corridors. IHS Towers and V.tal occupy complementary positions through differentiated engineering approaches to site acquisition constraints. These three anchors represent the structural separation between premium metropolitan lease economics and cost-optimized rural deployment models.
| Leading Market Players |
|---|
| American Tower Corporation |
| SBA Communications |
| IHS Towers |
| V.tal |
| Highline do Brasil |
| Brazil Tower Company |
| Brazil Infrastructure Company |
| QMC Telecom |
| Telxius |
| Others |
Pricing and Supply Chain Analysis
Premium fiber-integrated monopoles in São Paulo and Rio de Janeiro's metropolitan corridors command lease rate multiples over commodity lattice structures serving northern universal service zones, with this bifurcation anchoring both procurement contract structures and steel sourcing strategies across Brazilian tower fabricators. ANATEL's infrastructure sharing mandates compress co-location pricing in high-density hubs while elevating site acquisition premiums, feeding back into concentrated supplier relationships for galvanized structural steel and seismic-certified engineering services.
Pricing Analysis
Bundled capital leases with embedded maintenance are unbundling into separate performance-based service agreements across Minas Gerais and Paraná states. Price differentiation separates fiber-proximate urban sites with sub-100-meter latency guarantees from satellite-dependent Amazon basin installations. Pricing pressure intensifies in legacy 4G lattice segments as mobile operators stage 2G/3G decommissioning, while 5G-ready monopole retrofits sustain premium tiers. Tier-1 mobile operators exhibit lowest price sensitivity due to co-location economics, whereas regional ISPs and private mining networks negotiate hardest on per-site rates.
Supply Chain Analysis
Dual-sourcing requirements from major tower operators mandate qualified fabricator relationships in both southeastern Brazil and imported steel channels from China and South Korea. Galvanized structural steel, reinforced concrete foundations, and modular equipment shelters constitute critical input dependencies. Supply chain risk concentrates in commodity price volatility for zinc-coated steel driven by global mining cycles. Distribution runs through regional fabrication hubs serving ANATEL-certified installation contractors, with final-mile logistics managed by specialized heavy-lift operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in upgradation services and fiber-integrated site densification, with operational expenditure shifts from capital-heavy greenfield construction creating recurring revenue pools for maintenance and predictive analytics platforms.
For Market Incumbents: Anchor market position through accelerated permitting capabilities in São Paulo and Rio de Janeiro's zoning-constrained corridors, where municipal height codes create structural moats against speculative entrants. Deepen backward integration into solar-diesel hybrid power systems to capture ANATEL sustainability guideline premiums. Defend against regional mid-tier fabricators by consolidating maintenance fleet coverage across multi-tenant uptime guarantee contracts. For New Entrants and Emerging Players: Launch via specialized monopole engineering partnerships targeting environmentally restricted coastal districts in Rio de Janeiro where IHS Towers has demonstrated permitting acceleration models. White-space availability concentrates in Amazon basin satellite backhaul hybridization for Pará and Amazonas states, plus edge computing co-location shelters for industrial IoT latency requirements. Prioritize outcome-based maintenance contracting to bypass capital-intensive tower ownership barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where structural engineering talent scarcity limits qualified design firm capacity for complex 5G retrofit scenarios. Long-term viability favors asset-light site management specialists with fiber-integrated hub positions over pure-play steel fabricators exposed to commodity cycles. Acquisition targets should demonstrate municipal permitting relationships in São Paulo's metropolitan belt. Monitor ANATEL's pending electromagnetic field reclassification proceedings as inflection signal for structural modification cost escalations.| Strategic Initiative | Industry Significance |
|---|---|
| Permitting Acceleration Partnerships | Municipal zoning relationships in São Paulo compress site acquisition timelines below speculative development windows. |
| Fiber Backhaul Integration | Sub-100-meter latency positioning commands lease premiums from mobile operators and cloud providers. |
| Renewable Energy Retrofit | Solar-diesel hybrid systems align with ANATEL sustainability guidelines while reducing northern state opex. |
| Predictive Maintenance Platform | Outcome-based contracting with uptime guarantees consolidates regional fleet economics in Minas Gerais. |
| Edge Computing Co-location | Equipment shelter leasing to cloud providers captures industrial IoT demand from mining and logistics operators. |
Research Methodology
Direct dialogue with tower engineering directors, mobile operator procurement leads, ANATEL regulatory affairs specialists, and municipal zoning officers grounded qualitative findings in operational reality. Secondary validation drew from ANATEL spectrum auction documentation, Brazilian technical standards for seismic and wind-load certification, municipal antenna law filings in São Paulo and Rio de Janeiro, and mobile operator capex disclosure patterns. Bottom-up site-level economics triangulated against top-down market sizing from infrastructure investment flows.
Top-down macroeconomic anchors and bottom-up site-by-site revenue modeling converged across the projection horizon. Segmentation dimensions included product type (monopole, lattice, guyed, coaxial), service type (maintenance, installation, design, upgradation), end user (mobile operators, ISPs, private networks, enterprises), and technology generation (4G, 5G, LTE, Wi-Fi). CAGRs derived from installed base replacement cycles, ANATEL-mandated coverage obligations, and mobile operator densification timelines for 3.5 GHz propagation requirements.
Several conditions sit outside the modeled scope, including potential ANATEL spectrum reallocation proceedings, municipal zoning code amendments, and steel commodity price shocks beyond historical volatility bands. Forecasts reflect documented assumptions about infrastructure sharing mandate enforcement and universal service obligation funding continuity. Deviation in electromagnetic field exposure threshold tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Mexico Telecom Tower Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Canada Telecom Towers Market