
 Synthetic and Bio-Based Adipic Acid Market | 2026-2036
Synthetic and Bio-Based Adipic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Bio-Based Adipic Acid Market Analytics
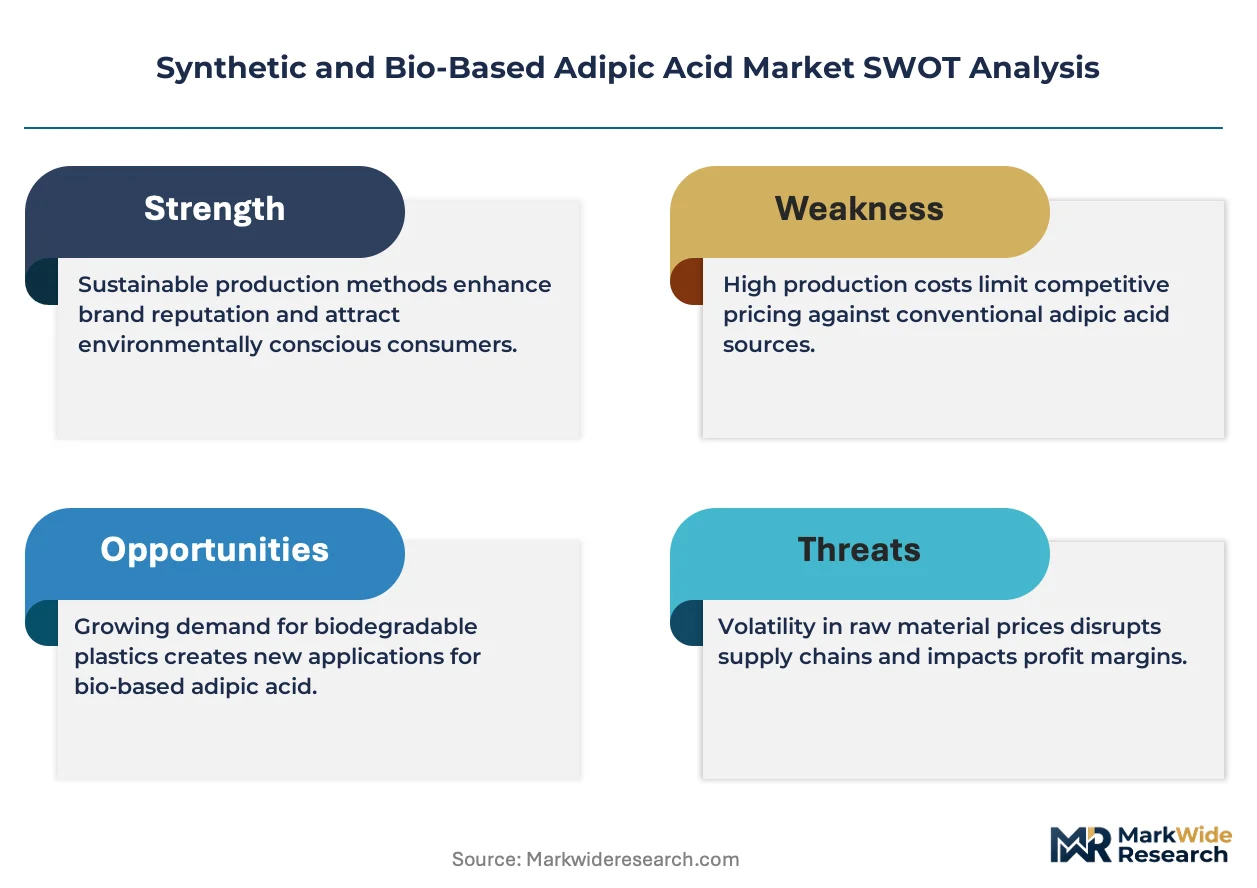
ISO 9001 certification is reorganizing supplier qualification among adipic acid manufacturers seeking automotive Tier-1 status. BASF SE leverages its Ludwigshafen integrated site to sustain captive cyclohexane supply. Ascend Performance Materials anchors North American capacity with its Chocolate Bayou complex. Solvay differentiates through specialty-grade offerings for European coating formulators.
Synthetic and bio-based adipic acid denotes a six-carbon dicarboxylic acid produced via cyclohexane oxidation or microbial fermentation of renewable feedstocks, serving primarily as the monomeric precursor to nylon-6,6 polyamide. Synthetic adipic acid dominates volume but carries elevated carbon intensity from nitrous oxide byproduct emissions. Bio-based adipic acid occupies the fastest-expanding margin pool as consumer goods brands enforce Scope 3 reduction targets. Polymer production leads application share, while coatings command premium pricing for high-purity grades.
EPA regulations under the Clean Air Act constrain nitrous oxide emissions from conventional adipic acid plants, while REACH registration requirements in Europe govern chemical safety documentation for imported volumes. The EU Green Deal's industrial decarbonization pathway pressures European producers to certify lower-carbon process routes. Stakeholders must monitor fermentation yield improvements and offtake agreements from renewable chemical platforms to calibrate capital allocation between synthetic retrofit and greenfield bio-based assets.
Market Dynamics
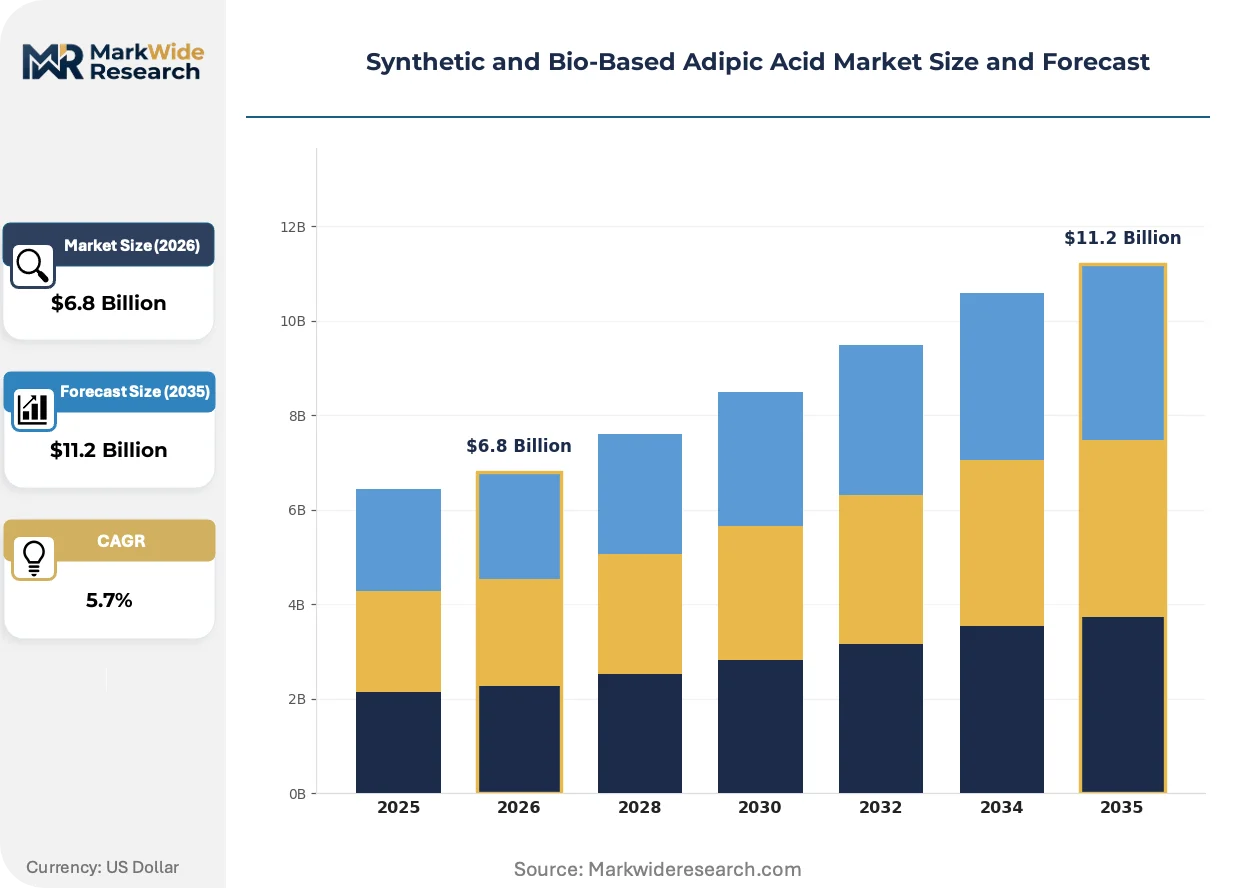
The automotive sector's lightweighting imperative is compressing nylon-6,6 demand into higher-purity adipic acid grades, while EPA nitrous oxide enforcement and EU Green Deal carbon-accounting rules bifurcate investment between synthetic retrofit and bio-based greenfield capacity.
Growth Catalysts
- Automotive Lightweighting Mandates:CAFE standards in the United States and EU CO2 fleet targets are expanding engineered polyamide consumption in under-the-hood components and structural parts.
- REACH Chemical Safety Documentation:ECHA registration requirements for imported adipic acid volumes are consolidating qualified supplier pools among European compounders seeking compliant feedstock security.
- Microbial Fermentation Yield Gains:Continuous processing advances in bio-based routes are narrowing the cost gap with cyclohexane oxidation for C6 dicarboxylic acid production.
Market Restraints
- Cyclohexane Price Volatility:Benzene derivative cost swings transmit directly into synthetic adipic acid variable margins, compressing profitability during crude oil spikes.
- Chinese Capacity Concentration:Shandong and Jiangsu province production clusters control substantial export volume, creating single-source dependency risk for European and North American formulators.
- Nitrous Oxide Abatement Capital Burden:EPA Clean Air Act compliance requires catalytic destruction unit installation at legacy oxidation plants, elevating fixed costs for incumbent synthetic producers.
Strategic Opportunities
- Indian Specialty Chemical Expansion:PLI scheme incentives for renewable chemical manufacturing are attracting fermentation-based adipic acid pilot investments targeting domestic nylon intermediates.
- Coatings High-Purity Premium Segment:European automotive refinish and industrial coating formulators are certifying specialty-grade supply chains for color consistency and weathering performance.
- Scope 3 Emissions Accounting Convergence:Consumer goods brands enforcing science-based targets are creating offtake premiums for bio-based adipic acid with certified lifecycle carbon footprints.
Industry Challenges
- Fermentation Scale-Up Engineering Talent Scarcity:Industrial bioprocessing expertise for C6 diacid production remains concentrated in academic and startup ecosystems, constraining rapid capacity expansion.
- ISO 9001 Automotive Tier-1 Certification Timelines:Supplier qualification cycles extending 18-24 months are delaying market entry for new bio-based entrants seeking nylon-6,6 polymer partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio-Based Adipic Acid Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Adipic Acid, Bio-Based Adipic Acid, Blended Adipic Acid, Modified Adipic Acid Application: Polymer Production, Coatings, Adhesives, Plasticizers End Use Industry: Automotive, Textile, Construction, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Ascend Performance Materials, Lanxess AG, BASF SE, Radici, Domo Chemicals, Asahi Kasei Corporation, Solvay, Rhodia, Invista, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio-Based Adipic Acid Market Evolving Landscape
Process chemistry and biological manufacturing routes are diverging sharply as carbon accounting penetrates procurement specifications, reshaping how adipic acid capacity earns capital allocation across synthetic retrofit and fermentation greenfield investments.
Enzymatic oxidation pathways utilizing genetically modified yeast strains are supplanting traditional cyclohexane-to-KA oil routes in pilot-scale deployments. Specialty chemical investors are funding 10,000-tonne demonstration plants in the Netherlands and California. This biological conversion is compressing the capital intensity gap between petroleum-derived and renewable feedstock routes.
EU Green Deal industrial decarbonization benchmarks are mandating verified carbon intensity disclosures for imported chemical intermediates. ECHA is harmonizing lifecycle assessment methodologies with REACH dossier requirements. European coating and polymer compounders are now requiring mass-balance certificates from adipic acid suppliers to maintain formulation registration compliance.
Automotive Tier-1 procurement teams are consolidating qualified supplier lists from twelve-vendor panels to four-vendor strategic partnerships. Long-term offtake agreements with fixed volume tiers and indexed pricing are displacing spot market purchasing for nylon-6,6 resin production. This concentration is most visible in Germany's Baden-Württemberg automotive cluster and Michigan's southeast Michigan supplier corridor.
Synthetic and Bio-Based Adipic Acid Market Segmentation
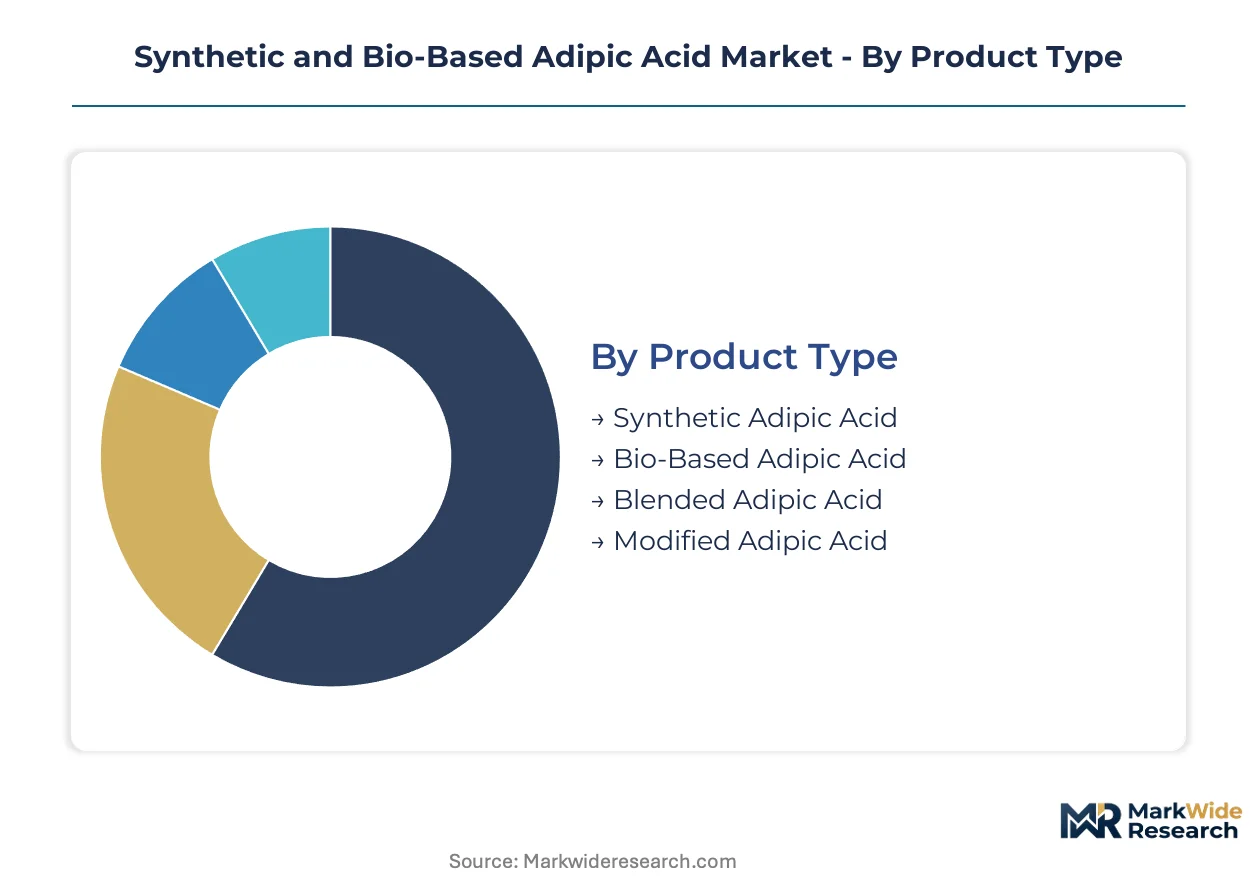
Adipic acid segmentation separates carbon-intensive legacy supply from emerging bio-based alternatives, with each category carrying distinct regulatory footprints and customer qualification requirements. Procurement teams weight purity grades, certification status, and Scope 3 emissions differently across end-use applications.
Product Type:
Synthetic routes dominate domestic supply in benzene-abundant regions, while bio-based production clusters near fermentation expertise and renewable feedstock infrastructure.
- Synthetic Adipic Acid:Cyclohexane oxidation yields high-purity C6 dicarboxylic acid with established ASTM specifications. Automotive nylon-6,6 polymerization in Germany, China, and the United States consumes the majority of volume, though EPA nitrous oxide abatement costs are compressing margins at legacy plants.
- Bio-Based Adipic Acid:Microbial fermentation of sugar-derived feedstocks produces chemically identical adipic acid with certified lower carbon intensity. Consumer goods brands in California and the Netherlands are securing offtake agreements to meet science-based emissions targets, with pilot capacity scaling in the Netherlands.
- Blended Adipic Acid:Mass-balance certified mixtures combining synthetic and fermentation-derived material serve coating formulators seeking incremental carbon reductions without full bio-based price premiums.
- Modified Adipic Acid:Esterified or branched derivatives for specialty plasticizer applications command formulation-specific qualification cycles from European PVC compounders.
Synthetic adipic acid holds the largest share; momentum sits with bio-based adipic acid as fermentation yields improve.
Application:
Volume concentration varies sharply by purity requirement, with polymer-grade specifications tolerating tighter variance bands than coating applications.
- Polymer Production:Nylon-6,6 polyamide precursor demand absorbs the majority of adipic acid volume. Automotive under-the-hood components in Michigan and Baden-Württemberg drive specification tightening for thermal stability.
- Coatings:High-purity grades for automotive refinish and industrial formulations command premium pricing. Color consistency requirements from German and Japanese OEMs are certifying specialty supply chains with extended qualification timelines.
- Adhesives:Polyurethane systems for construction and footwear applications utilize standard-grade material with less stringent moisture specifications.
- Plasticizers:Ester derivatives for flexible PVC compete with alternative phthalate and non-phthalate chemistries on cost-performance positioning.
Polymer production commands the volume base; coatings deliver the steepest margin expansion trajectory.
End Use Industry:
Customer procurement patterns diverge between specification-driven automotive qualification and price-sensitive textile sourcing.
- Automotive:Tier-1 supplier consolidation is compressing qualified vendor lists for nylon-6,6 resin feedstock. CAFE standards and EU CO2 fleet regulations are expanding engineered polyamide content in powertrain and structural applications.
- Textile:Carpet fiber and industrial yarn production in China and the southeastern United States sources standard-grade adipic acid through distributor networks with limited certification requirements.
- Construction:Geosynthetics and insulation foams utilize adipic acid-derived polyurethanes with performance specifications governed by ASTM and EN standards.
- Consumer Goods:Appliance housings and sporting equipment drive modest volumes with intermittent demand patterns tied to retail inventory cycles.
Automotive end-use holds the largest share; momentum sits with consumer goods as brand sustainability commitments harden.
Distribution Channel:
Channel selection correlates with customer scale and specification complexity, with direct relationships dominating certified polymer supply.
- Direct Sales:Long-term offtake agreements with fixed volume tiers and indexed pricing serve automotive and major polymer compounders. BASF SE and Ascend Performance Materials anchor direct relationships with qualified Tier-1 suppliers.
- Distributors:Regional chemical distributors manage inventory and technical service for mid-sized coating and adhesive formulators seeking smaller lot sizes.
- Wholesalers:Commodity-grade material for textile and construction applications flows through wholesale channels with limited technical support.
- Online Retail:Laboratory and pilot-scale quantities for R&D procurement are migrating to specialized chemical marketplaces with certificate of analysis documentation.
Direct sales holds the largest share; momentum sits with distributors as bio-based entrants seek market access without dedicated sales infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive compounders and coating formulators concentrate procurement in three manufacturing corridors: Germany's Baden-Württemberg cluster, China's Shandong-Jiangsu belt, and the US Great Lakes automotive corridor. Each geography carries distinct regulatory exposure and feedstock access profiles.
United States
CAFE standards and EPA nitrous oxide enforcement under the Clean Air Act are tightening emission controls at cyclohexane oxidation plants. Michigan's southeast Michigan supplier corridor anchors nylon-6,6 resin production for Detroit automakers. Ascend Performance Materials operates its Chocolate Bayou complex to secure captive feedstock supply.
Germany
EU Green Deal industrial decarbonization benchmarks and ECHA REACH registration requirements are consolidating qualified supplier pools among European compounders. BASF SE leverages its Ludwigshafen integrated site for cyclohexane supply security. Baden-Württemberg's automotive cluster drives specification tightening for thermal stability grades.
China
Dual carbon goals and provincial environmental inspections are pressuring Shandong and Jiangsu province production clusters to abate nitrous oxide emissions. These regions control substantial export volume for engineered nylon intermediates. Domestic automotive lightweighting programs are expanding local adipic acid consumption.
India
PLI scheme incentives for renewable chemical manufacturing are attracting fermentation-based adipic acid pilot investments. The country's national chemical regulator is harmonizing safety documentation with REACH-equivalent standards. Maharashtra and Gujarat industrial corridors are emerging as specialty chemical expansion zones.
Netherlands
ECHA lifecycle assessment harmonization with REACH dossier requirements is mandating verified carbon intensity disclosures for imported intermediates. Dutch coating formulators are certifying specialty-grade supply chains for color consistency. Pilot-scale bio-based demonstration plants are scaling near Rotterdam's renewable feedstock infrastructure.
Synthetic and Bio-Based Adipic Acid Market Competitive Landscape
Player mix skews toward integrated petrochemical majors with captive cyclohexane supply and fermentation-based specialists seeking automotive Tier-1 qualification. Market structure consolidates around three archetypes: benzene-integrated oxidation operators, bio-based platform developers, and specialty-grade refiners serving coating formulators. Dominant competitive moves include long-term offtake agreements with indexed pricing and ISO 9001 automotive supplier certification campaigns.
Within the integrated petrochemical tier, BASF SE and Ascend Performance Materials exemplify backward-integrated operators securing feedstock control through captive cyclohexane production. Solvay occupies a position among specialty-grade refiners differentiating through high-purity offerings. Lanxess AG sits within the European qualified supplier pool serving REACH-compliant compounders.
| Leading Market Players |
|---|
| Ascend Performance Materials |
| Lanxess AG |
| BASF SE |
| Radici |
| Domo Chemicals |
| Asahi Kasei Corporation |
| Solvay |
| Rhodia |
| Invista |
| Others |
Value Network & Pricing Analysis
Fermentation-derived adipic acid substitution for cyclohexane-oxidation material is redrawing feedstock procurement geographies and compressing the cost premium between petroleum-based and bio-based grades. European coating formulators and California-based consumer goods brands are indexing contract renewals to mass-balance certificates, forcing legacy oxidation operators to absorb nitrous oxide abatement costs without passing full tariffs downstream.
Pricing Analysis
Cost-plus contracts with benzene-indexed pricing clauses dominate synthetic adipic acid procurement between Shandong producers and European compounders. Price differentiation separates ISO 9001-certified automotive grades from standard textile material, with coating applications commanding the steepest premiums for color consistency guarantees. Pricing pressure stems from Chinese export volume concentration and EPA compliance cost stacking at US oxidation plants. Textile distributors exhibit highest price sensitivity through wholesale spot purchasing, while automotive Tier-1 suppliers accept indexed premiums for supply security.
Supply Chain Analysis
Inventory lead times stretch 8-12 weeks for European automotive compounders qualifying new bio-based suppliers through ISO 9001 certification cycles. Supply concentrates in China, Germany, and the United States, with Shandong-Jiangsu clusters controlling export volume and Ludwigshafen-Chocolate Bayou corridors serving captive automotive demand. Raw material dependencies include benzene derivatives for synthetic routes and sugar-derived feedstocks for fermentation platforms. Single-source vulnerability runs through Chinese export concentration for standard-grade material. Distribution runs through direct long-term offtake agreements for polymer-grade supply, with regional distributors managing coating and adhesive formulator accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where REACH dossier completion and EPA Clean Air Act compliance timelines lock qualified supplier status for incumbent oxidation operators and first-mover fermentation platforms.
For Market Incumbents: Consolidate backward integration into captive cyclohexane supply and accelerate nitrous oxide abatement unit deployment ahead of EU Green Deal carbon-accounting enforcement. Bio-based fermentation entrants threaten premium segment capture through Scope 3 offtake agreements with consumer goods brands; defend by locking automotive Tier-1 contracts with indexed volume tiers and thermal stability grade certification. For New Entrants and Emerging Players: Automotive Tier-1 supplier qualification service gaps expose entry points where incumbents under-serve mid-volume compounders seeking dual-source security. Target Netherlands and California coating formulators with mass-balance certified pilot volumes, leveraging ECHA lifecycle assessment harmonization as regulatory tailwind. Go-to-market angle: certified lower-carbon intensity with fixed-price contract structures displacing spot benzene exposure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation platform developers holding pilot-scale Dutch capacity and California demonstration plants. Five-to-ten year viability hinges on yield parity achievement with cyclohexane oxidation and automotive qualification completion. Acquisition target archetype: bio-based operators with secured sugar feedstock offtake and active ISO 9001 certification programs. Signal to watch: fermentation yield improvements crossing 80% theoretical maximum in continuous processing deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclohexane | BASF SE and Ascend Performance Materials secure feedstock cost control against benzene volatility. |
| Nitrous Oxide Abatement Deployment | EPA Clean Air Act compliance at legacy oxidation plants preserves qualified supplier status for automotive contracts. |
| Fermentation Yield Scale-Up | Bio-based platform developers narrow cost gap with synthetic routes through continuous processing advances. |
| Mass-Balance Certification | European coating formulators meet EU Green Deal carbon disclosure requirements through verified supply chains. |
| Long-Term Offtake Agreements | Automotive Tier-1 procurement teams consolidate vendor panels from twelve to four strategic partnerships. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, ECHA registration databases, and ACC/Cefic industry reports. Plant managers at oxidation facilities, procurement leads at nylon-6,6 compounders, distribution channel partners, and technical R&D directors at fermentation platforms provided operational perspective. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segmentation dimensions modeled include product type tier, end-use industry application, purity grade specification, and regional production hub concentration. CAGRs derived from volume-demand elasticity analysis against automotive lightweighting mandates and coating formulation growth. Forecast inputs incorporated fermentation yield improvement curves and nitrous oxide abatement capital deployment schedules without year-specific assumptions.
Underlying assumptions cover sustained automotive polyamide demand, REACH enforcement continuity, and fermentation yield trajectory stability, with deviation risk concentrated in Chinese environmental inspection intensity and crude oil price volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Global Tattoo Inks Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Dimethicone Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
Polyglycolic Acid (PGA) Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Special Boiling Point Solvents Market