
 Thermoformed Plastics for Printing Market | 2026-2036
Thermoformed Plastics for Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Plastics for Printing Market Intelligence
A capital-intensity divergence between integrated sheet producers and standalone thermoformers is reorganizing competitive tiers in the Thermoformed Plastics for Printing Market. Amcor Limited leverages captive resin sourcing and global extrusion assets to sustain margin control across multiple continents. Sonoco Products Company anchors its position through fiber-based and plastic hybrid packaging expertise that extends into printed thermoformed applications. Pactiv LLC competes aggressively in foodservice thermoforming, where volume scale and North American manufacturing density create defensive barriers.
Thermoformed plastics for printing encompass heated thermoplastic sheets shaped into contoured forms with subsequent graphic application via screen, digital, or offset methods, typically achieving detail resolution down to 40 microns on polystyrene and polypropylene substrates. These materials serve primarily as structural canvases for brand communication in retail and regulated packaging environments. Polypropylene segments are capturing disproportionate growth in food container applications due to microwave compatibility and enhanced ink adhesion properties. Polyethylene retains volume dominance in advertising displays and retail signage where cost minimization outweighs thermal performance requirements. PVC occupies a narrowing but technically defended niche in medical device trays where clarity and sterilization compatibility justify regulatory compliance investments.
The EPA oversees volatile organic compound emissions from printing operations on plastic substrates, while REACH and RoHS frameworks in Europe restrict phthalate plasticizers and heavy metal pigments in consumer-facing thermoformed articles. FDA food contact notifications govern material selection for printed food containers, creating compliance moats around qualified resin formulations and laminating adhesives. ISO 9001 and ISO 14001 certifications function as baseline qualifiers for supplier qualification by multinational brand owners. Stakeholders must monitor accelerating state-level extended producer responsibility laws in California and New York that will force redesign of printed thermoformed packaging for recyclability.
Market Dynamics
The EU F-Gas Regulation is compressing hydrofluorocarbon availability for thermoforming operations while simultaneously redirecting capital toward mechanical forming and electric heating retrofits across European converter facilities.
Growth Catalysts
- Food container microwave compatibility:Polypropylene formulations with enhanced heat deflection temperatures are displacing crystallized PET in ready-meal packaging. Brand owners in Germany and Japan specify these grades for dual-oven applications.
- REACH Article 33 supply chain disclosure:Downstream pressure for SVHC transparency is accelerating substitution of legacy plasticizers in printed thermoformed articles. Qualified resin suppliers capture preference from multinational FMCG procurement teams.
- Digital inkjet integration:Single-pass UV inkjet systems are eliminating screen-making delays for short-run promotional packaging. Converters in North American retail display segments deploy this capability for seasonal campaign turnaround.
Market Restraints
- Propylene monomer volatility:Polypropylene sheet producers face margin compression from naphtha-cracker feedstock swings tied to regional refinery utilization rates.
- German precision forming cluster concentration:Premium printing-grade thermoforming capacity concentrates in Baden-Württemberg and Bavaria, creating geographic supply risk for just-in-time packaging programs.
- PVC medical tray regulatory defense costs:DEHP plasticizer restrictions under EU MDR and US FDA 510(k) pathways require ongoing toxicology dossier maintenance for sterilization clarity applications.
Strategic Opportunities
- India foodservice penetration:Quick-service restaurant chains and organized retail are adopting printed thermoformed clamshells for branded takeaway packaging in Mumbai and Delhi NCR.
- California SB 54 extended producer responsibility:Mandated recyclability design rules will force substrate standardization, creating first-mover advantage for mono-material PP and PET formulations with compatible printing chemistries.
- Digital twin process simulation:Convergence of thermoforming simulation software with print registration control systems enables virtual prototyping of complex multi-cavity tools.
Industry Challenges
- ISO 14001 auditor scarcity:Certification backlogs for environmental management systems delay supplier qualification by multinational brand owners with 2025 sustainability targets.
- Legacy solvent ink fleet stranding:Converters with amortized flexographic presses face capex timing decisions on UV LED retrofit versus full digital replacement for short-run work.
- Food contact notification synchronization:FDA FCN approval timelines for novel laminating adhesives misalign with European EFSA positive list updates, complicating global formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Plastics for Printing Market |
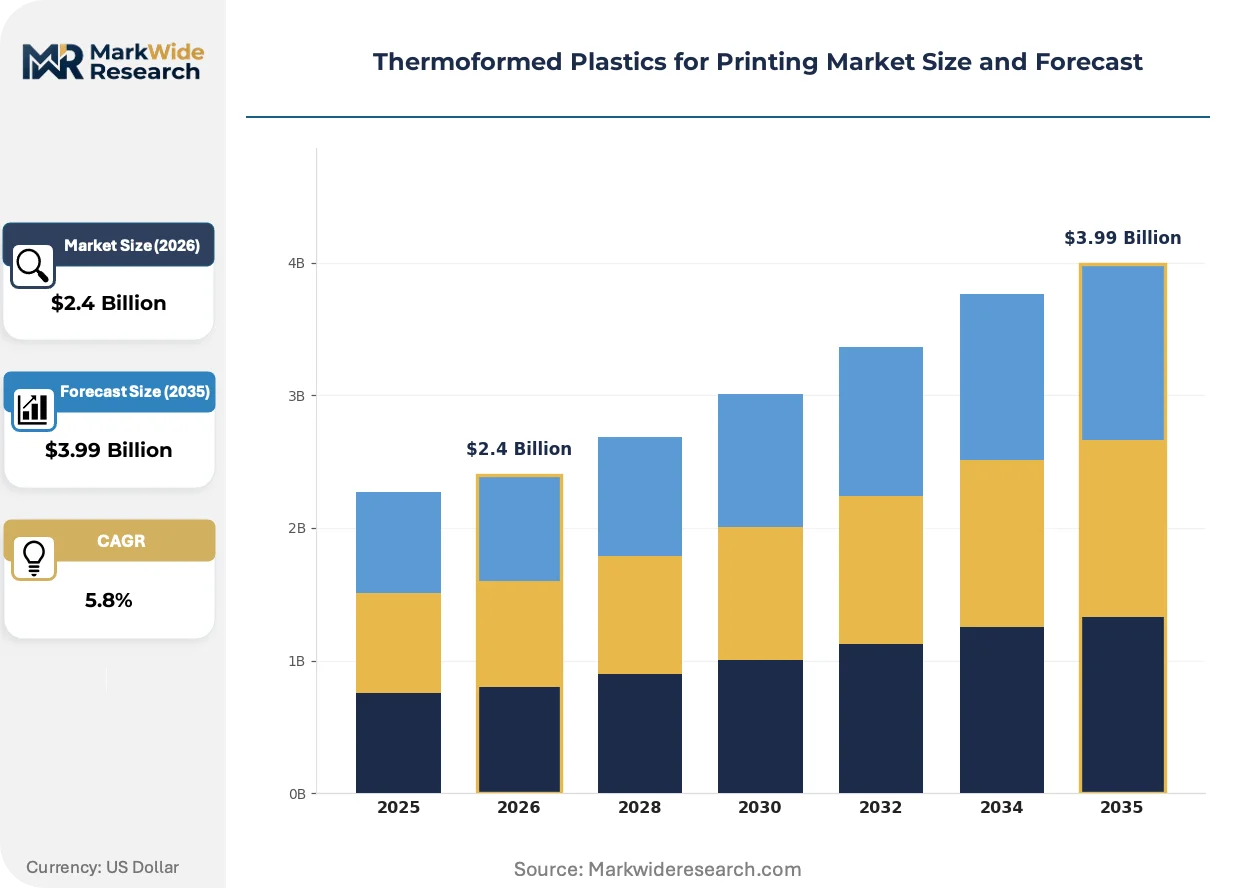
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polystyrene, Polyethylene, Polypropylene, PVC End User: Packaging, Automotive, Consumer Goods, Electronics Manufacturing Stage: Injection Molding, Blow Molding, Vacuum Forming, Thermoforming Application: Advertising Displays, Retail Signage, Medical Devices, Food Containers |
| Companies Covered | Omega Plastics LLC, Productive Plastics, Inc., Sonoco Products Company, Sulapac Oy, Universal Plastics Group, Inc, Aero-Plastics Inc., Pactiv LLC, Amcor Limited, Tekni-Plex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Plastics for Printing Market Strategic Shifts & Innovations
Active thermoforming process digitization and substrate chemistry evolution are compressing development cycles for printed packaging while simultaneously fragmenting traditional equipment supply relationships.
Advanced servo-driven pressure forming with real-time sheet temperature profiling is fragmenting the historical distinction between thin-gauge roll-fed and heavy-gauge cut-sheet operations. Medical device manufacturers and electronics OEMs now specify mid-gauge forming with embedded printed circuitry from single-source equipment platforms. Equipment suppliers with integrated controls architectures capture preference over standalone machinery vendors.
The EU F-Gas Regulation phase-down schedule is forcing accelerated adoption of electric infrared and ceramic heating elements in place of gas-fired radiant systems. German and Italian machinery builders now lead retrofit program deployment. Food container converters in the Benelux region report 15-20% energy cost reductions but face extended payback periods on capital-intensive oven replacements.
Brand owner specification of mass-balance certified polymers is restructuring resin procurement relationships for printed thermoformed packaging. European cosmetics and personal care verticals now require ISCC PLUS documentation for fossil-derived substrates with renewable feedstock attribution. Procurement teams in France and Switzerland are consolidating supplier panels to converters with certified polymer traceability systems.
Thermoformed Plastics for Printing Market Segmentation
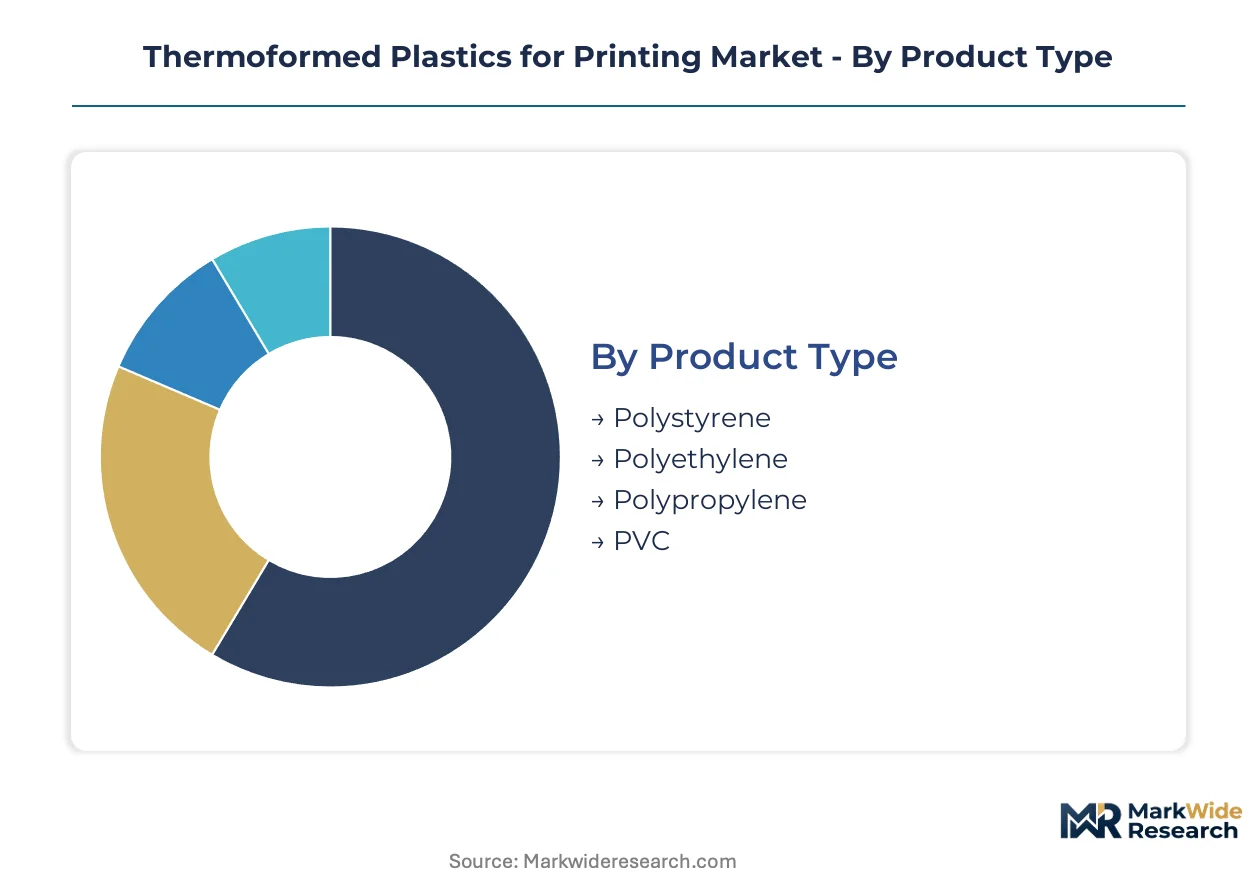
Thermoformed plastics for printing demand fragments across substrate chemistry, end-use specifications, and forming process economics. Each segmentation axis reveals distinct margin profiles and regulatory exposure that reshape procurement priorities for converters and brand owners.
Product Type:
Polypropylene and polystyrene formulations dominate export-oriented supply chains serving multinational FMCG specifications, while polyethylene and PVC grades anchor regional production serving price-sensitive domestic markets.
- Polystyrene:Crystal and high-impact grades deliver exceptional print clarity with detail resolution to 40 microns for retail signage and point-of-sale displays. German precision forming clusters specify these grades for premium cosmetic packaging requiring flawless graphic reproduction.
- Polypropylene:Copolymer formulations with enhanced heat deflection temperatures enable dual-oven food container applications. Brand owners in Japan and Germany specify microwave-compatible grades displacing crystallized PET in ready-meal segments.
- Polyethylene:Low-density and linear-low-density variants minimize substrate cost for high-volume advertising displays where thermal performance requirements remain modest.
- PVC:Rigid calendered sheets retain niche defense in medical device trays requiring sterilization clarity and DEHP plasticizer compliance under EU MDR pathways.
Polystyrene commands the established base in display and signage applications. The steepest expansion runs through polypropylene as food container specifications harden around microwave compatibility.
End User:
Packaging converters drive volume procurement with standardized resin specifications, while automotive and electronics OEMs impose custom qualification protocols that fragment supplier relationships.
- Packaging:Food container and cosmetic tray applications demand FDA food contact notification compliance and REACH Article 33 SVHC transparency. Mass-balance certification requirements from European cosmetics verticals now filter procurement to ISCC PLUS qualified converters.
- Automotive:Interior trim panels and instrument cluster housings require heat-resistant ABS and PC-ABS blends with printed decorative surfaces. OEMs specify mid-gauge pressure forming with embedded graphics from single-source equipment platforms.
- Consumer Goods:Electronics housings and appliance bezels utilize printed thermoformed skins over structural substrates, with Asian contract manufacturers driving specification standardization.
- Electronics:ESD-sensitive tray applications for semiconductor and component handling require conductive formulations with controlled surface resistivity and cleanroom-compatible printing chemistries.
Packaging captures the volume anchor position. Electronics represents the fastest-growing trajectory as semiconductor supply chain reshoring accelerates specialized tray demand.
Manufacturing Stage:
Thin-gauge roll-fed thermoforming dominates high-speed food container production, while heavy-gauge cut-sheet operations serve medical and automotive programs with extended cycle times and precision tolerances.
- Injection Molding:Produces structural components with integrated printed inserts or in-mold decoration, serving automotive interior panels where dimensional stability exceeds thermoforming capabilities.
- Blow Molding:Hollow container production with post-mold labeling or direct printing on curved surfaces competes with thermoformed alternatives in liquid packaging segments.
- Vacuum Forming:Low-pressure forming of thin-gauge sheet serves cost-minimized advertising displays and disposable packaging where detail resolution requirements remain secondary to speed.
- Thermoforming:Pressure and twin-sheet variants achieve the 40-micron graphic precision required for premium printed packaging, with servo-driven systems fragmenting the historical thin-gauge/heavy-gauge distinction.
Thermoforming holds the precision printing advantage. Vacuum forming defends the cost floor in commoditized display segments.
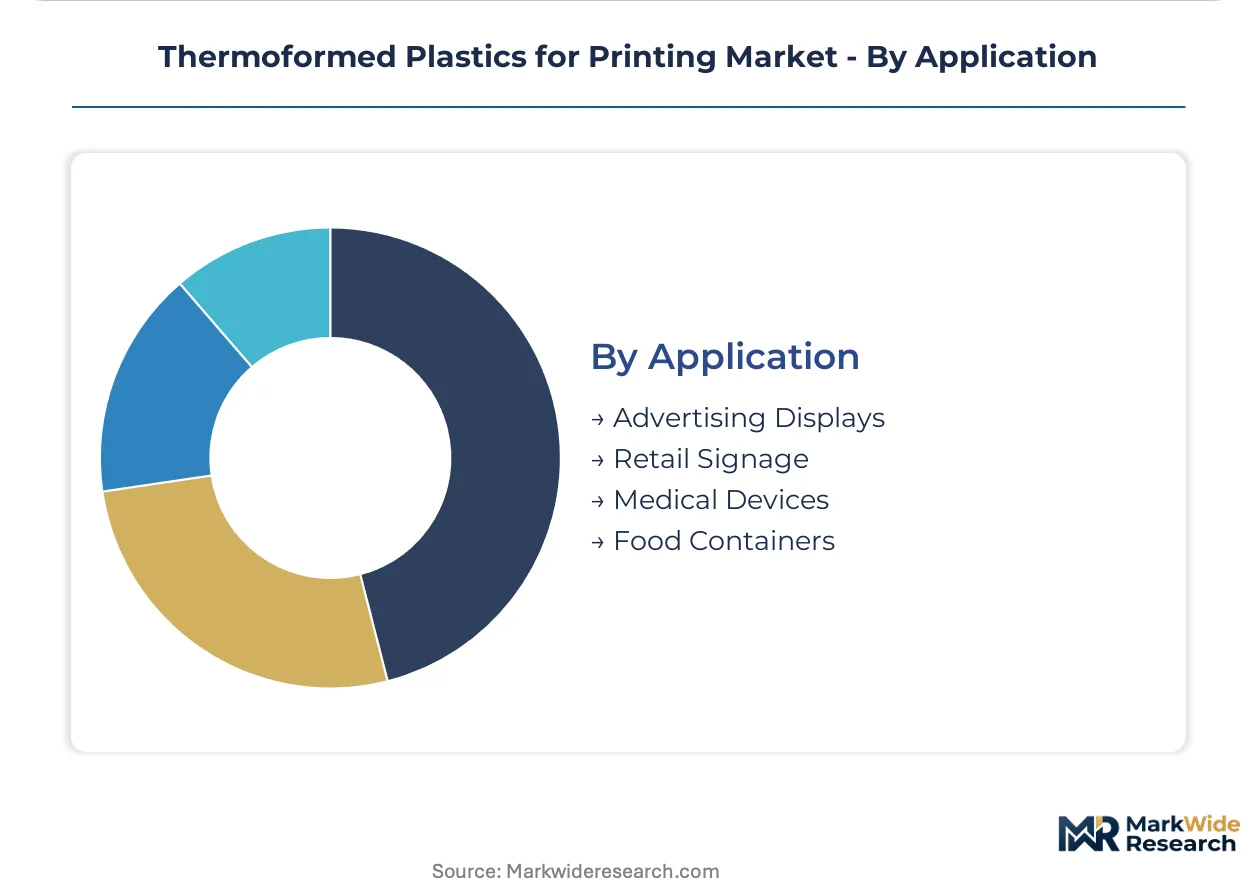
Application:
Food container and medical device applications impose the strictest material qualification burdens, while advertising displays tolerate broader formulation flexibility.
- Advertising Displays:Large-format retail signage and exhibition graphics prioritize substrate cost minimization over thermal performance, with polyethylene and polystyrene dominating North American point-of-purchase production.
- Retail Signage:Shelf talkers, danglers, and endcap displays require vibrant ink adhesion on polystyrene and PETG substrates, with seasonal campaign turnover driving digital inkjet adoption.
- Medical Devices:Sterilization trays and procedure kits demand PVC clarity or PETG alternatives with FDA 510(k) pathway compliance and ongoing toxicology dossier maintenance.
- Food Containers:Dual-oven ready-meal packaging specifies polypropylene with enhanced heat deflection, with California SB 54 recyclability mandates forcing mono-material standardization.
Advertising displays anchor volume throughput. Food containers are climbing the fastest as microwave compatibility and extended producer responsibility laws reshape material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision thermoforming clusters command premium pricing power against North American volume producers, creating a transatlantic cost-structure asymmetry that reshapes procurement routing for multinational brand owners.
Germany
Baden-Württemberg and Bavaria host dense concentrations of servo-driven pressure forming capacity serving cosmetic and medical packaging specifications. The EU F-Gas Regulation accelerates electric heating retrofits across converter facilities in Stuttgart and Munich industrial corridors. REACH Article 33 disclosure mandates filter procurement toward qualified resin suppliers with SVHC transparency systems.
United States
California SB 54 extended producer responsibility laws force mono-material PP and PET standardization for printed food containers. EPA volatile organic compound oversight shapes printing operation compliance investments across Midwestern converter networks. Pactiv LLC anchors volume-scale foodservice thermoforming capacity in manufacturing-dense regions.
Japan
METI industrial policy supports microwave-compatible polypropylene adoption for dual-oven ready-meal packaging specifications. Brand owners in Tokyo and Osaka metropolitan areas specify enhanced heat deflection grades displacing crystallized PET. Precision forming clusters in Chubu and Kansai regions serve premium electronics tray demand.
India
Quick-service restaurant chains in Mumbai and Delhi NCR adopt printed thermoformed clamshells for branded takeaway packaging. FSSAI food contact safety frameworks govern material selection for converter qualification. Organized retail expansion drives specification standardization across Maharashtra and Karnataka manufacturing zones.
China
GB standards and MIIT industrial guidelines shape substrate chemistry evolution for export-oriented packaging supply chains. Yangtze River Delta and Pearl River Delta clusters serve Asian contract manufacturer specifications for electronics housing applications. Dual carbon goals redirect capital toward electric forming equipment retrofits.
Thermoformed Plastics for Printing Market Key Industry Players
Concentration sits with integrated sheet producers possessing captive resin sourcing and global extrusion assets. Standalone thermoformers compete on volume scale and regional manufacturing density, particularly in North American foodservice segments. Three archetypes dominate: multinational packaging conglomerates with backward integration into resin supply, mid-cap specialists with hybrid fiber-plastic expertise, and regional volume players with defensive cost positions. Competitive moves center on capacity expansion in microwave-compatible polypropylene and strategic partnerships for mass-balance certified polymer procurement.
Among North American-based fabricators, Pactiv LLC and Sonoco Products Company exemplify distinct competitive positioning. Pactiv LLC occupies the volume-driven foodservice tier where manufacturing density creates defensive barriers. Sonoco Products Company anchors a hybrid packaging archetype extending fiber-based expertise into printed thermoformed applications. Amcor Limited represents the integrated multinational tier with global extrusion assets sustaining margin control across multiple continents. Omega Plastics LLC and Productive Plastics, Inc. sit within the specialist converter segment serving precision printing-grade specifications.
| Leading Market Players |
|---|
| Omega Plastics LLC |
| Productive Plastics, Inc. |
| Sonoco Products Company |
| Sulapac Oy |
| Universal Plastics Group, Inc |
| Aero-Plastics Inc. |
| Pactiv LLC |
| Amcor Limited |
| Tekni-Plex |
| Others |
Cost & Logistics Intelligence
Long-term resin offtake contracts with German precision forming clusters lock in polypropylene supply access and stabilize unit cost visibility for converters serving multinational FMCG specifications, insulating qualified suppliers from propylene monomer volatility while exposing non-contracted players to spot market swings.
Pricing Analysis
The customization-premium spread between configured-to-order microwave-compatible polypropylene and standard polyethylene substrates runs wide across the Thermoformed Plastics for Printing Market. Three-tier pricing structure across premium, standard, and economy levels separates FDA food contact notification grades from general advertising display materials. Cost compression in standard signage grades is intensifying because naphtha-cracker feedstock swings transmit directly to polyethylene sheet producers. Brand owners in food container applications demonstrate lowest price sensitivity, prioritizing dual-oven compatibility and REACH Article 33 compliance over unit cost minimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate converter relationships with Baden-Württemberg precision forming clusters, while strategic stockpiling of polypropylene resin concentrates among integrated sheet producers with captive extrusion assets. Supply concentrates in Germany, the United States, and Japan for premium printing-grade thermoforming capacity. Raw material dependencies center on propylene monomer, naphtha feedstocks, and mass-balance certified polymer attributions. Single-source vulnerability from German cluster concentration creates geographic supply risk for just-in-time packaging programs. Distribution runs through converter-direct relationships with multinational brand owner procurement teams, bypassing traditional distribution intermediaries in qualified resin segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational FMCG procurement teams consolidating supplier panels to ISCC PLUS qualified converters, fragmenting competitive access for standalone thermoformers lacking mass-balance certification infrastructure.
For Market Incumbents: Fortify backward integration into polypropylene extrusion assets to capture margin control against propylene monomer volatility, while accelerating electric infrared heating retrofits to preempt EU F-Gas Regulation compliance costs. Defensive capacity additions in microwave-compatible grades should concentrate in Stuttgart and Munich industrial corridors to defend geographic premium positioning against North American volume producers. For New Entrants and Emerging Players: Short-run digital inkjet service gaps in North American retail display segments offer white-space entry points where legacy solvent ink fleets face stranding risk. Target seasonal promotional packaging turnover with single-pass UV capabilities, penetrating through rapid campaign turnaround guarantees rather than capital-intensive extrusion scale. For Investors and Strategic Acquirers: Mid-gauge pressure forming specialists with embedded printed circuitry capabilities represent the priority acquisition archetype, as medical device manufacturers and electronics OEMs consolidate single-source equipment platforms. Monitor FDA food contact notification approval timelines for novel laminating adhesives as inflection indicators for global formulation strategy viability.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Heating Retrofit | EU F-Gas Regulation phase-down forces 15-20% energy cost reductions across Benelux converter facilities. |
| Mass-Balance Certification | ISCC PLUS documentation requirements from French cosmetics verticals filter procurement to qualified suppliers. |
| Digital Inkjet Integration | Single-pass UV systems eliminate screen-making delays for seasonal campaign turnaround in North American retail. |
| Mono-Material Standardization | California SB 54 recyclability mandates force PP and PET substrate consolidation for food container applications. |
| Servo-Driven Pressure Forming | Real-time sheet temperature profiling fragments thin-gauge/heavy-gauge distinctions for medical and electronics OEMs. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with thermoforming plant managers, procurement leads at multinational FMCG brand owners, resin formulation technical directors, and digital printing equipment specialists. Secondary validation drew from FDA food contact notification databases, ECHA SVHC candidate list updates, SEC 10-K filings of integrated packaging conglomerates, and customs trade data for polypropylene sheet imports. Bottom-up volume modeling across substrate chemistry and end-use specifications was triangulated against top-down macroeconomic drivers.
Across the analysis window, the forecasting framework modeled demand evolution through segmentation dimensions including substrate type, forming process economics, end-use qualification tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for policy-driven inflection points. Industry-specific inputs incorporated EU F-Gas Regulation phase-down schedules, California extended producer responsibility implementation timelines, and METI industrial policy support for microwave-compatible polypropylene adoption.
Forecasts assume regulatory continuity in REACH Article 33 disclosure mandates, FDA food contact notification pathways, and EU MDR plasticizer restrictions; material policy shifts would require re-modeling of qualified resin supplier preference dynamics. Propylene monomer volatility, state-level extended producer responsibility acceleration, and digital inkjet technology cost curves constitute primary revision triggers. Revision becomes warranted when mass-balance certification penetration crosses thresholds that restructure procurement panel consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Additive Manufacturing and Materials Market