
 Nanobody Market | 2026-2036
Nanobody Market Size, Share, and Industry Trends Forecast 2026-2036
Nanobody Market Outlook
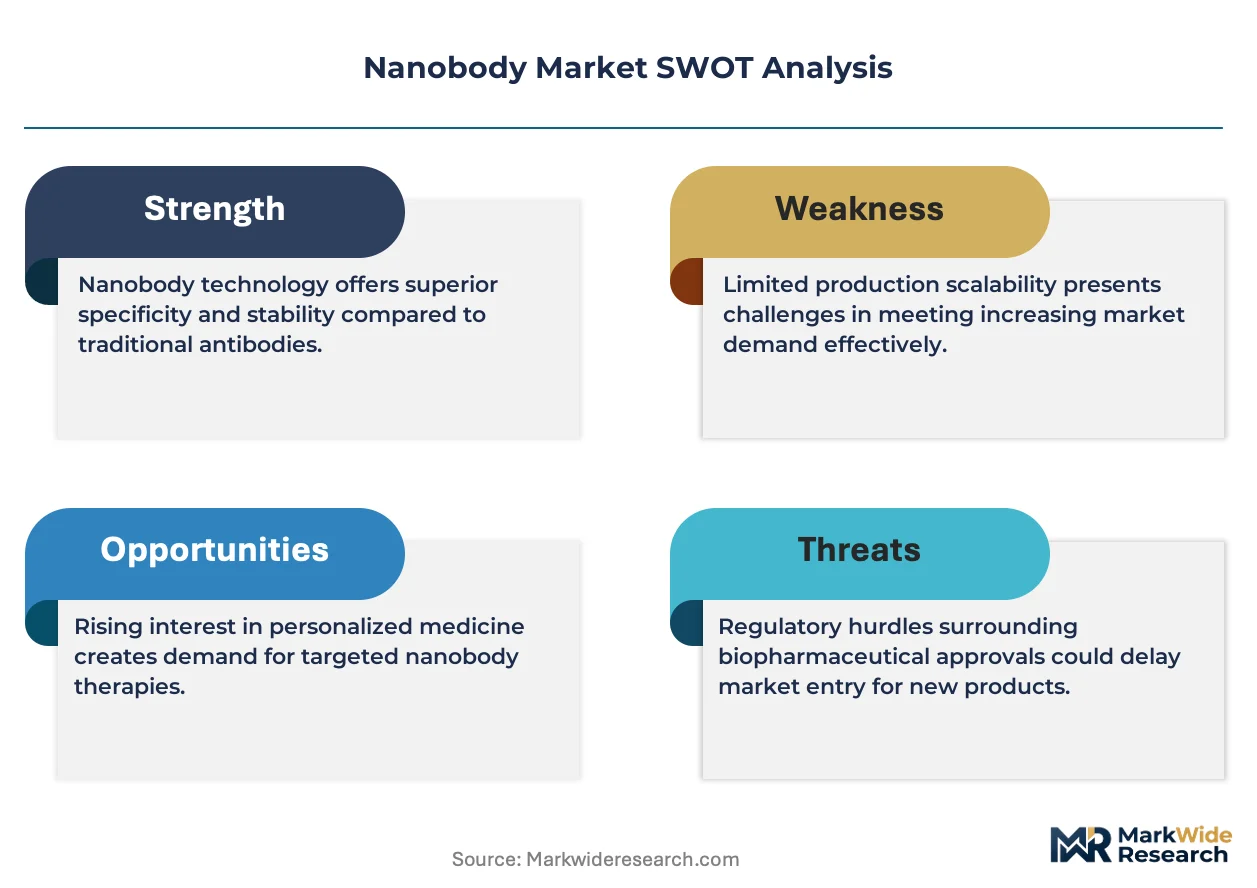
Modular therapeutic formats paired with companion diagnostics is recalibrating how hospital systems and pharmaceutical buyers evaluate nanobody procurement. Sanofi (Ablynx) leverages its legacy platform dominance in Europe to sustain manufacturing scale for caplacizumab-derived programs. AbCellera Biologics Inc. anchors North American discovery partnerships through its single-cell screening technology. GenScript Biotech Corporation competes on custom synthesis turnaround and GMP-grade nanobody production capacity in Asia-Pacific markets.
Nanobodies are single-domain antibody fragments derived from camelid heavy-chain-only immunoglobulins, typically spanning 12-15 kDa with a convex paratope structure that accesses cryptic epitopes inaccessible to conventional antibodies. These molecules serve primarily as targeted therapeutics, imaging agents, and research tools where tissue penetration and thermal stability prove decisive. Therapeutic nanobodies command the largest value pool given approved indications in thrombotic thrombocytopenic purpura and expanding oncology pipelines, while conjugated nanobodies represent the fastest-expanding segment as antibody-drug conjugate architectures incorporate nanobody scaffolds for payload delivery. Diagnostic nanobodies occupy a mature, margin-compressed position in research-use-only applications despite growing clinical interest.
FDA biologics licensing requirements and EMA's MDR framework jointly shape GMP manufacturing standards and clinical evidence thresholds for nanobody developers seeking commercial access. The EU AI Act introduces additional algorithmic transparency obligations for AI-driven nanobody discovery platforms deployed in European jurisdictions. Stakeholders must monitor how evolving pharmacovigilance requirements for novel biologic formats interact with accelerated approval pathways across major regulatory territories.
Market Dynamics
Pharmaceutical developers are racing to secure GMP manufacturing capacity ahead of EMA MDR enforcement timelines, compressing the window for pipeline candidates to reach commercial scale. This capacity scramble is redrawing partnership terms between discovery platforms and contract manufacturing organizations across Belgium, the United States, and China.
Growth Catalysts
- Companion diagnostic integration:Hospital systems now bundle nanobody therapeutics with biomarker testing protocols, expanding addressable patient populations for oncology programs.
- FDA accelerated approval pathways:The breakthrough therapy designation streamlines clinical evidence requirements for rare disease indications, shortening development timelines.
- Belgium's manufacturing cluster density:Ghent and Liège host concentrated fill-finish capacity that reduces logistics costs for European commercial launches.
Market Restraints
- Mammalian cell culture input costs:Serum and media price volatility constrains margin expansion for GMP-grade production runs.
- Single-source supplier concentration:Camelid immunization services cluster in specialized North American and European facilities, creating bottlenecks for early-stage discovery.
- MDR technical documentation burden:The EU's expanded clinical evidence requirements for novel biologic formats delay CE marking timelines.
Strategic Opportunities
- Intratumoral delivery applications:Nanobody tissue penetration advantages position the format for localized oncology administration routes.
- AI-driven discovery platform deployment:Machine learning algorithms trained on camelid immune repertoires compress lead identification timelines.
- China's biologics CDMO expansion:NMPA reforms and domestic capital investment create captive manufacturing capacity for Asia-Pacific commercialization.
Industry Challenges
- Camelid immunization expertise scarcity:Veterinary immunology specialists with heavy-chain antibody experience command premium compensation.
- GMP facility qualification timelines:EMA and FDA pre-approval inspections for novel molecular formats extend facility readiness schedules.
- Antibody-drug conjugate payload integration:Linker chemistry optimization for nanobody scaffolds requires specialized analytical development capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanobody Market |
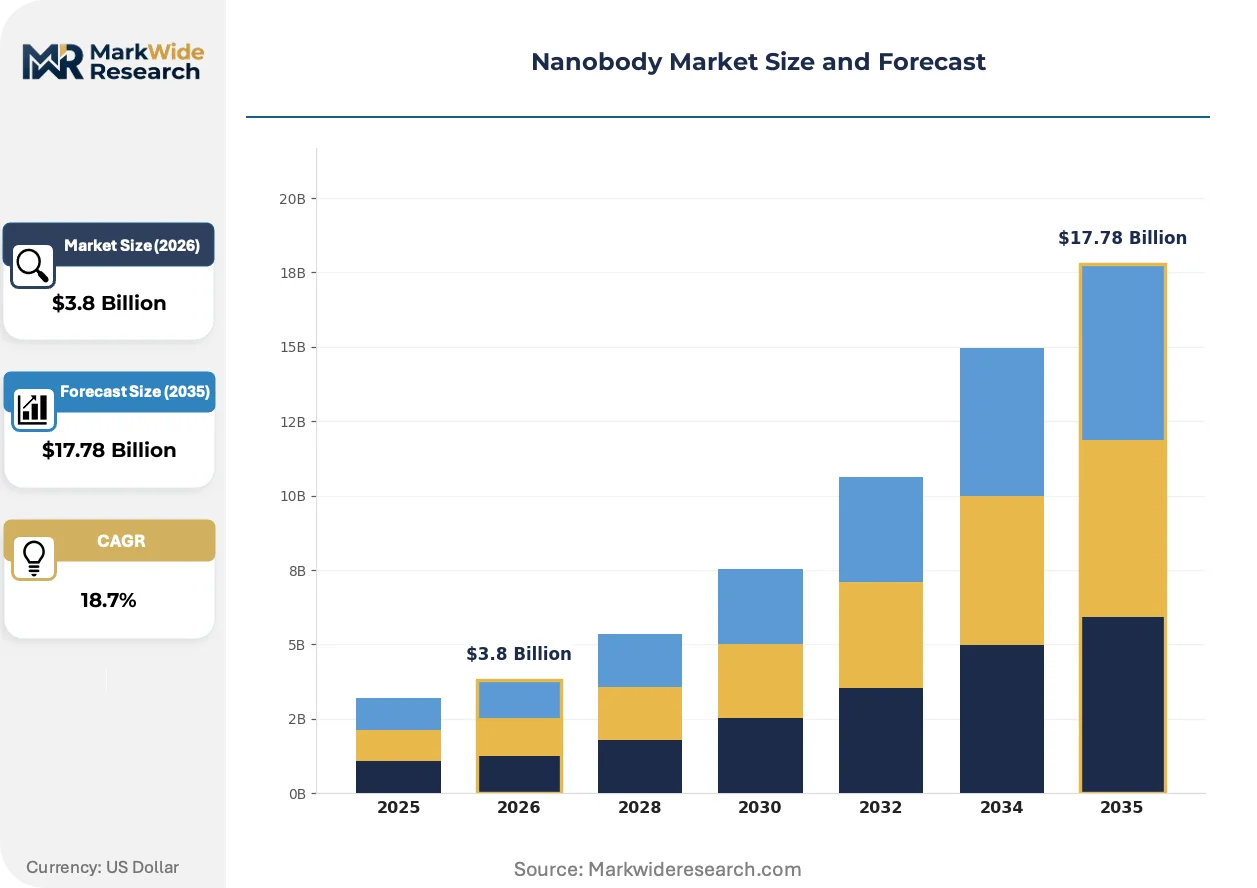
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Nanobodies, Diagnostic Nanobodies, Conjugated Nanobodies, Engineered Nanobodies Application: Oncology, Autoimmune Disorders, Infectious Diseases, Imaging End User: Pharmaceutical Companies, Research Institutes, Contract Research Organizations, Hospitals Delivery Mode: Intradermal, Subcutaneous, Intravenous, Oral |
| Companies Covered | Boehringer Ingelheim, BIOCYTOGEN, Sanofi (Ablynx), Alphamab Oncology, Sensei Biotherapeutics, Inc., Merck KGaA, GenScript Biotech Corporation, AbCellera Biologics Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanobody Market Strategic Shifts
Discovery and manufacturing workflows are converging around platform standardization, with automation and algorithmic design compressing the path from immunization to IND filing. These shifts are altering how developers allocate capital between in-house capabilities and outsourced partnerships.
Single-cell B-cell screening technology is automating the isolation of antigen-specific nanobody sequences from immunized camelid repertoires. Contract research organizations in North America and Europe are deploying these platforms to reduce lead identification timelines from months to weeks. The technology is automating away traditional hybridoma-based screening workflows that previously dominated antibody discovery.
The EU AI Act imposes algorithmic transparency obligations on machine learning systems used for nanobody candidate selection and optimization. Developers deploying AI-driven discovery platforms in European jurisdictions must document training data provenance and model decision logic. Early-stage biotech firms with limited regulatory affairs infrastructure face compliance costs that favor partnership with established platform holders.
Hospital procurement committees are consolidating nanobody therapeutic purchasing under centralized pharmacy and therapeutics committees. This concentration shifts negotiating leverage toward integrated delivery networks and away from individual prescriber preference. The United States exhibits the most pronounced consolidation, with major academic medical centers standardizing formularies across multi-hospital systems.
Nanobody Market Segmentation
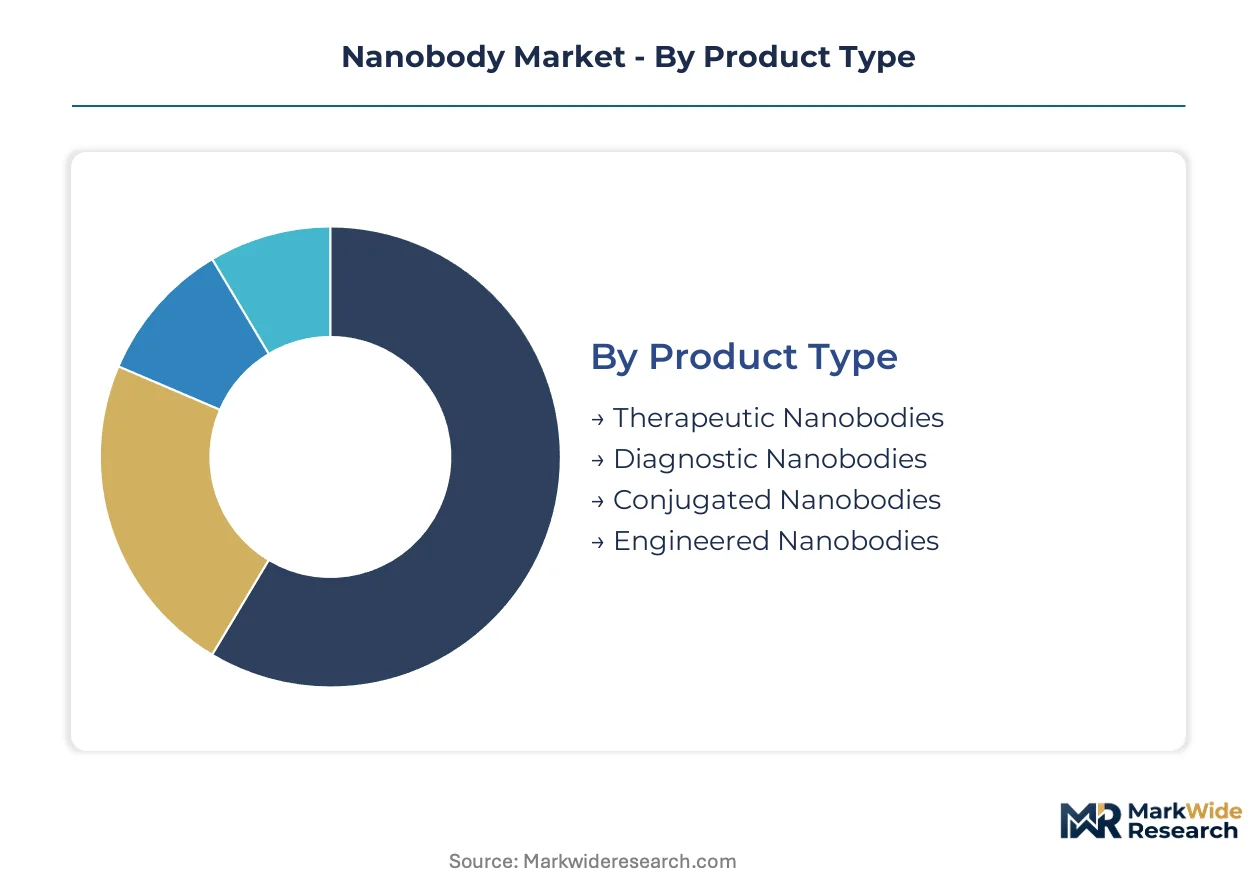
Nanobody developers face divergent regulatory pathways and manufacturing standards across product formats, forcing strategic portfolio choices that balance commercial timelines against technical complexity. Segmentation reveals where FDA breakthrough designations, EMA MDR compliance, and NMPA biologics reforms create asymmetric access costs for different molecular configurations.
Product Type:
FDA biologics licensing requirements and EMA's MDR framework impose distinct certification burdens: therapeutic formats demand Phase III efficacy data, while diagnostic applications navigate research-use-only versus clinical-grade validation tiers.
- Therapeutic Nanobodies:Full-length VHH domains engineered for systemic administration with validated GMP manufacturing protocols. Demand concentrates in hematology and oncology indications where caplacizumab's commercial precedent has de-risked regulatory pathways for subsequent candidates. FDA accelerated approval and EMA conditional marketing authorization compress development timelines for rare disease targets.
- Conjugated Nanobodies:Antibody-drug conjugate architectures incorporating nanobody scaffolds for targeted payload delivery. Manufacturing complexity escalates with linker chemistry optimization requirements, yet tissue penetration advantages position this format for solid tumor applications where conventional ADCs face penetration limits. This segment is expanding most quickly as oncology pipelines integrate nanobody binders with cytotoxic and radiolabeled payloads.
- Diagnostic Nanobodies:Research-use-only and clinical-grade reagents for biomarker detection and imaging applications. Margin compression characterizes the research segment despite volume scale.
- Engineered Nanobodies:Multivalent and multispecific constructs designed for extended half-life or dual-targeting functionality. Custom synthesis requirements limit standardization.
Leading the category by volume: Therapeutic Nanobodies. Growing fastest: Conjugated Nanobodies.
Application:
Cost tier stratification separates premium-priced oncology therapeutics from commoditized infectious disease diagnostics, with autoimmune indications occupying a mid-tier reimbursement position.
- Oncology:Solid tumor and hematologic malignancy programs dominate pipeline investment, with intratumoral delivery routes exploiting nanobody penetration advantages. United States academic medical centers drive demand for companion diagnostic-therapeutic bundles.
- Autoimmune Disorders:Inflammatory pathway modulation via nanobody cytokine blockade attracts development interest, though competitive intensity from conventional monoclonal antibodies constrains pricing power.
- Infectious Diseases:Neutralizing nanobodies against viral and bacterial targets serve pandemic preparedness and antimicrobial resistance applications. Research institutes in Belgium and China anchor procurement volume for preclinical validation studies.
- Imaging:Radiolabeled and fluorescent nanobody tracers for intraoperative guidance and molecular imaging. Regulatory pathways differ sharply between diagnostic and therapeutic radiopharmaceutical categories.
Dominant by revenue capture: Oncology. Steepest expansion trajectory: Imaging applications in surgical navigation.
End User:
Customer type determines contract structure complexity, with pharmaceutical companies demanding full technology transfer packages and research institutes prioritizing flexible licensing terms.
- Pharmaceutical Companies:Integrated developers and biotech firms seeking in-house GMP manufacturing capacity or captive CDMO relationships. Belgium's cluster density attracts European headquarters functions.
- Contract Research Organizations:Discovery and preclinical service providers automating single-cell screening workflows. North American CROs leverage AbCellera partnership structures to compress lead identification timelines.
- Research Institutes:Academic laboratories and national research centers utilizing nanobodies as structural biology tools and diagnostic reagents. Procurement concentrates through centralized university purchasing consortia.
- Hospitals:Pharmacy and therapeutics committees managing formulary placement for approved nanobody therapeutics. United States integrated delivery networks exercise consolidated negotiating leverage.
Highest contract value: Pharmaceutical Companies. Fastest procurement growth: Hospitals via centralized committee structures.
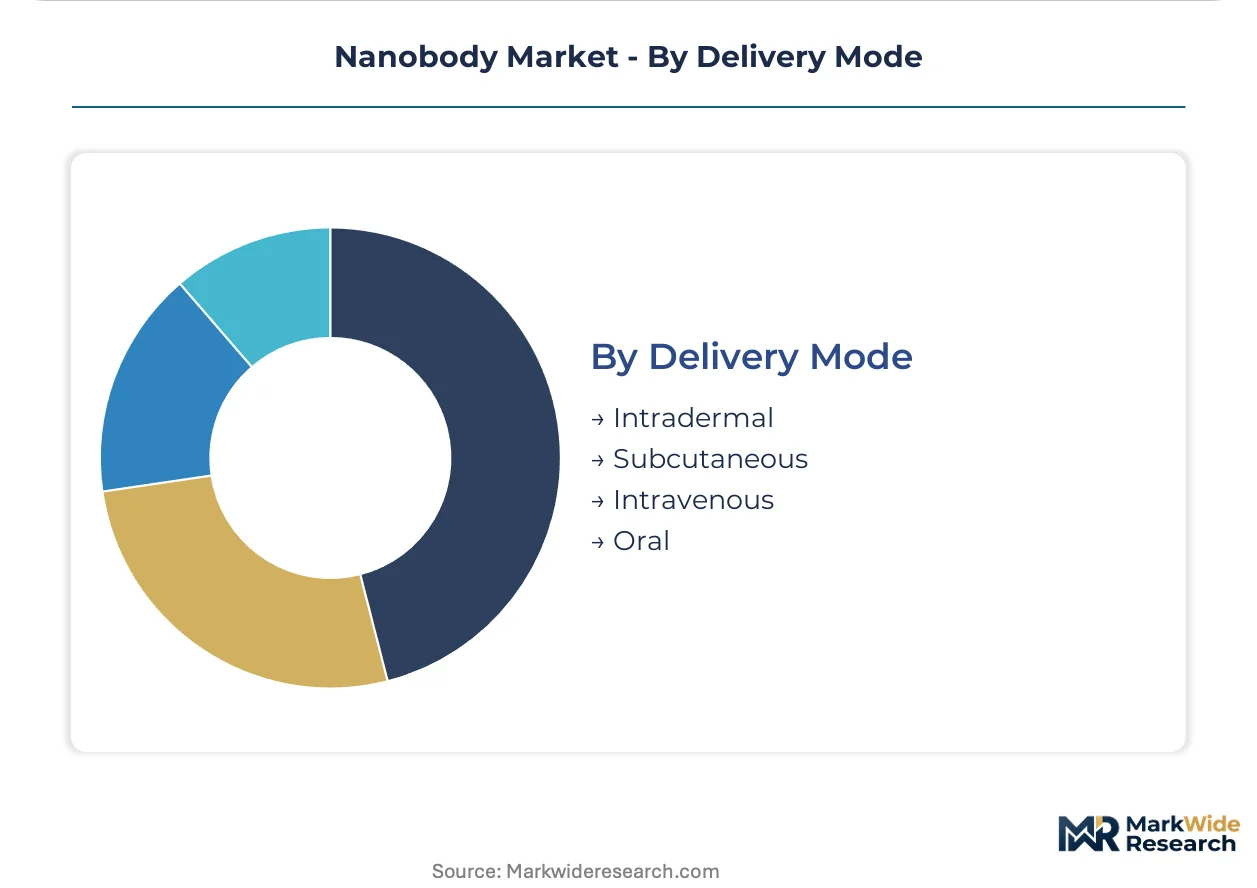
Delivery Mode:
Supply concentration for fill-finish capacity varies by route, with intravenous formulations requiring aseptic manufacturing investments that subcutaneous and intradermal formats partially circumvent.
- Intravenous:Standard administration for therapeutic nanobodies requiring immediate systemic exposure. GMP facility qualification timelines extend for aseptic processing validation.
- Subcutaneous:Patient-administered and clinic-based injection formats reducing healthcare utilization costs. Formulation stability requirements differ from intravenous presentations.
- Intradermal:Specialized delivery for vaccination and certain immunotherapy applications. Manufacturing scale remains constrained by device compatibility requirements.
- Oral:Gastrointestinal stability challenges limit current therapeutic applicability, though research interest persists for mucosal targeting applications.
Primary volume share: Intravenous. Gaining share fastest: Subcutaneous via patient convenience positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and the United States concentrate GMP manufacturing capacity while China scales domestic CDMO infrastructure. Demand clusters diverge: hospital systems in the United States drive therapeutic procurement, European research institutes anchor discovery services, and Chinese biotech firms expand internal pipeline development.
United States
FDA accelerated approval pathways and breakthrough therapy designations compress clinical timelines for rare disease nanobody candidates. The 21st Century Cures Act provisions sustain priority review voucher demand. Greater Boston and San Francisco Bay Area host concentrated discovery platform partnerships with automated single-cell screening deployments.
Belgium
EMA MDR enforcement timelines and centralized EMA headquarters proximity attract pharmaceutical companies seeking parallel EU commercial access. Ghent and Liège maintain specialized fill-finish capacity for aseptic biologic processing. Ablynx heritage infrastructure supports scaled manufacturing for caplacizumab-derived programs.
China
NMPA biologics licensing reforms and domestic capital investment accelerate GMP facility construction for nanobody production. The national regulator's acceptance of overseas clinical data streamlines multinational trial designs. Shanghai and Suzhou biotech parks concentrate CDMO capacity serving Asia-Pacific commercialization.
Switzerland
Swissmedic alignment with EMA standards enables seamless EU market access for nanobody developers establishing European headquarters. The country's bilateral mutual recognition agreements reduce redundant regulatory filings. Basel and Zurich host pharmaceutical R&D operations leveraging proximity to German and French manufacturing networks.
United Kingdom
MHRA post-Brexit regulatory autonomy creates divergent approval pathways from EMA frameworks for nanobody therapeutics. The Cell and Gene Therapy Catapult infrastructure supports translational manufacturing scale-up. Cambridge and Oxford research clusters sustain academic-industry discovery partnerships.
Nanobody Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across discovery, manufacturing, and commercialization functions. Market structure tilts toward platform consolidation: automated screening technologies and captive GMP capacity create scale advantages that fragment service-provider tiers. Three archetypes dominate—integrated pharmaceutical developers with legacy nanobody assets, discovery-platform technology licensors, and contract manufacturing organizations with regional specialization. Competitive moves center on manufacturing capacity pre-commitments ahead of regulatory enforcement deadlines and algorithmic discovery platform licensing to compress lead identification timelines.
Among discovery-platform specialists, AbCellera Biologics Inc. and GenScript Biotech Corporation exemplify divergent geographic anchoring strategies. Sanofi (Ablynx) occupies a position representing integrated therapeutic development and commercial manufacturing scale. Boehringer Ingelheim and Merck KGaA sit within the diversified pharmaceutical tier leveraging existing biologics infrastructure for nanobody pipeline expansion.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| BIOCYTOGEN |
| Sanofi (Ablynx) |
| Alphamab Oncology |
| Sensei Biotherapeutics, Inc. |
| Merck KGaA |
| GenScript Biotech Corporation |
| AbCellera Biologics Inc. |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Serum and cell culture media price indices cascade through nanobody manufacturing tiers, compressing margins for GMP-grade therapeutic batches while research-grade diagnostic reagents absorb volatility through spot purchasing. EMA MDR compliance costs and FDA pre-approval inspection timelines stratify pricing across certification levels, with hospital procurement committees exploiting volume concentration to extract contract concessions.
Pricing Analysis
Margin tightening in therapeutic nanobodies reflects mammalian cell culture input cost volatility and single-source supplier premiums for camelid immunization services. Pricing stratifies across GMP-certified, research-grade, and custom-synthesis tiers, with FDA breakthrough designation status commanding brand premiums. Cost-down pressure on diagnostic formats accelerates because research-use-only margin compression forces volume scaling. Pharmaceutical buyers exhibit lowest price sensitivity due to captive pipeline dependencies, while academic institutes negotiate aggressively on flexible licensing terms.
Supply Chain Analysis
Dual-sourcing requirements for camelid immunization services mandate qualification across North American and European veterinary facilities, fragmenting early-stage discovery capacity. Manufacturing concentrates in Belgium, the United States, and China, with Ghent and Liège hosting specialized fill-finish operations. Serum, recombinant media, and linker chemistry components feed from distinct supplier bases. Single-source vulnerability in heavy-chain antibody expertise creates bottleneck exposure. Distribution runs through pharmaceutical CDMO networks and centralized hospital pharmacy committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanobody market occupies a platform-transition phase where single-cell B-cell screening technology displaces legacy hybridoma workflows, compressing discovery timelines and reallocating capital toward automated infrastructure.
For Market Incumbents: Acquire captive GMP manufacturing capacity in Belgium or China ahead of EMA MDR enforcement deadlines. Secure exclusive partnerships with automated screening platform holders to defend discovery throughput against emerging AI-native entrants. Backward integration into camelid immunization services mitigates veterinary expertise scarcity. For New Entrants and Emerging Players: Capture radiolabeled imaging applications in surgical navigation where regulatory pathways remain less congested than oncology therapeutics. Target China's NMPA reform window for Asia-Pacific commercialization partnerships. License AI-driven discovery platforms to compress lead identification without building in-house automation. For Investors and Strategic Acquirers: The window for entry favors discovery-platform technology licensors with validated single-cell screening deployments and European regulatory affairs infrastructure. Long-term viability hinges on manufacturing scale pre-commitments ahead of biologics licensing deadlines. Watch FDA breakthrough therapy designation grants as inflection indicators for pipeline de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Discovery Platform Deployment | Machine learning algorithms trained on camelid immune repertoires compress lead identification timelines from months to weeks. |
| GMP Manufacturing Scale-Up | Belgium and China facility investments ahead of EMA MDR timelines secure commercial launch capacity for pipeline candidates. |
| Companion Diagnostic Integration | Biomarker testing protocol bundling expands addressable patient populations for oncology programs in United States academic medical centers. |
| Regulatory Approval Pathway Navigation | FDA breakthrough therapy designation and EMA conditional marketing authorization compress clinical evidence requirements for rare disease targets. |
| Intratumoral Delivery Format Development | Localized administration routes exploit nanobody tissue penetration advantages in solid tumor applications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. FDA biologics licensing submissions, EMA MDR technical documentation, ClinicalTrials.gov records, and GMP facility inspection databases furnished validation sources. Bottom-up therapeutic volume estimates and top-down market sizing triangulated across product type, application, end user, and delivery mode dimensions.
Granularity-level modeling treated therapeutic nanobodies, conjugated formats, diagnostic reagents, and engineered constructs as distinct regulatory and manufacturing cost structures. Patient population segmentation, administration route, and regional regulatory cluster variations informed volume projections across the analysis window. CAGRs derived from pipeline candidate progression rates, approval probability weightings, and pricing trajectory assumptions. Camelid immunization capacity constraints and GMP facility qualification timelines fed supply-side boundary conditions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA MDR enforcement timing, FDA accelerated approval pathway modifications, and NMPA biologics reform implementation. Deviation in camelid immunization service availability or serum price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Nanobiotechnology Market