
 Boron Nitride Nanotubes in Nanomedicine Market | 2026-2036
Boron Nitride Nanotubes in Nanomedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Boron Nitride Nanotubes in Nanomedicine Market Analysis
Project finance tied to university spinouts and government nanotechnology grants is reconfiguring which entrants can scale boron nitride nanotube production for medical use. BNNT, LLC leverages its specialized synthesis expertise to anchor supply for research-stage applications. American Elements sustains broad catalog distribution that competes across multiple advanced material categories. Nanothinx S.A. specializes in precision nanotube architectures that differentiate its offerings for targeted therapeutic research.
Boron nitride nanotubes in nanomedicine constitute cylindrical nanostructures composed of boron and nitrogen atoms arranged in hexagonal sheets, typically 1-100 nanometers in diameter with high thermal stability, electrical insulation, and biocompatibility that enable their use as drug carriers, imaging contrast agents, and neutron capture therapy enhancers in cancer treatment. The powder segment dominates current supply volumes due to its versatility in downstream formulation, while dispersion formats command premium positioning in injectable delivery development where homogeneous suspension stability proves critical. Oncology applications lead therapy area allocation as neutron capture therapy protocols advance, with cardiovascular and neurology segments trailing but attracting exploratory research investment.
FDA oversees Investigational New Drug applications and nanomaterial characterization standards in the United States, while EMA enforces similar safety and efficacy benchmarks through its nanomedicine reflection papers in Europe, and PMDA in Japan evaluates quality consistency for imported nanotube-based therapeutics. These regulators collectively shape development timelines by demanding extensive toxicological data and manufacturing reproducibility documentation before clinical authorization. Stakeholders must monitor evolving guidance documents on long-term biodistribution studies to anticipate submission requirements.
Market Dynamics
Neutron capture therapy protocols are compressing clinical development timelines for boron nitride nanotube therapeutics, forcing developers to synchronize manufacturing scale-up with evolving FDA and EMA nanomaterial guidance.
Growth Catalysts
- EMA Nanomedicine Reflection Papers:The European regulator's evolving framework creates compliance clarity that accelerates Investigational New Drug submissions for BNNT-based oncology candidates.
- Japan's radiotherapy infrastructure:PMDA's quality consistency protocols for imported nanotube therapeutics align with existing boron neutron capture therapy centers in Osaka and Tsukuba.
- Surface functionalization chemistry:Advances in covalent modification enable precise drug loading ratios that improve therapeutic index calculations for targeted delivery systems.
Market Restraints
- High-purity boron precursor costs:Isotope-enriched boron-10 feedstock volatility constrains production economics for neutron capture applications.
- Synthesis bottleneck concentration:Specialized high-temperature plasma synthesis capacity clusters among limited equipment operators, creating supply vulnerability.
- Carbon nanotube substitution:Established CNT drug delivery platforms compete for the same oncology research funding pools and investigator attention.
Strategic Opportunities
- German precision medicine clusters:Munich and Heidelberg research consortia offer co-development partnerships for next-generation radiotherapy enhancers.
- Cardiovascular stent coatings:BNNT's thermal stability and hemocompatibility properties open expansion beyond oncology into interventional cardiology device applications.
- ISO/TS 80004 nanotechnology standards:Emerging characterization protocols will reduce regulatory friction by harmonizing physicochemical measurement methodologies across jurisdictions.
Industry Challenges
- Toxicological specialist scarcity:Qualified nanotoxicologists capable of designing FDA-compliant biodistribution studies command premium compensation and extended recruitment timelines.
- Batch-to-batch physicochemical variability:Length and diameter distribution control in high-volume synthesis remains technically demanding, complicating regulatory filing consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boron Nitride Nanotubes in Nanomedicine Market |
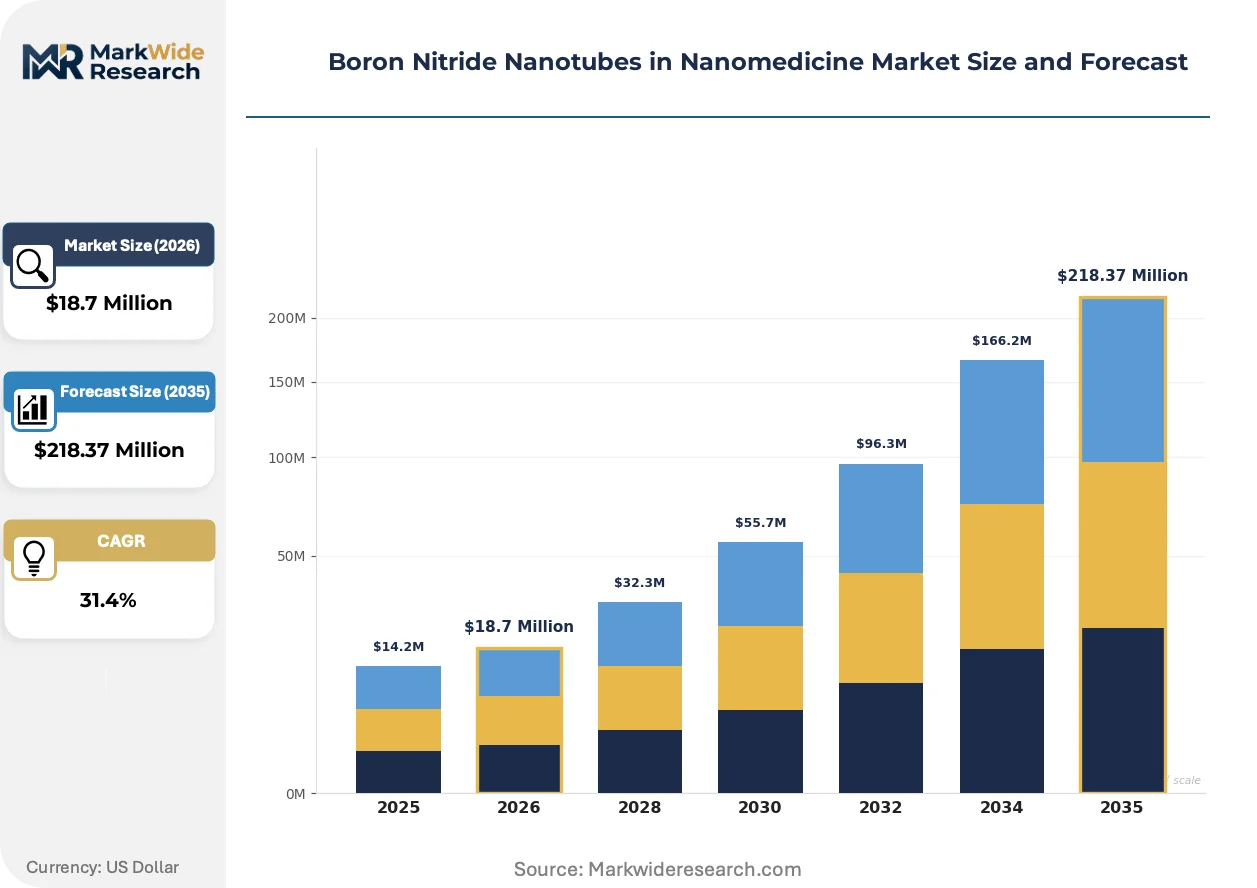
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispersion, Composite, Coating, Powder Therapy Area: Oncology, Cardiovascular, Neurology, Orthopedics Delivery Mode: Oral, Intravenous, Topical, Injectable End User: Hospitals, Research Labs, Clinics, Biopharma |
| Companies Covered | BNNT, LLC, Nanothinx S.A., American Elements, RUSNANO Group, Tokyo Chemical Industry Co., Ltd., Reade Advanced Materials, SkySpring Nanomaterials, Inc., Saint-Gobain Ceramics & Plastics, Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boron Nitride Nanotubes in Nanomedicine Market Emerging Trajectories
Functionalization chemistry advances are compressing the gap between research-grade materials and pharmaceutical-grade specifications, reshaping how developers approach clinical translation timelines.
Aqueous dispersion stabilization using phospholipid bilayer coatings is rendering obsolete organic solvent-based surface modification protocols that complicated downstream biocompatibility testing. Oncology formulation groups at major research hospitals are adopting these water-compatible systems within eighteen-month procurement cycles. The shift eliminates solvent residue validation burdens and accelerates preclinical safety package assembly.
REACH nanomaterial registration requirements in Europe are forcing toxicological data generation earlier in development pipelines than traditional small-molecule timelines. ECHA's 2022-2024 substance evaluation waves captured several boron-containing nanomaterials, establishing precedent for extensive environmental fate studies. Developers now front-load ecotoxicology budgets to avoid registration delays that would push European trial initiation past competitor windows.
Academic medical center procurement officers are consolidating supplier qualifications around ISO 13485-certified manufacturers, displacing catalog distributors for clinical-grade nanotube sourcing. This concentration favors entities with dedicated quality management systems over general advanced materials traders. The pattern is most pronounced in United States National Cancer Institute-designated centers where IND-enabling studies require documented GMP-adjacent production controls.
Boron Nitride Nanotubes in Nanomedicine Market Segmentation
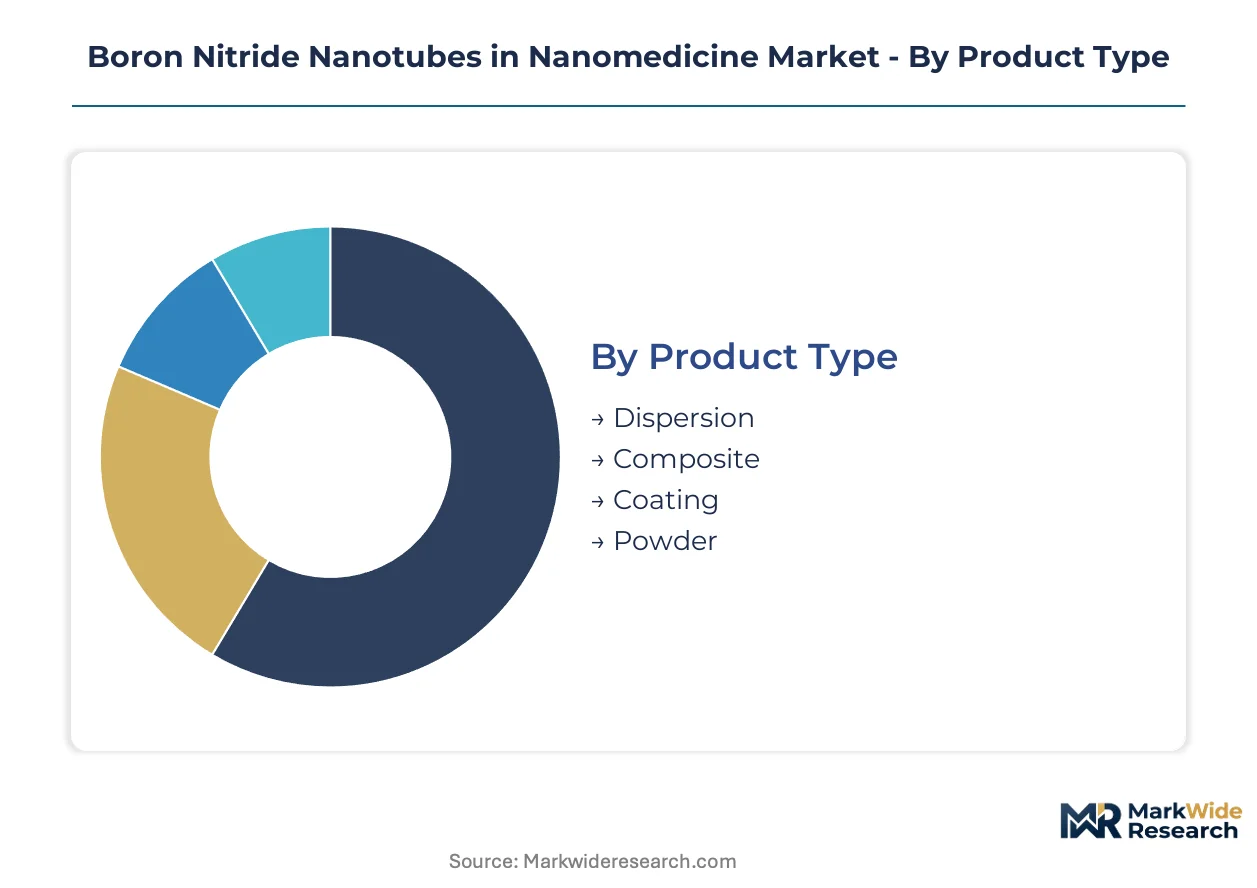
Segmentation in boron nitride nanotube nanomedicine reveals how physicochemical form factors, therapeutic targets, and institutional procurement capabilities determine commercial viability. Each dimension carries distinct regulatory pathways and manufacturing scale requirements that shape developer resource allocation.
Product Type:
After-sales technical support intensity varies sharply across product formats, with dispersion and coating formulations demanding sustained analytical troubleshooting that powder and composite segments rarely require.
- Powder:Raw hexagonal boron nitride nanotubes in aggregated particulate form serve as feedstock for downstream formulation. Demand concentrates in United States National Cancer Institute-designated centers where in-house functionalization capabilities reduce reliance on pre-processed materials. High-purity boron-10 isotope enrichment costs constrain neutron capture therapy applications.
- Dispersion:Aqueous suspensions stabilized through phospholipid bilayer coatings enable direct injectable formulation without solvent residue complications. Japanese PMDA quality consistency protocols favor these homogeneous systems for boron neutron capture therapy centers in Osaka and Tsukuba. Premium positioning reflects extended stability validation requirements.
- Composite:BNNT-polymer or BNNT-ceramic matrices integrate into implantable devices and structural scaffolds. Orthopedic and cardiovascular device manufacturers in Germany's precision medicine clusters drive specification development.
- Coating:Surface-deposited nanotube layers enhance stent hemocompatibility and radiotherapy applicator thermal management. Interventional cardiology device firms require batch-to-batch thickness reproducibility documentation.
By volume, Powder leads. By growth pace, Dispersion is ahead.
Therapy Area:
Cost tier stratification separates high-investment radiotherapy enhancement applications from exploratory therapeutic research with shorter validation horizons.
- Oncology:Neutron capture therapy protocols exploit boron-10's nuclear cross-section for targeted tumor cell destruction. Clinical development timelines compress as FDA nanomaterial guidance evolves alongside EMA reflection papers. United States and Japanese treatment centers anchor demand concentration.
- Cardiovascular:BNNT thermal stability and electrical insulation properties suit catheter and stent coating applications. German research consortia in Munich and Heidelberg advance hemocompatibility characterization methodologies.
- Neurology:Blood-brain barrier penetration studies remain preclinical, with academic medical centers evaluating surface-functionalized nanotubes for glioblastoma targeting. Toxicological specialist scarcity extends investigation timelines.
- Orthopedics:Composite scaffolds for bone regeneration leverage mechanical strength-to-weight ratios. ISO 13485-certified manufacturers displace catalog distributors as procurement officers consolidate supplier qualifications.
Oncology commands the dominant revenue share. Cardiovascular applications are climbing the fastest as device coating specifications mature.
Delivery Mode:
Customer type segmentation separates institutional procurement systems with dedicated nanomaterial handling protocols from distributed clinical networks with simpler logistical requirements.
- Intravenous:Direct bloodstream administration demands rigorous pyrogen and particulate testing. Injectable dispersion formats require documented GMP-adjacent production controls for IND-enabling studies.
- Injectable:Localized depot formulations including subcutaneous and intratumoral routes reduce systemic exposure concerns. ECHA REACH nanomaterial registration requirements front-load ecotoxicology budgets for European trial initiation.
- Oral:Gastrointestinal stability challenges limit current application, with exploratory research targeting inflammatory bowel disease indications through mucoadhesive formulations.
- Topical:Dermal and transdermal routes exploit BNNT thermal conductivity for wound healing and localized hyperthermia protocols. Simpler regulatory pathways attract early-stage developers.
Intravenous dominates current clinical translation activity. Injectable localized delivery is gaining share fastest as neutron capture therapy protocols advance.
End User:
Supply concentration among specialized synthesis operators creates tiered access patterns that favor research labs and biopharma with dedicated technical partnerships over general hospital procurement.
- Research Labs:Academic medical centers and university spinouts drive formulation innovation. Government nanotechnology grants in the United States, Japan, and Germany reconfigure scaling capabilities among entrants.
- Biopharma:Pharmaceutical developers integrate BNNT platforms into radiotherapy enhancer pipelines. Synchronization of manufacturing scale-up with evolving regulatory guidance compresses development timelines.
- Hospitals:Treatment centers with existing boron neutron capture therapy infrastructure in Osaka and Tsukuba anchor therapeutic demand. Procurement consolidation around ISO-certified manufacturers displaces catalog distribution.
- Clinics:Outpatient and specialized treatment facilities represent downstream demand with limited direct nanomaterial sourcing, relying on compounded formulations from hospital pharmacy networks.
Research Labs lead by active project volume. Biopharma partnerships are expanding most quickly as IND submissions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for high-purity boron-10 isotope feedstock shapes trade flows, with specialized synthesis capacity concentrating in nations with advanced plasma reactor infrastructure and radiotherapy research funding.
United States
National Cancer Institute-designated centers in Houston and Boston drive clinical translation demand for neutron capture therapy enhancers. FDA Investigational New Drug applications for nanomaterial-based therapeutics require extensive toxicological documentation that extends development timelines. Government nanotechnology grants through the National Science Foundation reconfigure scaling capabilities among university spinouts in California and Massachusetts.
Japan
PMDA quality consistency protocols for imported nanotube therapeutics align with existing boron neutron capture therapy infrastructure in Osaka and Tsukuba. METI funding for advanced materials research accelerates surface functionalization chemistry development. Tokyo-based medical device manufacturers integrate BNNT coatings into next-generation radiotherapy applicators.
Germany
Precision medicine clusters in Munich and Heidelberg advance hemocompatibility characterization methodologies for cardiovascular device applications. EMA nanomedicine reflection papers create compliance clarity that accelerates European trial initiation for oncology candidates. Bavarian research consortia specialize in composite scaffold development for orthopedic regeneration.
China
NMPA evolving standards for nanomaterial characterization shape domestic clinical development pathways. MIIT funding for advanced ceramics supports high-temperature synthesis capacity expansion in Jiangsu and Shandong provinces. Shanghai-based biopharma developers explore blood-brain barrier penetration applications for glioblastoma targeting.
Boron Nitride Nanotubes in Nanomedicine Market Vendor Landscape
On the supply side, the industry is fragmented across specialized synthesis operators, broad advanced materials distributors, and precision nanotube architects with divergent scale requirements. Three archetypes dominate: dedicated BNNT manufacturers with captive plasma reactor technology, catalog distributors competing across multiple nanomaterial categories, and functionalization specialists serving research-stage therapeutic development. Capacity expansion and strategic partnerships with academic medical centers constitute the primary competitive moves as developers synchronize manufacturing scale-up with evolving regulatory guidance.
Among specialized synthesis operators, BNNT, LLC and Nanothinx S.A. occupy positions anchored in distinct geographic and structural configurations. BNNT, LLC represents the dedicated manufacturer archetype with concentrated expertise in high-purity production. Nanothinx S.A., a Greek S.A.-structured entity, exemplifies precision architecture specialization for targeted therapeutic research. American Elements, as a California-based catalog distributor, competes across multiple advanced material categories with broad portfolio reach. These three entities illustrate the tiered competitive structure where technical depth, geographic proximity to research clusters, and regulatory compliance capabilities determine partnership viability with institutional procurement systems.
| Leading Market Players |
|---|
| BNNT, LLC |
| Nanothinx S.A. |
| American Elements |
| RUSNANO Group |
| Tokyo Chemical Industry Co., Ltd. |
| Reade Advanced Materials |
| SkySpring Nanomaterials, Inc. |
| Saint-Gobain Ceramics & Plastics, Inc. |
| Pfizer Inc. |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific air freight corridors from Osaka and Tsukuba to Houston and Boston carry isotope-enriched boron-10 feedstock at rates that compound with high-purity synthesis premiums, concentrating pricing power among plasma reactor operators while forcing downstream dispersion formulators to absorb logistics volatility or pass through to research-stage buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium positioning attaches to phospholipid-stabilized aqueous dispersions with documented GMP-adjacent production controls, while powder feedstock trades at standard tiers and unpurified research-grade material occupies economy positioning. Price differentiation rests on ISO 13485 certification status and boron-10 isotope enrichment grade. Cost compression in the standard tier is intensifying because carbon nanotube substitutes compete for oncology research funding pools. Academic medical centers with in-house functionalization capabilities prove least price-sensitive; distributed hospital pharmacy networks face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on high-temperature plasma synthesis equipment limit capacity expansion outside Japan, the United States, and Germany. Raw material flows draw from isotope-enriched boron-10 feedstock sourced through nuclear materials suppliers, specialized precursor chemical distributors, and high-purity gas providers. Single-source vulnerability concentrates in plasma reactor fabrication, where two equipment builders control global installed base. Distribution runs through ISO-certified manufacturers to National Cancer Institute-designated centers, displacing catalog distributors for clinical-grade sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: FDA and EMA nanomaterial guidance documents create submission precedent that locks out later entrants lacking extensive toxicological data packages.
For Market Incumbents: Insulate manufacturing scale-up advantages through backward integration into boron-10 isotope enrichment, securing feedstock against precursor cost volatility. Anchor partnerships with Osaka and Tsukuba treatment centers to entrench PMDA quality consistency protocols as competitive barriers against emerging synthesis operators. For New Entrants and Emerging Players: Establish a beachhead in cardiovascular stent coating applications, where German precision medicine clusters lack entrenched BNNT suppliers and hemocompatibility characterization demands align with smaller-scale precision synthesis capabilities. Pursue co-development partnerships with Munich and Heidelberg research consortia rather than direct competition in neutron capture therapy supply. For Investors and Strategic Acquirers: Carve-out targets emerge from university spinouts with captive plasma reactor technology and government nanotechnology grant backing but lacking IND submission experience. Long-term viability favors entities with documented GMP-adjacent production controls and ISO 13485 certification. Watch for EMA nanomedicine reflection paper finalization as inflection indicator accelerating European trial initiation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Enables procurement consolidation at NCI-designated centers displacing catalog distributors. |
| Backward Integration into Boron-10 Enrichment | Secures captive supply of isotope feedstock against nuclear materials market volatility. |
| PMDA Quality Consistency Protocol Alignment | Unlocks therapeutic demand from Osaka and Tsukuba neutron capture therapy infrastructure. |
| Phospholipid Bilayer Coating Scale-Up | Eliminates solvent residue validation burdens accelerating preclinical safety package assembly. |
| German Precision Medicine Cluster Partnership | Positions for cardiovascular device coating specifications advancing toward commercial validation. |
Methodological Framework
Initial hypotheses were tested against primary input from nanotoxicology specialists, plasma reactor equipment operators, regulatory affairs leads at EMA and FDA, hospital procurement officers at NCI-designated centers, and biopharma formulation executives. These interviews were cross-referenced with secondary validation from FDA Investigational New Drug filings, EMA nanomedicine reflection papers, ClinicalTrials.gov oncology protocol registrations, and REACH nanomaterial registration databases. Bottom-up demand modeling from therapy-area procurement volumes was reconciled with top-down supply capacity assessments from high-temperature synthesis equipment installations.
Demand-supply balance dynamics across the analysis window were projected through segmentation across product format, therapy area, delivery mode, and end-user procurement capability. CAGRs were derived from fitted growth curves calibrated to neutron capture therapy protocol advancement timelines and evolving nanomaterial regulatory guidance publication schedules. Forecast inputs incorporated boron-10 isotope feedstock availability constraints and academic medical center grant funding cycles.
Stress conditions across EMA guidance finalization timing, PMDA import protocol stringency, and boron-10 precursor cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory pathway convergence and synthesis capacity expansion feasibility. Material shifts in FDA nanomaterial characterization standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Nanotechnology Drug Delivery Market