
 Nanozymes Market | 2026-2036
Nanozymes Market Size, Share, and Industry Trends Forecast 2026-2036
Nanozymes Market Foresight
Multi-source procurement of nanozyme precursors is shifting toward vertically integrated in-house synthesis as supply security tightens. Novozymes A/S anchors European enzyme technology leadership through its Novonesis Group restructuring. NanoComposix competes in noble-metal nanostructure supply with tight quality specifications. Creative Enzymes specializes in custom catalytic formulations for research-scale buyers.
Nanozymes are artificial enzyme mimics—typically metal oxide, carbon, or hybrid nanomaterials with catalytic active sites that accelerate biochemical reactions under mild conditions, operating across pH ranges of 3–10 and temperatures from 20°C to 80°C. Their primary commercial purpose centers on replacing natural enzymes in cost-sensitive or stability-critical applications where protein denaturation limits performance. Metal-based nanozymes dominate current revenue pools due to established peroxidase-mimic platforms in diagnostic assays, while carbon-based variants capture the fastest expansion trajectory driven by graphene and quantum dot functionalization for environmental sensing. Biomedical applications concentrate margin pools in immunoassay and therapeutic delivery, whereas environmental remediation segments compete on volume throughput with thinner unit economics.
FDA regulates nanozyme-containing diagnostics as Class II or III medical devices under 21 CFR requirements, while EPA oversees environmental release thresholds for catalytic nanoparticles in remediation deployments. REACH registration obligations in Europe compel toxicity dossiers for metal-based formulations above one-tonne annual volumes. ISO 10993 biocompatibility standards shape product development roadmaps for pharmaceutical-facing suppliers. Stakeholders must monitor evolving nanomaterial classification thresholds across FDA, EPA, and ECHA frameworks to anticipate compliance cost escalations that could alter competitive economics.
Market Dynamics
Biomedical diagnostics manufacturers are compressing assay development timelines by substituting natural enzymes with metal-oxide nanozymes, triggering cascading demand for peroxidase-mimic platforms across immunoassay and point-of-care testing workflows.
Growth Catalysts
- China's NMPA pathway acceleration:Compressed review timelines for nanomaterial-based therapeutics are pulling commercialization schedules forward by 12-18 months for domestic and foreign applicants.
- Peroxidase-mimic assay standardization:Diagnostic kit manufacturers are embedding iron-oxide and cerium-oxide nanozymes into ELISA and lateral-flow platforms to eliminate cold-chain dependencies.
- East Asian manufacturing concentration:Shanghai and Suzhou industrial zones host vertically integrated precursor-to-assembly operations that shorten procurement lead times for biomedical device makers.
Market Restraints
- Metal precursor cost volatility:Platinum-group and rare-earth oxide feedstocks exhibit price swings that compress margin buffers for noble-metal nanostructure suppliers.
- REACH dossier burdens:ECHA registration obligations for metal-based formulations above one-tonne annual volumes impose six-figure compliance costs that deter mid-scale entrants.
- Natural enzyme residual preference:Pharmaceutical-grade therapeutic applications retain protein-enzyme specifications due to established toxicology profiles, limiting nanozyme penetration in injectable formats.
Strategic Opportunities
- Carbon-based platform expansion:Graphene-oxide and quantum-dot functionalization for environmental sensing applications opens volume markets outside biomedical pricing pressures.
- EPA remediation deployment thresholds:Relaxed catalytic nanoparticle release limits for groundwater treatment create first-mover advantages in industrial cleanup contracting.
- ISO 10993 biocompatibility certification:Early alignment with pharmaceutical-facing standards positions suppliers for therapeutic delivery partnerships as regulatory clarity emerges.
Industry Challenges
- Toxicology specialist scarcity:Nanomaterial safety assessment expertise concentrates in contract research organizations, inflating internal hiring costs for development-stage firms.
- Legacy assay validation protocols:Diagnostic laboratories require parallel testing runs against natural enzyme baselines, extending product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanozymes Market |
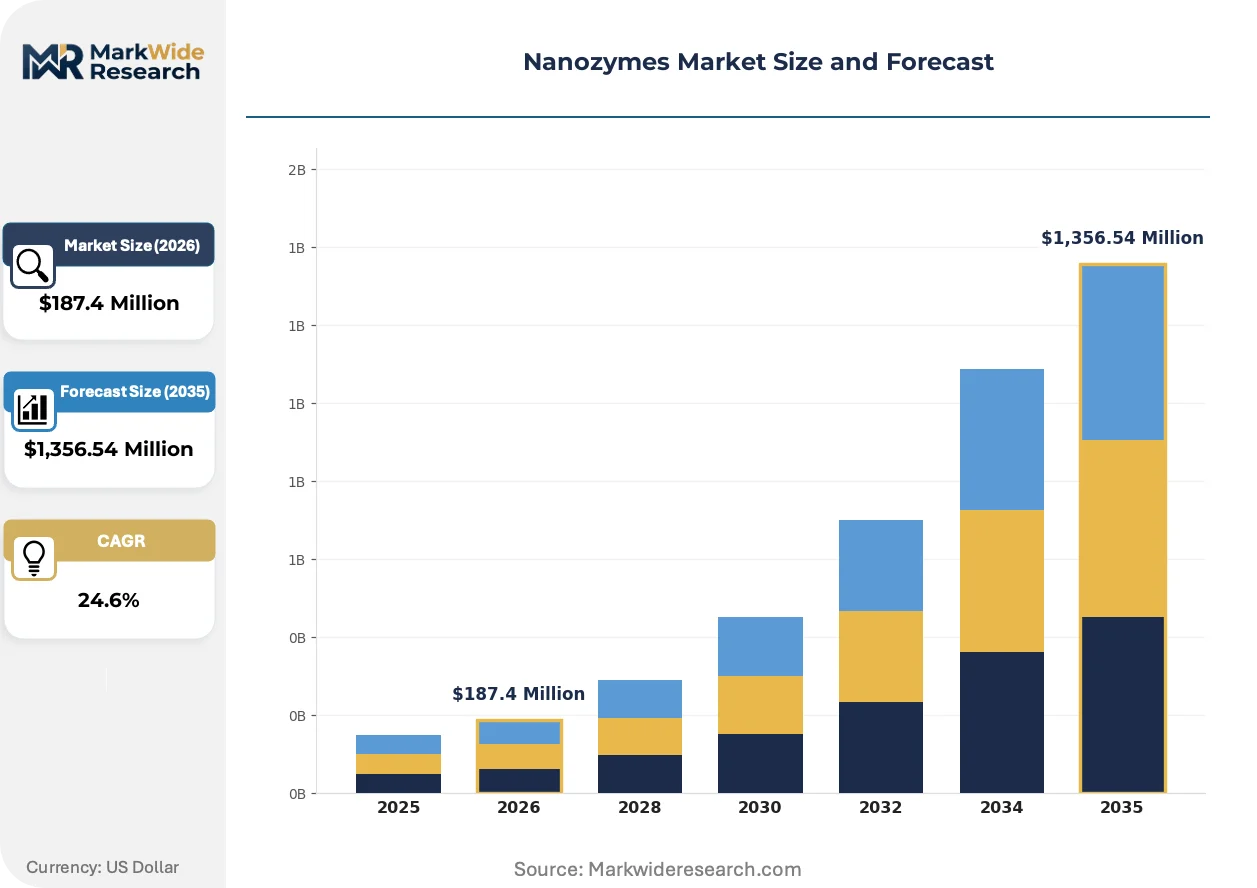
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,356.54 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-Based Nanozymes, Carbon-Based Nanozymes, Polymer Nanozymes, Hybrid Nanozymes Application: Biomedical Applications, Environmental Remediation, Agriculture, Industrial Catalysis Technology: Synthesis Techniques, Characterization Methods, Functionalization Approaches, Stabilization Techniques End User: Pharmaceutical Companies, Research Institutions, Agricultural Firms, Environmental Agencies |
| Companies Covered | Novozymes A/S (Novonesis Group), Cenyx Biotech Inc., NanoComposix, Nanozyme Inc., Profacgen, Creative Enzymes, EnzyPep B.V., Haydale Graphene Industries, Tanaka Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanozymes Market Shifts & Advancements
Hybrid nanomaterial architectures are displacing single-composition platforms by combining catalytic activity with magnetic or fluorescent properties, enabling multiplexed detection workflows that compress instrument footprint and reagent consumption simultaneously.
Graphene-oxide nanozymes with peroxidase-mimic functionality are expanding into agricultural pathogen detection kits, where Chinese and Brazilian crop-protection distributors are piloting field-deployable strips that eliminate laboratory infrastructure requirements. This convergence is compressing the addressable market for centralized diagnostic equipment while opening subscription-based consumable revenue streams.
REACH registration obligations are tightening substance dossier requirements for metal-oxide nanoparticles, compelling European suppliers to consolidate formulation lines and withdraw marginal SKUs rather than absorb per-variant toxicology costs. Carbon-based alternatives capture displaced demand as ECHA scrutiny intensifies on cerium and iron oxide classifications.
Diagnostic laboratories are unbundling after-sales technical support from reagent procurement contracts, instead sourcing nanozyme formulations through group purchasing organizations that centralize quality auditing and logistics. This pattern concentrates buying power in the United States and Germany, where hospital network consolidation has accelerated procurement rationalization programs.
Nanozymes Market Segmentation
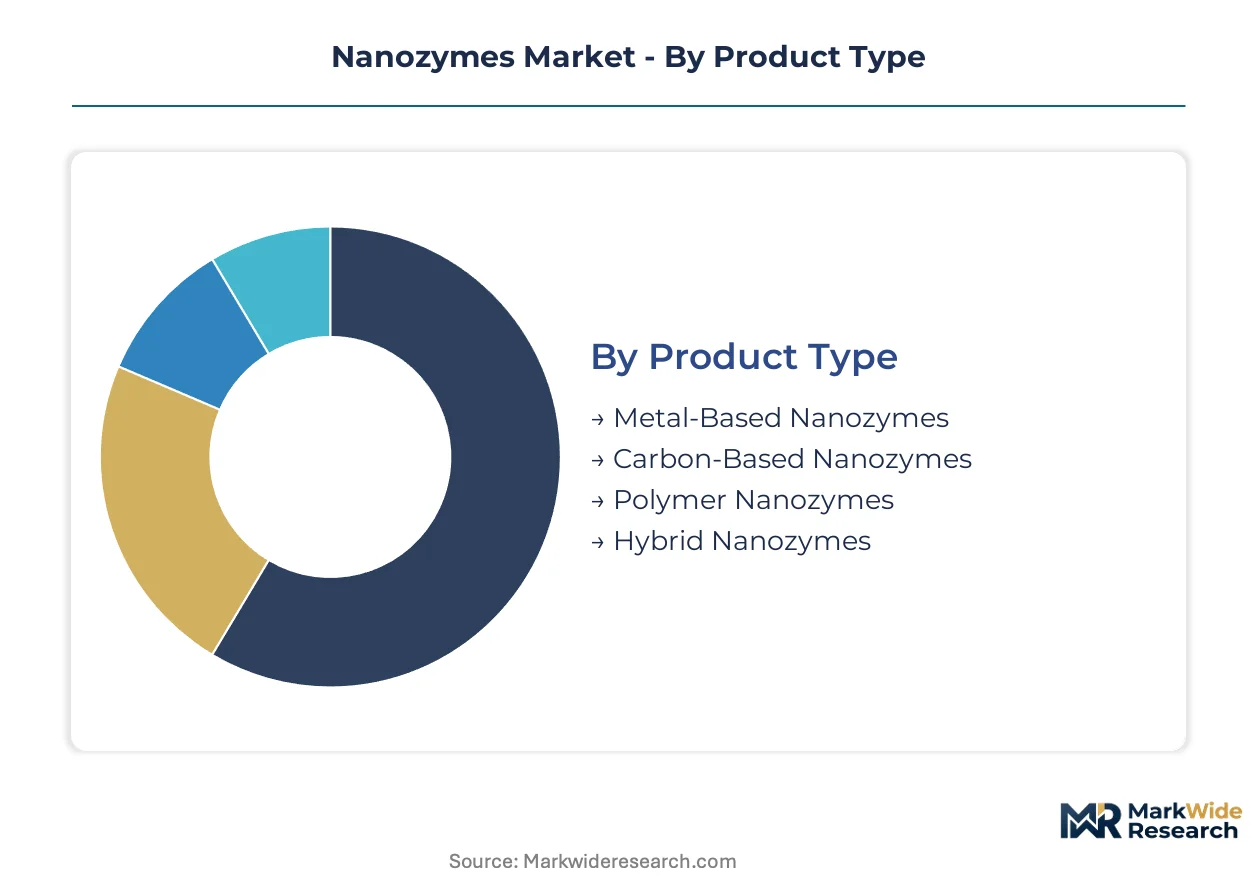
Nanozyme commercialization pathways diverge sharply by material chemistry and end-use performance requirements. Product type selection dictates manufacturing complexity, regulatory pathway, and margin structure across diagnostic, therapeutic, and industrial deployments.
Product Type:
Metal-based platforms anchor current revenue volumes while carbon-based variants command premium pricing in emerging applications.
- Metal-Based Nanozymes:Iron-oxide and cerium-oxide formulations deliver established peroxidase-mimic catalysis for ELISA and lateral-flow diagnostics. Shanghai and Suzhou manufacturing clusters concentrate supply for biomedical device makers seeking cold-chain elimination. Demand concentrates in immunoassay workflows where thermal stability outweighs unit cost sensitivity.
- Carbon-Based Nanozymes:Graphene-oxide and quantum-dot architectures enable environmental sensing applications with tunable optical properties. EPA remediation deployment thresholds are relaxing for groundwater treatment applications, opening industrial cleanup contracting opportunities outside biomedical pricing pressures. This segment is climbing the fastest as ECHA scrutiny intensifies on metal-oxide classifications.
- Polymer Nanozymes:Organic-inorganic hybrid scaffolds offer biocompatibility advantages for therapeutic delivery formulations under ISO 10993 development protocols.
- Hybrid Nanozymes:Multi-functional architectures combining magnetic separation with fluorescent detection enable multiplexed assay workflows that compress instrument footprint.
Today's leader: Metal-Based Nanozymes. Tomorrow's challenger: Carbon-Based Nanozymes.
Application:
Biomedical segments extract premium margins while environmental and agricultural deployments compete on throughput scale.
- Biomedical Applications:Immunoassay diagnostics and therapeutic delivery systems concentrate margin pools. NMPA pathway acceleration in China is compressing commercialization timelines for nanomaterial-based therapeutics by 12-18 months. FDA Class II and III device classifications under 21 CFR requirements shape product development roadmaps for pharmaceutical-facing suppliers.
- Environmental Remediation:Catalytic nanoparticle deployments for groundwater and soil treatment operate on volume economics with thinner unit margins. EPA oversight of environmental release thresholds creates first-mover advantages in industrial cleanup contracting for compliant formulations.
- Agriculture:Field-deployable pathogen detection strips are piloting in Chinese and Brazilian crop-protection distribution networks, eliminating laboratory infrastructure requirements.
- Industrial Catalysis:Process optimization applications in chemical manufacturing leverage thermal stability advantages over protein enzymes.
Biomedical Applications currently dominate value capture. Environmental Remediation is gaining share fastest as regulatory clarity emerges.
Technology:
Upstream process capabilities determine reproducibility and scale-up economics across manufacturing stages.
- Synthesis Techniques:Solvothermal and co-precipitation methods dominate metal-oxide production with established quality specifications.
- Characterization Methods:Transmission electron microscopy and X-ray photoelectron spectroscopy verify active site density and surface chemistry for batch release.
- Functionalization Approaches:Surface ligand engineering enables target specificity in diagnostic and therapeutic applications.
- Stabilization Techniques:Encapsulation and covalent immobilization extend operational lifetimes in harsh pH and temperature conditions.
Synthesis Techniques remain the critical bottleneck. Functionalization Approaches represent the steepest expansion trajectory as application diversity broadens.
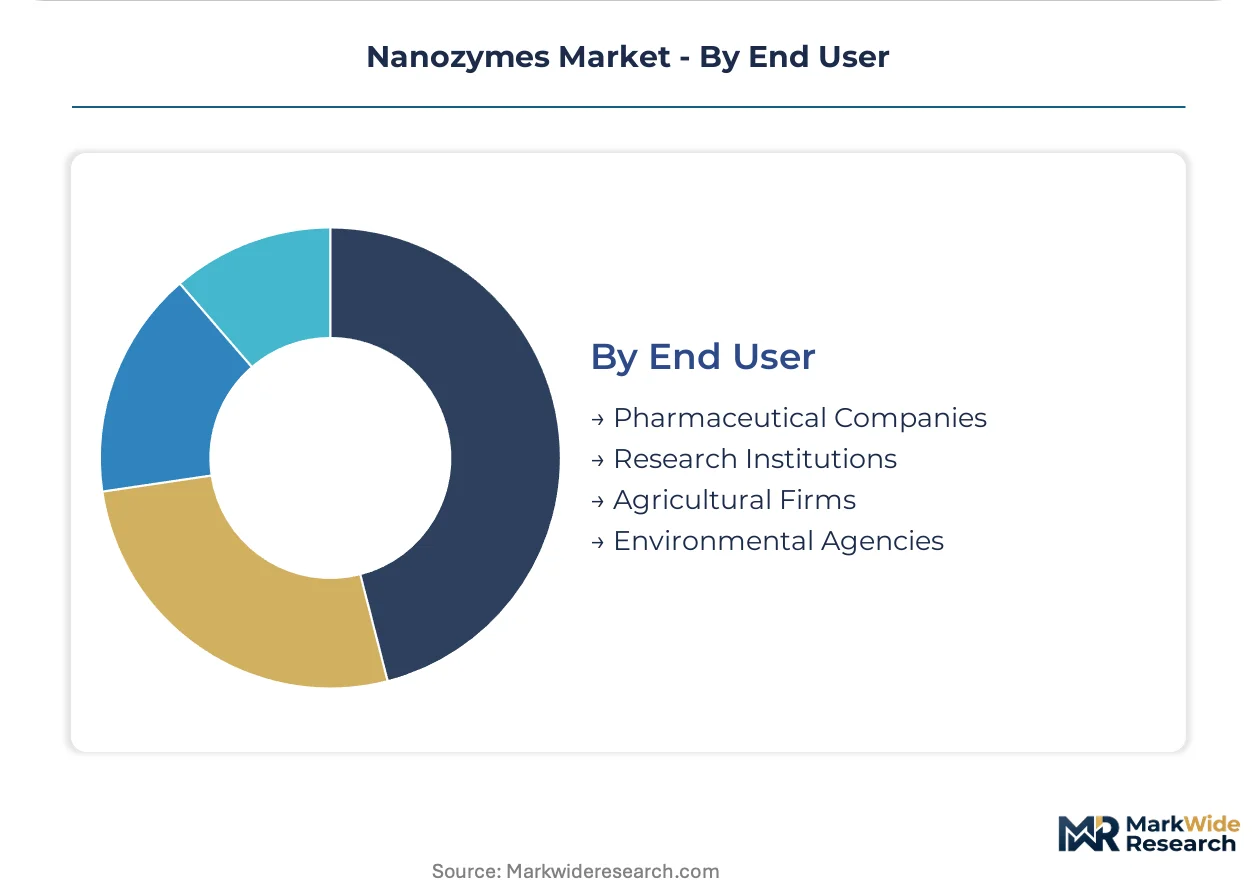
End User:
Procurement rationalization is concentrating buying power among consolidated hospital networks and research consortia.
- Pharmaceutical Companies:Therapeutic development programs require ISO 10993 biocompatibility certification and established toxicology profiles that favor partnerships with qualified suppliers.
- Research Institutions:Academic buyers source custom catalytic formulations through group purchasing organizations that centralize quality auditing and logistics.
- Agricultural Firms:Crop-protection distributors in China and Brazil are piloting subscription-based consumable models for field-deployable detection strips.
- Environmental Agencies:Public-sector remediation contractors prioritize EPA-compliant formulations with documented release thresholds.
Pharmaceutical Companies anchor premium demand. Agricultural Firms are expanding most quickly as distributed detection replaces centralized laboratory infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Suzhou anchor global nanozyme manufacturing capacity through vertically integrated precursor-to-assembly operations that compress procurement lead times for biomedical device makers. Diagnostic kit manufacturers in these clusters exploit NMPA pathway acceleration to pull commercialization schedules forward by 12-18 months.
China
Domestic demand concentrates in immunoassay diagnostics where iron-oxide and cerium-oxide nanozymes eliminate cold-chain dependencies. NMPA compressed review timelines for nanomaterial-based therapeutics pull commercialization schedules forward. Shanghai and Suzhou industrial zones host captive precursor synthesis and final assembly operations serving East Asian biomedical device supply chains.
United States
Diagnostic laboratories unbundle after-sales technical support from reagent procurement contracts, sourcing nanozyme formulations through group purchasing organizations that centralize quality auditing. FDA regulates nanozyme-containing diagnostics as Class II or III medical devices under 21 CFR requirements. Greater Boston and San Diego biotech clusters concentrate therapeutic delivery development partnerships.
Germany
Hospital network consolidation accelerates procurement rationalization programs that concentrate buying power in group purchasing organizations. REACH registration obligations under ECHA impose six-figure compliance costs for metal-based formulations above one-tonne annual volumes. Bavaria and Baden-Württemberg host precision diagnostic equipment manufacturers integrating nanozyme reagents into multiplexed assay workflows.
Japan
Pharmaceutical-grade therapeutic applications retain protein-enzyme specifications due to established toxicology profiles, limiting nanozyme penetration in injectable formats. METI oversees industrial catalysis deployment standards for process optimization applications. Kansai and Chubu industrial corridors concentrate chemical manufacturing operations leveraging thermal stability advantages over protein enzymes.
Brazil
Crop-protection distributors pilot field-deployable pathogen detection strips that eliminate laboratory infrastructure requirements, opening subscription-based consumable revenue streams. ANVISA regulates nanomaterial-containing agricultural inputs through evolving safety assessment protocols. São Paulo state anchors agribusiness distribution networks deploying graphene-oxide nanozyme platforms for agricultural pathogen detection.
Nanozymes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-based platform specialization and environmental sensing applications. The vendor base stratifies across three maturity tiers: legacy enzyme technology conglomerates with diagnostic reagent portfolios, mid-scale nanomaterial specialists with metal-oxide production capabilities, and development-stage firms commercializing graphene-oxide and quantum-dot architectures. Dominant competitive moves include backward integration into precursor synthesis to secure supply security, and strategic partnerships with diagnostic OEMs to embed nanozymes into standardized assay platforms.
Among enzyme technology conglomerates, Novozymes A/S represents established European leadership through its Novonesis Group restructuring. NanoComposix and Creative Enzymes exemplify contrasting specialization archetypes: the former occupies a position in noble-metal nanostructure supply with tight quality specifications, while the latter sits within custom catalytic formulation services for research-scale buyers. These three anchors illustrate the competitive spectrum from scale-driven standard supply to bespoke development partnerships.
| Leading Market Players |
|---|
| Novozymes A/S (Novonesis Group) |
| Cenyx Biotech Inc. |
| NanoComposix |
| Nanozyme Inc. |
| Profacgen |
| Creative Enzymes |
| EnzyPep B.V. |
| Haydale Graphene Industries |
| Tanaka Holdings |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap nanomaterial specialists in East Asia anchor supply security through backward integration into precursor synthesis, translating captive production into pricing discipline that resists volatility in platinum-group feedstock markets. This ownership pattern concentrates margin defense in Shanghai and Suzhou industrial zones where biomedical device makers source iron-oxide and cerium-oxide nanozymes for cold-chain elimination.
Pricing Analysis
Input-cost pass-through from rare-earth oxide and platinum-group metal feedstocks governs pricing stratification across metal-based nanozyme tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified therapeutic formulations from research-grade diagnostic reagents and bulk environmental remediation volumes. Cost compression in standard-tier metal-oxide platforms is intensifying because REACH dossier burdens consolidate supplier bases and reduce competitive pressure. Agricultural distributors in Brazil exhibit highest price sensitivity due to subscription-based consumable models, while pharmaceutical companies in Greater Boston and San Diego absorb premiums for biocompatibility certification.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated hospital networks and diagnostic kit manufacturers, while research-scale buyers source through group purchasing organizations that centralize quality auditing. Geographic supply concentration centers on China, South Korea, and Germany, with Shanghai and Suzhou hosting vertically integrated precursor-to-assembly operations. Raw material dependencies draw from Australian rare-earth oxide mines, South African platinum-group metal refiners, and Chinese graphene precursor producers. Single-source vulnerability in noble-metal nanostructure supply inflates procurement risk for peroxidase-mimic diagnostic platforms. Distribution runs through biomedical device OEMs embedding nanozymes into standardized ELISA and lateral-flow assay workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanozymes market reads as a late-cycle quality story where diagnostic manufacturers are substituting natural enzymes with metal-oxide platforms to compress assay development timelines and eliminate cold-chain infrastructure. This demand-shift toward thermally stable, premium-specification catalytic materials rewards suppliers with established biocompatibility certification and regulatory dossier completion.
For Market Incumbents: Hedge against carbon-based platform displacement by securing graphene-oxide and quantum-dot functionalization capabilities through targeted R&D partnerships or specialist acquisitions. Backward integration into rare-earth oxide precursor synthesis defends margin buffers against feedstock volatility that compresses noble-metal nanostructure economics. Monitor ECHA classification tightening on cerium and iron oxide formulations, which threatens to accelerate demand migration toward carbon-based alternatives. For New Entrants and Emerging Players: Begin with environmental sensing applications where EPA remediation deployment thresholds are relaxing for groundwater treatment, creating first-mover contracting advantages outside biomedical pricing pressures. Agricultural pathogen detection strips in Brazilian and Chinese crop-protection distribution networks represent the most penetrable white-space segment, with subscription-based consumable models replacing centralized laboratory infrastructure. Pursue direct partnerships with regional agribusiness distributors rather than competing for consolidated pharmaceutical company procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale nanomaterial specialists with metal-oxide production capabilities facing REACH compliance cost escalation, creating distressed acquisition opportunities for platforms with transferable synthesis expertise. Long-term viability over the five-to-ten year window hinges on carbon-based platform transition completion and therapeutic delivery regulatory clarity emergence. Watch NMPA approval velocity for nanomaterial-based therapeutics as the inflection indicator signaling premium valuation re-rating for biocompatibility-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Biocompatibility Certification | Positions suppliers for pharmaceutical partnerships as FDA therapeutic clarity emerges. |
| Backward Integration into Precursor Synthesis | Captive rare-earth oxide supply secures margin buffers against feedstock volatility. |
| Carbon-Based Platform Expansion | Graphene-oxide functionalization opens EPA-compliant environmental remediation contracting. |
| NMPA Pathway Acceleration Partnership | Compressed review timelines pull commercialization schedules forward for domestic applicants. |
| Agricultural Distribution Channel Development | Field-deployable strip subscriptions replace laboratory infrastructure in Brazilian crop-protection networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with diagnostic kit manufacturers, regulatory affairs specialists at nanomaterial suppliers, hospital procurement managers, and agricultural distributor executives with secondary validation from FDA 510(k) filings, NMPA approval databases, ECHA REACH registration records, and EPA environmental release guidance documents. Bottom-up demand modeling from end-use segment procurement patterns was triangulated against top-down supply capacity assessments from manufacturing cluster surveys.
Comparable-period anchoring established baseline reference points from historical diagnostic reagent substitution trends and nanomaterial therapeutic development timelines, with projections extending across the analysis window. Segmentation dimensions modeled include material chemistry platform, application vertical, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across biomedical diagnostics, environmental remediation, and agricultural detection deployment trajectories, incorporating NMPA pathway acceleration effects and ECHA classification tightening scenarios as scenario-weighted inputs.
Several conditions sit outside the modeled scope, including unforeseen nanotoxicology reclassification by FDA or ECHA, disruptive natural enzyme stabilization breakthroughs, and geopolitical trade restrictions on rare-earth oxide supply chains. Forecasts reflect assumptions about regulatory pathway stability and substitution elasticity in diagnostic workflows. Periodic stress-testing of base assumptions is recommended against emerging biocompatibility data and carbon-based platform performance benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Nanobody Market