
 Nanopharmaceuticals Market | 2026-2036
Nanopharmaceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Nanopharmaceuticals Market Intelligence
Multi-source API sourcing for lipid and polymer excipients is recalibrating how nanopharmaceutical developers secure supply chain resilience. Gilead Sciences leverages vertical integration in liposomal manufacturing to control quality from raw material to finished dose. Novartis anchors its position through sustained investment in polymeric nanoparticle platforms for oncology. Alnylam Pharmaceuticals differentiates via specialized expertise in lipid nanoparticle delivery for RNA therapeutics.
Nanopharmaceuticals comprise drug products engineered with at least one dimension in the 1-100 nanometer range, utilizing liposomes, polymeric nanoparticles, or metallic cores to enhance bioavailability, target tissue specificity, or controlled release kinetics. These formulations primarily serve to improve therapeutic indices of small molecules, biologics, and nucleic acids across oncology, neurology, and infectious disease applications. Liposomes dominate current revenue pools due to established manufacturing infrastructure and payer familiarity, while polymeric nanoparticles represent the fastest-expanding segment driven by mRNA vaccine platform spillover and personalized medicine pipelines. Intravenous delivery maintains structural primacy for oncology indications, though targeted delivery modalities are capturing margin expansion as precision medicine protocols proliferate in major hospital systems.
FDA's nanotechnology regulatory framework, EMA's quality guidelines for nanomedicines, and ISO/TS 19601 standards collectively shape product characterization requirements, batch release criteria, and cross-border market access for developers. These standards elevate barriers for entrants lacking analytical capabilities but reward incumbents with validated quality systems and prior regulatory approvals. Stakeholders must monitor evolving pharmacovigilance expectations for long-circulating nanocarriers and alignment between regional health technology assessment bodies on value demonstration for premium nanotherapies.
Market Dynamics
The transition from batch to continuous manufacturing for lipid nanoparticles is compressing production timelines and forcing asset reconfiguration across contract development organizations. This shift demands synchronized upstream and downstream process validation while recalibrating quality assurance protocols for real-time release testing.
Growth Catalysts
- FDA's 2022 Nanotechnology Guidance:Streamlined characterization requirements accelerate IND-to-NDA timelines for developers with validated analytical platforms.
- Oncology precision protocols:Academic medical centers in the United States, Germany, and Japan expand nanodrug formularies to improve therapeutic indices for checkpoint inhibitors.
- Lipid excipient diversification:Multi-source API sourcing strategies reduce dependency on single-supplier ionizable lipids.
Market Restraints
- High-purity phospholipid concentration:Manufacturing of hydrogenated soy phosphatidylcholine concentrates among three specialized chemical suppliers in Germany and Japan.
- Complex bioequivalence pathways:EMA's reflection papers create prolonged regulatory uncertainty for follow-on nanomedicines.
- Capital intensity of aseptic fill-finish:Dedicated isolator lines for nanosuspensions require $40-80 million facility investments.
Strategic Opportunities
- Neurological indication expansion:Blood-brain barrier penetration capabilities open CNS therapeutic categories previously inaccessible to biologics.
- India's PLI scheme for pharmaceuticals:Domestic manufacturing incentives attract nanopharmaceutical production for emerging market supply.
- mRNA platform spillover:COVID-19 vaccine lipid nanoparticle expertise transfers to personalized cancer vaccine pipelines.
Industry Challenges
- Analytical method standardization:Particle size distribution and surface charge characterization lack harmonized protocols across FDA, EMA, and PMDA.
- Specialized workforce scarcity:Formulation scientists with nanoscale drug delivery expertise command premium compensation and extended recruitment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanopharmaceuticals Market |
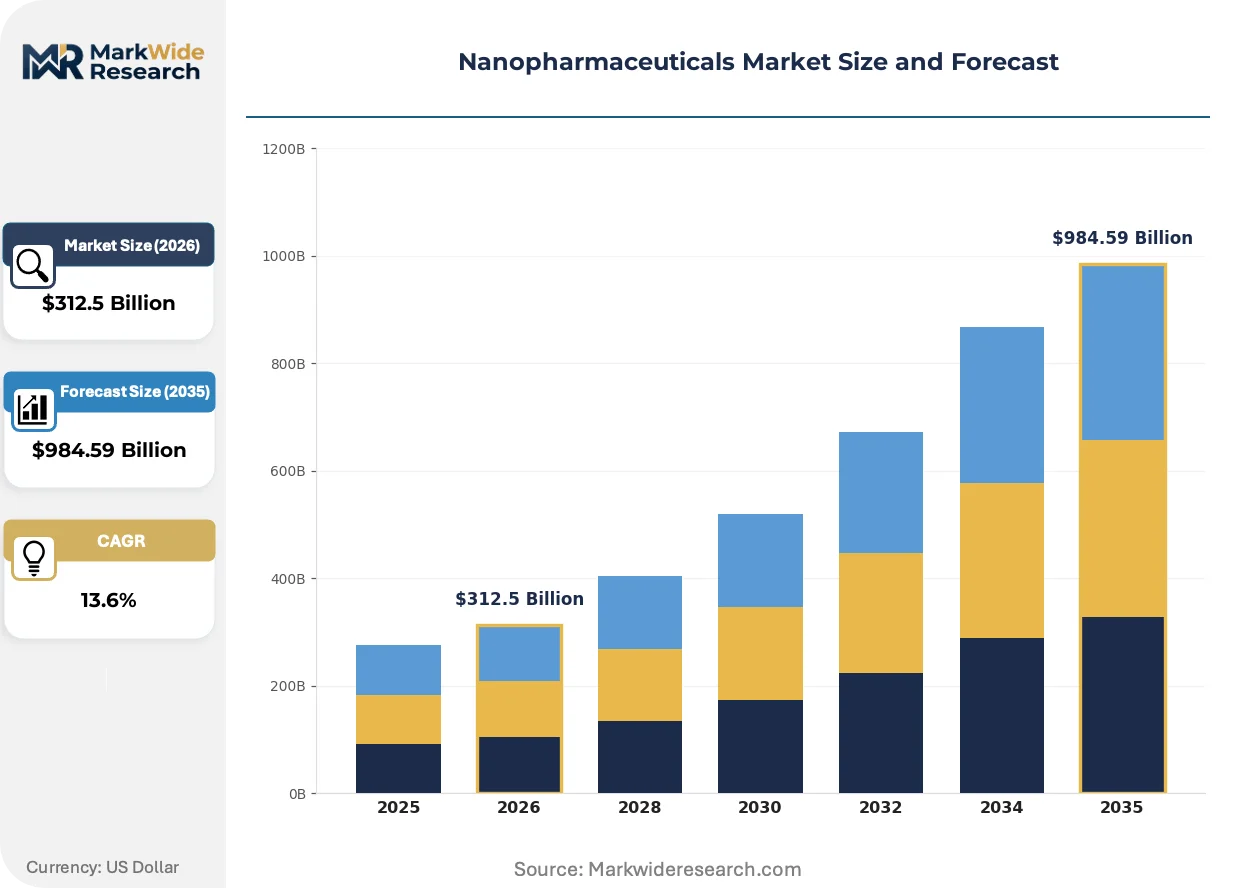
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $984.59 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomes, Nanocrystals, Polymeric Nanoparticles, Dendrimers, Solid Lipid Nanoparticles, Metallic Nanoparticles Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases, Dermatology, Immunology Delivery Mode: Oral, Intravenous, Transdermal, Inhalation, Targeted Delivery, Implantable Systems End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations |
| Companies Covered | Gilead Sciences, Sun Pharmaceutical, Amgen, AstraZeneca, Novartis, Alnylam Pharmaceuticals, Regeneron Pharmaceuticals, Merck, Vertex Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanopharmaceuticals Market Strategic Shifts & Innovations
Convergence between synthetic biology and materials science is generating programmable nanocarriers with stimuli-responsive release kinetics. These architectures promise to resolve the long-standing tension between circulation stability and target tissue payload delivery.
Active targeting ligands—antibodies, aptamers, and small molecules—are integrating into liposomal and polymeric platforms to achieve tissue-specific accumulation beyond passive enhanced permeability and retention effects. Oncology departments at tertiary hospitals in the United States and Japan pilot these constructs in combination with companion diagnostics. The structural consequence is fragmenting addressable markets into biomarker-defined subpopulations requiring matched therapeutic-diagnostic pairs.
EMA's quality guidelines for nanomedicines, finalized after extensive stakeholder consultation, mandate comprehensive physicochemical characterization datasets for marketing authorization applications. Developers must demonstrate batch-to-batch consistency for critical quality attributes including particle morphology and drug loading efficiency. Follow-on nanomedicine sponsors in Europe face heightened evidentiary burdens for establishing equivalence to reference products.
Hospital procurement committees increasingly require health technology assessment evidence demonstrating cost-effectiveness per quality-adjusted life year for premium nanotherapies. Payer infrastructure in Germany and Japan has adapted faster than United States commercial insurance formularies. This behavioral shift concentrates initial launch sequencing in markets with established value-based reimbursement mechanisms.
Nanopharmaceuticals Market Segmentation
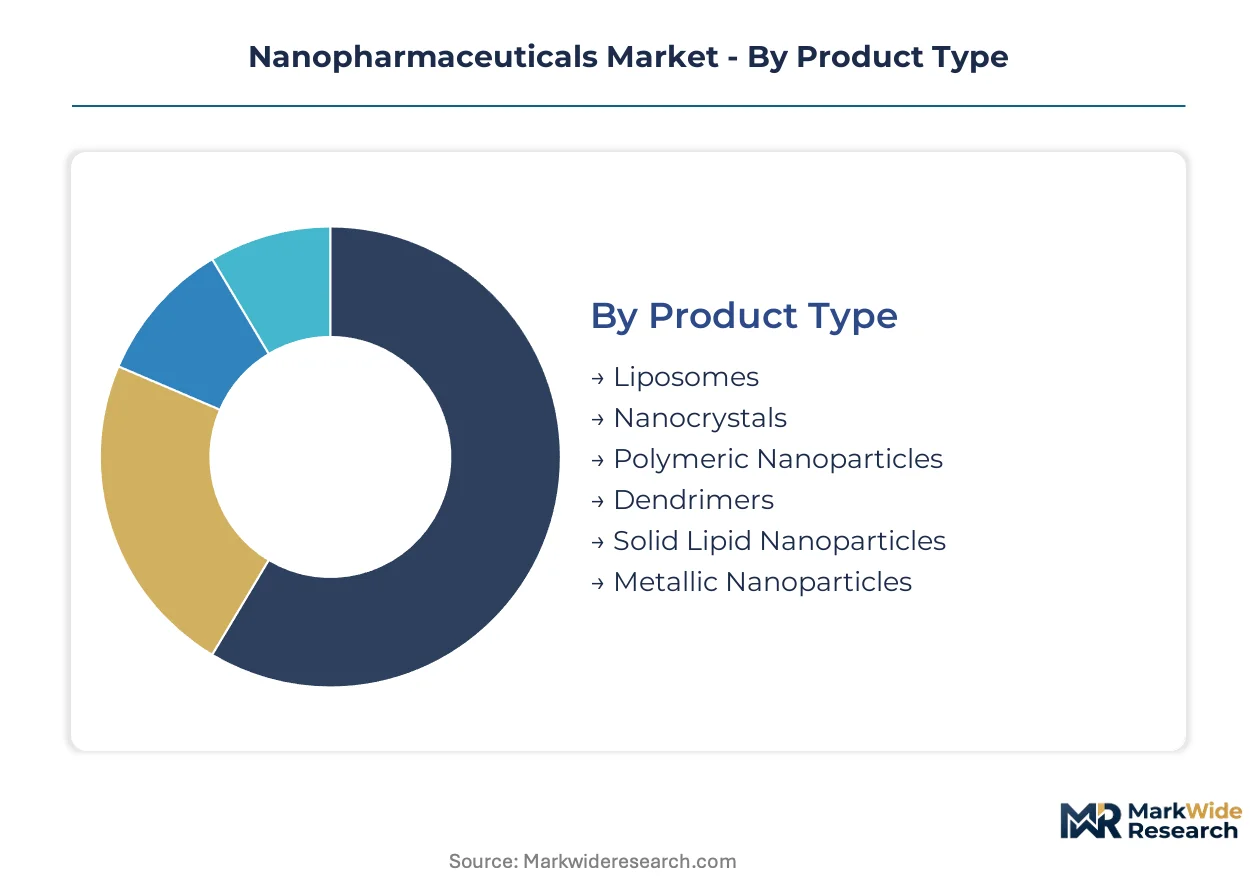
Segmentation in nanopharmaceuticals reveals how formulation architecture, clinical application, and delivery logistics create distinct competitive arenas with divergent margin profiles and regulatory pathways. Buyers prioritize different performance attributes depending on whether they operate in commercial manufacturing, clinical development, or academic research environments.
Product Type:
Cost tier differentiation separates established manufacturing platforms from emerging technologies requiring specialized capital investment and analytical capabilities.
- Liposomes:Phospholipid bilayer vesicles encapsulating hydrophilic and hydrophobic payloads with proven scalability for oncology applications. Academic medical centers in the United States, Germany, and Japan anchor demand through expanded nanodrug formularies for checkpoint inhibitor combinations.
- Polymeric Nanoparticles:Biodegradable polymer matrices enabling controlled release kinetics and surface functionalization for active targeting. Demand concentrates in mRNA vaccine platform spillover applications and personalized medicine pipelines where PLGA-PEG architectures dominate clinical translation.
- Nanocrystals:Pure drug particles stabilized with surface-active agents to enhance dissolution velocity for poorly soluble compounds.
- Dendrimers:Hyperbranched macromolecules with precise molecular weights enabling multivalent drug conjugation and imaging agent coordination.
- Solid Lipid Nanoparticles:Lipid matrices combining biocompatibility advantages of liposomes with enhanced physical stability for dermal and oral routes.
- Metallic Nanoparticles:Gold and iron oxide cores serving diagnostic imaging and photothermal ablation functions alongside therapeutic delivery.
Liposomes lead volumes today; polymeric nanoparticles are gaining share fastest.
Therapy Area:
Application urgency and reimbursement infrastructure determine which therapeutic categories absorb premium nanocarrier costs.
- Oncology:Tumor-targeted delivery addressing the therapeutic index limitations of cytotoxic agents and enabling combination immunotherapy protocols. Precision medicine proliferation in major hospital systems drives formulary expansion for liposomal doxorubicin and nab-paclitaxel equivalents.
- Neurology:Blood-brain barrier penetration capabilities opening CNS therapeutic categories previously inaccessible to biologics and nucleic acids. Academic medical centers pilot these constructs for glioblastoma and neurodegenerative indications where conventional delivery fails.
- Cardiovascular:Targeted delivery to atherosclerotic plaques and ischemic myocardium for regenerative and anti-inflammatory payloads.
- Infectious Diseases:Antimicrobial encapsulation overcoming resistance mechanisms and improving pharmacokinetic profiles for recalcitrant pathogens.
- Dermatology:Transdermal and topical formulations addressing psoriasis, melanoma, and cosmetic applications.
- Immunology:Vaccine adjuvant and immune tolerance induction applications leveraging nanocarrier lymphatic targeting.
Oncology commands the dominant revenue position; neurology shows the steepest expansion trajectory.
Delivery Mode:
Customer operational capabilities and patient compliance requirements shape route selection across hospital, outpatient, and home settings.
- Intravenous:Direct systemic administration maintaining structural primacy for oncology indications requiring precise dose control and rapid therapeutic onset. Tertiary hospital infusion centers anchor demand with established handling protocols for nanosuspensions.
- Targeted Delivery:Active ligand-mediated accumulation achieving tissue specificity beyond passive enhanced permeability and retention effects. Oncology departments at tertiary hospitals in the United States and Japan pilot antibody- and aptamer-conjugated constructs with companion diagnostics.
- Oral:Patient-preferred route driving formulation innovation for bioavailability enhancement of poorly soluble compounds.
- Transdermal:Non-invasive administration for chronic conditions and localized dermatological action.
- Inhalation:Pulmonary deposition for respiratory and systemic delivery of macromolecules.
- Implantable Systems:Long-acting depot formulations for contraception, hormonal therapy, and chronic pain management.
Intravenous administration retains volume leadership; targeted delivery modalities capture the fastest margin expansion.
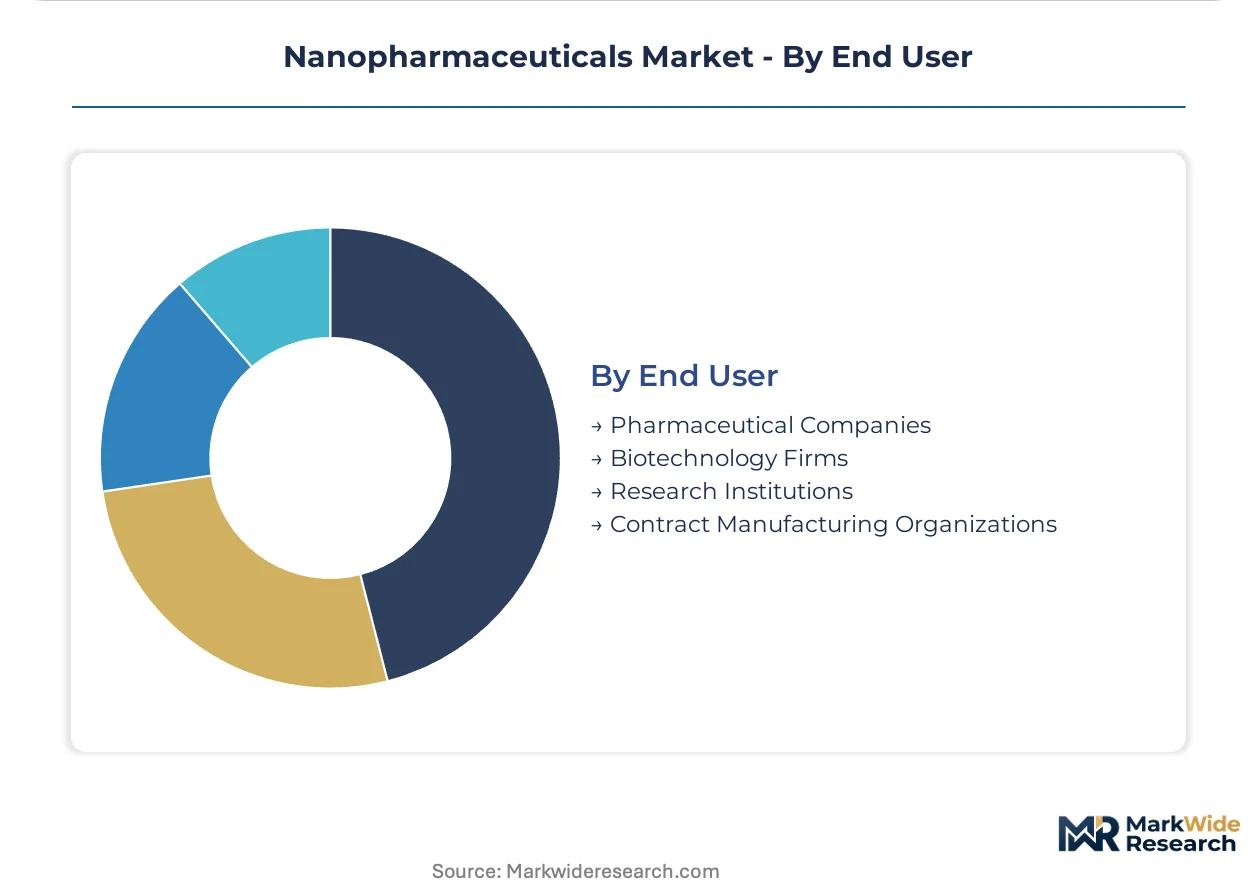
End User:
Volume scale and technical sophistication separate commercial manufacturers from development-stage organizations with distinct procurement behaviors.
- Pharmaceutical Companies:Large-scale commercial manufacturing demanding validated quality systems and regulatory precedents for market authorization. Gilead Sciences exemplifies vertical integration strategies controlling quality from raw material to finished dose.
- Biotechnology Firms:Platform technology developers prioritizing specialized expertise in lipid nanoparticle or polymeric architectures for nucleic acid delivery. Alnylam Pharmaceuticals anchors this segment through RNA therapeutic pipelines.
- Research Institutions:Academic laboratories requiring small-batch flexibility and early-stage characterization support for proof-of-concept studies.
- Contract Manufacturing Organizations:Multi-client facilities investing in continuous manufacturing transitions and real-time release testing capabilities for lipid nanoparticles.
Pharmaceutical companies dominate current procurement volumes; biotechnology firms are expanding their share most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping nanopharmaceutical production geography as developers migrate manufacturing toward jurisdictions with favorable cost-of-compliance structures while maintaining FDA and EMA market access.
United States
Oncology precision protocols at academic medical centers in Boston and Houston are expanding nanodrug formularies for checkpoint inhibitor combinations. FDA's 2022 nanotechnology guidance accelerates IND-to-NDA timelines for developers with validated analytical platforms. The Greater Boston cluster anchors commercial manufacturing with specialized aseptic fill-finish capabilities.
Germany
High-purity phospholipid manufacturing concentrates among specialized chemical suppliers in the Rhine-Ruhr region, creating supply-side dependencies for liposomal formulations. EMA's quality guidelines for nanomedicines mandate comprehensive physicochemical characterization datasets for marketing authorization applications. The Munich-Stuttgart corridor hosts contract development organizations investing in continuous manufacturing transitions for lipid nanoparticles.
Japan
PMDA alignment with ISO/TS 19601 standards shapes product characterization requirements for batch release criteria in the Tokyo-Osaka pharmaceutical corridor. METI funding for advanced pharmaceutical manufacturing supports domestic production incentives for emerging market supply. The Kansai region pilots active targeting ligand constructs with companion diagnostics at tertiary hospital networks.
India
Domestic manufacturing incentives under the PLI scheme for pharmaceuticals attract nanopharmaceutical production for emerging market supply chains. CDSCO regulatory pathways for nanomedicines are evolving toward harmonization with WHO prequalification standards. The Hyderabad-Bengaluru corridor develops specialized workforce pipelines for formulation scientists with nanoscale drug delivery expertise.
Switzerland
Swissmedic's alignment with EMA reflection papers creates regulatory clarity for follow-on nanomedicines while maintaining premium pricing infrastructure. Basel-Zurich industrial clusters concentrate polymeric nanoparticle platform development for personalized medicine pipelines. The country's value-based reimbursement mechanisms concentrate initial launch sequencing for premium nanotherapies.
Nanopharmaceuticals Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized delivery architectures and nucleic acid platforms. The vendor base stratifies across three maturity tiers: vertically integrated pharmaceutical conglomerates controlling quality from raw material to finished dose; biotechnology specialists with platform technology depth; and contract manufacturing organizations investing in continuous process capabilities. Dominant competitive moves include backward integration into lipid excipient supply and strategic partnerships for blood-brain barrier penetration technologies.
Within the vertically integrated tier, Gilead Sciences exemplifies upstream control over liposomal manufacturing quality systems. Among biotechnology specialists, Alnylam Pharmaceuticals occupies a position representing specialized expertise in lipid nanoparticle delivery for RNA therapeutics. Novartis anchors the polymeric nanoparticle platform segment through sustained investment in oncology applications. These three entities collectively represent the strategic archetypes shaping competitive dynamics: captive supply integration, nucleic acid delivery specialization, and polymeric platform scale.
| Leading Market Players |
|---|
| Gilead Sciences |
| Sun Pharmaceutical |
| Amgen |
| AstraZeneca |
| Novartis |
| Alnylam Pharmaceuticals |
| Regeneron Pharmaceuticals |
| Merck |
| Vertex Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
EMA's quality guidelines for nanomedicines gate qualified supply for premium-tier nanotherapies, as batch-to-batch consistency requirements concentrate manufacturing among validated producers with analytical capabilities. Payer infrastructure in Germany and Japan rewards these compliant suppliers with value-based reimbursement access, while cost-sensitive emerging markets absorb economy-tier liposomal generics from multi-source API producers.
Pricing Analysis
Input-cost pass-through from high-purity phospholipid and ionizable lipid excipients anchors pricing stratification across premium, standard, and economy tiers. Price differentiation rests on certification grade against ISO/TS 19601 and FDA nanotechnology guidance compliance, plus volume scale for contract manufacturing organizations. Cost compression in the economy tier intensifies as Indian PLI scheme beneficiaries expand liposomal generic output. Biotechnology firms with RNA therapeutic pipelines show least price sensitivity due to platform valuation premiums, while hospital procurement committees in emerging markets exhibit highest sensitivity to per-dose costs.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr region, Greater Boston, and the Tokyo-Osaka corridor anchor hub-and-spoke patterns for temperature-sensitive nanosuspensions. Manufacturing concentrates in Germany, the United States, and Japan for high-purity phospholipids and specialized aseptic fill-finish capabilities. Raw material dependencies include hydrogenated soy phosphatidylcholine, synthetic ionizable lipids, and PLGA-PEG copolymers. Single-source vulnerability for ionizable lipids from specialized chemical suppliers creates structural risk. Distribution runs through validated cold-chain logistics with real-time release testing protocols at contract development organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanopharmaceuticals market compounds steadily as oncology precision protocols at academic medical centers institutionalize nanodrug formularies for checkpoint inhibitor combinations. Regulatory clarity from FDA and EMA frameworks reduces approval risk premiums for validated developers.
For Market Incumbents: Deepen backward integration into lipid excipient supply to defend against emerging entrant cost advantages from India's PLI scheme beneficiaries. Add aseptic fill-finish capacity in the Munich-Stuttgart corridor where EMA quality guidelines concentrate demand for compliant manufacturing. Certification investment against evolving pharmacovigilance expectations for long-circulating nanocarriers remains essential.
For New Entrants and Emerging Players: Enter via blood-brain barrier penetration capabilities for neurological indications, the steepest-expansion therapeutic category with lowest incumbent platform saturation. Target academic medical center pilot programs in Japan's Kansai region for active targeting ligand constructs with companion diagnostics. License mRNA lipid nanoparticle expertise from COVID-19 vaccine technology transfers as the go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized formulation scientists with nanoscale drug delivery expertise because workforce scarcity commands premium compensation and extended recruitment cycles. Five-to-ten year viability favors biotechnology specialists with validated RNA therapeutic platforms over commodity liposomal generic producers. Watch PMDA alignment with ISO/TS 19601 standards as the signal for Japanese market access inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA nanotechnology guidance streamlines IND-to-NDA timelines for compliant developers. |
| Backward Integration | Gilead Sciences controls liposomal quality from phospholipid raw material to finished dose. |
| Manufacturing Scale-Up | Continuous manufacturing transitions compress lipid nanoparticle production timelines at contract organizations. |
| Pipeline Diversification | Novartis sustains polymeric nanoparticle investment for oncology precision medicine protocols. |
| Strategic Partnership | Alnylam Pharmaceuticals anchors RNA therapeutic delivery through lipid nanoparticle platform specialization. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists grounded qualitative insights. Secondary validation drew from FDA nanotechnology guidance documents, EMA reflection papers, ClinicalTrials.gov entries, and ISO/TS 19601 standards. Bottom-up and top-down triangulation cross-referenced manufacturer capacity disclosures with hospital procurement database trends.
Bottom-up modeling segmented volume and value across formulation architecture, therapy area, delivery mode, and end-user sophistication tiers. Analytical frameworks projected expansion over the projection horizon by linking oncology precision protocol adoption rates to nanodrug formulary expansion. CAGRs derived from regression against historical liposomal and polymeric nanoparticle revenue trajectories, incorporating mRNA platform spillover assumptions and personalized medicine pipeline conversion rates.
Inputs from FDA, EMA, and PMDA regulatory filings were available through the study window; gaps in real-time pharmacovigilance data for long-circulating nanocarriers introduce uncertainty bands around safety-profile assumptions. Forecasts reflect documented assumptions regarding payer infrastructure evolution and continuous manufacturing adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nano Biosensors Market