
 Nano Biosensors Market | 2026-2036
Nano Biosensors Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Biosensors Market Outlook
Project finance and equipment-leasing partnerships for diagnostic platforms is reshaping competitive entry in nano biosensors, lowering capital barriers for mid-tier clinical laboratories. Abbott leverages its vertically integrated manufacturing footprint to sustain cost advantages across electrochemical sensor production. Roche anchors its position through deep R&D intensity in optical detection modalities. Dexcom specializes in continuous monitoring architectures that extend its reach beyond traditional laboratory settings.
Nano biosensors integrate nanoscale recognition elements—typically gold nanoparticles, carbon nanotubes, or graphene oxide—with transduction mechanisms to detect biological analytes at picomolar concentrations. These devices convert molecular binding events into quantifiable electrical, optical, or mass-based signals for real-time diagnostic or environmental surveillance applications. Electrochemical sensors occupy the largest installed base due to their compatibility with portable electronics and minimal power requirements, while quantum dot-enhanced platforms represent the fastest-expanding technology segment as fluorescence quantum yields improve manufacturing consistency. Healthcare facilities constitute the dominant end-user channel, though agricultural enterprises are emerging as a high-margin niche for pathogen and contaminant detection.
The FDA governs premarket submission pathways for clinical nano biosensors under its in vitro diagnostic framework, while the EPA establishes detection thresholds for environmental monitoring deployments. ISO 13485 quality management standards shape supplier qualification across the medical device supply chain, creating compliance moats for certified manufacturers. Stakeholders must monitor how the EPA's revised drinking water contaminant candidate list redirects R&D budgets toward multiplexed environmental sensor arrays.
Market Dynamics
Point-of-care diagnostic platforms are compressing laboratory infrastructure requirements while FDA premarket notification pathways tighten clinical validation thresholds for new nano biosensor entrants.
Growth Catalysts
- ISO 13485 certification mandates:Medical device supply chains now require certified quality management systems, creating compliance moats that favor established electrochemical sensor manufacturers with documented traceability protocols.
- Carbon nanotube functionalization advances:Improved covalent surface chemistry enables picomolar detection limits for glucose and cardiac biomarkers, accelerating hospital adoption of continuous monitoring architectures.
- Venture capital clustering in Boston and San Diego:Academic medical center partnerships with startup ecosystems concentrate R&D talent and prototype-to-clinic pathways for optical detection modalities.
Market Restraints
- Gold nanoparticle supply concentration:Precursor chemical production concentrates among specialty material suppliers, exposing sensor manufacturers to input cost volatility and batch-to-batch consistency risks.
- EPA environmental detection thresholds:Multiplexed agricultural sensor arrays face extended validation timelines against the agency's revised drinking water contaminant candidate list, delaying commercial deployment.
- Electrochemical interference limitations:Serum matrix effects and non-specific binding in complex biological samples constrain diagnostic accuracy without additional sample preparation steps.
Strategic Opportunities
- Indian agricultural pathogen detection:FSSAI food safety mandates and CDSCO diagnostic device classifications create dual regulatory tailwinds for graphene oxide-based contaminant sensors in grain storage and processing facilities.
- Quantum dot-CRISPR convergence:Fluorescence resonance energy transfer between quantum dot donors and guide RNA complexes enables single-molecule nucleic acid detection with smartphone-readable outputs.
- Equipment-leasing distribution models:Project finance partnerships lower capital barriers for mid-tier clinical laboratories seeking electrochemical platform access without upfront instrument acquisition.
Industry Challenges
- Nanofabrication technician scarcity:Cleanroom lithography and thin-film deposition expertise concentrates among semiconductor industry veterans, creating recruitment bottlenecks for sensor startups scaling manufacturing.
- 510(k) predicate device navigation:FDA substantial equivalence determinations for novel transduction mechanisms require extensive clinical performance studies, extending time-to-revenue for optical detection platforms.
- Legacy laboratory information system integration:Hospital IT infrastructure built around centralized core lab workflows resists point-of-care data architecture modifications without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Biosensors Market |
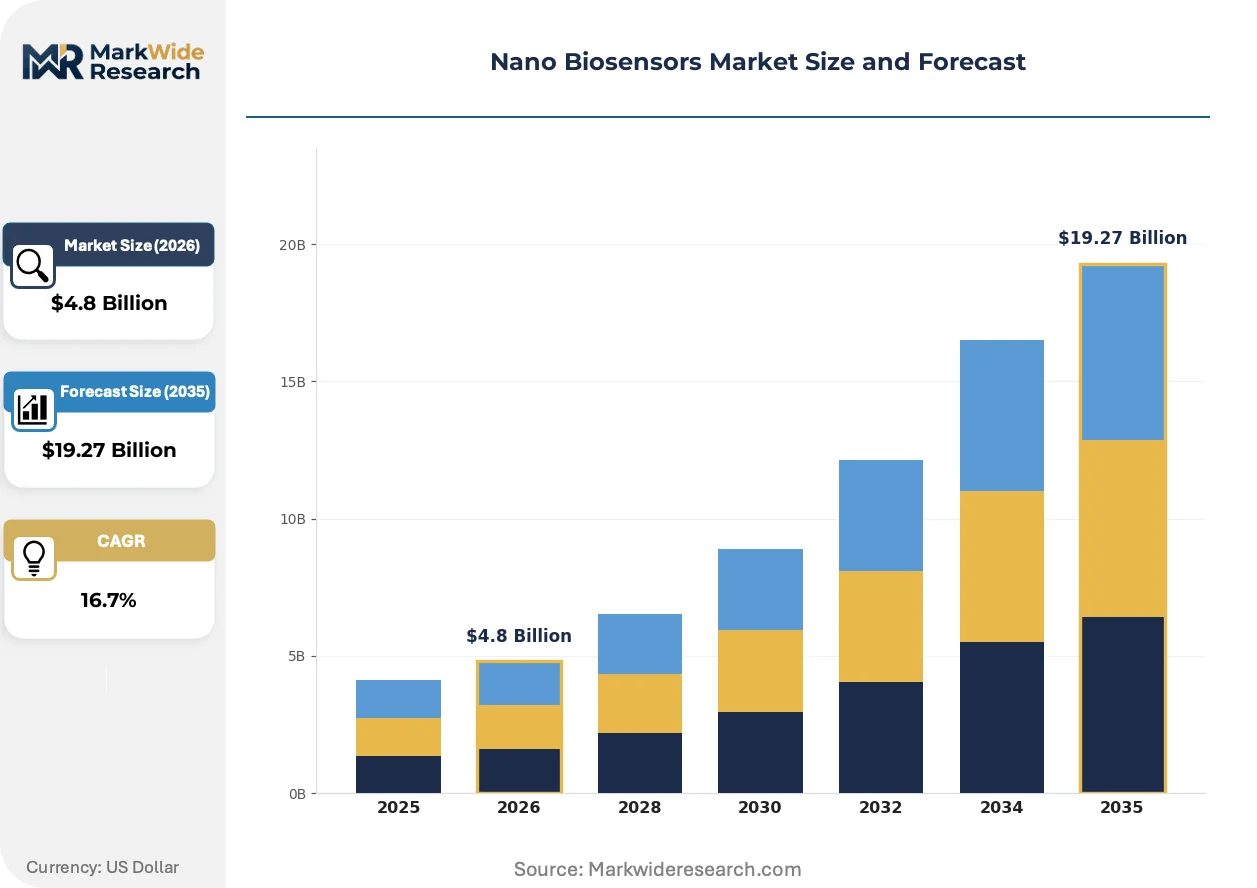
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical Sensors, Optical Sensors, Piezoelectric Sensors, Thermal Sensors Application: Food Safety, Environmental Monitoring, Medical Diagnostics, Pharmaceuticals Technology: Nanomaterials, Microfluidics, Surface Plasmon Resonance, Quantum Dots End User: Laboratories, Healthcare Facilities, Agricultural Enterprises, Research Institutes |
| Companies Covered | Abbott, Roche, Medtronic, Bio-Rad Laboratories, Inc., DuPont, Biosensors International Group, Ltd., Dexcom, Inc., Masimo, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Biosensors Market Strategic Shifts
Transduction mechanism miniaturization and fluorescence quantum yield improvements are compressing instrument footprints while expanding detection capabilities beyond traditional laboratory settings.
Graphene oxide field-effect transducers are virtualizing the interface between biological recognition elements and signal processing electronics. Agricultural enterprises in water-stressed regions adopt these platforms for real-time soil pathogen surveillance. The technology is virtualizing the need for centralized laboratory infrastructure by enabling smartphone-integrated readout circuits.
EMA's In Vitro Diagnostic Regulation (IVDR) reclassification rules are elevating clinical evidence requirements for nano biosensor conformity assessments. Manufacturers must now submit performance evaluation reports with expanded analytical and clinical validation data. Class C devices for infectious disease detection face the steepest compliance burden, redirecting R&D budgets toward quality management system enhancements.
Point-of-care procurement committees now mandate total cost-of-ownership calculations over instrument acquisition price alone. Hospital supply chains are consolidating vendor relationships around platforms offering bundled reagent contracts and remote technical support. This behavioral shift is most visible in United States academic medical centers negotiating multi-site electrochemical sensor deployments with standardized training protocols.
Nano Biosensors Market Segmentation
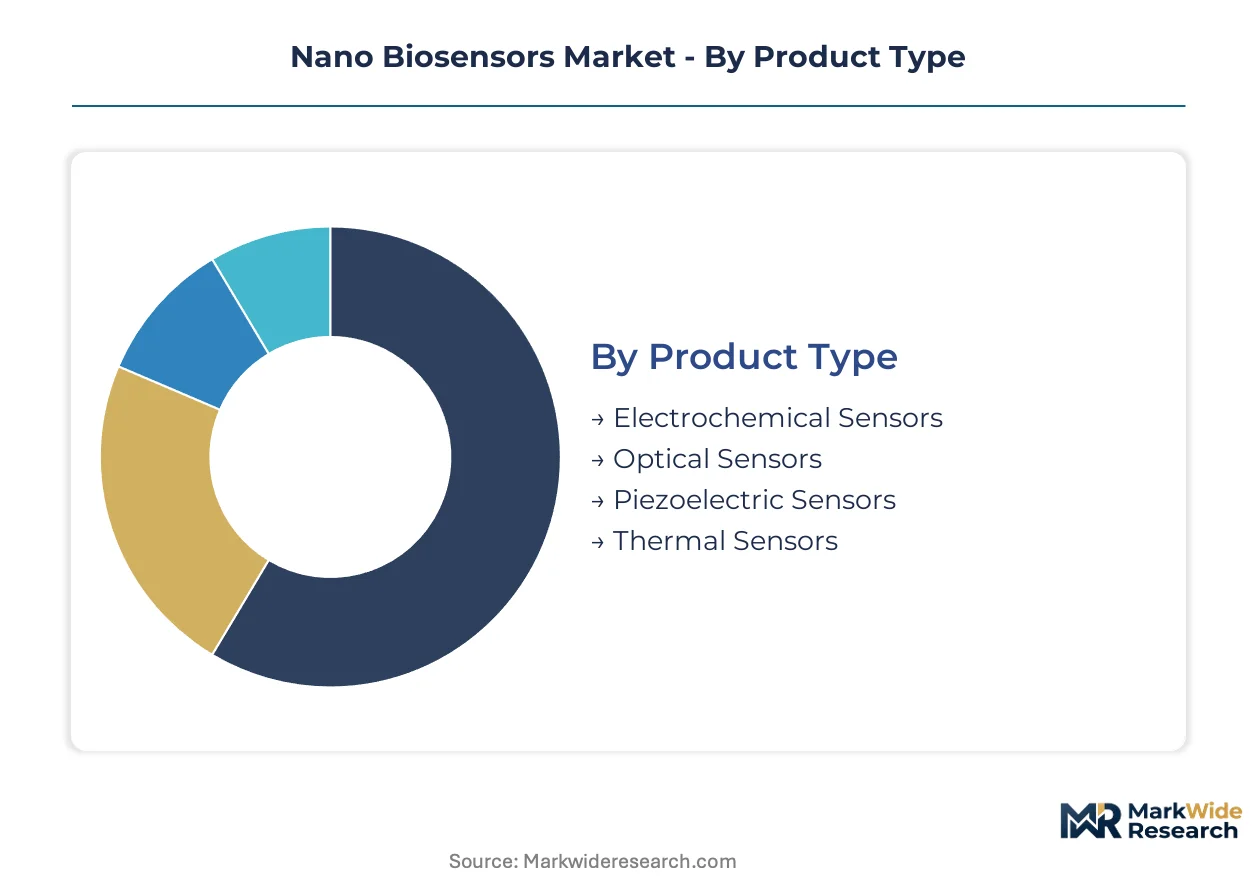
Nano biosensors fragment across four distinct taxonomies that determine procurement patterns and regulatory pathways. Product type dictates manufacturing complexity and capital requirements. Application verticals shape validation timelines and reimbursement structures. Technology platforms differentiate detection limits and portability profiles. End-user concentration influences distribution economics and service bundling strategies.
Product Type:
Mature electrochemical architectures dominate installed capacity while optical platforms represent the steepest expansion trajectory.
- Electrochemical Sensors:These devices exploit electron transfer reactions at nanostructured electrode interfaces to quantify analytes through current or potential measurements. Hospital procurement committees in the United States favor these platforms for point-of-care glucose and cardiac marker testing due to minimal power requirements and smartphone-compatible form factors. ISO 13485-certified manufacturers with vertically integrated electrode production maintain cost advantages in multi-site laboratory contracts.
- Optical Sensors:Fluorescence, absorbance, and luminescence transduction mechanisms achieve superior detection limits for nucleic acid and protein targets. Academic medical centers in Boston and San Diego cluster around quantum dot-enhanced architectures for CRISPR-integrated diagnostic workflows. EMA's IVDR reclassification elevates clinical evidence burdens for these platforms, extending conformity assessment timelines.
- Piezoelectric Sensors:Mass-sensitive quartz crystal microbalances detect antigen-antibody binding through resonant frequency shifts.
- Thermal Sensors:Calorimetric transduction measures enzymatic reaction heat release for metabolic analyte quantification.
Electrochemical sensors handle the majority of throughput; optical sensors are climbing the fastest on share.
Application:
Medical diagnostics commands premium pricing while environmental monitoring faces elongated EPA validation cycles.
- Medical Diagnostics:Infectious disease panels, cardiac biomarker assays, and continuous glucose monitors constitute the revenue core. FDA 510(k) pathways for novel transduction mechanisms demand extensive predicate device navigation, favoring established electrochemical manufacturers with documented clinical performance libraries. Point-of-care procurement committees now mandate total cost-of-ownership calculations over instrument acquisition price alone.
- Food Safety:Pathogen detection in grain storage and processing facilities drives graphene oxide sensor adoption. India's FSSAI mandates and CDSCO diagnostic classifications create dual regulatory tailwinds for agricultural deployment. Multiplexed contaminant arrays face extended validation timelines against evolving detection thresholds.
- Environmental Monitoring:Real-time soil pathogen surveillance in water-stressed regions virtualizes centralized laboratory infrastructure.
- Pharmaceuticals:Process analytical technology integration supports biomanufacturing quality control workflows.
Medical diagnostics captures the dominant revenue pool; food safety is gaining share fastest.
Technology:
Cost tiers separate commoditized nanomaterial substrates from precision-engineered quantum dot architectures.
- Nanomaterials:Gold nanoparticles, carbon nanotubes, and graphene oxide provide recognition element scaffolds with tunable surface chemistry. Carbon nanotube functionalization advances enable picomolar detection limits for glucose and cardiac biomarkers, accelerating hospital adoption of continuous monitoring architectures. Gold nanoparticle supply concentration among specialty chemical suppliers exposes manufacturers to input cost volatility.
- Quantum Dots:Semiconductor nanocrystals with size-tunable fluorescence emission achieve single-molecule detection sensitivity. Quantum dot-CRISPR convergence enables smartphone-readable nucleic acid outputs through fluorescence resonance energy transfer. Manufacturing consistency improvements in quantum yield are compressing batch-to-batch performance variation.
- Microfluidics:Lab-on-chip architectures integrate sample preparation with detection in disposable cartridges.
- Surface Plasmon Resonance:Label-free binding kinetics measurement supports pharmaceutical development workflows.
Nanomaterials underpin the largest installed base; quantum dots show the steepest expansion trajectory.
End User:
Customer type stratifies around capital availability and technical integration capabilities.
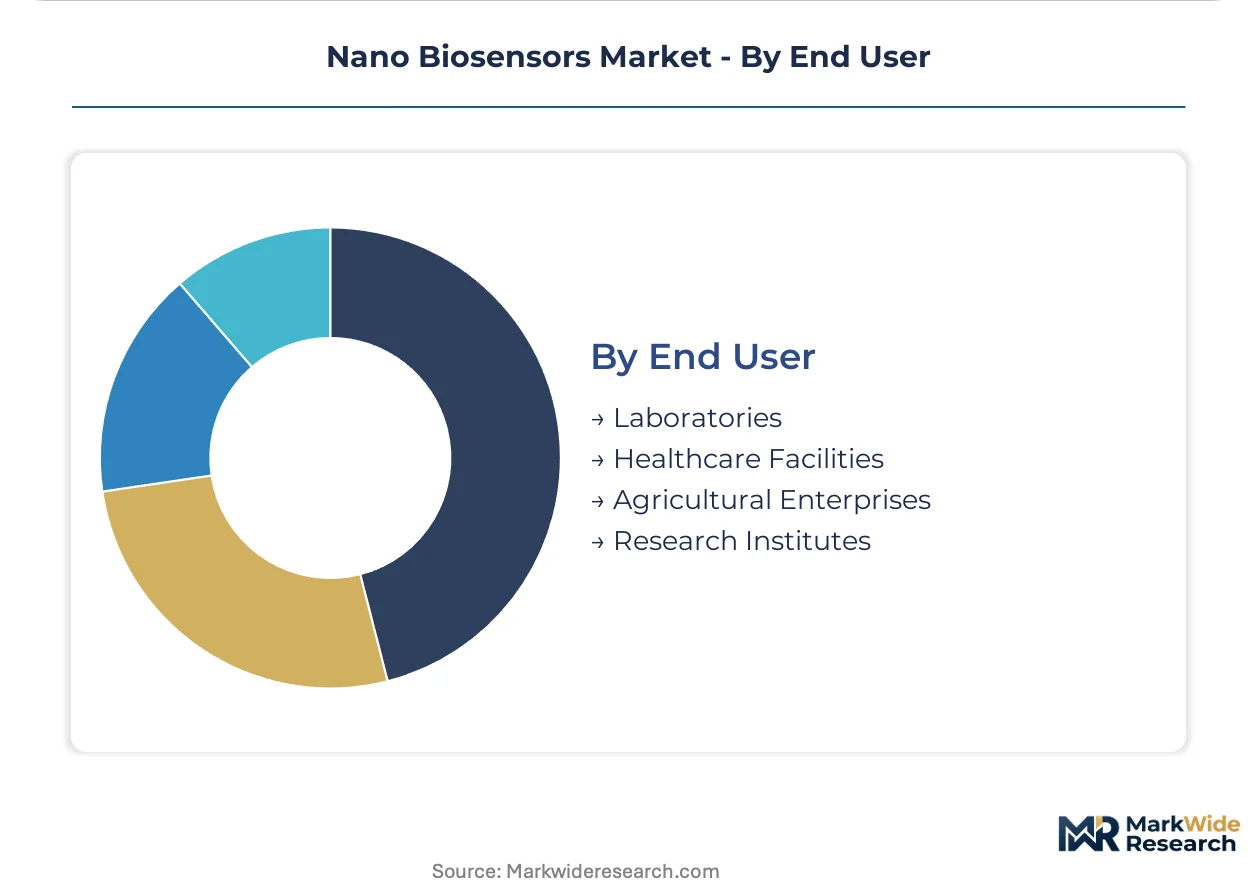
- Healthcare Facilities:Point-of-care diagnostic platforms compress laboratory infrastructure requirements while FDA premarket notification pathways tighten clinical validation thresholds. United States academic medical centers negotiate multi-site electrochemical deployments with standardized training protocols. Hospital IT infrastructure resists point-of-care data architecture modifications without custom middleware development.
- Agricultural Enterprises:Real-time soil pathogen surveillance in water-stressed regions adopts graphene oxide field-effect transducers. Equipment-leasing distribution models lower capital barriers for mid-tier operations seeking platform access without upfront instrument acquisition.
- Laboratories:Centralized core lab workflows maintain dominance in high-throughput reference testing.
- Research Institutes:Prototype-to-clinic partnerships with venture-backed startups concentrate R&D talent around Boston and San Diego.
Healthcare facilities command the dominant procurement volume; agricultural enterprises are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers extract premium pricing for FDA-cleared electrochemical platforms while Indian agricultural sensor deployments absorb cost compression from localized graphene oxide production. This pricing-power asymmetry shapes regional investment flows and partnership structures across the forecast window.
United States
Academic medical centers in Boston and San Diego anchor venture capital clustering for optical detection modalities. FDA premarket notification pathways tighten clinical validation thresholds for novel transduction mechanisms. Hospital procurement committees negotiate multi-site electrochemical deployments with standardized training protocols across Massachusetts and California research corridors.
Germany
EMA's In Vitro Diagnostic Regulation elevates conformity assessment burdens for Class C infectious disease devices. Industrial sensor manufacturers in Baden-Württemberg integrate ISO 13485 quality management systems to maintain medical device supply chain access. Stuttgart-based precision engineering clusters support thin-film deposition capabilities for nanofabrication scale-up.
India
FSSAI food safety mandates and CDSCO diagnostic device classifications create dual regulatory tailwinds for agricultural pathogen detection. Graphene oxide-based contaminant sensors penetrate grain storage facilities in Maharashtra and Gujarat. Equipment-leasing distribution models lower capital barriers for mid-tier operations in water-stressed agricultural regions.
China
NMPA medical device classification rules shape premarket submission pathways for clinical nano biosensors. Carbon nanotube functionalization advances concentrate among Yangtze River Delta materials suppliers. Shanghai and Suzhou industrial parks host prototype-to-manufacturing transitions for electrochemical platform exporters.
Japan
PMDA quality management requirements align with global ISO 13485 standards for multinational sensor manufacturers. METI funding programs support quantum dot manufacturing consistency improvements. Tokyo-Osaka industrial corridors maintain dominance in high-precision optical detection component fabrication for regional OEM supply.
Nano Biosensors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in nanomaterial and transduction element supply. The vendor base stratifies across three tiers: multinational conglomerates with vertically integrated manufacturing footprints, mid-cap specialists with certified quality management systems, and venture-backed startups clustered near academic medical centers. Strategic moves concentrate on equipment-leasing partnerships for diagnostic platforms and quantum dot-CRISPR technology convergence for nucleic acid detection workflows.
Among United States-based platform integrators, Abbott and Dexcom occupy positions representing electrochemical and continuous monitoring archetypes respectively. Roche exemplifies the deep R&D intensity model for optical detection modalities. These three anchors illustrate how geographic proximity to FDA regulatory expertise and venture capital ecosystems shapes competitive positioning in point-of-care diagnostics.
| Leading Market Players |
|---|
| Abbott |
| Roche |
| Medtronic |
| Bio-Rad Laboratories, Inc. |
| DuPont |
| Biosensors International Group, Ltd. |
| Dexcom, Inc. |
| Masimo |
| Agilent Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Shenzhen express freight corridors absorb volatile fuel surcharges that cascade through carbon nanotube precursor shipments, compressing margins for electrochemical sensor manufacturers while amplifying price premiums for ISO 13485-certified optical platforms in United States academic medical centers.
Pricing Analysis
The customization-premium spread separates configured-to-order quantum dot-CRISPR platforms from standard electrochemical glucose monitors by a factor reflecting both R&D amortization and clinical validation depth. Pricing stratifies across premium, standard, and economy tiers anchored by certification grade, with FDA-cleared Class C infectious disease devices commanding substantial premiums over research-use-only configurations. Cost compression in graphene oxide substrates is intensifying because localized Indian production scales, eroding price premiums for agricultural pathogen sensors. Mid-tier clinical laboratories exhibit acute price sensitivity, while academic medical centers negotiating multi-site deployments prioritize total cost-of-ownership over instrument acquisition.
Supply Chain Analysis
Contract manufacturing concentration rests with Yangtze River Delta electronics manufacturing services for electrochemical platform assembly and Baden-Württemberg precision engineering clusters for thin-film deposition. Geographic supply concentration centers on China for carbon nanotube functionalization, India for graphene oxide synthesis, and Japan for quantum dot manufacturing consistency. Raw material dependencies draw from gold nanoparticle precursors, semiconductor-grade silicon wafers, and specialty photoresists. Single-source vulnerability in carbon nanotube covalent surface chemistry expertise creates recruitment bottlenecks. Distribution runs through hospital procurement committees consolidating vendor relationships around bundled reagent contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cleanroom lithography technician scarcity constrains manufacturing scale-up for venture-backed startups, privileging incumbents with captive nanofabrication expertise and documented ISO 13485 traceability protocols.
For Market Incumbents: Insulate electrode production capabilities through backward integration into specialty material supply, securing batch-to-batch consistency against gold nanoparticle precursor volatility. Expand capacity in Maharashtra and Gujarat to capture FSSAI-mandated agricultural sensor demand before CDSCO diagnostic classifications tighten. Deepen hospital IT integration partnerships to overcome legacy laboratory information system resistance. For New Entrants and Emerging Players: Mid-tier clinical laboratories in water-stressed Indian agricultural regions represent the most penetrable entry point, where equipment-leasing distribution models neutralize capital barriers. Quantum dot-CRISPR smartphone-readable outputs for nucleic acid detection offer differentiation against established electrochemical glucose platforms. Pursue prototype-to-clinic partnerships with Boston and San Diego academic medical centers to accelerate FDA predicate device navigation. For Investors and Strategic Acquirers: EMA's IVDR reclassification reshapes the acquisition landscape, elevating clinical evidence burdens that favor targets with pre-submitted performance evaluation reports. Long-term viability hinges on quality management system maturity rather than transduction mechanism novelty alone. Monitor EPA revised drinking water contaminant candidate list revisions as the inflection signal redirecting R&D budgets toward multiplexed environmental arrays.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Creates compliance moats for electrochemical sensor manufacturers seeking hospital procurement access. |
| Quantum Dot-CRISPR Convergence | Enables single-molecule nucleic acid detection with smartphone-readable outputs beyond laboratory settings. |
| Equipment-Leasing Distribution Model | Lowers capital barriers for mid-tier clinical laboratories through project finance partnerships. |
| Graphene Oxide Field-Effect Transducer Scale-Up | Virtualizes centralized laboratory infrastructure for real-time soil pathogen surveillance in water-stressed regions. |
| Hospital System Partnership | Secures multi-site electrochemical deployments with standardized training protocols across academic medical centers. |
Study Parameters
A standing panel of biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration against secondary validation from FDA 510(k) filings, EMA IVDR submission databases, ISO 13485 certification registries, and hospital procurement databases. Bottom-up sensor shipment estimates triangulated with top-down healthcare capital expenditure projections.
Scenario-bracketing framed demand projections across the analysis window, modeling electrochemical versus optical platform splits, healthcare facility versus agricultural enterprise end-user concentrations, and nanomaterial versus quantum dot technology trajectories. CAGRs derived from segment-level growth rate synthesis incorporating carbon nanotube functionalization advance timelines and EPA detection threshold revision probabilities.
Macroeconomic conditions sit as an overlay; deviation in venture capital availability, specialty chemical input costs, or FDA premarket notification processing timelines would shift the trajectory. Quarterly review of cleanroom lithography technician labor market indicators and predicate device clearance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nanopore Technologies Market