
 Designer DNA Nanocages Market | 2026-2036
Designer DNA Nanocages Market Size, Share, and Industry Trends Forecast 2026-2036
Designer DNA Nanocages Market Outlook
Project finance for dedicated nanofabrication facilities is narrowing the competitive field to well-capitalized entrants. Ginkgo Bioworks leverages its foundry infrastructure to occupy scale advantages in programmable nanomaterial production. Tilibit nanosystems anchors its position through specialized biochemical synthesis capabilities for custom DNA origami architectures. Nanobio Designs differentiates via tight control over functionalization workflows that link therapeutic payloads to cage scaffolds.
Designer DNA nanocages are self-assembling nucleic acid structures, typically 20-100 nanometers in dimension, engineered through scaffolded DNA origami or tile-based assembly to encapsulate cargo molecules with sub-nanometer spatial precision. These architectures serve primarily as programmable vehicles for targeted intracellular delivery, diagnostic signal amplification, and spatial organization of molecular reagents. Self-assembling variants command the deepest installed base due to their straightforward benchtop production, while functionalized cages capture expanding margin pools as pharmaceutical buyers prioritize ready-to-conjugate platforms bearing aptamer or antibody handles. Biochemical synthesis methods retain dominance in academic settings, though solid-state fabrication is gaining traction where reproducibility standards tighten.
FDA oversight of nucleic acid therapeutics and EPA guidelines for nanoscale material environmental release jointly shape product development pathways and commercialization timelines in the United States. ISO 10993 biocompatibility standards and REACH registration requirements in Europe add compliance layers that favor organizations with established regulatory affairs functions. Stakeholders must weigh capital deployment between captive synthesis infrastructure and outsourced foundry partnerships before the competitive set crystallizes around proven manufacturing platforms.
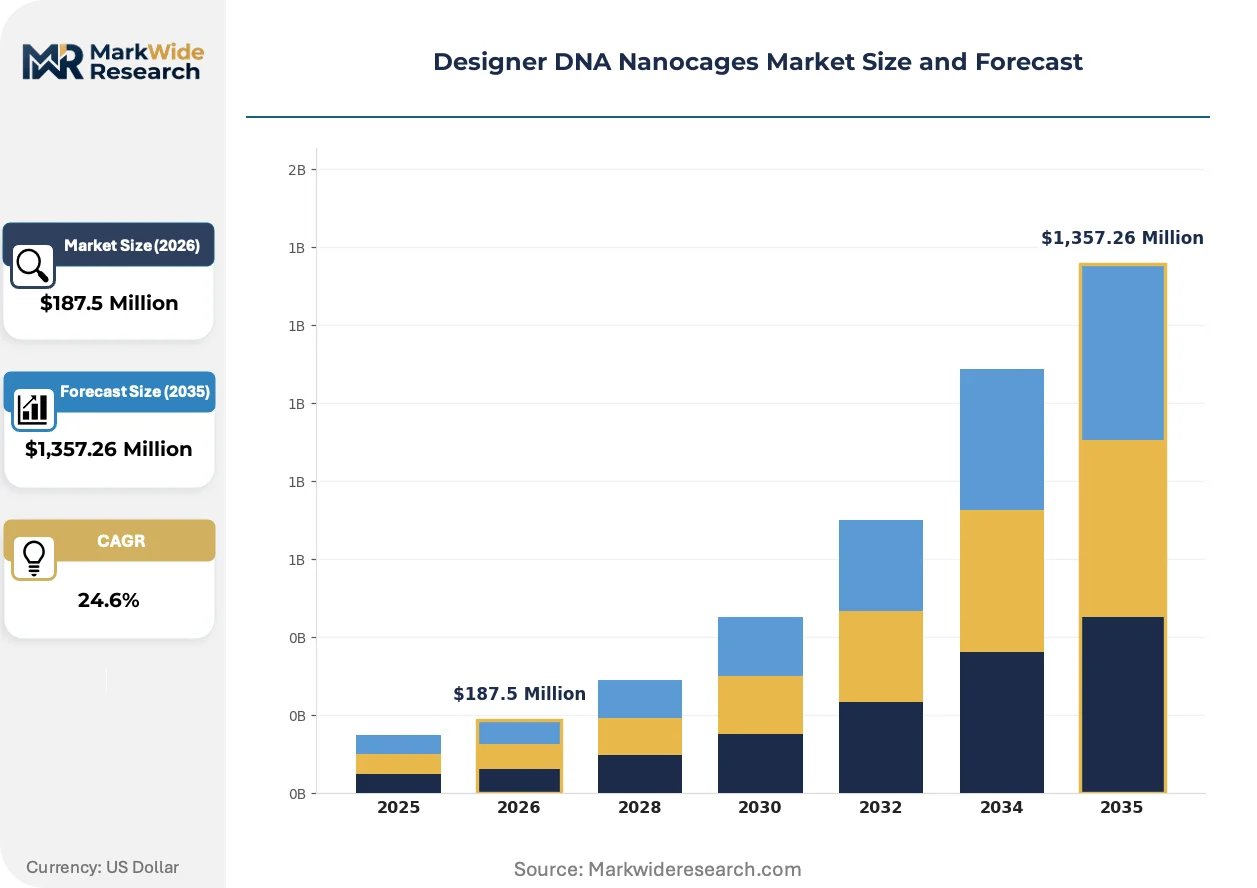
Market Dynamics
Pharmaceutical buyers are consolidating their supplier base around DNA nanocage platforms that demonstrate validated GMP compliance, compressing procurement timelines and elevating technical due diligence above price competition.
Growth Catalysts
- ISO 10993 biocompatibility harmonization:Streamlined safety testing protocols across the United States and European Union are reducing redundant validation cycles for nanocage-based therapeutics entering clinical pipelines.
- Precision oncology pipelines:Major pharmaceutical manufacturers are embedding DNA origami scaffolds into antibody-drug conjugate programs targeting intracellular delivery of cytotoxic payloads.
- Synthetic biology foundry density in Boston:Concentrated contract manufacturing infrastructure lowers barrier-to-entry for biotech startups developing custom cage architectures.
Market Restraints
- Phosphoramidite cost volatility:Oligonucleotide synthesis feedstock prices fluctuate with semiconductor-grade chemical supply chains concentrated in East Asian manufacturing hubs.
- EPA nanoscale material release protocols:Environmental fate testing requirements for DNA nanostructures add twelve-to-eighteen month pre-commercialization timelines for U.S.-based developers.
- Biological stability limitations:Serum nuclease degradation of unmodified DNA cages restricts circulatory half-life without costly backbone chemistries.
Strategic Opportunities
- In vivo CRISPR delivery expansion:Ribonucleoprotein encapsulation within DNA nanocages opens programmable gene editing applications previously blocked by viral vector immunogenicity.
- India's PLI scheme for biologics:Production-linked incentives for advanced pharmaceutical manufacturing attract contract synthesis investment for cost-sensitive cage production.
- Digital microfluidic integration:Benchtop automated assembly platforms merge with DNA origami design software to enable distributed, on-demand nanocage fabrication.
Industry Challenges
- Scaffolded origami design expertise scarcity:Computational biologists capable of optimizing cage topology for specific cargo geometries command premium compensation, constraining team expansion.
- GMP facility qualification timelines:Dedicated cleanroom infrastructure for nucleic acid nanomaterial production requires capital deployment years ahead of revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Designer DNA Nanocages Market |
| Market Size in 2026 | $187.5 Million |
| Market Size in 2035 | $1,357.26 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Assembling, Functionalized, Targeted, Engineered Technology: Solid-State, Optical Trap, Biochemical Synthesis, Nanostructuring End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Academic Labs Application: Drug Delivery, Diagnostics, Bioimaging, Therapeutic Agents |
| Companies Covered | Gattaquant, Nanobio Designs, tilibit nanosystems, Helixworks, Genisphere, Ginkgo Bioworks, Nanolab Technologies, Nanogami, DNA Nanobots, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Designer DNA Nanocages Market Strategic Shifts
Benchtop automation and AI-assisted sequence design are compressing the traditional DNA origami development cycle from months to weeks, forcing incumbent foundries to demonstrate throughput advantages beyond scale alone.
Dynamic DNA nanostructures incorporating toehold-mediated strand displacement are collapsing the distinction between passive encapsulation and active payload release. Pharmaceutical formulators at early-stage biotechnology firms are adopting these architectures for stimuli-responsive intracellular delivery. The shift is collapsing conventional licensing models that separated scaffold IP from functionalization chemistry.
REACH registration requirements for novel nanomaterials in the European Union are mandating expanded toxicological datasets for DNA-based constructs below 100 nanometers. ECHA guidance on substance identification for programmable nucleic acids is compelling manufacturers to establish analytical characterization protocols earlier in development. German and Swiss contract research organizations are capturing expanded service revenue from this compliance burden.
Academic technology transfer offices are demanding equity stakes rather than traditional royalty structures for DNA origami platform licenses. Biotechnology venture capital firms are accepting these terms to secure exclusive access to cage architectures with demonstrated in vivo stability. The pattern is most visible in Massachusetts and California, where university-affiliated startups dominate early-phase therapeutic programs.
Designer DNA Nanocages Market Segmentation
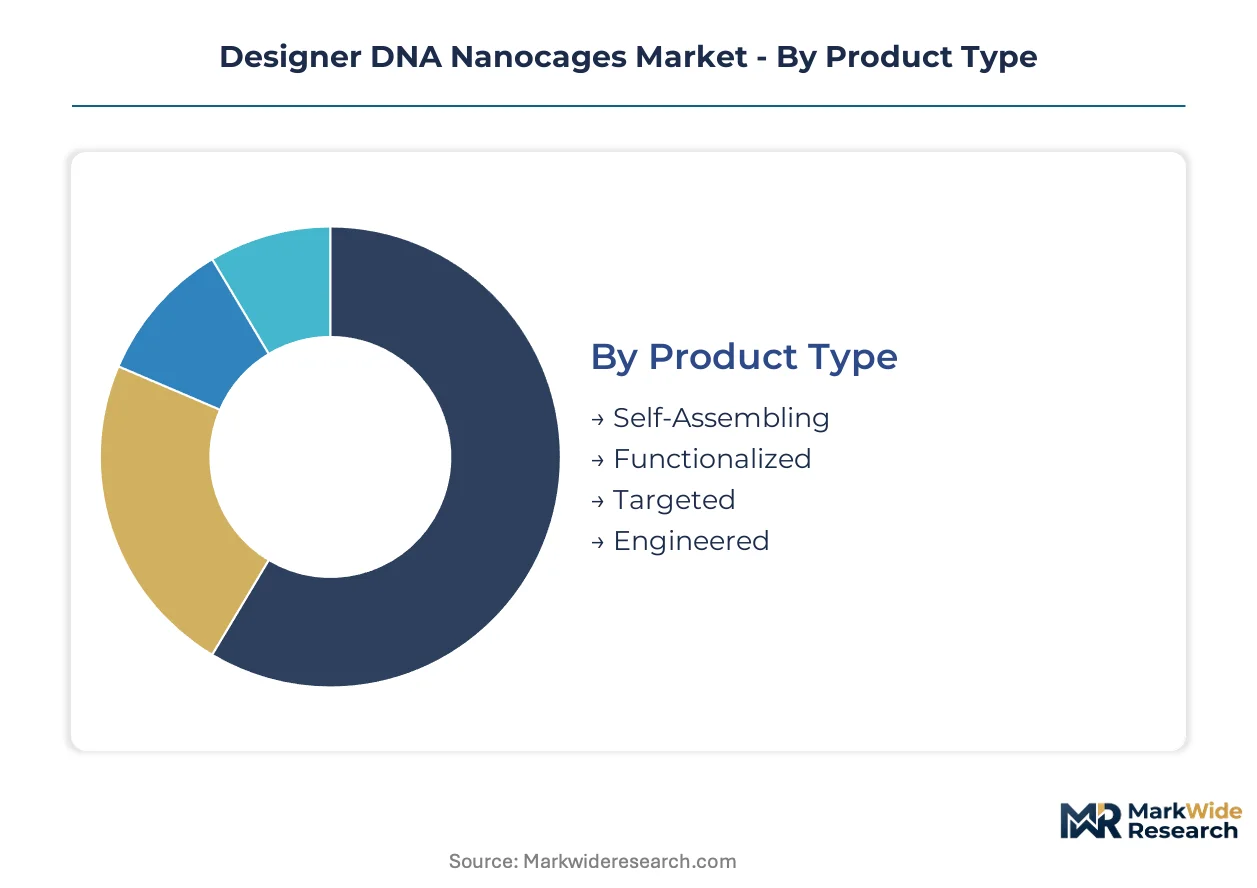
Segmentation in the Designer DNA Nanocages Market reveals distinct technology readiness levels and commercial deployment patterns. Product architecture and synthesis methodology determine pricing power, regulatory pathway complexity, and partnership attractiveness to pharmaceutical buyers.
Product Type:
The maturity spectrum spans benchtop-ready formats to emerging architectures requiring custom development cycles.
- Self-Assembling:Scaffolded DNA origami structures autonomously fold from designed oligonucleotide sequences without external templating. Research institutions in Boston and San Diego favor these for rapid prototyping of cage geometries. Benchtop production protocols and minimal equipment requirements sustain this segment's installed base across academic settings.
- Functionalized:Pre-modified cages bearing aptamer, antibody, or small-molecule handles enable direct conjugation to therapeutic payloads. Pharmaceutical companies prioritize these ready-to-deploy platforms to compress preclinical timelines. The segment commands premium positioning as buyers trade upfront cost for accelerated regulatory filing preparation.
- Targeted:Architectures engineered for specific cellular uptake mechanisms or tissue homing properties.
- Engineered:Custom-designed topologies optimized for unique cargo geometries or release kinetics.
Self-assembling variants retain volume leadership; functionalized platforms hold the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive fabrication modes from accessible benchtop methods.
- Biochemical Synthesis:Phosphoramidite-based solid-phase oligonucleotide production dominates current manufacturing throughput. East Asian chemical supply chains and contract manufacturing infrastructure in India support cost-sensitive scale-up for clinical-grade material. The method's maturity attracts pharmaceutical sponsors requiring GMP-compliant documentation.
- Solid-State:Lithographic and template-directed fabrication approaches enable sub-nanometer positional precision for reproducible cage geometries. Swiss and German precision manufacturing clusters host specialized equipment providers serving diagnostic applications with stringent batch-to-batch consistency requirements. Capital barriers limit adoption to well-funded consortia.
- Optical Trap:Laser-based manipulation enables single-molecule assembly verification.
- Nanostructuring:Hybrid top-down/bottom-up approaches integrating microfluidic confinement with DNA self-assembly.
Biochemical synthesis anchors current production volumes; solid-state methods are climbing the fastest toward commercial qualification.
End User:
Customer type dictates procurement scale, technical specification depth, and regulatory documentation burden.
- Pharmaceutical Companies:Integrated drug developers seeking IND-enabling platforms for nucleic acid or small-molecule delivery. FDA engagement timelines and companion diagnostic strategies shape their cage architecture selections. Procurement teams consolidate supplier relationships around validated GMP compliance to streamline technical due diligence.
- Biotechnology Firms:Venture-backed developers of precision therapeutics requiring flexible partnership terms for custom cage engineering. Massachusetts and California startup density creates concentrated demand for foundry-accessible production models with equity-friendly licensing structures.
- Research Institutions:Academic and government laboratories pursuing fundamental nanotechnology research.
- Academic Labs:University-based groups focused on origami design methodology and characterization protocols.
Pharmaceutical companies drive revenue concentration; biotechnology firms represent the most rapidly expanding customer category.
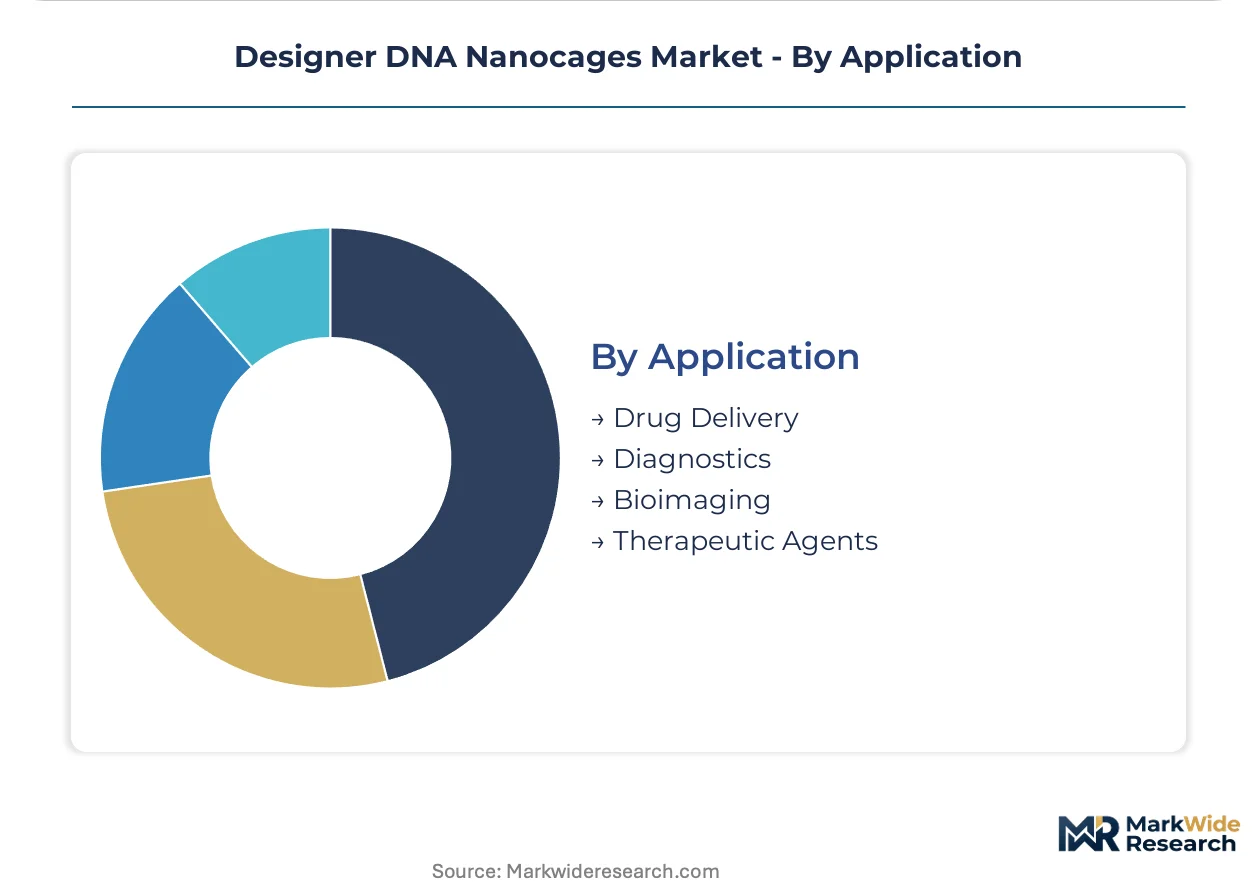
Application:
Application focus determines the regulatory pathway, performance specification, and partnership ecosystem for cage deployment.
- Drug Delivery:Encapsulation vehicles for cytotoxic agents, gene editing machinery, or nucleic acid therapeutics requiring endosomal escape and intracellular release. Antibody-drug conjugate programs at major manufacturers embed DNA origami scaffolds to achieve payload concentrations previously unattainable with conventional linker chemistries.
- Diagnostics:Signal amplification scaffolds for molecular detection and point-of-care assay platforms. German and Swiss contract research organizations capture service revenue from ECHA-mandated toxicological characterization for diagnostic nanomaterials below 100 nanometers.
- Bioimaging:Contrast agent carriers and spatial calibration standards for microscopy and in vivo imaging.
- Therapeutic Agents:Active immunomodulatory or directly cytotoxic DNA constructs functioning as the therapeutic itself.
Drug delivery commands the deepest current investment; diagnostics platforms are gaining share fastest through companion test development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in DNA nanocages track phosphoramidite feedstock dependencies and pharmaceutical R&D outsourcing patterns. The United States maintains structural trade deficits in oligonucleotide precursors while exporting high-margin functionalized cage architectures. Switzerland and Germany capture premium diagnostic-grade production through precision manufacturing clusters.
United States
FDA's nucleic acid therapeutic framework accelerates IND timelines for cage-encapsulated payloads. Boston and San Diego synthetic biology clusters concentrate contract manufacturing infrastructure for programmable nanomaterials. EPA nanoscale release protocols extend pre-commercialization timelines by twelve-to-eighteen months for domestic developers.
Germany
ECHA REACH registration mandates toxicological datasets for sub-100 nanometer DNA constructs entering diagnostic applications. Precision manufacturing clusters in Baden-Württemberg host specialized equipment providers serving batch-consistency-critical pharmaceutical buyers. German contract research organizations capture expanded service revenue from ECHA compliance characterization requirements.
Switzerland
Swissmedic oversight of nucleic acid therapeutics aligns with ISO 10993 biocompatibility harmonization across EU markets. Basel and Zurich precision manufacturing corridors specialize in solid-state fabrication approaches for reproducible cage geometries. Swiss foundry infrastructure attracts pharmaceutical sponsors requiring GMP-compliant documentation for clinical-grade material.
India
CDSCO's evolving biologics pathway and PLI scheme for advanced pharmaceutical manufacturing attract contract synthesis investment. Maharashtra and Gujarat chemical manufacturing corridors leverage phosphoramidite feedstock access for cost-sensitive scale-up. Indian contract manufacturers capture expanding revenue from biotechnology firms seeking equity-friendly production partnerships.
United Kingdom
MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for nucleic acid nanomaterials. London-Oxford-Cambridge golden triangle concentrates academic technology transfer offices demanding equity stakes for DNA origami platform licenses. UK-based startups dominate early-phase therapeutic programs through university-affiliated venture structures.
Designer DNA Nanocages Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in biochemical synthesis and functionalization chemistry. The vendor base stratifies between foundry-scale operators and boutique architecture designers. Three archetypes dominate: synthetic biology foundries with captive infrastructure, specialized DNA origami synthesis houses, and functionalization workflow developers. Competitive moves center on GMP facility qualification races and exclusive university licensing negotiations.
Within the foundry-scale tier, Ginkgo Bioworks and tilibit nanosystems occupy positions representing divergent scale strategies. Ginkgo Bioworks exemplifies platform integrators leveraging vertical infrastructure for programmable nanomaterial production. tilibit nanosystems anchors specialized biochemical synthesis capabilities for custom DNA origami architectures. Nanobio Designs sits within the functionalization specialist archetype, differentiated through payload-linkage workflow control.
| Leading Market Players |
|---|
| Gattaquant |
| Nanobio Designs |
| tilibit nanosystems |
| Helixworks |
| Genisphere |
| Ginkgo Bioworks |
| Nanolab Technologies |
| Nanogami |
| DNA Nanobots |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Long Beach freight corridor shapes cost dynamics for phosphoramidite feedstock imports, concentrating supply leverage with East Asian chemical manufacturers while forcing pharmaceutical buyers to absorb premium pricing for GMP-certified cage architectures or accept extended procurement timelines from cost-sensitive Indian contract manufacturers.
Pricing Analysis
Pharmaceutical companies anchor pricing stratification across premium, standard, and economy tiers. Premium functionalized cages with pre-conjugated aptamer handles command spreads over benchtop self-assembling formats due to FDA-compliant documentation and accelerated IND-enabling timelines. Price differentiation hinges on certification grade and customization depth. Pricing pressure stems from phosphoramidite cost volatility tied to semiconductor-grade chemical supply chains. Biotechnology startups exhibit highest price sensitivity; integrated drug developers prioritize technical validation over unit economics.
Supply Chain Analysis
Phosphoramidite feedstock production draws from China, South Korea, and Japan, with purification and derivatization concentrated in Taiwanese chemical manufacturing hubs. DNA synthesis reagents, modified nucleoside building blocks, and solid-phase synthesis resins constitute critical input dependencies. Single-source vulnerability runs through East Asian semiconductor-grade chemical supply chains disrupted by export control restrictions. Distribution runs through contract research organizations in Boston and San Diego, with foundry-scale operators capturing margin through captive synthesis infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Designer DNA nanocages represent a service-attach opportunity where GMP compliance consulting and regulatory filing support expand faster than hardware sales of synthesis equipment or raw scaffold materials.
For Market Incumbents: Pre-empt foundry-scale consolidation by securing exclusive licensing terms with Massachusetts and California university technology transfer offices before equity-demanding structures become universal. Lock in phosphoramidite supply agreements with East Asian manufacturers to buffer against semiconductor chemical allocation shifts. Prioritize GMP facility qualification races in Switzerland and Germany where precision manufacturing clusters attract diagnostic-grade pharmaceutical sponsors. For New Entrants and Emerging Players: India's Maharashtra and Gujarat chemical manufacturing corridors offer underpenetrated contract synthesis capacity for cost-sensitive cage production under PLI scheme incentives. Target biotechnology firms seeking equity-friendly production partnerships rather than competing for pharmaceutical procurement tenders requiring multi-year GMP track records. Deploy digital microfluidic integration as a go-to-market angle to enable distributed, on-demand fabrication bypassing foundry infrastructure requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized biochemical synthesis houses with demonstrated in vivo stability data over platform-integrator foundries facing capital intensity pressures. Five-to-ten year viability hinges on regulatory approval velocity for nucleic acid therapeutic encapsulation platforms. Monitor FDA nucleic acid therapeutic framework expansion and EPA nanoscale material release protocol streamlining as inflection indicators for clinical translation timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Qualification | FDA-compliant cleanroom infrastructure accelerates IND timelines for cage-encapsulated payloads. |
| University Licensing Agreement | Equity-friendly terms with MIT and Stanford technology transfer offices secure exclusive origami architectures. |
| Backward Integration into Phosphoramidites | Captive synthesis of oligonucleotide feedstocks buffers East Asian supply chain volatility. |
| Regulatory Consulting Service Launch | ECHA REACH registration support captures expanded revenue from European diagnostic nanomaterial compliance burdens. |
| Digital Microfluidic Platform Integration | Benchtop automation partnerships compress DNA origami development cycles from months to weeks. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads at pharmaceutical sponsors, GMP facility managers, and technology transfer officers at Massachusetts and California universities. Secondary validation drew from FDA IND filings, EMA scientific advice letters, ClinicalTrials.gov entries for DNA nanocage programs, and SEC disclosures from synthetic biology foundries. Bottom-up cage production volume estimates were triangulated against top-down pharmaceutical R&D spending allocation models.
Calibration against historical nucleic acid therapeutic approval timelines and phosphoramidite price indices informed projection modeling across the analysis window. Segmentation dimensions included product architecture, synthesis methodology, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and pharmaceutical pipeline progression rates. Forecast inputs incorporated EPA nanoscale material release protocol evolution and ISO 10993 biocompatibility harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian contract manufacturers or sudden FDA framework acceleration would shift outcomes beyond modeled ranges. Cross-checking against ECHA substance registration databases and CDSCO biologics pathway announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nanozymes Market