
 Nanotechnology Drug Delivery Market | 2026-2036
Nanotechnology Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology Drug Delivery Market Intelligence
The EU Green Deal's pharmaceutical sustainability framework is realigning formulation priorities toward biodegradable nanocarriers and reduced solvent-intensive manufacturing. Pfizer Inc. leverages its lipid nanoparticle expertise from mRNA vaccine platforms to extend into oncology and rare disease applications. Johnson & Johnson anchors its nanomedicine pipeline through Janssen's nanocrystal technology, which enhances bioavailability of poorly soluble compounds. Novartis AG dominates the commercial landscape with FDA-approved nanotherapeutics including its liposomal cytarabine-daunorubicin formulation for acute myeloid leukemia.
Nanotechnology drug delivery engineers therapeutic payloads at dimensions typically below 200 nanometers, exploiting enhanced permeability and retention effects for passive tumor targeting or surface-conjugated ligands for active receptor-mediated uptake. Liposomes and polymeric nanoparticles represent the most mature product categories with established manufacturing scales, while dendrimers and carbon nanotubes occupy earlier-stage development pipelines with higher technical risk but differentiated payload capacity. Oncology applications command the largest current revenue share given the clinical validation of nanocarriers in solid tumor treatment, though neurological disorder applications are attracting accelerated investment as blood-brain barrier penetration technologies advance.
FDA's Center for Drug Evaluation and Research maintains specific nanotechnology guidance documents governing characterization, stability, and immunotoxicity evaluation, while EMA's reflection paper on nanomedicines creates parallel compliance obligations for European market access. ISO/TS 19337 provides standardized terminology and measurement protocols that reduce regulatory friction during multinational submissions. Stakeholders must monitor evolving bioequivalence standards for complex generic nanotherapeutics, as FDA and EMA divergence on interchangeability criteria could fragment market entry strategies for follow-on products.
Market Dynamics
The EU Green Deal's pharmaceutical sustainability framework is compressing formulation timelines toward biodegradable nanocarriers, forcing sponsors to revalidate legacy lipid-polymer platforms under tightened solvent-emission thresholds.
Growth Catalysts
- Accelerated Approval Pathways:FDA's nanotechnology-specific guidance compresses IND-to-NDA timelines for complex generic nanotherapeutics. Sponsors exploit this regulatory channel for liposomal oncology platforms.
- Blood-Brain Barrier Technologies:Surface-modified polymeric nanoparticles enable receptor-mediated transcytosis for neurological applications. Academic medical centers in Germany and Japan are expanding compassionate-use protocols.
- National Cancer Institute Infrastructure:The Nanotechnology Characterization Laboratory validates physicochemical parameters and immunotoxicity profiles, de-risking commercial translation for emerging platforms.
Market Restraints
- High-Purity Lipid Supply Concentration:Ionizable cationic lipids for mRNA-nanoparticle formulations depend on a concentrated supplier base in Switzerland and Germany, exposing sponsors to input-cost volatility.
- Complex Generic Bioequivalence Divergence:FDA and EMA maintain non-aligned interchangeability criteria for follow-on nanotherapeutics, fragmenting market-entry strategies and extending legal-review timelines.
- Manufacturing Scale-Up Thermodynamics:Microfluidic mixing protocols for uniform particle-size distributions face heat-transfer limitations above 100-liter batch volumes, constraining single-use bioreactor adoption.
Strategic Opportunities
- India's CDSCO Fast-Track Channel:The country's pharmaceutical regulator offers expedited review for nanomedicines addressing unmet oncology needs, attracting contract-manufacturing investment from Western sponsors.
- Exosome-Derived Delivery Convergence:Native extracellular vesicles are converging with synthetic lipid engineering to reduce immunogenicity risks. Biotech platforms in South Korea and Singapore lead preclinical translation.
- EU Green Deal Biodegradable Mandates:Formulation priorities are realigning toward polylactic-co-glycolic acid and chitosan carriers, creating first-mover advantage for sponsors with validated biodegradable-scale chemistry.
Industry Challenges
- Particle-Characterization Talent Scarcity:Analytical method development for dynamic light scattering and nanoparticle tracking analysis requires specialized skill sets that outpace graduate-program output in the United States and Europe.
- ISO/TS 19337 Implementation Friction:Standardized terminology and measurement protocols for multinational submissions demand harmonization across quality-assurance functions, extending documentation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology Drug Delivery Market |
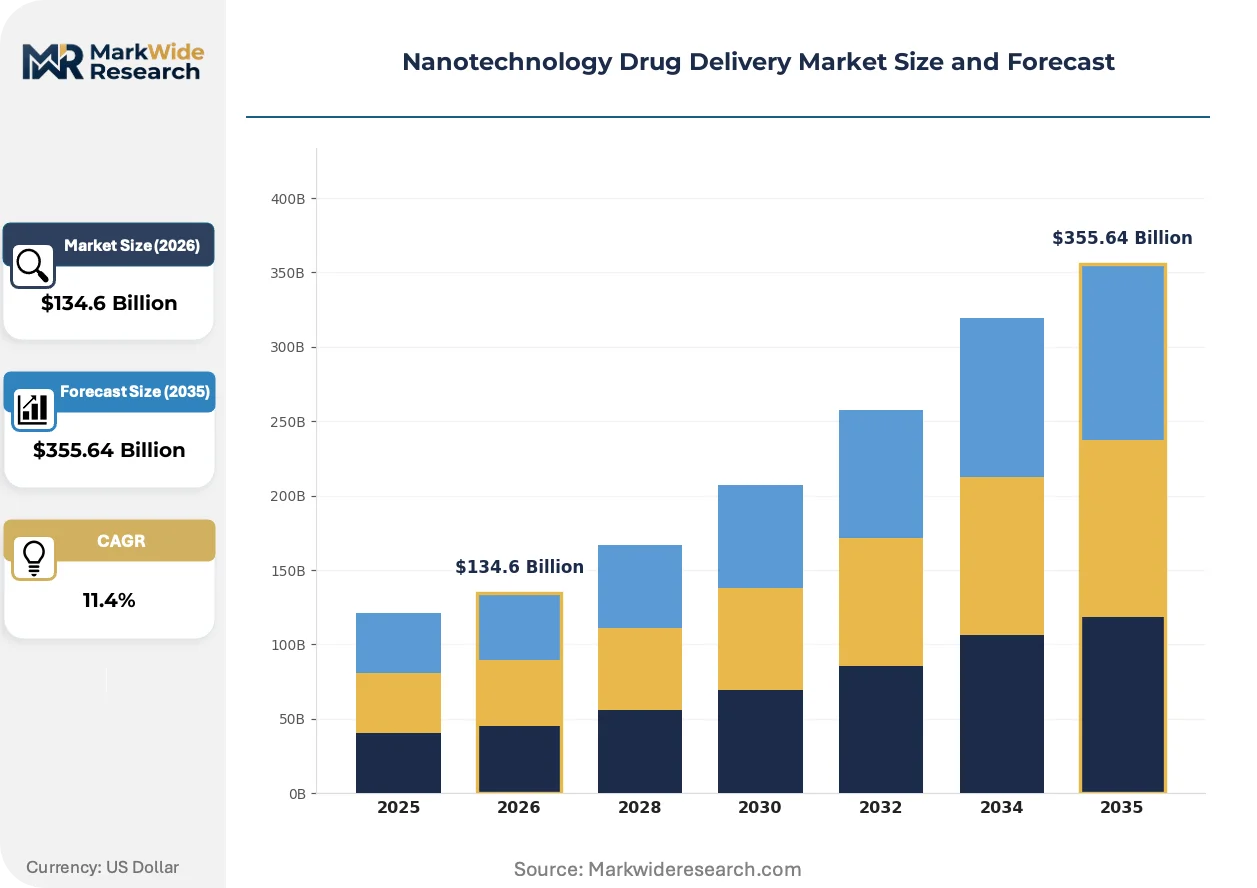
| Market Size in 2026 | $134.6 Billion |
| Market Size in 2035 | $355.64 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomes, Dendrimers, Nanoparticles, Nanocrystals, Nanotubes Application: Oncology, Cardiovascular Disorders, Infectious Diseases, Neurological Disorders, Autoimmune Diseases Delivery Technique: Intravenous, Transdermal, Oral, Inhalation, Targeted Delivery End User: Pharmaceutical Manufacturers, Biotechnology Firms, Research Institutes, Contract Research Organizations |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Johnson & Johnson, Novartis AG, Bristol-Myers Squibb, Roche Holding AG, AbbVie Inc., Sanofi S.A., Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology Drug Delivery Market Strategic Shifts & Innovations
Active pharmaceutical ingredient solubility limitations are forcing convergence between materials-science advances and regulatory-science frameworks, reshaping how sponsors design characterization packages for commercial-scale nanocarriers.
Targeted protein degradation moieties delivered via polymeric nanoparticles are converging with antibody-directed cellular uptake mechanisms. Oncology-focused biotech platforms in Massachusetts and Basel are adopting these bifunctional systems for solid-tumor penetration. The technology is converging with companion-diagnostic development, compressing patient-stratification timelines and reshaping clinical-trial enrollment.
EMA's reflection paper on nanomedicines creates parallel compliance obligations for stability and immunotoxicity evaluation beyond FDA requirements. European sponsors must duplicate characterization studies or risk market-access delays. Liposomal cytarabine-daunorubicin formulations and similar complex generics face the tightest scrutiny, with notified bodies demanding extended real-world evidence packages.
Hospital formulary committees are consolidating purchasing authority for nanotherapeutics under centralized pharmacy-therapeutics review. Academic medical centers in Texas, Bavaria, and Kanagawa are unbundling infusion-service contracts from drug-procurement agreements. This shift is most visible in oncology departments where biosimilar nanomedicines compete for limited infusion-chair capacity and cold-chain logistics slots.
Nanotechnology Drug Delivery Market Segmentation
Nanotechnology drug delivery platforms require precise technical segmentation to align formulation architectures with disease-specific penetration requirements. Each dimension—product chemistry, clinical indication, administration route, and development stakeholder—creates distinct value-capture opportunities and regulatory validation pathways.
Product Type:
Upgrade cycles from conventional formulations to nanoscale architectures are accelerating as sponsors pursue bioavailability improvements and patent-life extensions.
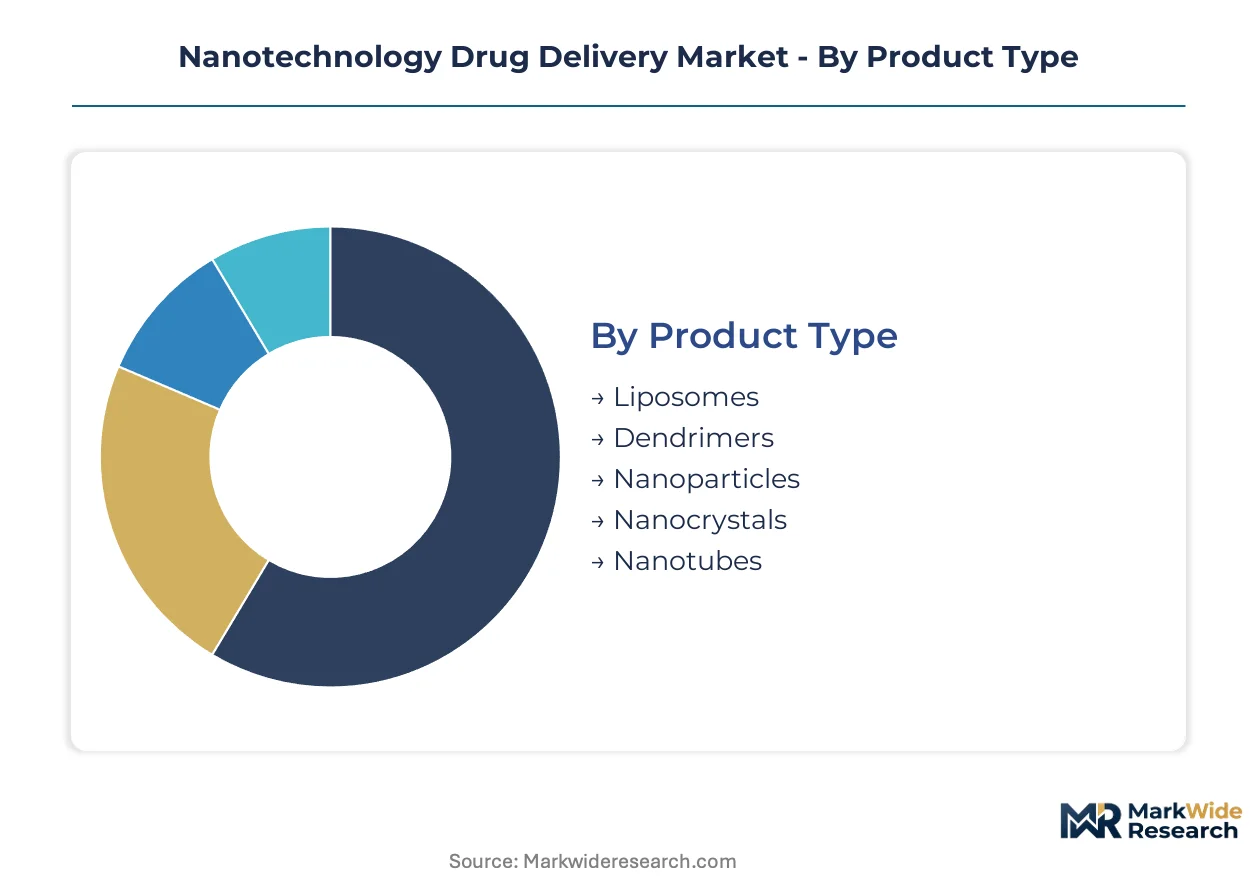
- Liposomes:Phospholipid bilayer vesicles encapsulate hydrophilic cores within hydrophobic membranes, enabling sustained-release kinetics for cytotoxic agents. Demand concentrates in United States oncology infusion centers where liposomal doxorubicin formulations command preferred formulary status for Kaposi's sarcoma and ovarian cancer protocols.
- Nanoparticles:Polymeric or lipid-based solid matrices below 200 nanometers exploit enhanced permeability and retention effects for passive tumor accumulation. German and Swiss contract manufacturers are expanding GMP capacity for poly(lactic-co-glycolic acid) platforms as biodegradable mandates tighten under EU Green Deal frameworks.
- Dendrimers:Hyperbranched macromolecules with defined generational layers enable precise payload multivalency for targeted ligand presentation.
- Nanocrystals:Pure drug nanoscale crystals enhance dissolution velocity for poorly soluble compounds without carrier excipients.
- Nanotubes:Cylindrical carbon or inorganic structures offer exceptional mechanical strength and electrical conductivity for stimuli-responsive release applications.
Liposomes sit at the top of the volume ranking, with nanoparticles climbing the fastest as mRNA-lipid expertise transfers into oncology and rare disease pipelines.
Application:
Clinical indication selection determines reimbursement architecture and companion diagnostic requirements, with oncology commanding the most mature commercial infrastructure.
- Oncology:Solid tumor penetration via passive EPR effects or active receptor targeting dominates current revenue concentration. Academic medical centers in Texas and Bavaria are consolidating nanotherapeutic purchasing under centralized pharmacy-therapeutics committees.
- Neurological Disorders:Blood-brain barrier penetration technologies using surface-modified carriers are attracting accelerated investment. Japanese and German regulators have expanded compassionate-use protocols for receptor-mediated transcytosis platforms in glioblastoma and Alzheimer's models.
- Cardiovascular Disorders:Nanocarrier delivery of statin combinations and antithrombotic agents targets atherosclerotic plaque microenvironments.
- Infectious Diseases:Lipid nanoparticle mRNA platforms demonstrated scalable infectious disease prophylaxis, with manufacturing infrastructure now repurposing for antimicrobial resistance indications.
- Autoimmune Diseases:Tolerogenic nanoparticle delivery of antigen-specific immunomodulators is advancing through preclinical stages for multiple sclerosis and rheumatoid arthritis.
Oncology captures the dominant revenue position, while neurological disorders are expanding most quickly as BBB technologies mature.
Delivery Technique:
Route of administration selection constrains particle-size specifications and stability requirements, with intravenous infusion establishing the baseline for complex nanotherapeutic validation.
- Intravenous:Direct systemic circulation enables immediate bioavailability for emergency oncology protocols and requires stringent endotoxin controls. United States hospital systems are unbundling infusion-service contracts from drug-procurement agreements, reshaping vendor selection criteria.
- Targeted Delivery:Ligand-conjugated or magnetically guided systems achieve cell-specific uptake with reduced off-tissue exposure. South Korean and Singaporean biotech platforms are converging exosome engineering with synthetic lipid systems for reduced immunogenicity profiles.
- Transdermal:Microneedle arrays and permeation-enhancing lipid systems bypass hepatic first-pass metabolism for chronic disease management.
- Oral:Gastrointestinal stability challenges limit current applicability, though enteric-coated nanocrystals are advancing for chronic cardiovascular indications.
- Inhalation:Pulmonary deposition of lipid nanoparticles targets respiratory infections and local lung malignancies with reduced systemic exposure.
Intravenous administration maintains volume leadership, with targeted delivery gaining share fastest as companion diagnostic integration compresses patient stratification timelines.
End User:
Development-stage partnerships determine IP ownership structures and regulatory submission responsibilities, with pharmaceutical manufacturers retaining commercialization control for approved platforms.
- Pharmaceutical Manufacturers:Integrated sponsors manage full lifecycle development from preclinical characterization through post-marketing surveillance. FDA's nanotechnology-specific guidance documents compress IND-to-NDA timelines for sponsors with established lipid-nanoparticle manufacturing expertise.
- Contract Research Organizations:Specialized CROs provide GMP manufacturing and analytical method development for emerging biotech sponsors. India's CDSCO fast-track channel is attracting Western contract-manufacturing investment for oncology-focused nanomedicines.
- Biotechnology Firms:Platform-technology companies license delivery architectures to pharmaceutical partners for disease-specific applications.
- Research Institutes:Academic centers generate foundational characterization data through the National Cancer Institute's Nanotechnology Characterization Laboratory and equivalent European infrastructure.
Pharmaceutical manufacturers dominate current volume, with contract research organizations expanding most quickly as virtual biotech models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The nanotechnology drug delivery industry traces its commercial roots to the United States, where the National Cancer Institute established the Nanotechnology Characterization Laboratory in 2004 to standardize preclinical validation protocols. This infrastructure enabled the first wave of FDA-approved liposomal oncology formulations. Manufacturing and clinical adoption have since diffused across Switzerland, Germany, Japan, and India, each developing specialized capabilities aligned with domestic regulatory frameworks and therapeutic priorities.
United States
Oncology infusion centers at MD Anderson in Houston and Memorial Sloan Kettering in New York drive demand for liposomal doxorubicin and paclitaxel albumin-bound formulations. FDA's accelerated approval pathway for nanotechnology-enabled therapies compresses IND-to-NDA timelines, attracting sponsor investment. Boston's Kendall Square biotech cluster hosts platform-technology firms licensing delivery architectures to pharmaceutical partners.
Germany
Bavarian contract manufacturers expand GMP capacity for poly(lactic-co-glycolic acid) platforms as EU Green Deal solvent-emission thresholds tighten. EMA's reflection paper on nanomedicines mandates stability and immunotoxicity studies beyond FDA requirements, extending documentation timelines for European market access. Heidelberg and Munich academic medical centers lead compassionate-use protocols for blood-brain barrier penetration technologies.
Switzerland
Basel anchors lipid-nanoparticle expertise transfer from mRNA vaccine platforms into oncology applications. Swissmedic maintains alignment with EMA nanomedicine guidance while offering streamlined review for biodegradable carrier innovations. The Lake Geneva region concentrates ionizable cationic lipid suppliers, exposing sponsors to input-cost volatility from concentrated high-purity feedstock production.
Japan
PMDA expanded compassionate-use pathways for receptor-mediated transcytosis platforms in glioblastoma and Alzheimer's models. Tokyo and Kanagawa academic medical centers unbundle infusion-service contracts from drug-procurement agreements, reshaping vendor selection criteria. METI funding prioritizes blood-brain barrier technologies through national innovation programs targeting neurological disorder unmet needs.
India
CDSCO's fast-track channel for nanomedicines addressing unmet oncology needs attracts Western contract-manufacturing investment. Hyderabad and Ahmedabad clusters specialize in generic liposomal formulation production for export markets. Domestic pharmaceutical manufacturers leverage cost-advantaged analytical method development to serve virtual biotech sponsors lacking in-house characterization capabilities.
Nanotechnology Drug Delivery Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory validation depth, with integrated pharmaceutical manufacturers commanding pricing power derived from established lipid-nanoparticle manufacturing expertise. The vendor base stratifies into three archetypes: platform-technology licensors monetizing delivery architectures, full-stack sponsors managing lifecycle development from preclinical characterization through post-marketing surveillance, and specialized contract manufacturers offering GMP capacity for emerging biotech sponsors. Dominant competitive moves include strategic partnerships for companion-diagnostic integration and capacity expansion in biodegradable carrier chemistry to align with EU Green Deal mandates.
Within the integrated pharmaceutical tier, Pfizer Inc., Novartis AG, and Johnson & Johnson occupy positions defined by established nanomedicine formularies and regulatory submission track records. Pfizer exemplifies platform-technology leverage, transferring lipid-nanoparticle expertise across therapeutic categories. Novartis anchors the commercial landscape through FDA-approved liposomal cytarabine-daunorubicin formulations for acute myeloid leukemia. Johnson & Johnson represents nanocrystal technology specialization, enhancing bioavailability of poorly soluble compounds through Janssen's delivery platforms. These three entities sit within a competitive structure where manufacturing scale and regulatory relationships determine formulary access and infusion-service contract awards.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Novartis AG |
| Bristol-Myers Squibb |
| Roche Holding AG |
| AbbVie Inc. |
| Sanofi S.A. |
| Amgen Inc. |
| Others |
Cost & Logistics Intelligence
Regulatory certification tiers separate GMP-validated lipid-nanoparticle formulations from preclinical-grade materials, creating a bifurcation that concentrates pricing power among sponsors with FDA master file submissions while forcing commodity-grade suppliers into volume-driven contracts with contract research organizations in India and Germany.
Pricing Analysis
Value-based pricing tied to clinical outcome metrics governs commercial-stage nanotherapeutics, with oncology formulations commanding premium positioning against cardiovascular applications due to companion diagnostic bundling and unmet need severity. Price differentiation rests on regulatory validation depth—FDA-approved platforms capture formulary preference over EMA-only submissions. Cost compression in generic liposomal segments is intensifying because of CDSCO fast-track approvals in India. Hospital pharmacy-therapeutics committees exhibit highest price sensitivity, while rare disease sponsors face lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
GMP certification and FDA master file status gate supplier qualification, limiting ionizable cationic lipid sourcing to Switzerland, Germany, and select US facilities with validated analytical methods. Manufacturing draws from high-purity phospholipid feedstocks, single-use bioreactor assemblies, and specialized microfluidic mixing hardware. Single-source vulnerability concentrates around Swiss-German lipid suppliers exposed to solvent-emission regulatory tightening. Distribution runs through cold-chain logistics networks serving academic medical centers and hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory validation, with FDA's nanotechnology-specific guidance compressing development timelines and expanding addressable patient populations for sponsors with established characterization capabilities.
For Market Incumbents: Deepen lipid-nanoparticle manufacturing expertise through backward integration into high-purity cationic lipid production, defending against emerging platform-technology licensors from South Korea and Singapore. Expand GMP capacity in biodegradable carrier chemistry to align with EU Green Deal solvent-emission mandates.
For New Entrants and Emerging Players: Capture neurological disorder applications where blood-brain barrier penetration technologies remain underpenetrated relative to oncology saturation. Target Japanese and German compassionate-use pathways for receptor-mediated transcytosis platforms. Pursue exosome-derived delivery convergence through academic medical center partnerships.
For Investors and Strategic Acquirers: Consolidation pressure builds where particle-characterization talent scarcity outpaces graduate program output in the United States and Europe. Long-term viability favors vertically integrated sponsors with regulatory submission track records across multiple jurisdictions. Watch for FDA-EMA bioequivalence divergence resolution as inflection signal for complex generic nanotherapeutic entry strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA nanotechnology guidance compresses IND-to-NDA timelines for lipid-nanoparticle sponsors. |
| Manufacturing Scale-Up | Microfluidic mixing capacity expansion addresses heat-transfer limitations above 100-liter batches. |
| Backward Integration | In-house cationic lipid production reduces exposure to Swiss-German supplier concentration. |
| Companion Diagnostic Integration | Patient stratification bundling with nanotherapeutics secures formulary preference in oncology. |
| Biodegradable Carrier Transition | Polylactic-co-glycolic acid platform validation aligns with EU Green Deal emission mandates. |
Research Approach
Direct dialogue with regulatory affairs leads, formulary directors at academic medical centers, nanomedicine platform engineers, and contract manufacturing executives grounded qualitative assessment, cross-referenced with FDA nanotechnology guidance documents, EMA reflection papers, ClinicalTrials.gov entries, and ISO/TS 19337 technical specifications. Bottom-up segment sizing and top-down market triangulation validated volume estimates.
Bottom-up modeling anchored projections across product chemistry, clinical indication, administration route, and development stakeholder segments, with top-down cross-checks against National Cancer Institute infrastructure investment and pharmaceutical R&D disclosure patterns. CAGRs were derived from segment-level growth rate blending and regulatory milestone timing. Blood-brain barrier technology maturation and EU Green Deal implementation pace served as scenario variables.
Regulatory guidance revision, bioequivalence standard divergence between FDA and EMA, and ionizable cationic lipid supply disruption are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA nanotechnology characterization requirements or EMA nanomedicine reflection paper updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanopore Technologies Market