
 Nanobiotechnology Market | 2026-2036
Nanobiotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Nanobiotechnology Market Outlook
Buyer concentration among pharmaceutical companies is shifting as large drugmakers consolidate procurement while biotech startups fragment demand with specialized nanocarrier contracts. Johnson & Johnson Services, Inc. leverages its vertically integrated device-pharma platform to control nano-formulation pipelines. Thermo Fisher Scientific, Inc. dominates analytical instrumentation supply for nanoparticle characterization. Danaher Corporation anchors life sciences tooling through its operating company structure.
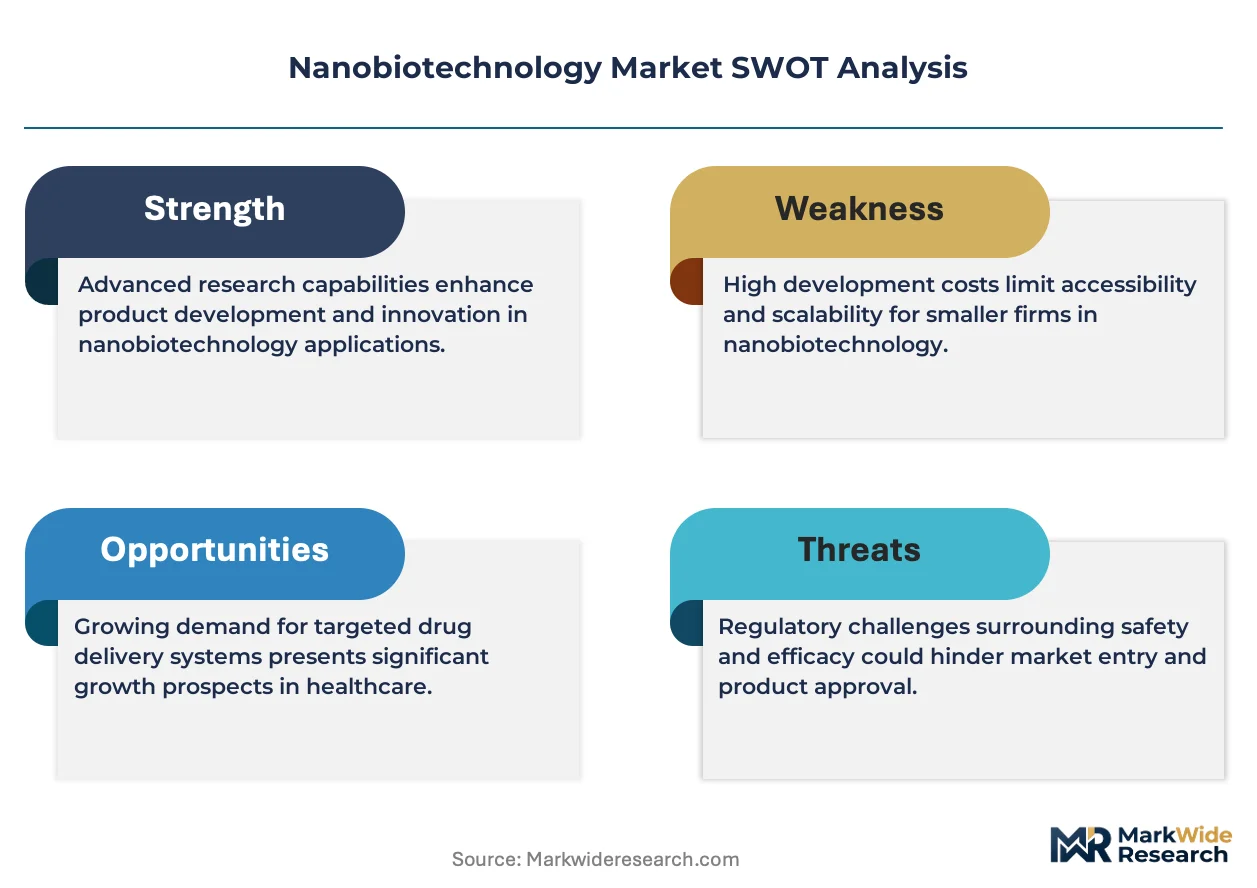
Nanobiotechnology fuses nanoscale materials with biological systems, typically operating at 1-100 nanometers where quantum effects alter surface reactivity, drug loading capacity, and cellular uptake kinetics. Sol-gel synthesis and electrospinning constitute primary manufacturing routes for producing biocompatible nanofibers and porous silica carriers with tunable pore diameters. Nanocarriers command margin concentration in drug delivery applications due to formulation complexity and patent protection, while nanosensors in diagnostics represent the fastest-expanding application segment driven by point-of-care miniaturization. Regenerative medicine applications remain comparatively nascent, with scaffold-based nanofiber products requiring extended clinical validation timelines.
The FDA oversees nanomedicine safety through its Nanotechnology Task Force guidance, while the EPA regulates environmental release of engineered nanomaterials under the Toxic Substances Control Act. ISO 10993 biocompatibility standards govern preclinical evaluation frameworks, creating compliance cost barriers for new entrants. Stakeholders must monitor evolving EMA nanomedicine reflection papers and FDA combination product rulings to anticipate classification decisions that determine approval pathways and competitive positioning.
Market Dynamics
FDA's accelerated approval pathways for nanomedicines are compressing development timelines and forcing pharmaceutical companies to restructure their formulation partnerships around speed-to-clinic metrics rather than traditional milestone-based contracting.
Growth Catalysts
- NIH nano-enabled diagnostics funding:United States federal research budgets are expanding fabrication capabilities for point-of-care nanosensors, directly stimulating contract manufacturing demand.
- EMA nanomedicine reflection papers:European regulatory clarity on classification criteria is reducing submission preparation uncertainty and shortening pre-IND consultation cycles.
- Lipid nanoparticle mRNA platforms:Post-pandemic manufacturing infrastructure is repurposing toward oncology and rare disease applications, creating capacity spillover.
Market Restraints
- High-purity reagent cost volatility:Pharmaceutical-grade phospholipids and PEGylated lipids face supply concentration among specialty chemical producers in Switzerland and Germany.
- ISO 10993 biocompatibility testing backlog:Preclinical evaluation frameworks require extended cytotoxicity and sensitization studies, creating queue delays at certified laboratories.
- Silicon-based quantum dot substitution:Carbon nanodots and graphene quantum dots are displacing heavy metal-containing alternatives in imaging applications, eroding incumbent process investments.
Strategic Opportunities
- Underpenetrated Brazil:ANVISA's emerging nanomedicine guidance framework creates first-mover advantage for companies establishing local bioequivalence testing partnerships.
- AI-driven nanoparticle design:Machine learning algorithms for predicting protein-corona formation are converging with high-throughput microfluidic synthesis, compressing lead optimization cycles.
- Cell and gene therapy vector demand:Viral and non-viral nanocarrier requirements for CRISPR delivery are outpacing dedicated manufacturing capacity in North America.
Industry Challenges
- Cross-functional nanotoxicology expertise gap:Formulation scientists with combined materials chemistry and immunology training command premium compensation and extended recruitment timelines.
- Scale-up reproducibility failures:Microfluidic manufacturing parameters optimized at milliliter scales frequently destabilize during liter-scale GMP batch transitions.
- Patent thickets around PEGylation:Dense intellectual property landscapes surrounding polyethylene glycol surface modifications complicate freedom-to-operate analyses for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanobiotechnology Market |
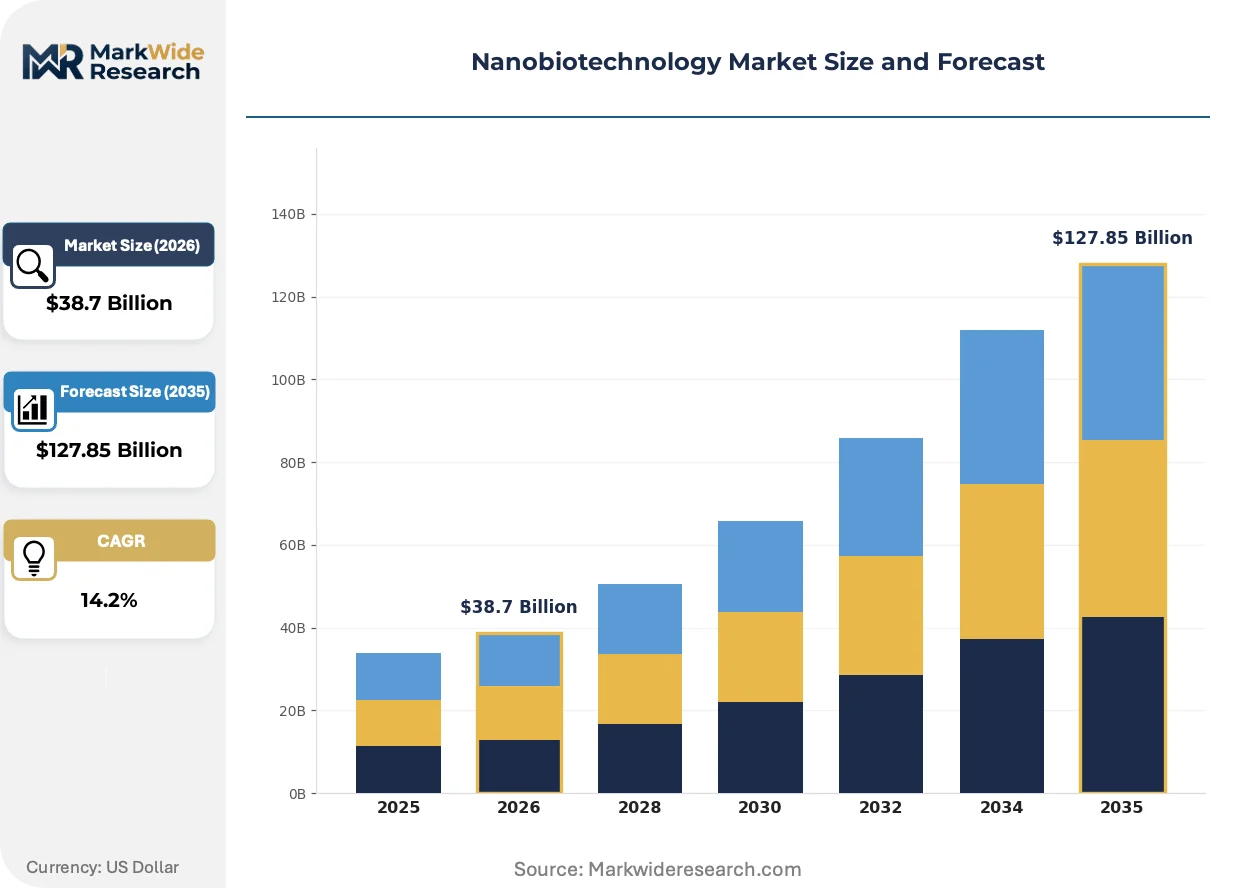
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanosensors, Nanocarriers, Nanoparticles, Nanofibers Application: Drug Delivery, Diagnostics, Imaging, Regenerative Medicine End User: Pharmaceutical Companies, Research Institutions, Healthcare Providers, Biotech Firms Technology: Electrospinning, Laser Ablation, Sol-Gel Synthesis, Chemical Vapor Deposition |
| Companies Covered | Johnson & Johnson Services, Inc., Abbott, Novartis AG, Merck and Co. Inc., Thermo Fisher Scientific, Inc., Pfizer, Inc., Sanofi, Danaher Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanobiotechnology Market Strategic Shifts
Active pharmaceutical ingredient delivery is undergoing platform consolidation as single-function nanocarriers give way to multifunctional systems integrating targeting, imaging, and triggered release within single architectures.
DNA origami is unifying structural scaffolding with therapeutic cargo encapsulation, enabling sub-50 nanometer containers with programmable shape-dependent cellular uptake. Oncology drug developers at major pharmaceutical firms are adopting these platforms for tumor microenvironment penetration studies. The technology is unifying previously separate synthetic biology and nanomedicine supplier ecosystems into integrated service offerings.
REACH registration requirements for engineered nanomaterials are mandating extensive physicochemical characterization data sets prior to commercial import into European Union member states. Chemical manufacturers must submit dissolution kinetics and environmental fate studies that exceed standard bulk substance dossiers. Nanocarrier suppliers serving EU pharmaceutical markets are responding by establishing captive analytical laboratories or exclusive partnerships with European contract research organizations.
Hospital procurement departments are consolidating nanodiagnostic contracts under centralized laboratory management structures, displacing decentralized point-of-care purchasing decisions. Integrated delivery networks in the United States are negotiating multi-year supply agreements covering reagents, instruments, and service contracts as unified bundles. This consolidation is most visible in academic medical centers where pathology and radiology departments previously operated independent nanoparticle-based imaging agent budgets.
Nanobiotechnology Market Segmentation
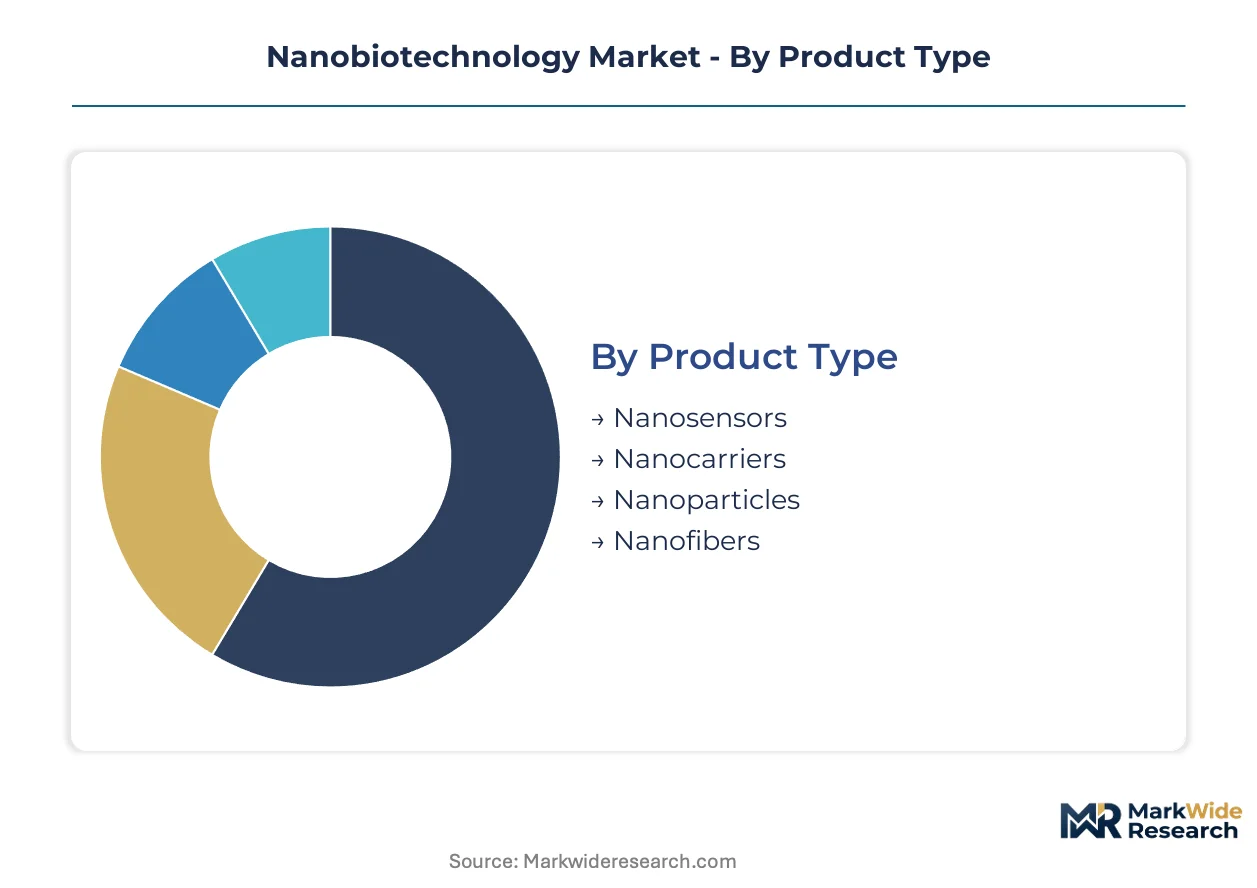
Segmentation in nanobiotechnology reveals how technical specifications, regulatory pathways, and procurement authority distribute value across the value chain. Buyers prioritize different performance attributes depending on whether they seek GMP-compliant manufacturing inputs or research-grade materials.
Product Type:
Buyers in this category differentiate primarily by formulation complexity and patent protection intensity.
- Nanocarriers:Lipid nanoparticles and polymeric micelles encapsulate active pharmaceutical ingredients with tunable release kinetics. Demand concentrates among oncology drug developers at large pharmaceutical firms seeking tumor microenvironment penetration, constrained by phospholipid supply concentration in Switzerland and Germany.
- Nanosensors:Quantum dots and plasmonic nanoparticles detect biomarkers with single-molecule sensitivity. NIH-funded point-of-care diagnostics programs in the United States are expanding fabrication contracts for electrochemical and optical transducer platforms.
- Nanoparticles:Metallic and ceramic cores serve imaging contrast and thermal therapy functions.
- Nanofibers:Electrospun scaffolds guide tissue regeneration with biomimetic topography.
Nanocarriers lead volumes today; nanosensors are gaining share fastest.
Application:
Margin concentration varies sharply by clinical validation timeline and reimbursement certainty.
- Drug Delivery:Targeted therapeutics using antibody-conjugated liposomes and exosome mimics achieve enhanced permeability and retention in tumor tissue. EMA nanomedicine reflection papers are shortening pre-IND consultation cycles for European submissions.
- Diagnostics:Lateral flow assays and lab-on-chip devices miniaturize nucleic acid and protein detection. Hospital procurement consolidation under integrated delivery networks in the United States is bundling reagent and instrument contracts.
- Imaging:Superparamagnetic iron oxide and gold nanorods enhance MRI and photoacoustic contrast.
- Regenerative Medicine:Nanofiber scaffolds and self-assembling peptides direct stem cell differentiation.
Drug delivery commands the steepest margins; diagnostics shows the most rapid volume expansion.
End User:
Procurement scale and technical specification authority separate institutional buyers in this dimension.
- Pharmaceutical Companies:Large drugmakers consolidate nanocarrier procurement under centralized formulation partnerships, prioritizing speed-to-clinic metrics over milestone-based contracting. FDA accelerated approval pathways are compressing vendor selection timelines.
- Biotech Firms:Venture-backed developers fragment demand with specialized contracts for DNA origami containers and CRISPR delivery vectors.
- Research Institutions:Academic laboratories purchase exploratory quantities through NIH grant mechanisms.
- Healthcare Providers:Academic medical centers negotiate multi-year supply agreements covering nanoparticle-based imaging agents.
Pharmaceutical companies dominate current procurement; biotech firms are expanding contract volume most aggressively.
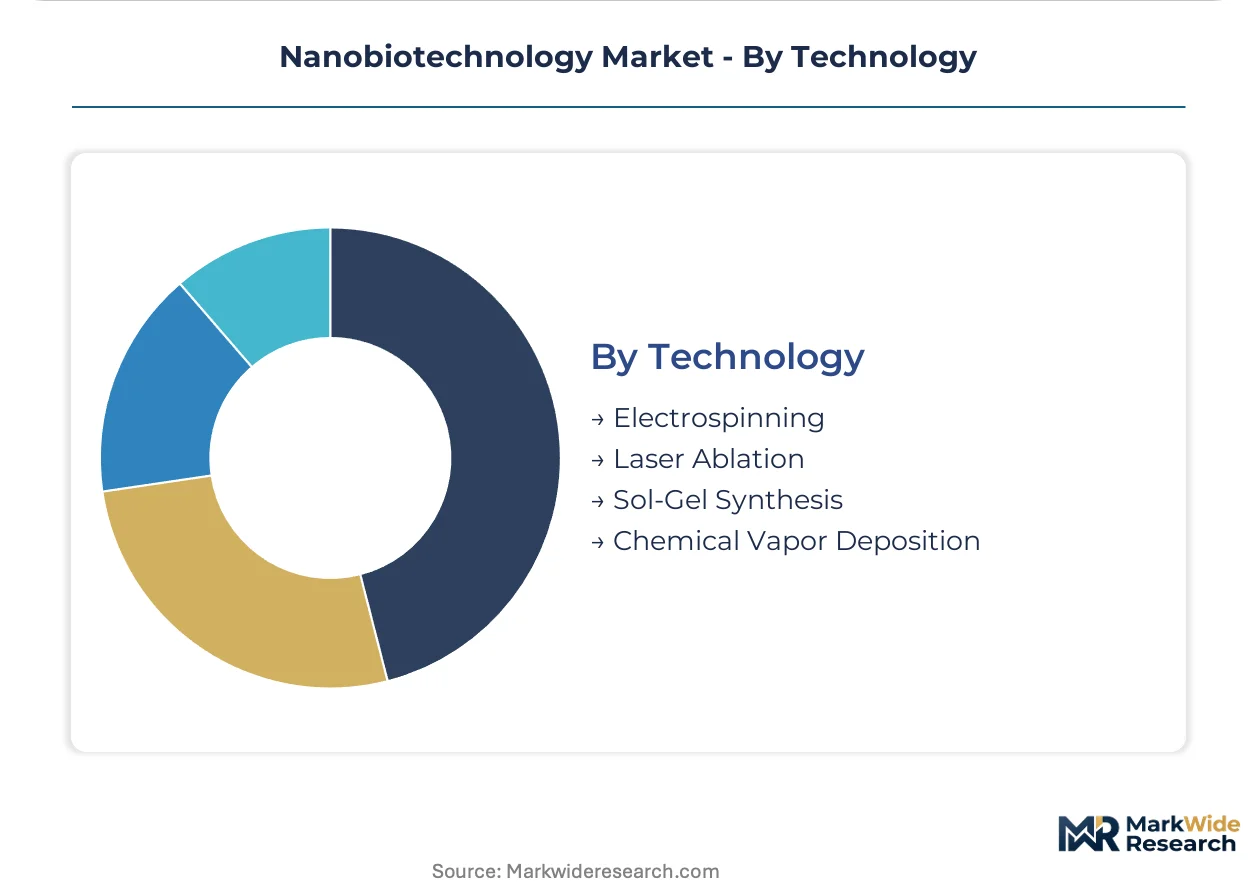
Technology:
Manufacturing scalability and GMP translation readiness determine technology selection.
- Sol-Gel Synthesis:Produces porous silica carriers with controlled pore diameters for drug loading. Post-pandemic lipid nanoparticle infrastructure is repurposing toward oncology applications, creating capacity spillover for hybrid organic-inorganic systems.
- Electrospinning:Generates aligned nanofiber scaffolds with biomimetic mechanical properties. Scale-up reproducibility failures at liter-scale GMP transitions constrain regenerative medicine commercialization.
- Laser Ablation:Fabricates ligand-free metal nanoparticles with defined size distributions.
- Chemical Vapor Deposition:Deposits conformal coatings for implantable device biocompatibility.
Sol-gel synthesis anchors current manufacturing volume; electrospinning is climbing fastest in regenerative medicine applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands larger NIH nano-enabled diagnostics budgets than Germany, yet Swiss phospholipid suppliers constrain formulation capacity for both markets. Regulatory clarity and manufacturing infrastructure divergence separate high-activity clusters from emerging contenders.
United States
FDA accelerated approval pathways compress nanomedicine development timelines for oncology developers clustered around Boston and San Francisco. NIH funding for point-of-care nanosensors intensifies fabrication contract demand in Maryland and Massachusetts research corridors. The National Nanotechnology Initiative coordinates federal investment across 20 agency programs.
Germany
EMA nanomedicine reflection papers reduce submission uncertainty for Heidelberg and Munich-based drug developers. REACH registration mandates for engineered nanomaterials require extensive physicochemical dossiers prior to commercial import. The country's specialty chemical producers in Ludwigshafen and Leverkusen concentrate pharmaceutical-grade phospholipid supply.
Switzerland
Swissmedic maintains stringent nanomedicine classification criteria that shape European regulatory precedent. Basel anchors Roche and Novartis formulation pipelines with integrated nanocarrier development capabilities. The country's precision manufacturing heritage supports cGMP lipid nanoparticle production at scale.
China
NMPA reform of nanomedicine review standards accelerates domestic oncology product approvals. Yangtze River Delta clusters in Shanghai and Suzhou attract contract manufacturing investment for lipid nanoparticle platforms. The country's dual carbon goals drive substitution toward carbon-based quantum dots in imaging applications.
Brazil
ANVISA's emerging nanomedicine guidance creates first-mover positioning for bioequivalence testing partnerships. São Paulo academic medical centers consolidate nanoparticle-based imaging agent procurement under unified laboratory management. Local pharmaceutical distributors anticipate regulatory alignment with FDA and EMA precedents.
Nanobiotechnology Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation, instrumentation, and reagent supply tiers. Johnson & Johnson Services, Inc. and Danaher Corporation anchor vertically integrated platforms spanning device-pharma convergence and life sciences tooling. Three archetypes dominate: pharmaceutical conglomerates with captive nanocarrier pipelines, analytical instrumentation suppliers controlling characterization workflows, and specialty chemical producers commanding high-purity lipid inputs. Competitive moves concentrate on M&A for microfluidic manufacturing capabilities and strategic partnerships for AI-driven nanoparticle design platforms.
Among pharmaceutical conglomerates, Johnson & Johnson Services, Inc. and Novartis AG exemplify integrated platform strategies spanning therapeutic development through commercial formulation. Thermo Fisher Scientific, Inc. anchors the analytical instrumentation tier with nanoparticle characterization workflows. Danaher Corporation occupies a distinctive position through its operating company structure consolidating life sciences tooling supply. Merck KGaA represents the specialty chemical archetype with phospholipid and PEGylated lipid production concentration.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Abbott |
| Novartis AG |
| Merck and Co. Inc. |
| Thermo Fisher Scientific, Inc. |
| Pfizer, Inc. |
| Sanofi |
| Danaher Corporation |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade phospholipid spot indices in Basel and Ludwigshafen cascade through nanocarrier manufacturing tiers, compressing margins for formulation specialists while amplifying pricing power for integrated chemical conglomerates with captive lipid production.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for research-grade nanoparticles. Three-tier pricing structure across GMP-certified, ISO-compliant, and exploratory-grade levels separates pharmaceutical procurement from academic purchasing. Cost compression in standard-grade nanosensors is intensifying because NIH-funded fabrication contracts favor domestic US suppliers. Biotech startups exhibit highest price sensitivity due to grant-dependent budgets, while large pharmaceutical firms prioritize speed-to-clinic over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and German phospholipid producers for pharmaceutical-grade lipid nanoparticle inputs. Manufacturing gravity centers on Switzerland, Germany, and the United States for GMP-compliant nanocarriers, with China expanding share in research-grade materials. The value chain draws from high-purity phospholipids, PEGylated lipids, and specialized microfluidic chips as critical inputs. Tariff exposure on European chemical imports threatens US formulation cost structures. Distribution runs through integrated delivery networks consolidating multi-year reagent and instrument bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nanobiotechnology functions as a stable compounder anchored by FDA and EMA regulatory pathways that extend product lifecycle exclusivity for approved nanomedicines.
For Market Incumbents: Deploy AI-driven nanoparticle design platforms to compress lead optimization cycles against emerging machine-learning-native competitors. Secure backward integration into high-purity phospholipid supply through exclusive partnerships with Swiss chemical producers. Patent thicket navigation around PEGylation technologies constitutes the priority defensive investment. For New Entrants and Emerging Players: Capture ANVISA's emerging nanomedicine guidance window in Brazil through local bioequivalence testing partnerships before regulatory alignment with FDA precedents closes first-mover positioning. AI-driven protein-corona prediction tools represent the most penetrable white space. Lead with CRISPR delivery vector specialization to bypass incumbent lipid nanopptide dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with microfluidic manufacturing specialists holding GMP translation capabilities for cell and gene therapy vectors. The five-to-ten year horizon favors platforms with demonstrated scale-up reproducibility beyond milliliter proof-of-concept. Monitor EMA nanomedicine reflection paper evolution as the signal indicating European submission preparation demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Manufacturing Scale-Up | GMP translation capabilities unlock cell and gene therapy vector contracts from venture-backed developers. |
| AI-Driven Nanoparticle Design Partnership | Machine learning platforms for protein-corona prediction compress lead optimization cycles for oncology developers. |
| Captive Phospholipid Supply Agreement | Exclusive sourcing from Ludwigshafen or Basel producers insulates formulation margins against reagent cost volatility. |
| ANVISA Bioequivalence Testing Localization | First-mover establishment in São Paulo captures Brazil's emerging nanomedicine regulatory alignment with FDA precedents. |
| DNA Origami Platform Integration | Structural scaffolding unification with therapeutic cargo encapsulation opens sub-50 nanometer tumor penetration applications. |
Study Parameters
Direct dialogue with nanomedicine formulation scientists, regulatory affairs directors at pharmaceutical firms, NIH program officers, and hospital procurement managers grounded the qualitative foundation. Secondary validation drew from FDA Nanotechnology Task Force guidance documents, EMA nanomedicine reflection papers, ISO 10993 biocompatibility standards, and ClinicalTrials.gov nanocarrier trial registrations. Bottom-up triangulation across contract manufacturing capacity data and top-down reconciliation against NIH funding disbursements ensured cross-verification.
Segment-level value outputs across the projection horizon reflect modeled interactions between nanocarrier, nanosensor, nanoparticle, and nanofiber product categories against drug delivery, diagnostics, imaging, and regenerative medicine applications. Technology dimensions including sol-gel synthesis, electrospinning, laser ablation, and chemical vapor deposition anchored manufacturing scalability assumptions. CAGRs were derived from NIH funding trajectory analysis, FDA approval pathway throughput, and phospholipid supply capacity expansion schedules.
Regulatory reclassification of combination products, phospholipid supply disruption from Swiss or German chemical producers, and quantum dot substitution acceleration are the dominant revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Europe Nanozymes Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market