
 Europe Nanozymes Market | 2026-2036
Europe Nanozymes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nanozymes Market Insights
A shift from single-source to multi-source nanomaterial procurement is decoupling supply risk from production continuity across European nanozyme developers. Sigma-Aldrich Corporation (Merck) leverages its pan-European distribution infrastructure to sustain bulk reagent availability for research-scale buyers. Creative Enzymes anchors its competitive stance through specialized enzymatic modification protocols. Cline Scientific differentiates via precision surface-engineering capabilities for diagnostic-grade nanozymes.
Nanozymes are nanoscale materials exhibiting enzyme-like catalytic activity, typically comprising metal oxides, noble metals, or carbon allotropes with surface-active sites that mimic natural enzyme kinetics; their primary function is to catalyze biochemical reactions under mild conditions without protein denaturation risks. Metallic nanozymes currently dominate commercial supply due to established iron oxide and gold nanoparticle synthesis pathways, while carbon-based nanozymes capture expanding interest from environmental remediation deployers seeking lower toxicity profiles. Biomedical applications generate the deepest margin pools as regulatory scrutiny elevates performance validation requirements for in-vivo diagnostic platforms.
EMA medical device oversight, REACH chemical registration mandates, and the EU Green Deal sustainable chemistry framework collectively shape product development timelines and market access conditions for nanozyme suppliers operating across European member states. ECHA substance evaluation protocols specifically demand extensive toxicological datasets for nanoparticle catalysts, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving MDR classification criteria for nanozyme-integrated diagnostic devices and calibrate R&D portfolios accordingly.
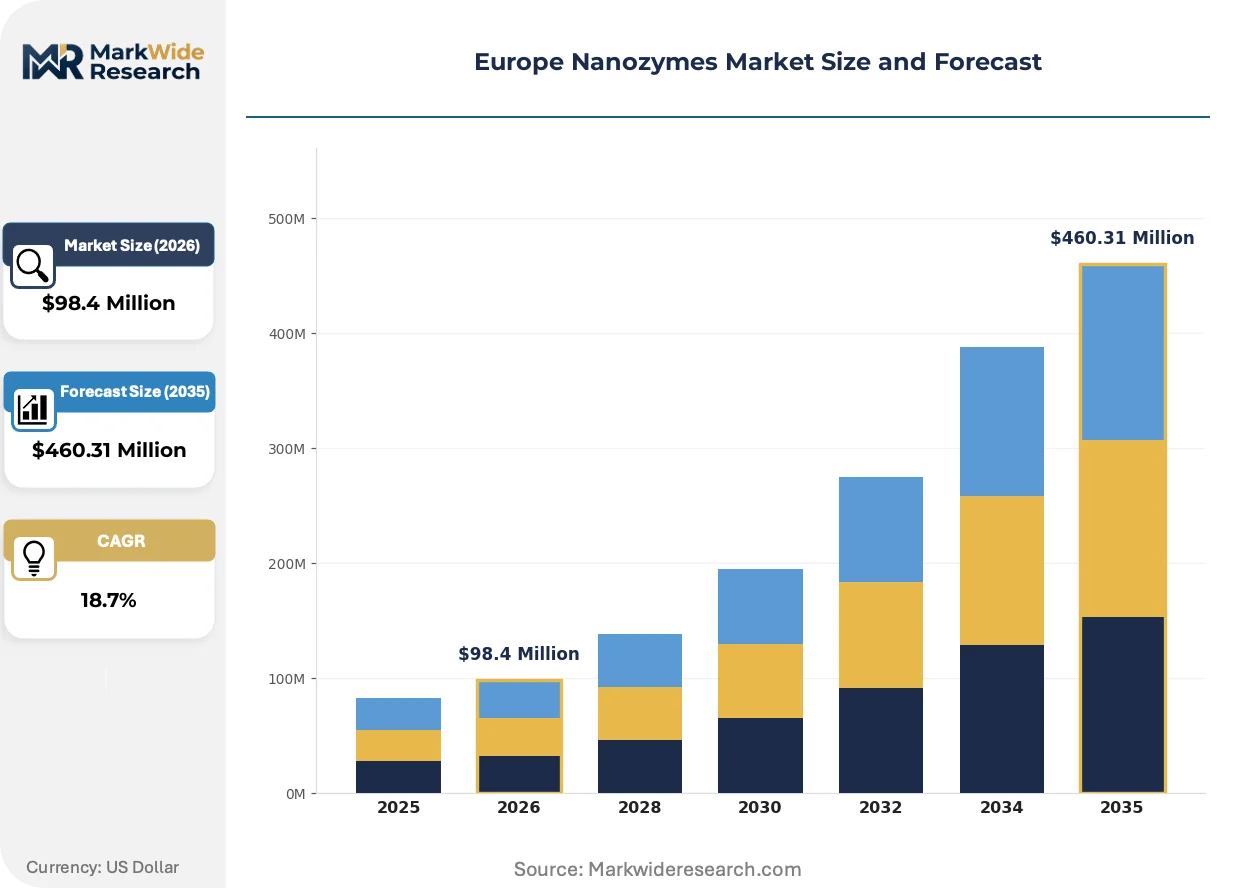
Market Dynamics
REACH chemical registration mandates and EMA medical device oversight are compressing product development timelines while elevating toxicological data requirements for nanoparticle catalysts across European member states.
Growth Catalysts
- EU Green Deal sustainable chemistry framework:The framework mandates substitution of hazardous conventional catalysts with lower-toxicity nanomaterials, accelerating procurement of carbon-based nanozymes for environmental remediation applications.
- Biomedical diagnostics segment:In-vivo diagnostic platforms require validated catalytic materials that resist protein denaturation, pulling iron oxide and gold nanoparticle nanozymes into clinical assay development pipelines.
- German research clusters:Dense concentrations of nanotechnology institutions in Munich, Heidelberg, and Berlin-Dahlem generate specialized workforce pipelines and shared characterization facilities that reduce R&D fixed costs for nanozyme developers.
Market Restraints
- ECHA substance evaluation protocols:Extensive toxicological dataset requirements for nanoparticle catalysts create compliance barriers that extend registration timelines and favor established manufacturers with dedicated regulatory affairs capabilities.
- Precious metal input volatility:Gold and platinum group metal price swings compress margins for noble metal nanozyme producers who lack long-term supply contracts or recycling loops.
- Natural enzyme substitution threat:Advances in directed evolution and immobilized enzyme engineering threaten nanozyme positioning in cost-sensitive industrial catalysis applications where protein stability can be engineered sufficiently.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Czech Republic offer lower-cost cleanroom and chemical synthesis infrastructure for nanozyme production serving EU markets while maintaining REACH compliance.
- MDR classification criteria evolution:Emerging clarity on nanozyme-integrated diagnostic device classifications enables calibrated R&D portfolio allocation toward Class IIb and III device pathways with premium pricing potential.
- Carbon allotrope-noble metal convergence:Hybrid nanozymes combining graphene quantum dots with platinum surface sites address both toxicity concerns and catalytic efficiency demands in point-of-care diagnostic platforms.
Industry Challenges
- Surface characterization skill scarcity:Industrial-scale production of diagnostic-grade nanozymes requires expertise in XPS, DLS, and zeta potential analysis that outstrips current European analytical chemistry training pipeline output.
- ISO 10993 biocompatibility certification timelines:Cytotoxicity and sensitization testing for nanozyme-integrated medical devices extends time-to-revenue by 18-24 months beyond conventional catalyst certification pathways.
- Legacy pharmaceutical quality system integration:Nanozyme suppliers must adapt batch records, change control, and supplier qualification protocols to fit ICH Q7 and EU GMP frameworks designed for small-molecule APIs rather than nanomaterials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nanozymes Market |
| Market Size in 2026 | $98.4 Million |
| Market Size in 2035 | $460.31 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Nanozymes, Carbon-based Nanozymes, Polymer-based Nanozymes, Composite Nanozymes Application: Environmental Remediation, Biomedical Applications, Agricultural Solutions, Industrial Catalysis End User: Healthcare, Agriculture, Environmental Agencies, Research Institutions Technology: Enzymatic Methods, Chemical Synthesis, Biosynthesis, Microfabrication |
| Companies Covered | Sigma-Aldrich Corporation (Merck), Creative Enzymes, Cline Scientific, Tanaka Holdings, nanoComposix, EnzyPep B.V., BBI Solutions, Haydale Graphene Industries, Novozymes A/S (Novonesis Group), Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nanozymes Market Trends and Innovations
Surface engineering protocols and regulatory data requirements are compressing competitive differentiation from synthesis scale toward precision functionalization capabilities and toxicological dossier depth.
Core-shell iron oxide nanozymes with tunable catalytic pockets are modularizing across European diagnostic manufacturers. Roche and Siemens Healthineers development teams in Mannheim and Basel are adopting standardized surface modification kits that compress assay optimization cycles from months to weeks. This modularization enables smaller CROs to enter nanozyme-integrated immunoassay development without captive nanoparticle synthesis infrastructure.
REACH authorization requirements for Substances of Very High Concern are tightening supply chain documentation obligations for nanozyme importers. ECHA's 2023-2025 substance evaluation roadmap specifically targets cobalt and nickel nanoparticle catalysts, forcing reformulation toward iron oxide and carbon-based alternatives in environmental sensing applications. German and Dutch nanozyme distributors are building in-house regulatory dossier capabilities to maintain market access for non-EU sourced materials.
Research-scale buyers are consolidating purchase volumes through pan-European reagent consortia rather than direct manufacturer relationships. The Max Planck Society and European Molecular Biology Laboratory procurement frameworks now specify nanozyme lots with full characterization certificates, displacing catalog-only purchases. France and Switzerland host the most mature consortia structures, with German Max Planck institutes rapidly adopting similar centralized sourcing protocols.
Europe Nanozymes Market Segmentation
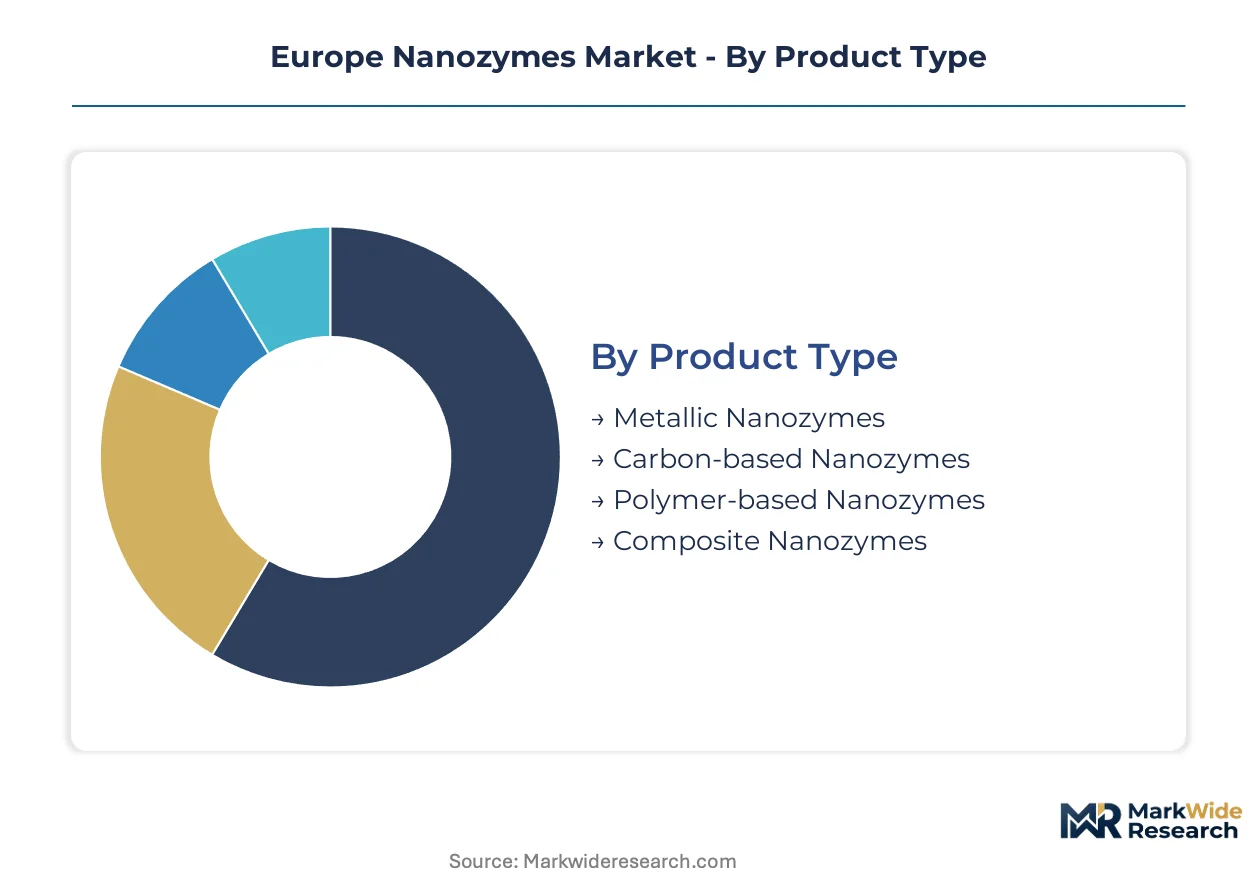
Segmentation in the Europe Nanozymes Market reveals how divergent technical requirements across healthcare, environmental, and industrial buyers reshape procurement patterns. Product specifications vary dramatically between diagnostic-grade surface-engineered particles and bulk environmental remediation catalysts, fragmenting supplier specialization and pricing architecture.
Product Type:
Buyers differentiate primarily by toxicity tolerance thresholds and catalytic precision requirements, with diagnostic applications demanding sub-nanometer surface control that bulk environmental deployers sacrifice for cost efficiency.
- Metallic Nanozymes:Iron oxide and gold nanoparticle formulations dominate current supply through established sol-gel and citrate reduction synthesis pathways. German pharmaceutical manufacturers in Mannheim and Basel drive procurement of diagnostic-grade metallic nanozymes for immunoassay platforms, constrained by ECHA substance evaluation protocols for cobalt and nickel alternatives.
- Carbon-based Nanozymes:Graphene quantum dots and carbon nanotube architectures offer lower toxicity profiles that satisfy EU Green Deal substitution mandates for hazardous conventional catalysts. Dutch environmental remediation contractors are accelerating procurement of carbon allotropes for water treatment applications where REACH compliance documentation outweighs premium pricing.
- Polymer-based Nanozymes:Synthetic polymer scaffolds with embedded catalytic sites serve niche biomedical coating applications requiring bioresorbable characteristics.
- Composite Nanozymes:Hybrid architectures combining metallic cores with carbon or polymer shells address multifunctional demands in point-of-care diagnostic devices.
Volume sits with Metallic Nanozymes; growth tilts toward Carbon-based Nanozymes.
Application:
Margin concentration follows regulatory validation depth, with biomedical platforms commanding premium pricing against commoditized environmental bulk sales.
- Biomedical Applications:In-vivo diagnostic and therapeutic platforms require nanozymes with ISO 10993 biocompatibility certification and batch-to-batch catalytic consistency. Roche and Siemens Healthineers development teams in Germany and Switzerland anchor demand for surface-engineered iron oxide nanozymes in immunoassay workflows.
- Environmental Remediation:Water treatment and soil decontamination deployers prioritize cost-per-gram efficiency over characterization depth, with Polish and Czech Republic infrastructure projects driving regional procurement of unmodified carbon-based catalysts.
- Agricultural Solutions:Pesticide degradation and soil health monitoring applications in France and Spain generate intermittent demand for field-stable nanozyme formulations.
- Industrial Catalysis:Process chemistry applications in specialty chemical manufacturing seek nanozyme alternatives to platinum group metal catalysts facing precious metal price volatility.
Biomedical Applications capture premium pricing; Environmental Remediation scales fastest by volume.
End User:
Procurement sophistication separates institutional buyers with captive regulatory affairs capabilities from fragmented agricultural and environmental agency purchasers.
- Healthcare:Hospital systems and diagnostic manufacturers demand full toxicological dossiers and MDR-compliant device integration pathways. Max Planck Society and European Molecular Biology Laboratory procurement frameworks now mandate characterization certificates that displace catalog-only purchases.
- Research Institutions:Universities and national laboratories drive standardization of surface modification kits that compress assay optimization cycles for smaller CROs.
- Environmental Agencies:National and municipal water authorities in Germany and the Netherlands prioritize REACH-registered materials with established supply chain documentation.
- Agriculture:Farm cooperatives and agritech distributors exhibit price sensitivity that favors unmodified nanozyme formulations over engineered variants.
Healthcare concentrates revenue; Research Institutions expand procurement most quickly.
Technology:
Manufacturing process selection determines regulatory pathway complexity and scale-up capital requirements, with biological routes offering sustainability positioning against chemical precision.
- Chemical Synthesis:Sol-gel, hydrothermal, and co-precipitation methods dominate commercial production of iron oxide and gold nanoparticles through reproducible batch control. Established German and Swiss chemical manufacturers leverage existing GMP infrastructure for diagnostic-grade nanozyme supply.
- Biosynthesis:Microbial and plant-mediated reduction routes produce lower-toxicity carbon-based nanozymes aligned with EU Green Deal sustainable chemistry mandates.
- Enzymatic Methods:Template-directed biomineralization offers sub-nanometer precision for specialized diagnostic applications with limited scale.
- Microfabrication:Lithographic and printing-based patterning serves device-integrated nanozyme arrays in point-of-care platform development.
Chemical Synthesis anchors current volume; Biosynthesis gains share fastest on sustainability positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron oxide nanoparticle feedstock from German chemical manufacturers anchors European nanozyme production capacity. REACH-registered precursor supply chains radiate from the Rhine-Ruhr industrial corridor toward formulation facilities in Switzerland and the Netherlands.
Germany
Diagnostic-grade metallic nanozyme demand concentrates around Mannheim and Basel-adjacent pharmaceutical corridors. EMA medical device oversight and ECHA substance evaluation protocols compress development timelines for iron oxide nanoparticle suppliers. Munich, Heidelberg, and Berlin-Dahlem research clusters generate specialized workforce pipelines and shared characterization facilities that reduce R&D fixed costs for nanozyme developers.
Switzerland
Swissmedic regulatory frameworks and proximity to German pharmaceutical demand position Basel and Zurich as diagnostic nanozyme integration hubs. REACH compliance documentation requirements favor established importers with dedicated regulatory affairs capabilities. Roche and Siemens Healthineers development teams anchor demand for surface-engineered iron oxide nanozymes in immunoassay workflows.
Netherlands
Dutch environmental remediation contractors accelerate procurement of carbon-based nanozymes for water treatment applications. EU Green Deal sustainable chemistry mandates drive substitution of hazardous conventional catalysts with lower-toxicity carbon allotropes. Eindhoven and Rotterdam chemical synthesis infrastructure supports REACH-registered nanomaterial production for EU-wide distribution.
United Kingdom
Post-Brexit regulatory divergence from ECHA protocols creates parallel registration pathways for nanozyme suppliers serving UK diagnostic manufacturers. MHRA medical device oversight maintains alignment with MDR classification criteria for nanozyme-integrated platforms. London-Oxford-Cambridge research consortia standardize surface modification kits that compress assay optimization cycles for smaller CROs.
Poland
Lower-cost cleanroom and chemical synthesis infrastructure in Warsaw and Kraków attracts nanozyme production serving EU markets while maintaining REACH compliance. Environmental agency procurement for water treatment applications prioritizes cost-per-gram efficiency over characterization depth. Polish infrastructure projects drive regional demand for unmodified carbon-based catalysts in soil decontamination deploys.
Europe Nanozymes Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek regulatory dossier capabilities and manufacturing scale. The vendor base fragments across three tiers: pan-European distributors with REACH-registered bulk supply, specialized surface-engineering boutiques, and research-scale reagent providers. Diagnostic-grade manufacturers and environmental remediation suppliers represent distinct strategic archetypes with divergent margin structures. Portfolio diversification toward carbon-based alternatives and geographic expansion into Eastern European manufacturing zones constitute the primary competitive vectors.
Among pan-European distributors, Sigma-Aldrich Corporation (Merck) exemplifies the integrated supply archetype through its REACH-registered precursor infrastructure. Creative Enzymes and Cline Scientific occupy positions within the specialized engineering tier, representing enzymatic modification and precision surface-engineering capabilities respectively. These three entities anchor the competitive spectrum from bulk reagent availability to diagnostic-grade functionalization.
| Leading Market Players |
|---|
| Sigma-Aldrich Corporation (Merck) |
| Creative Enzymes |
| Cline Scientific |
| Tanaka Holdings |
| nanoComposix |
| EnzyPep B.V. |
| BBI Solutions |
| Haydale Graphene Industries |
| Novozymes A/S (Novonesis Group) |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap German chemical manufacturers anchor precursor supply for European nanozyme producers, translating captive iron oxide nanoparticle production into pricing discipline that resists commoditization pressure from Asian imports. Their integration from REACH-registered feedstock through diagnostic-grade surface engineering creates margin buffers that insulate against precious metal volatility while elevating barriers for unbundled reagent competitors.
Pricing Analysis
Warranty-bundled characterization certificates separate diagnostic-grade nanozyme pricing from catalog-only research reagents. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification depth and batch-to-batch catalytic consistency guarantees. Pricing pressure stems from ECHA substance evaluation protocols extending registration timelines and favoring established dossier holders. Environmental remediation buyers exhibit highest price sensitivity, sacrificing surface characterization depth for cost-per-gram efficiency, while healthcare diagnostic manufacturers absorb premiums for MDR-compliant device integration pathways.
Supply Chain Analysis
Dual-sourcing mandates from Max Planck Society and European Molecular Biology Laboratory procurement frameworks force nanozyme buyers to qualify multiple REACH-registered suppliers per material category. Supply concentrates in Germany, Switzerland, and the Netherlands for diagnostic-grade metallic nanozymes, while Poland and Czech Republic host emerging carbon-based production capacity. Raw material dependencies rest on iron oxide and gold nanoparticle precursors from Rhine-Ruhr chemical corridors, platinum group metals subject to price volatility, and graphene quantum dot feedstocks. Single-source vulnerability around ECHA-authorized cobalt and nickel nanoparticle alternatives forces reformulation toward iron oxide and carbon-based architectures. Distribution runs through pan-European reagent consortia consolidating research-scale volumes alongside direct manufacturer relationships for diagnostic OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Nanozymes Market sits in a technology-transition phase where carbon allotrope-noble metal hybrid architectures displace single-material metallic nanozymes in point-of-care diagnostic platforms. REACH compliance documentation requirements and ECHA substance evaluation protocols compress competitive differentiation toward precision functionalization capabilities rather than synthesis scale.
For Market Incumbents: Hedge against natural enzyme substitution threats by deepening surface engineering IP portfolios and securing long-term platinum group metal supply contracts or recycling loops. Incumbent manufacturers must accelerate ISO 10993 biocompatibility certification timelines to maintain premium positioning against emerging carbon-based competitors. Capacity addition in Poland and Czech Republic cleanroom infrastructure addresses cost compression in environmental remediation tiers while preserving REACH compliance. For New Entrants and Emerging Players: Launch via research-scale reagent consortia standardization programs to bypass captive synthesis infrastructure requirements. The most penetrable white space sits in carbon-based nanozymes for Dutch and German environmental remediation contractors seeking EU Green Deal-compliant catalyst substitution. Agricultural solutions in France and Spain offer secondary entry points with lower regulatory validation depth than biomedical applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized surface-engineering boutiques in Switzerland and Germany with existing ECHA dossier capabilities and diagnostic OEM relationships. Long-term viability hinges on regulatory affairs depth rather than synthesis scale across the analysis window. Watch for MDR classification criteria evolution clarity as the inflection signal enabling calibrated R&D portfolio allocation toward Class IIb and III device pathways with premium pricing potential.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Capability Buildout | ECHA substance evaluation protocols favor established manufacturers with dedicated regulatory affairs teams. |
| Carbon Allotrope-Noble Metal Hybrid Development | Graphene quantum dot-platinum architectures address toxicity concerns and catalytic efficiency in point-of-care platforms. |
| Eastern European Manufacturing Expansion | Poland and Czech Republic offer lower-cost cleanroom infrastructure while maintaining REACH compliance for EU markets. |
| ISO 10993 Biocompatibility Certification Acceleration | Diagnostic-grade nanozyme suppliers compress 18-24 month cytotoxicity testing timelines to accelerate time-to-revenue. |
| Pan-European Reagent Consortium Integration | Max Planck Society and EMBL procurement frameworks displace catalog-only purchases with full characterization certificate mandates. |
Research Methodology
Independent corroboration across nanozyme manufacturer technical directors, diagnostic OEM procurement leads, and ECHA regulatory affairs specialists underwrites the qualitative findings in this study. Primary interviews with plant managers at German and Swiss chemical synthesis facilities, biomedical engineers at Roche and Siemens Healthineers development teams, and environmental agency procurement officers in the Netherlands and Germany combined with secondary validation from REACH registration databases, EMA medical device submission filings, and EU Green Deal policy documentation. Bottom-up segmentation modeling triangulates against top-down macroeconomic indicators across the European nanomaterials sector.
Rate-of-change decomposition separates volume expansion from value capture across product type, application, end user, and technology dimensions throughout the forecast period. Segmentation modeling incorporates metallic versus carbon-based nanozyme substitution dynamics, biomedical versus environmental application margin structures, and chemical synthesis versus biosynthesis route adoption patterns. CAGRs derive from fitted growth curves calibrated to historical REACH registration timelines and diagnostic device approval pathway data. Industry-specific forecast inputs include ECHA substance evaluation roadmap priorities and MDR classification criteria evolution for nanozyme-integrated platforms.
The model assumes a particular technology adoption path; alternative pathways for carbon-based nanozymes displacing metallic architectures in environmental remediation would alter the outlook. Forecasts reflect assumptions around REACH compliance documentation requirements and EMA medical device oversight timelines. Deviation in ECHA substance evaluation protocol stringency or MDR classification criteria clarity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanobiotechnology
Bio-Inspired and Nano-Engineered Surfaces Market
Nanobiotechnology
Nanobody Market
Nanobiotechnology
Designer DNA Nanocages Market
Nanobiotechnology
Nanozymes Market
Nanobiotechnology
Europe Molecular Biosensors Market
Nanobiotechnology
Nanopore Technologies Market
Nanobiotechnology
Nano Biosensors Market
Nanobiotechnology
Nanobiotechnology Market
Nanobiotechnology
Nanotechnology Drug Delivery Market
Nanobiotechnology
Nanopharmaceuticals Market
Nanobiotechnology
Nanopore Sequencing Market
Nanobiotechnology
Boron Nitride Nanotubes in Nanomedicine Market