
 Myanmar ICT Market | 2026-2036
Myanmar ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar ICT Market Outlook
Myanmar's Type Approval certification for telecom equipment is reorganizing vendor eligibility, forcing international suppliers to adapt testing documentation before market entry. Huawei Technologies Co., Ltd. leverages its existing regional certification infrastructure to sustain equipment shipments despite licensing delays. Ooredoo Myanmar Limited anchors mobile broadband expansion in secondary cities where spectrum allocation permits 4G rollout. Frontiir Co., Ltd. competes through localized software development that navigates content restriction protocols.
Information and communications technology in Myanmar encompasses computing hardware, network infrastructure, enterprise software, and digital services delivered across fixed and wireless channels. Fiber-optic backhaul capacity currently limits last-mile throughput to approximately 100 Mbps in urban nodes, constraining cloud application performance for enterprise clients. Hardware and services segments attract capital as government tenders prioritize domestic data sovereignty and on-premise server deployment for sensitive ministries. Cloud-based solutions gain traction among SMEs seeking subscription models that bypass large capital outlays for server procurement.
The Posts and Telecommunications Department enforces licensing under the Telecommunications Law, while the Central Committee for Ensuring Cyber Security monitors content filtering mandates that affect platform architecture. BIS-aligned technical standards for imported networking equipment create compliance timelines that delay product launches by six to twelve months. Stakeholders must track regulatory shifts around data localization requirements and foreign ownership caps that could alter partnership structures for international technology vendors.
Market Dynamics
Myanmar's ICT sector operates under the dual pressure of central bank digitization mandates and restrictive telecom licensing frameworks that constrain vendor participation. The Ministry of Transport and Communications enforces equipment certification timelines that compress deployment schedules while expanding domestic data sovereignty requirements.
Growth Catalysts
- Central Bank Directives:Myanmar's banking regulator mandates core banking system upgrades, forcing lenders to procure enterprise software and secure data center capacity. This creates immediate demand for on-premise server infrastructure.
- Yangon Technology Corridor:Fiber deployment and data center construction in this urban cluster concentrates capital flows and technical talent, accelerating last-mile connectivity upgrades for enterprise clients.
- 4G Spectrum Allocation:Secondary cities receive mobile broadband licenses under revised telecom rules, permitting operators to expand coverage beyond the capital region.
Market Restraints
- BIS-Aligned Testing Delays:Imported networking equipment faces six-to-twelve-month compliance timelines, stretching product launch schedules and freezing vendor revenue recognition.
- Fiber-Optic Backhaul Bottlenecks:Urban throughput limits near 100 Mbps constrain cloud application performance, forcing enterprises to maintain costly on-premise alternatives.
- Foreign Ownership Caps:Partnership structures for international technology vendors face structural uncertainty as regulators review equity restrictions.
Strategic Opportunities
- SME Subscription Models:Cloud-based solutions bypass capital outlays for server procurement, opening addressable demand among budget-constrained smaller enterprises.
- Localized Software Development:Content restriction protocols create protected space for domestic developers to build compliant applications without foreign competition.
- Secondary City Broadband:Spectrum permits in non-Yangon municipalities allow first-mover positioning where infrastructure investment lags metropolitan levels.
Industry Challenges
- Type Approval Documentation:International suppliers must reorganize testing protocols to meet reorganized vendor eligibility criteria, consuming technical resources without revenue offset.
- Cyber Security Committee Mandates:Content filtering requirements force platform architecture redesigns that extend development cycles and inflate engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar ICT Market |
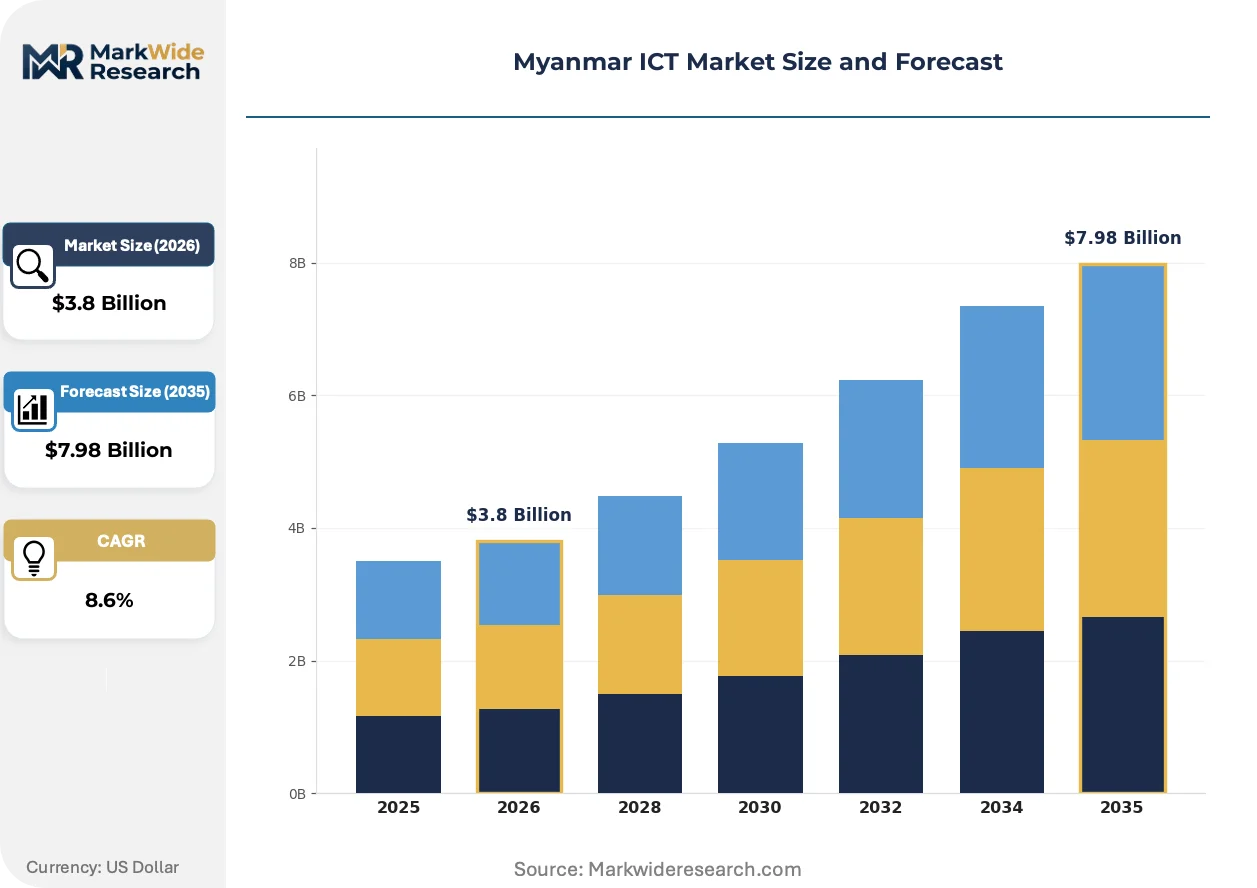
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Accessories End User: SMEs, Enterprises, Government, Individuals Deployment: On-premise, Cloud-based, Hybrid, Mobile Solution: ERP, CRM, Cybersecurity, Communication Tools |
| Companies Covered | Myanma Posts and Telecommunications, Ooredoo Myanmar Limited, Telenor Myanmar Limited, Huawei Technologies Co., Ltd., Cisco Systems, Inc., Microsoft Corporation, IBM Corporation, Oracle Corporation, Frontiir Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar ICT Market Strategic Shifts
Myanmar's ICT landscape is compressing around three vectors: cloud infrastructure substitution of legacy hardware, regulatory enforcement of data localization, and procurement model fragmentation between subscription services and sovereign server deployment. These forces interact to reshape competitive positioning.
Cloud-native enterprise software is displacing traditional on-premise server installations across Myanmar's banking and government sectors. Financial institutions under central bank pressure adopt subscription-based core banking platforms to accelerate compliance timelines. This shift compresses capital equipment procurement cycles while expanding recurring revenue pools for software vendors.
Myanmar's Posts and Telecommunications Department enforces data localization requirements through the Telecommunications Law, compelling foreign platform operators to route domestic traffic through in-country infrastructure. The policy redirects cloud service architecture toward hybrid deployments with local edge nodes. Enterprise clients in sensitive ministries respond by prioritizing domestic data sovereignty certifications in vendor selection.
Procurement fragmentation splits Myanmar's enterprise market between capital-intensive hardware tenders and operational-expense-driven cloud subscriptions. Government agencies favor on-premise server deployment for sovereignty compliance, while SMEs bypass procurement committees entirely through direct software-as-a-service adoption. This bifurcation concentrates vendor specialization along customer type rather than industry vertical.
Myanmar ICT Market Segmentation
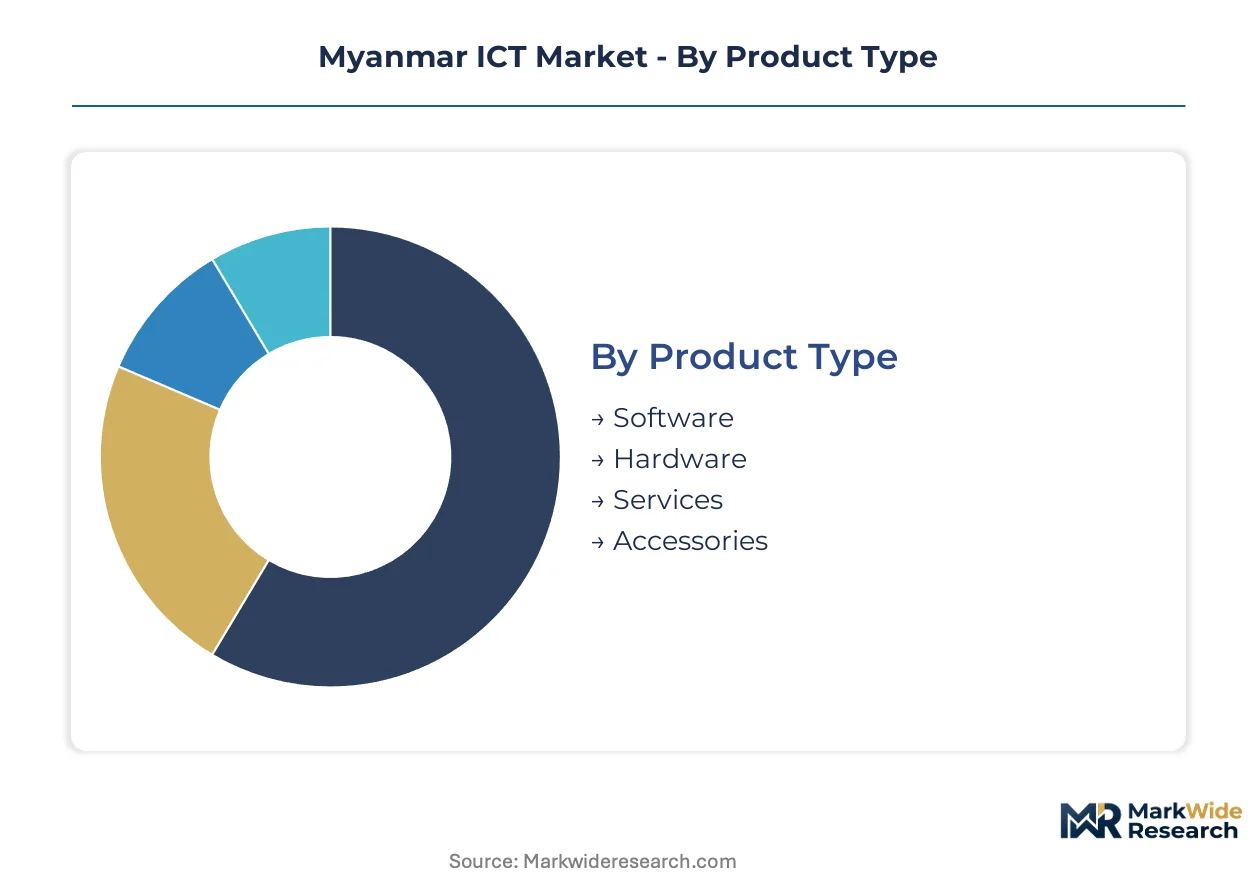
Myanmar's ICT market fragments across four critical dimensions that determine vendor go-to-market strategy and margin capture. Product mix, customer type, deployment architecture, and solution category each concentrate revenue in distinct pockets shaped by central bank digitization mandates and Posts and Telecommunications Department licensing frameworks.
Product Type:
Margin pools concentrate in software and services where recurring revenue models offset hardware commoditization pressures from BIS-aligned certification delays.
- Software:Enterprise applications including core banking platforms and government ERP systems dominate procurement under central bank directives. Financial institutions in Yangon's technology corridor drive demand for subscription-based deployment that accelerates compliance timelines without capital-intensive server procurement.
- Hardware:Servers, networking equipment, and computing devices face extended six-to-twelve-month Type Approval certification timelines. Domestic data sovereignty requirements favor on-premise infrastructure for sensitive ministries, concentrating procurement around sovereign-certified server deployments.
- Services:System integration and managed services capture value from fragmented vendor ecosystems where international suppliers require local partnership structures.
- Accessories:Peripherals and consumables distribute through retail channels serving individual and SME segments with lower regulatory friction.
Hardware holds installed capacity. Software is rotating up the share rankings.
End User:
Customer concentration tilts toward banking and government verticals where regulatory mandates compress procurement cycles and inflate contract values.
- Enterprises:Large financial institutions and state-owned enterprises command the dominant share of ICT spending. Core banking system upgrades mandated by the central bank generate immediate demand for enterprise software and secure data center capacity.
- Government:Ministries prioritize on-premise server deployment for data sovereignty compliance, creating protected demand for hardware vendors with domestic certification.
- SMEs:Budget-constrained smaller enterprises bypass procurement committees through direct cloud subscription adoption, opening addressable demand for SaaS providers.
- Individuals:Mobile broadband expansion in secondary cities drives consumer demand for devices and connectivity services.
Enterprises anchor current spending. SMEs are climbing the fastest as subscription models lower entry barriers.
Deployment:
Architecture preferences split between sovereignty-driven on-premise installations and capital-efficiency-driven cloud migration.
- On-premise:Physical server infrastructure maintained within organizational premises satisfies data localization requirements enforced through the Telecommunications Law. Government agencies and sensitive ministries mandate this architecture for domestic traffic routing compliance.
- Cloud-based:Subscription delivery models gain traction among SMEs seeking to bypass large capital outlays. Financial institutions adopt cloud-native core banking platforms to accelerate central bank compliance timelines.
- Hybrid:Mixed deployments with local edge nodes redirect foreign platform architecture toward compliant domestic infrastructure.
- Mobile:Wireless-first deployment serves individual users and field-based government services where fixed infrastructure remains limited.
On-premise retains institutional lock-in. Cloud-based deployment is expanding most quickly among commercial adopters.
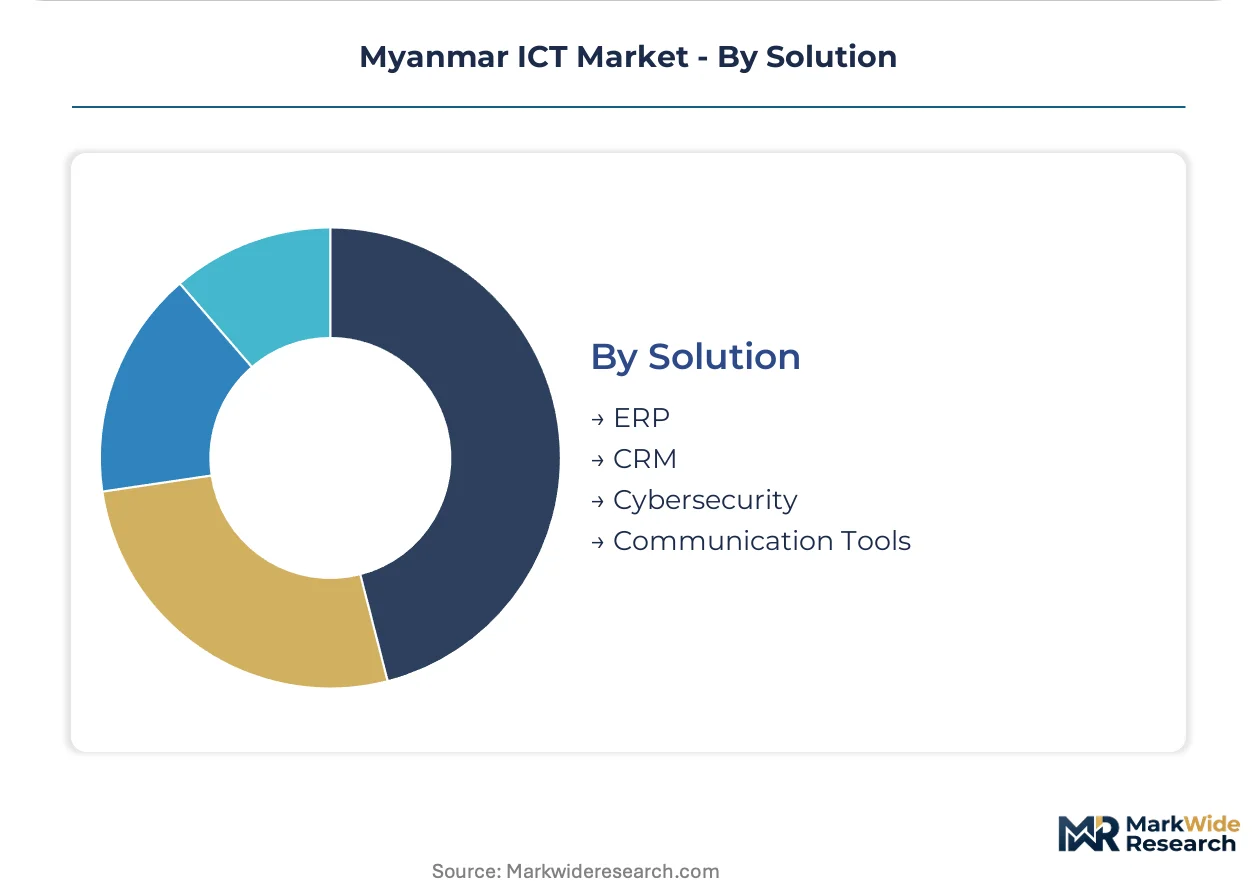
Solution:
Functional category prioritization reflects regulatory pressure points and operational vulnerability assessments across Myanmar's digitizing economy.
- ERP:Enterprise resource planning systems integrate financial, procurement, and human capital functions. Banking sector digitization mandates concentrate demand in Yangon's technology corridor where data center construction accelerates implementation.
- Cybersecurity:Content filtering mandates from the Central Committee for Ensuring Cyber Security force platform architecture redesigns. Compliance requirements inflate engineering costs while creating protected space for localized development.
- CRM:Customer relationship management tools support banking and telecom customer acquisition in competitive secondary city markets.
- Communication Tools:Unified messaging and collaboration platforms navigate content restriction protocols through localized hosting arrangements.
ERP maintains legacy dominance. Cybersecurity is gaining share fastest as regulatory enforcement tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Myanmar's ICT demand concentrates in financial institutions under central bank digitization mandates and government ministries enforcing data sovereignty compliance. Enterprise software procurement dominates Yangon's technology corridor where data center construction accelerates. Geographic expansion into secondary cities follows revised telecom licensing frameworks.
Yangon Region
Myanmar's commercial capital anchors enterprise ICT spending through banking sector core system upgrades mandated by the Central Bank of Myanmar. The Posts and Telecommunications Department enforces equipment certification timelines that compress deployment schedules for fiber-optic infrastructure. Yangon's technology corridor concentrates data center construction and enterprise software implementation, with last-mile connectivity upgrades accelerating cloud adoption among financial institutions.
Mandalay Region
Secondary city mobile broadband expansion drives ICT infrastructure investment following 4G spectrum allocation outside the capital region. The Ministry of Transport and Communications administers telecom licensing rules that reshape operator competition in central Myanmar. Mandalay's emerging commercial clusters attract fiber deployment investment as operators seek first-mover positioning where metropolitan infrastructure lags.
Naypyidaw Union Territory
Government ministry procurement dominates ICT demand through on-premise server deployment for sensitive data sovereignty compliance. The Central Committee for Ensuring Cyber Security monitors content filtering mandates affecting platform architecture across administrative functions. Naypyidaw's concentration of state functions creates protected demand for domestic-certified hardware vendors serving sovereign infrastructure requirements.
Bago Region
Industrial zone connectivity requirements spur enterprise network infrastructure investment alongside manufacturing digitization initiatives. The Posts and Telecommunications Department enforces BIS-aligned technical standards for imported networking equipment that delay product launches. Bago's logistics corridors attract fiber-backhaul investment linking commercial operations to Yangon's technology infrastructure.
Myanmar ICT Market Competitive Environment
Player mix skews toward international equipment vendors navigating Type Approval certification delays alongside domestic operators leveraging spectrum allocation advantages. Market structure concentrates around three strategic archetypes: global technology conglomerates with regional certification infrastructure, licensed telecom operators expanding mobile broadband coverage, and localized software developers building compliant applications. Competitive positioning hardens around strategic partnerships with government agencies and portfolio diversification into hybrid cloud deployments.
Within the international equipment tier, Huawei Technologies Co., Ltd. and Cisco Systems, Inc. occupy positions shaped by certification infrastructure depth and compliance timeline management. Ooredoo Myanmar Limited represents the licensed operator archetype navigating spectrum-dependent expansion. Frontiir Co., Ltd. exemplifies the localized development model building applications within content restriction protocols. These anchors illustrate how vendor positioning splits between certification-scale advantages and regulatory-compliance specialization.
| Leading Market Players |
|---|
| Myanma Posts and Telecommunications |
| Ooredoo Myanmar Limited |
| Telenor Myanmar Limited |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Frontiir Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Six-to-twelve-month Type Approval certification timelines concentrate procurement risk among vendors with established testing infrastructure, compressing margin capture for late entrants while amplifying pricing power for certified incumbents serving Myanmar's government and banking verticals.
Pricing Analysis
Cost-plus contracts with BIS-aligned indexation dominate enterprise hardware procurement, with final pricing tethered to certification completion milestones and domestic assembly requirements. Price differentiation separates sovereign-certified server deployments for Naypyidaw ministries from standard-tier equipment for commercial buyers. Pricing pressure intensifies in the hardware segment as extended compliance timelines freeze revenue recognition and inflate carrying costs. SMEs exhibit highest price sensitivity, bypassing procurement committees through direct SaaS adoption that eliminates capital outlay entirely.
Supply Chain Analysis
Strategic stockpiling of networking equipment prevails over just-in-time approaches as vendors buffer against Type Approval delays that stretch deployment schedules. Supply concentration rests on China, South Korea, and Singapore for fiber-optic components, enterprise servers, and certification testing services. Critical dependencies include semiconductor chips, optical transceivers, and lithium-ion backup power systems. Single-source vulnerability concentrates in BIS-aligned testing facilities that gate all imported networking equipment. Distribution runs through Yangon-based system integrators with established Posts and Telecommunications Department relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's ICT sector is navigating a cyclical recovery anchored to central bank digitization mandates that force lender core system upgrades regardless of macroeconomic headwinds.
For Market Incumbents: Shield installed base relationships through accelerated certification investment that compresses competitor entry timelines. Deepen vertical integration into domestic data center construction to capture Yangon technology corridor buildout. Prioritize hybrid cloud architecture development as foreign platform operators face localization mandates from the Posts and Telecommunications Department. For New Entrants and Emerging Players: Lead with SME subscription models that bypass capital-intensive procurement committees and exploit pricing sensitivity in the underserved commercial tier. Target Mandalay Region mobile broadband expansion where spectrum allocation permits first-mover positioning. Anchor go-to-market strategy through localized software development partnerships that navigate Central Committee for Ensuring Cyber Security content protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software deployment as recurring revenue models displace hardware-heavy infrastructure plays. Long-term viability favors vendors with hybrid architecture capabilities spanning sovereign on-premise and edge-node delivery. Acquisition targets should demonstrate established Posts and Telecommunications Department certification relationships. Monitor Type Approval timeline compression as the signal indicating regulatory environment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Type Approval Certification Acceleration | Compresses six-to-twelve-month compliance timelines that currently freeze vendor revenue recognition. |
| Hybrid Cloud Platform Integration | Aligns foreign platform architecture with Telecommunications Law data localization mandates. |
| Secondary City Spectrum Deployment | Captures Mandalay and Bago Region mobile broadband expansion under revised licensing frameworks. |
| Domestic Data Center Partnership | Satisfies government ministry sovereignty requirements through sovereign-certified infrastructure. |
| Localized Software Development | Builds compliant applications within Central Committee for Ensuring Cyber Security content protocols. |
Study Parameters
Initial hypotheses were tested against primary input from telecom licensing officers, enterprise IT procurement heads, banking technology executives, and data center construction managers and refined through secondary validation. Sources included Posts and Telecommunications Department regulatory filings, Central Bank of Myanmar digitization directives, operator spectrum allocation records, and equipment import customs data. Bottom-up demand modeling triangulated against top-down market sizing across deployment architecture and end-user verticals.
Variance decomposition isolated segment-level growth contributions across the projection horizon. The analytical framework modeled product type, end-user vertical, deployment architecture, and solution category dimensions with regulatory compliance tier as an industry-specific overlay. CAGRs were derived from trend extrapolation of central bank mandate implementation timelines and telecom licensing issuance patterns. Forecast inputs incorporated fiber-backhaul capacity expansion schedules and cloud subscription adoption curves among Yangon-based financial institutions.
The analysis sits within stated boundaries; outcomes outside sustained central bank digitization enforcement or Posts and Telecommunications Department licensing continuity would require recalibration. Forecasts reflect assumptions regarding Type Approval timeline stability and foreign ownership cap maintenance. Revision becomes warranted when regulatory enforcement intensity crosses thresholds that alter vendor participation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
5G RAN Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Ireland Telecom Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Smart SIM Market
Telecommunications
Global International Calling Apps Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Tetra Terminals Market