
 Government Cloud Computing Market | 2026-2036
Government Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Government Cloud Computing Market Outlook
Multi-source procurement strategies are rebalancing how agencies acquire cloud capacity, shifting away from single-vendor enterprise agreements toward diversified portfolio approaches. Amazon Web Services leverages its extensive FedRAMP authorization portfolio to anchor federal civilian workloads. Microsoft Corporation competes through Azure Government enclaves purpose-built for classified environments. Oracle Corporation specializes in database-centric cloud migrations that sustain legacy application continuity for defense clients.
Government cloud computing denotes the delivery of on-demand computing resources—spanning servers, storage, databases, networking, software, and analytics—over the internet to public-sector organizations operating under stringent data sovereignty and security mandates. Infrastructure as a Service dominates current procurement volumes due to its utility in modernizing aging data centers without capital-intensive hardware replacement. Hybrid Cloud deployments are expanding fastest among defense end users who require air-gapped private infrastructure alongside burst capacity into accredited public enclaves. Software as a Service captures concentrated margin pools in compliance management applications where pre-certified configurations reduce agency audit burdens.
FedRAMP, the European Union's CSRD-adjacent digital sovereignty frameworks, and NATO's cloud security criteria collectively shape vendor eligibility and data residency requirements across member governments. The EU AI Act introduces additional algorithmic transparency obligations for cloud-hosted artificial intelligence services procured by public bodies. Stakeholders must monitor evolving cross-border data flow restrictions and alignment between national security classifications and commercial cloud accreditation levels.
Market Dynamics
FedRAMP authorization timelines and NATO cloud security criteria are compressing vendor qualification windows while fragmenting procurement across sovereign-accredited providers.
Growth Catalysts
- Defense Modernization Mandates:NATO member states are accelerating classified workload migrations to hybrid cloud architectures that satisfy air-gapped security requirements.
- CSRD-Adjacent Sovereignty Frameworks:European Union public bodies now require data residency guarantees that favor EU-based cloud regions over non-European alternatives.
- AI Service Procurement:Government agencies are expanding cloud-hosted machine learning deployments for fraud detection and citizen service automation.
Market Restraints
- Certification Backlogs:FedRAMP authorization queues now stretch eighteen to twenty-four months for moderate-impact systems.
- Specialized Talent Scarcity:Cleared cloud architects with security clearance eligibility concentrate in Washington DC and London metropolitan corridors.
- Legacy Integration Friction:COBOL-dependent defense payroll systems resist containerization without complete application rewrites.
Strategic Opportunities
- Sub-National Government Tiers:State and municipal agencies in Germany and Australia remain underpenetrated relative to federal counterparts.
- Zero-Trust Architecture Convergence:Cloud-native security meshes are integrating with identity verification platforms for continuous authentication.
- Japan's Government Cloud Standard:METI guidelines for public-sector SaaS procurement create preferential pathways for accredited foreign providers.
Industry Challenges
- Cross-Domain Solution Engineering:Building secure data diodes between classified and unclassified cloud enclaves requires rare specialized engineering expertise.
- Supply Chain Attestation:Hardware provenance verification for server components now extends to third-country semiconductor fabrication facilities.
- Interoperability Certification Delays:NATO's cloud security criteria lack harmonized implementation timelines across member national procurement offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Government Cloud Computing Market |
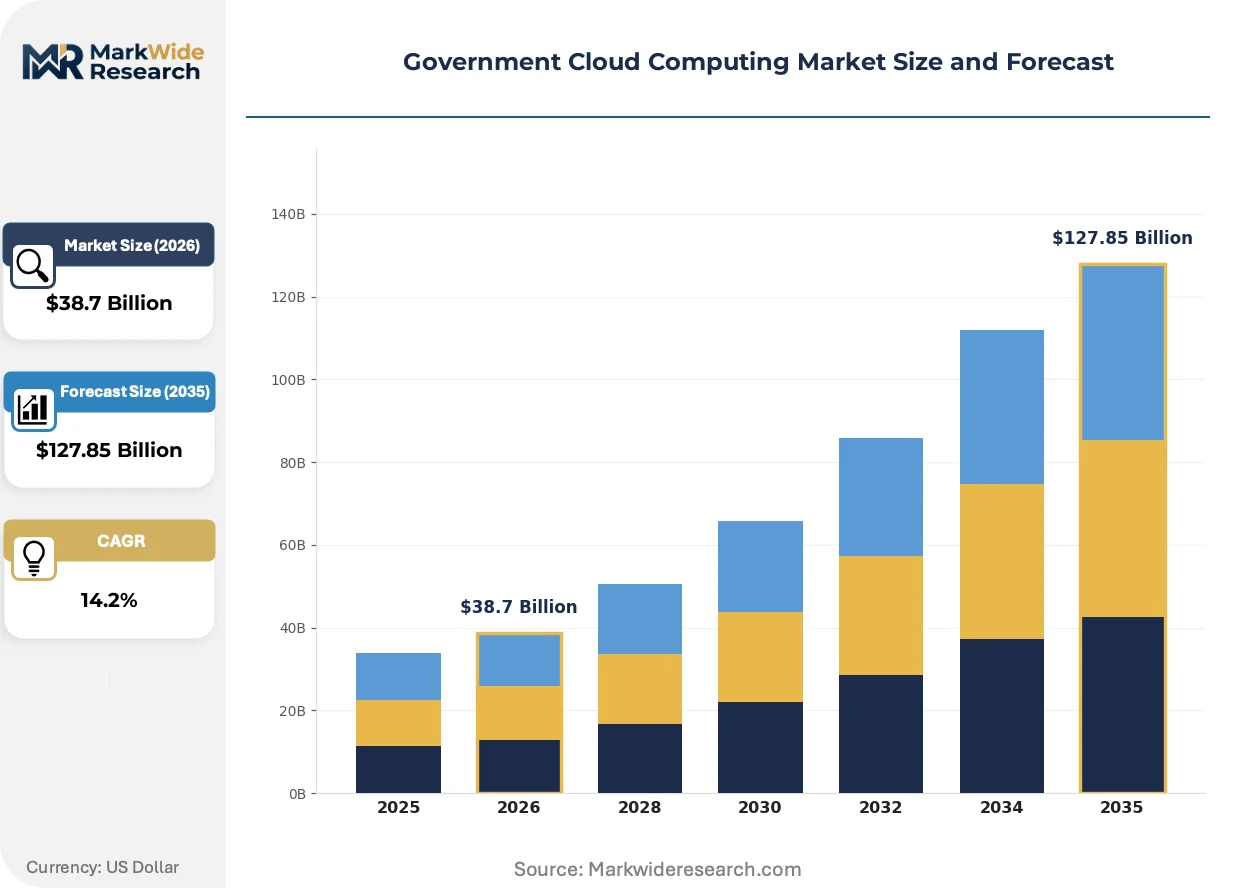
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: Civil Services, Defense, Law Enforcement, Public Health Application: Data Storage, Compliance Management, Resource Allocation, Identity Management |
| Companies Covered | IBM Corporation, VMware, Inc., Amazon Web Services, Inc., DigitalOcean, LLC, Salesforce, Microsoft Corporation, Oracle Corporation, General Dynamics Information Technology, Alphabet Inc. (Google LLC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Government Cloud Computing Market Strategic Shifts
Container orchestration and confidential computing are redefining how agencies isolate sensitive workloads, while procurement officers experiment with consumption-based pricing models that displace traditional enterprise license agreements.
Confidential computing enclaves are integrating hardware-based memory encryption to protect data during active processing. Defense agencies in Five Eyes countries are piloting these capabilities for signals intelligence analytics. This architecture is integrating trusted execution environments that previously required dedicated on-premises hardware.
The EU AI Act mandates algorithmic transparency documentation for cloud-hosted artificial intelligence procured by public bodies. Vendors must now submit conformity assessments covering training data provenance and model decision logic. French and German procurement offices are rejecting bids lacking pre-certified AI governance attestations.
Agency buyers are consolidating vendor relationships through multi-cloud brokerage platforms that abstract underlying infrastructure differences. Federal civilian departments in the United States are replacing direct negotiations with Amazon Web Services, Microsoft Azure, and Oracle Cloud with intermediary-managed service contracts. This pattern concentrates buying power while fragmenting operational accountability across provider ecosystems.
Government Cloud Computing Market Segmentation
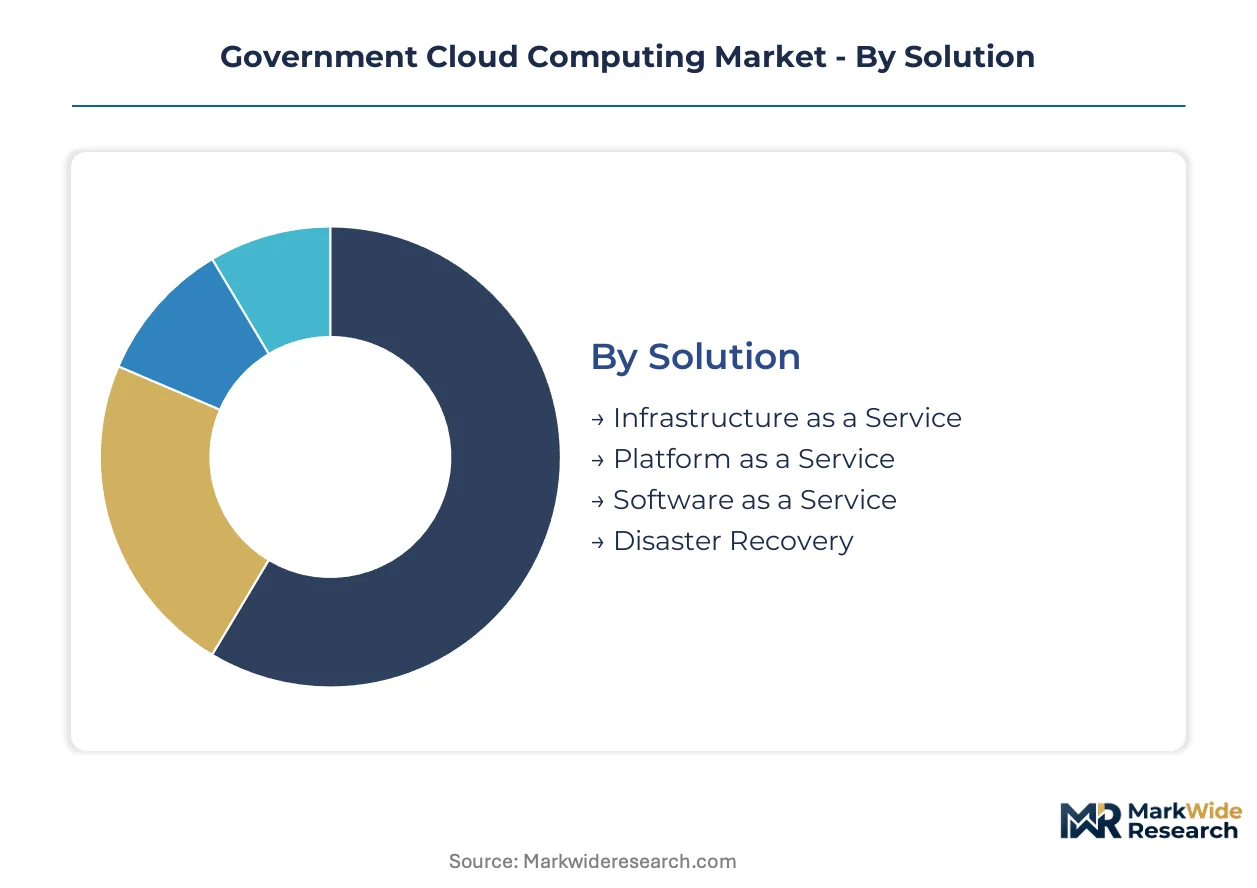
Segmentation in government cloud computing reveals how procurement patterns diverge across security classifications, operational mandates, and legacy system constraints. Each dimension exposes distinct vendor qualification requirements and budget allocation priorities that reshape competitive positioning.
Solution:
Agencies replace capital-intensive data center builds with consumption-based alternatives that accelerate modernization without congressional appropriations cycles.
- Infrastructure as a Service:Virtualized compute, storage, and networking resources delivered through FedRAMP-accredited environments. Federal civilian agencies in the United States concentrate demand here as they retire aging mainframe facilities without hardware procurement delays.
- Platform as a Service:Managed middleware and development environments that abstract infrastructure management from application teams. Defense contractors in the United Kingdom favor PaaS for rapid deployment of mission-critical systems requiring NATO-aligned security baselines.
- Software as a Service:Pre-configured applications with embedded compliance certifications that reduce agency audit preparation. Pre-certified HR and financial management suites dominate procurement volumes.
- Disaster Recovery:Geographically distributed replication services ensuring continuity for citizen-facing systems. State-level implementations in Germany drive regional failover requirements.
Volume placements concentrate in Infrastructure as a Service; the faster expansion belongs to Disaster Recovery.
Deployment:
Security clearance levels and data classification regimes dictate infrastructure topology choices across agency tiers.
- Public Cloud:Shared infrastructure accredited for unclassified workloads with standardized security controls. Municipal governments in Australia leverage public enclaves for cost-sensitive citizen service portals.
- Private Cloud:Dedicated single-tenant environments satisfying stringent data residency mandates. French ministries deploy private clouds to meet CNIL sovereignty requirements for sensitive citizen records.
- Hybrid Cloud:Integrated architectures combining air-gapped private infrastructure with burst capacity into accredited public zones. NATO defense agencies require hybrid configurations for classified analytics with unclassified data fusion.
- Community Cloud:Shared infrastructure restricted to specific government verticals with common compliance needs. Inter-agency law enforcement networks in Canada utilize community deployments for cross-jurisdictional information sharing.
Procurement volumes favor Hybrid Cloud configurations; Community Cloud deployments are climbing the fastest as cross-agency collaboration mandates intensify.
End User:
Budget authority and security clearance infrastructure determine cloud adoption velocity across government functions.
- Civil Services:Administrative agencies managing citizen benefits, regulatory oversight, and operational support. The United States Department of Agriculture exemplifies large-scale civil migration to FedRAMP-authorized platforms.
- Defense:Military organizations requiring air-gapped or classified processing environments. Five Eyes intelligence-sharing countries concentrate specialized vendor ecosystems around defense-grade accreditation.
- Law Enforcement:Police and investigative agencies with chain-of-custody requirements for digital evidence. Secure evidence management drives specialized procurement specifications.
- Public Health:Health ministries and disease surveillance organizations managing sensitive population data. HIPAA-aligned cloud configurations predominate in United States federal health agencies.
Defense commands the largest absolute spending; Public Health agencies are expanding most quickly following pandemic-era infrastructure investments.
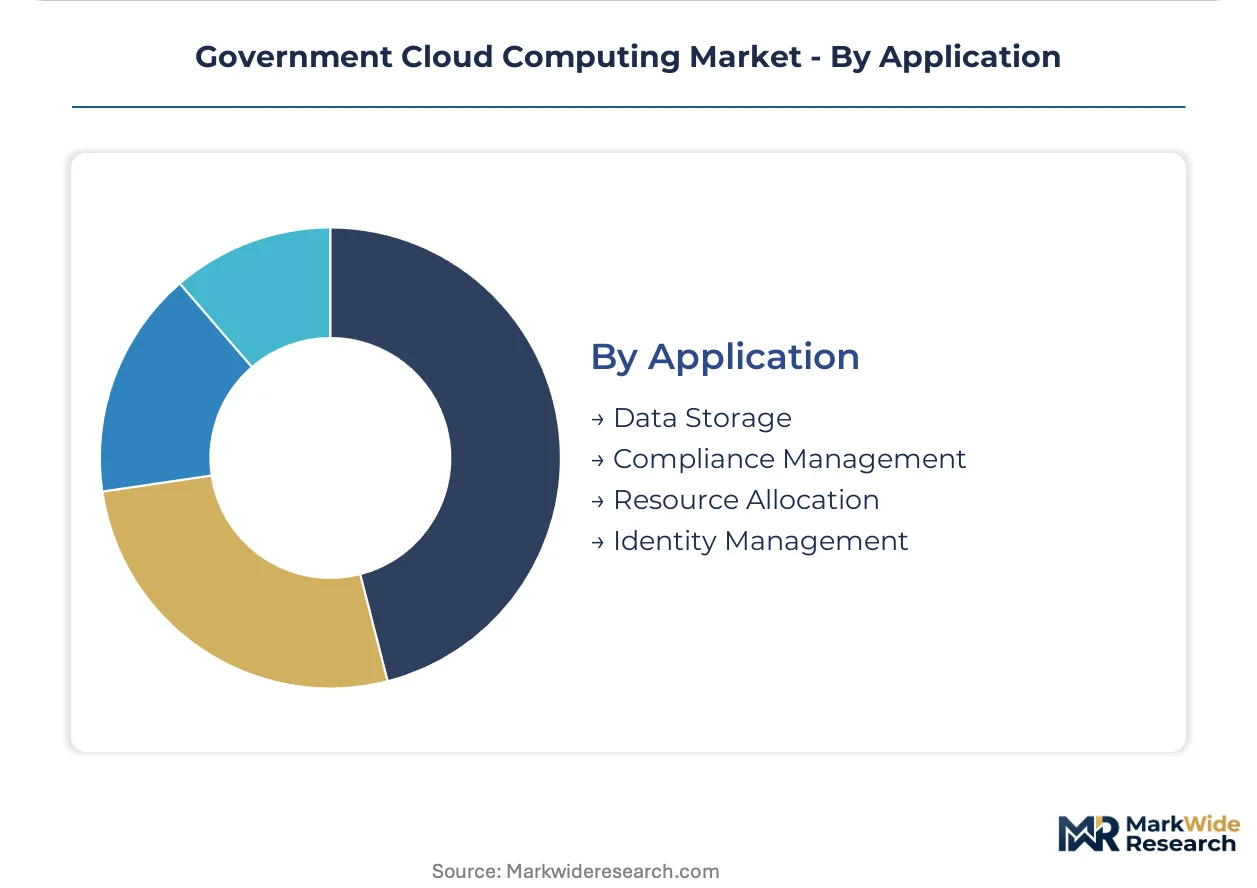
Application:
Functional use cases determine integration complexity and vendor specialization requirements.
- Data Storage:Scalable object and block storage for archival, operational, and analytics datasets. Long-term retention mandates for federal records drive petabyte-scale implementations.
- Compliance Management:Automated policy enforcement and audit documentation platforms. Pre-certified configurations reduce FedRAMP authorization burdens for downstream agencies.
- Resource Allocation:Dynamic workload scheduling and capacity optimization across distributed environments. Multi-cloud brokerage platforms increasingly incorporate resource allocation intelligence.
- Identity Management:Zero-trust authentication and privileged access controls for distributed workforces. Continuous verification architectures displace perimeter-based security models.
Data Storage captures foundational procurement volumes; Identity Management exhibits the steepest expansion trajectory as zero-trust mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscaler concentration anchors North American cloud infrastructure development. Federal procurement regulations and defense classification requirements reshape regional vendor qualification pathways across sovereign jurisdictions.
United States
FedRAMP authorization queues and defense modernization mandates drive procurement velocity. The Department of Defense's CMMC framework tightens contractor cybersecurity requirements. Northern Virginia's data center corridor hosts the densest concentration of accredited government cloud facilities.
United Kingdom
NATO-aligned security baselines and post-Brexit data sovereignty rules redirect procurement toward domestic-accredited providers. The National Cyber Security Centre's cloud security principles govern public-sector vendor selection. London's government technology cluster concentrates cleared engineering talent for classified workload migration.
Germany
Gaia-X sovereignty requirements and BSI cloud certification standards favor EU-based infrastructure. The country's federal IT consolidation program accelerates agency migration to accredited platforms. Frankfurt's financial and government technology hub anchors continental cloud region development.
Australia
Five Eyes intelligence-sharing obligations and the Australian Cyber Security Centre's cloud certification program shape vendor eligibility. State-level digital transformation initiatives expand procurement beyond federal agencies. Canberra's defense and intelligence corridor concentrates classified cloud engineering expertise.
Japan
METI's government cloud standard creates preferential procurement pathways for accredited foreign providers. The country's digital agency drives cross-ministry infrastructure consolidation. Tokyo's metropolitan government technology market leads sub-national cloud adoption among prefectural administrations.
Government Cloud Computing Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors align with systems integrators to navigate complex authorization pathways. The market structures around three tiers: hyperscale cloud providers with comprehensive accreditation portfolios, defense-specialized contractors with security clearance infrastructure, and regional sovereign cloud operators with data residency guarantees. Two competitive archetypes have emerged: full-stack platform vendors competing on breadth of certified services, and niche specialists winning on classified environment expertise. Portfolio diversification and geographic expansion represent the dominant competitive moves as vendors seek to bridge civilian and defense accreditation domains.
Among hyperscale platform providers, Amazon Web Services, Microsoft Corporation, and Oracle Corporation exemplify contrasting strategic positioning. AWS anchors the market through extensive FedRAMP authorization breadth. Microsoft occupies a position centered on classified enclave specialization. Oracle represents database-centric migration continuity for defense clients retaining legacy application architectures.
| Leading Market Players |
|---|
| IBM Corporation |
| VMware, Inc. |
| Amazon Web Services, Inc. |
| DigitalOcean, LLC |
| Salesforce |
| Microsoft Corporation |
| Oracle Corporation |
| General Dynamics Information Technology |
| Alphabet Inc. (Google LLC) |
| Others |
Value Chain & Pricing Dynamics
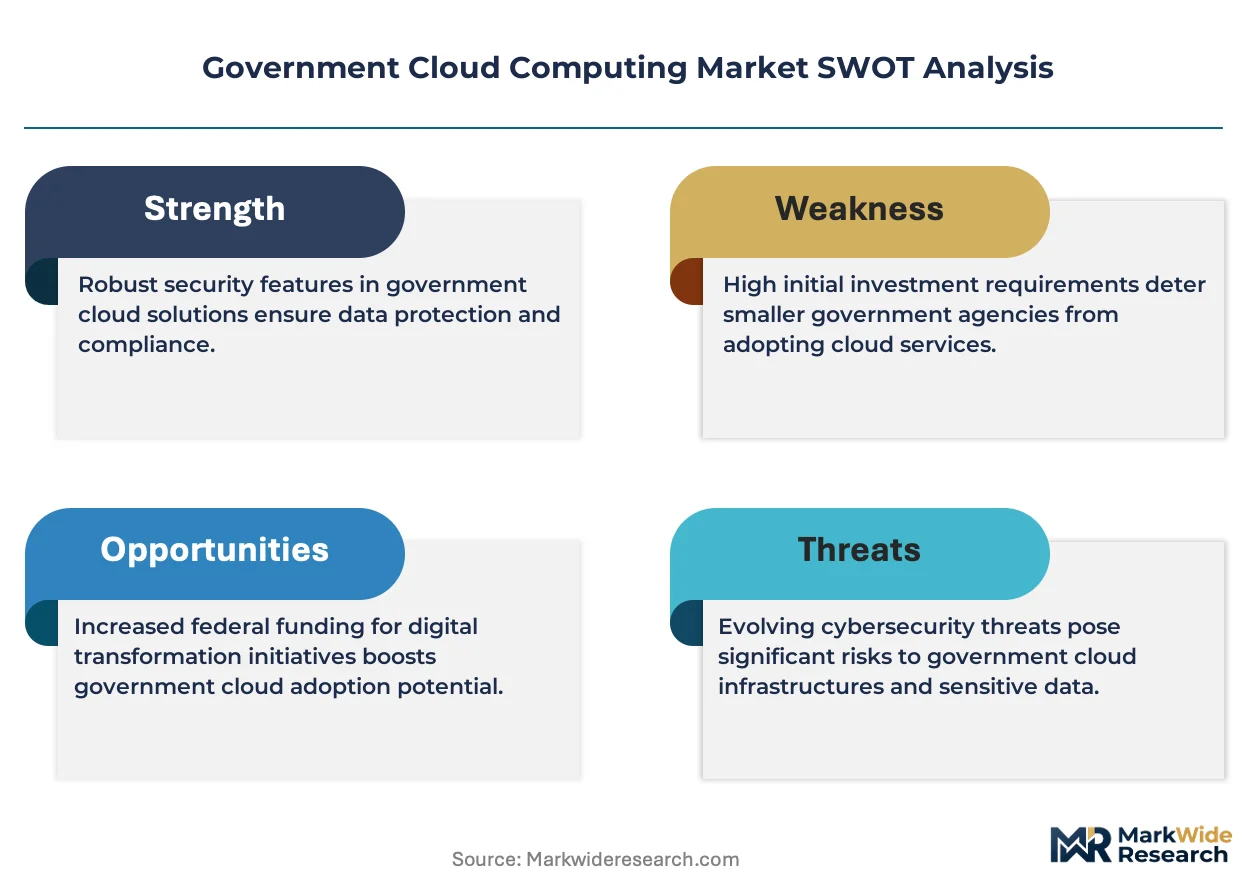
FedRAMP authorization timelines and the EU AI Act's algorithmic transparency mandates gate both qualified supply and premium-tier pricing access for vendors serving government cloud markets. Vendors lacking pre-certified compliance attestations face exclusion from procurement shortlists regardless of price competitiveness, while accredited providers command service premiums for sovereign cloud deployments.
Pricing Analysis
Service bundling distinguishes government cloud pricing, with FedRAMP Moderate and High baseline certifications treated as value-added inclusions rather than standard features. Three-tier pricing structure across premium sovereign enclaves, standard accredited public zones, and economy-grade community clouds reflects certification grade and data residency guarantees. Cost compression in standard tiers is intensifying as multi-cloud brokerage platforms aggregate buyer leverage across agencies. Municipal governments in Australia exhibit highest price sensitivity due to constrained IT budgets, while defense agencies in Five Eyes countries prioritize security over unit cost.
Supply Chain Analysis
Direct-to-agency channels handle hyperscale demand from federal civilian departments, while systems integrators intermediate for complex classified workload migrations. Hardware supply concentrates in Taiwan for advanced semiconductors, the United States for server assembly, and China for commodity components. Raw material dependencies span silicon wafers, rare earth elements for magnetic storage, and specialized alloys for data center cooling infrastructure. Single-source vulnerability in trusted foundry capacity for confidential computing enclaves poses structural risk. Distribution runs through authorized resellers with security clearance infrastructure for classified environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Government cloud computing is consolidating around vendors with comprehensive accreditation portfolios, as eighteen-to-twenty-four-month FedRAMP queues force weaker players toward subcontractor roles or exit.
For Market Incumbents: Hedge against multi-cloud brokerage disintermediation by deepening direct agency relationships through dedicated government cloud engineering centers in Washington DC and London. Prioritize NATO cloud security criteria pre-certification to capture defense modernization budgets before harmonized implementation timelines stabilize. Vertical integration into sovereign data center operations reduces third-country hardware provenance exposure. For New Entrants and Emerging Players: Systems integrators with existing security clearance infrastructure represent the most viable channel partnership path for bypassing direct authorization backlogs. Target sub-national government tiers in Germany and Australia, where federal consolidation programs have not yet penetrated state and municipal procurement. Specialize in zero-trust security mesh integration for agencies replacing perimeter-based architectures. For Investors and Strategic Acquirers: NATO member state defense cloud contract awards are the leading indicator that sovereign-accredited provider valuations will diverge from commercial cloud comparables. Focus acquisition screening on regional sovereign cloud operators with established data residency guarantees and existing BSI or CNIL certifications. Monitor FedRAMP authorization queue length as the primary demand-supply imbalance signal.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Reduces eighteen-month qualification windows that currently fragment vendor eligibility across agencies. |
| Sovereign Cloud Region Expansion | Captures EU data residency mandates under Gaia-X and CSRD-adjacent frameworks in France and Germany. |
| Zero-Trust Platform Integration | Aligns with Department of Defense CMMC requirements for continuous authentication architectures. |
| Confidential Computing Partnership | Addresses Five Eyes signals intelligence demand for hardware-based memory encryption capabilities. |
| Multi-Cloud Brokerage Acquisition | Consolidates fragmented operational accountability across AWS, Azure, and Oracle Government Cloud deployments. |
Study Parameters
SEC filings from hyperscale cloud providers, FedRAMP authorization databases, and NATO procurement disclosure records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with federal IT procurement officers, cleared cloud architects, systems integrator program managers, and defense contractor solution architects validated demand assumptions and authorization timeline estimates. Bottom-up triangulation across agency budget documentation and top-down reconciliation against vendor-reported government cloud revenue segments anchored value projections.
Historical trendline analysis of federal civilian cloud migration patterns and defense modernization appropriation cycles established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated solution type, deployment architecture, security classification tier, and end-user agency function. CAGRs were derived from regression analysis of accredited workload growth against authorization pipeline velocity. Forecast inputs included FedRAMP queue length projections and NATO cloud security criteria harmonization timelines.
Caveats apply where FedRAMP authorization process reforms or EU AI Act enforcement intensity could materially shift the outlook for vendor market access. Forecasts reflect assumptions regarding sustained defense modernization funding and cross-border data flow policy stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Hadoop-As-A-Service (Haas) Market
Cloud Computing
Cloud ECS Market
Cloud Computing
Asia-Pacific Mobile Cloud Market
Cloud Computing
Private Cloud Market
Cloud Computing
VM Service Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Middle East and Africa Cloud Infrastructure Services Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
UK Cloud Backup Market
Cloud Computing
SME Cloud Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
Global Grid Computing Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
Virtual Machines Market
Cloud Computing
Philippines ICT Market