
 Malaysia Bicycle Market | 2026-2036
Malaysia Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Bicycle Market Outlook
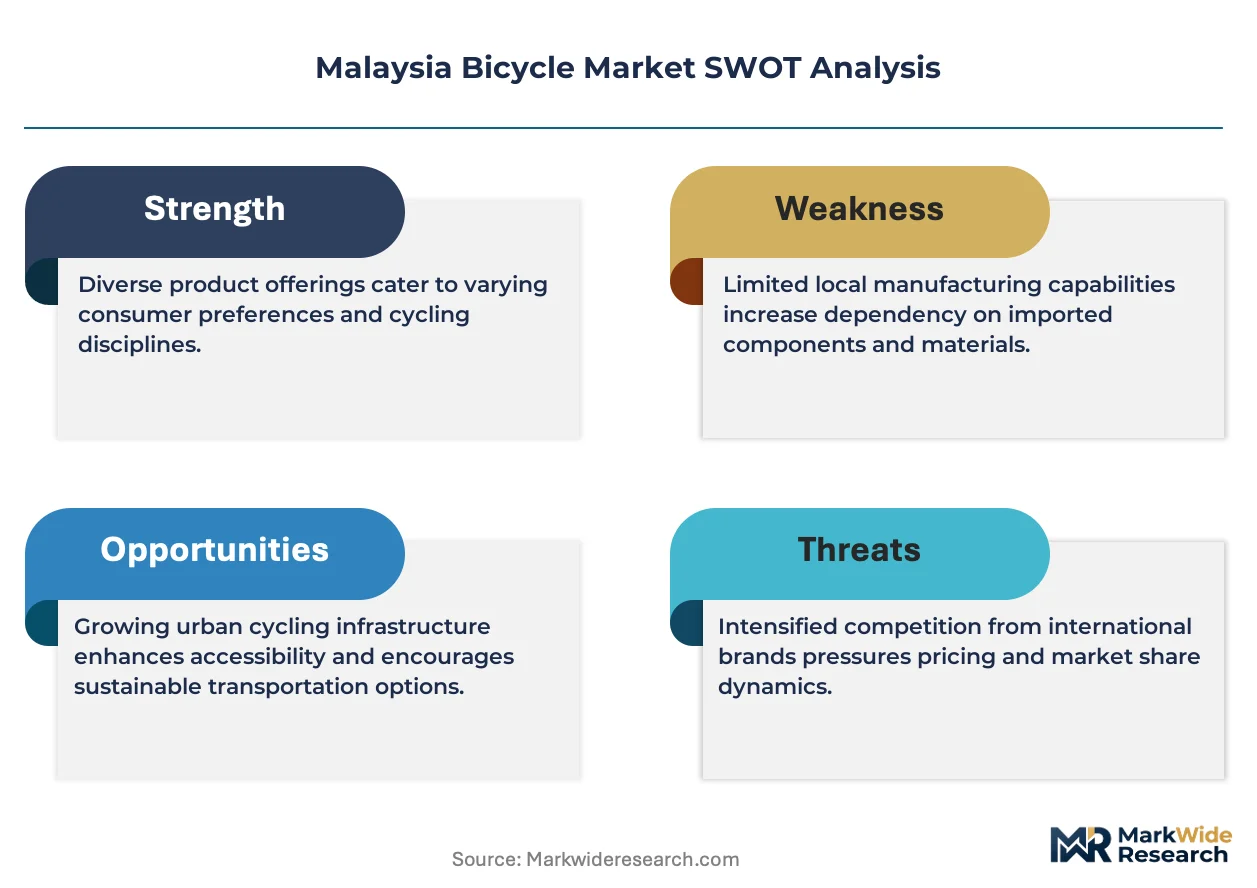
Subscription-based bicycle maintenance and software-defined fleet management is rebalancing what manufacturers and retailers actually monetize. Trek Bikes leverages its dealer network to bundle service contracts with premium road bike sales. Giant Bicycles anchors its position through in-house carbon fiber frame production and direct-to-consumer digital channels. Hero Cycles Ltd competes on volume scale in the budget tier, supplying mass-market hybrids through Malaysian supermarket partnerships.
A bicycle is a human-powered, pedal-driven vehicle with two wheels attached to a frame, typically constructed from aluminum alloys, carbon fiber composites, or chromoly steel tubing, with gear ratios ranging from single-speed to 22-speed derailleur systems and braking mechanisms encompassing rim, disc, or hydraulic configurations; its primary commercial purpose spans personal transportation, fitness, sport competition, and urban last-mile logistics. Mountain bikes and road bikes together occupy the largest revenue share, with mountain bikes dominating sales in East Malaysian terrain markets and road bikes capturing premium spend in West Malaysian club cycling networks. The distribution channel structure reveals specialty stores commanding the highest margin pools through test-ride experiences and fitting services, while online retail extends fastest among younger recreational users seeking price transparency.
Malaysia's Road Transport Department (JPJ) bicycle lane standards, the National Cycling Policy framework, and SIRIM Bhd product safety certifications collectively determine which frame geometries and component grades gain market access. These regulations elevate compliance costs for imported complete bikes while creating protected demand pockets for locally assembled models meeting domestic certification pathways. Stakeholders must track how JPJ infrastructure commitments translate into lane mileage targets and whether SIRIM tightens e-bike battery safety protocols.
Market Dynamics
Malaysia's bicycle sector is restructuring around JPJ-mandated lane infrastructure and battery-safety certification pathways that favor locally assembled e-bikes over fully imported units.
Growth Catalysts
- JPJ Bicycle Lane Standards:Federal lane mileage targets in the Klang Valley corridor are creating protected demand for commuter-ready hybrids and folding frames.
- E-bike Battery Localization:SIRIM Bhd certification requirements for lithium-ion packs are pulling assembly operations into Penang and Selangor industrial zones.
- Last-mile Logistics:Food delivery platforms in Kuala Lumpur are standardizing fleet procurement around 250W pedal-assist configurations.
Market Restraints
- Carbon Fiber Import Concentration:Premium frame tubing supply concentrates in Taiwanese and Chinese factories, exposing assemblers to shipping rate volatility.
- SIRIM Testing Bottlenecks:E-bike electrical system approvals face 8-12 week backlogs at the Shah Alam laboratory.
- Private Vehicle Subsidy Persistence:Fuel price controls and national car loan schemes dampen modal shift incentives for suburban households.
Strategic Opportunities
- East Malaysian Terrain Markets:Sarawak and Sabah trail networks remain underserved by full-suspension mountain bike distribution.
- Subscription Maintenance Models:Fleet operators are piloting per-kilometer service contracts replacing upfront component sales.
- Intermodal Transit Integration:RapidKL rail stations present untapped dockless bicycle parking concession opportunities.
Industry Challenges
- Certification Timeline Compression:New e-bike entrants face SIRIM battery thermal runaway testing protocols that extend product launch windows.
- Frame Geometry Standardization:Disparate JPJ lane width specifications across states complicate nationwide fleet deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Bicycle Market |
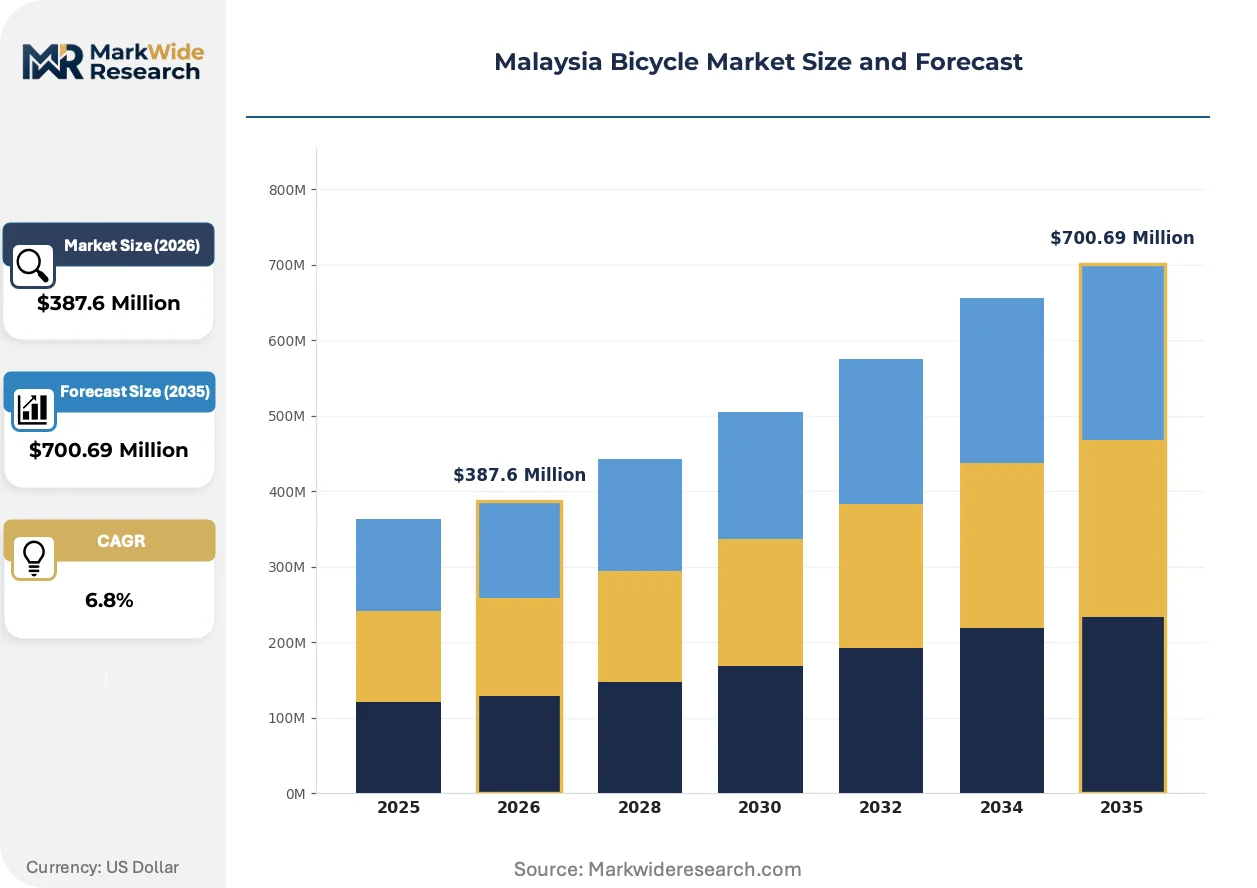
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain Bike, Road Bike, Hybrid Bike, BMX End User: Children, Adults, Professionals, Recreational Users Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Glory Bicycle Sdn Bhd, Accell Group, Firefox, Liv, Canyon, Trek Bikes, Hero Cycles Ltd, Merida Bikes, Giant Bicycles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Bicycle Market Strategic Shifts
Component digitization and policy-driven localization are compressing traditional import-heavy supply chains while opening service-based revenue streams.
Smart torque-sensing pedal-assist systems are converging with fleet telematics platforms. Delivery operators in Penang and Johor Bahru are retrofitting existing mechanical drivetrains with sensor-equipped bottom brackets. This convergence is enabling real-time battery health monitoring that shifts maintenance from reactive repairs to predictive component swaps.
Malaysia's National Cycling Policy framework is tightening domestic content thresholds for federal infrastructure-linked procurement. The policy requires 40% local value-add for bicycles deployed on JPJ-designated lanes. Premium road bike assemblers in Selangor are responding by sourcing handlebar tape, saddles, and wheelsets from domestic rubber and aluminum processors.
Recreational buyers are fragmenting across direct-to-consumer digital channels and experience-driven specialty retail. Younger cyclists in the Klang Valley research specifications online before completing purchases at fitting studios offering dynamic saddle pressure mapping. This bifurcation is squeezing mid-tier distributors lacking either price transparency or premium service depth.
Malaysia Bicycle Market Segmentation
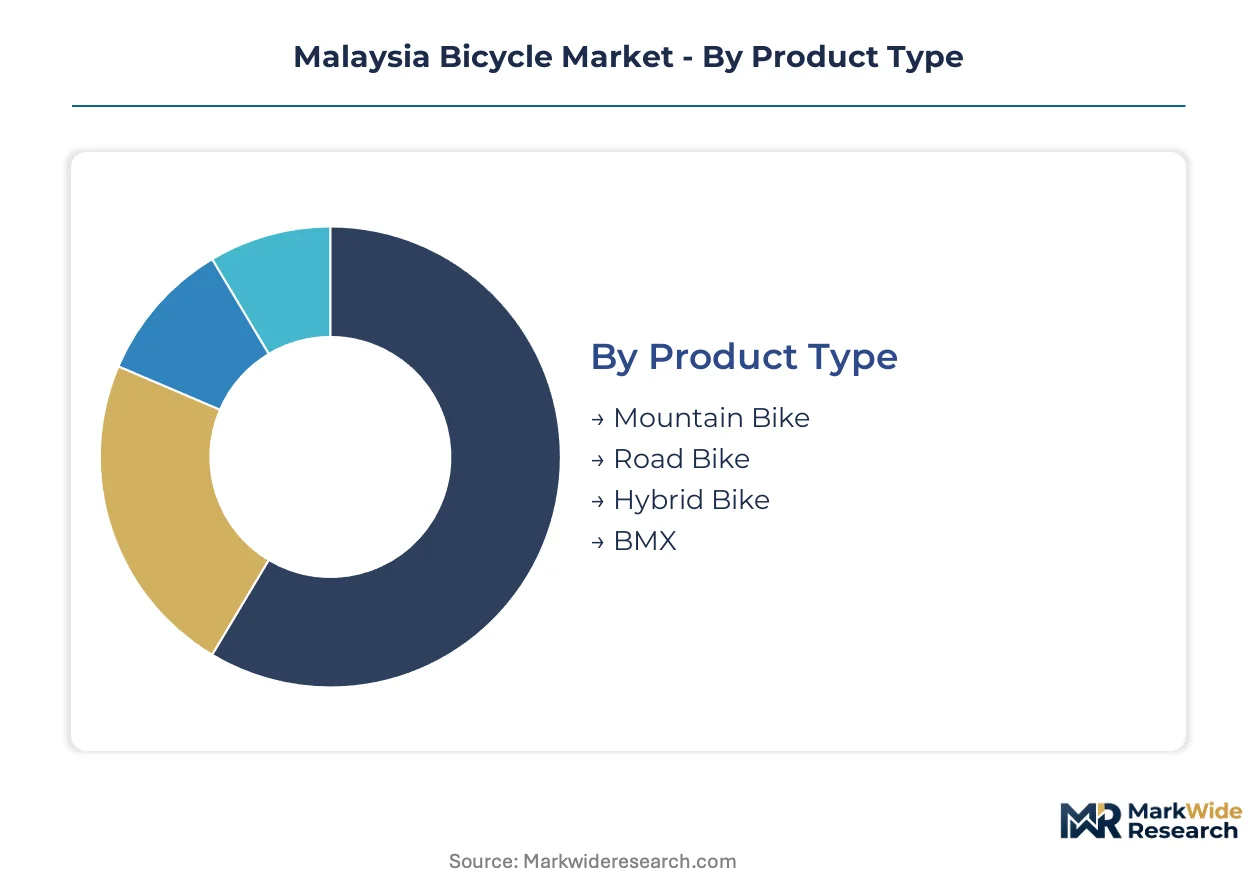
Malaysia's bicycle market segments reflect divergent supply chain configurations, from carbon fiber import dependency in premium tiers to localized assembly for SIRIM-certified e-bikes. Understanding these divides reveals where procurement leverage concentrates and which channels capture margin.
Product Type:
Frame material sourcing and assembly location vary sharply across product categories, with East Malaysian terrain demands pulling supply toward full-suspension capabilities and West Malaysian club networks driving premium road bike imports.
- Mountain Bike:Full-suspension and hardtail configurations dominate Sarawak and Sabah trail networks where terrain complexity demands robust frame geometries. Kuching and Kota Kinabalu retailers report strongest demand for 27.5-inch and 29-inch wheel variants suited to tropical mud conditions.
- Road Bike:Carbon fiber frame assemblies from Taiwanese factories supply West Malaysian cycling clubs in Kuala Lumpur and Penang. These units carry the highest landed cost exposure to shipping rate volatility and SIRIM import documentation delays.
- Hybrid Bike:Aluminum-frame commuters with flat handlebars serve Klang Valley last-mile connectivity gaps; JPJ lane expansion is pulling procurement toward locally assembled units meeting domestic content thresholds.
- BMX:Chromoly steel frames concentrate in youth recreational demand around Selangor skate parks and urban plazas; limited distribution infrastructure outside major metros constrains penetration.
Mountain bikes absorb the bulk of installed capacity in East Malaysia; hybrid bikes are expanding most quickly on federal infrastructure procurement.
End User:
Customer type determines service bundling requirements and price elasticity, with fleet operators demanding predictive maintenance contracts that reshape manufacturer revenue models.
- Adults:Urban commuters in Kuala Lumpur and Penang drive e-bike adoption; food delivery platforms standardize 250W pedal-assist fleet specifications with telematics integration.
- Children:Mass-market units concentrate in supermarket and department store channels; Hero Cycles Ltd supplies volume through domestic retail partnerships with limited fitting services.
- Professionals:Competitive cyclists and club riders demand dynamic saddle pressure mapping and test-ride experiences available only through specialty retail channels in the Klang Valley.
- Recreational Users:Digital-native buyers research specifications online before completing purchases; this segment fragments across direct-to-consumer platforms and experience-driven fitting studios.
Adult commuters represent the dominant volume base; recreational users are gaining share fastest through channel bifurcation.
Distribution Channel:
Channel selection determines margin capture and customer acquisition cost, with specialty stores defending position through service depth while online retail extends reach among price-sensitive segments.
- Specialty Stores:Test-ride experiences and professional fitting services command premium pricing; Trek Bikes leverages this channel to bundle maintenance contracts with road bike sales.
- Online Retail:Price transparency attracts younger recreational users; Giant Bicycles anchors direct-to-consumer digital channels with in-house carbon fiber production enabling margin compression.
- Department Stores:Mid-tier hybrids and children's bikes move through seasonal promotions; limited technical support constrains repeat purchase rates.
- Supermarkets:Budget-tier mass-market units serve impulse purchases and gift demand; Hero Cycles Ltd dominates this channel through volume scale and simplified SKU management.
Specialty stores retain the highest margin pools; online retail is climbing the fastest on generational purchasing shifts.
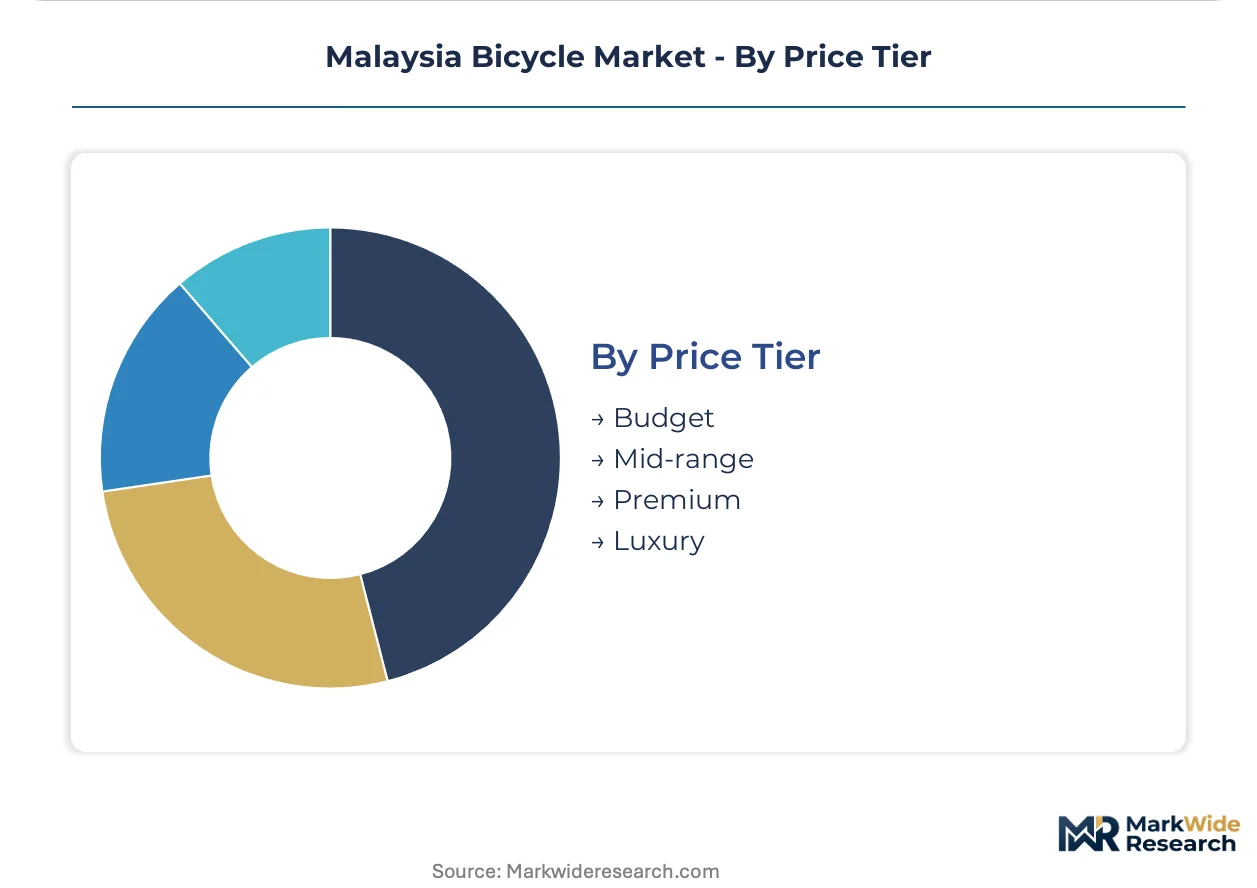
Price Tier:
Certification grade and volume scale stratify pricing, with SIRIM battery safety protocols creating compliance cost barriers that segment the e-bike market.
- Premium:Carbon fiber road bikes and full-suspension mountain bikes face 8-12 week SIRIM testing backlogs at Shah Alam; these delays protect incumbent assemblers with established certification pathways.
- Mid-range:Aluminum-frame hybrids and hardtail mountain bikes balance performance and accessibility; this tier captures modal shift demand from suburban households responding to JPJ lane expansion.
- Budget:Steel-frame utility bikes and basic children's units concentrate in supermarket and department store channels; fuel price controls dampen substitution incentives for this price-sensitive segment.
- Luxury:Custom geometry and component-grade differentiation serve competitive professionals; limited domestic assembly capability concentrates supply in direct import channels with highest documentation burden.
Mid-range pricing absorbs the bulk of federal infrastructure-linked procurement; premium tiers face steepest expansion constraints from certification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Klang Valley corridor anchors Malaysia's bicycle demand, with Kuala Lumpur's urban commuters and last-mile logistics operators driving procurement volumes for e-bikes and folding frames.
Selangor
Shah Alam hosts SIRIM Bhd's primary testing laboratory where e-bike battery thermal runaway protocols create 8-12 week certification backlogs. The state's industrial zones in Subang and Petaling Jaya concentrate assembly operations for locally sourced aluminum frames and rubber components meeting federal domestic content thresholds.
Penang
George Town's heritage tourism and university corridors sustain recreational cycling demand alongside emerging food delivery fleet procurement. The state's Free Industrial Zone pulls lithium-ion pack assembly operations seeking proximity to electronics component suppliers and SIRIM certification pathways.
Sarawak
Kuching's trail networks and tropical terrain conditions drive full-suspension mountain bike demand with specialized requirements for mud-resistant 27.5-inch and 29-inch wheel variants. Limited distribution infrastructure outside the capital constrains premium brand penetration despite robust recreational usage.
Sabah
Kota Kinabalu's adventure tourism sector and coastal commuting patterns create bifurcated demand between hardtail mountain bikes for trail access and hybrid commuters for urban connectivity. East Malaysian logistics costs elevate landed prices for carbon fiber frames against West Malaysian distribution centers.
Malaysia Bicycle Market Competitive Environment
Capital-heavy producers compete with asset-light designers across Malaysia's bicycle sector, with integrated frame manufacturers holding cost advantages against import-dependent assemblers. The vendor base stratifies into three tiers: premium road and mountain bike specialists, mid-range hybrid assemblers serving federal procurement, and volume-scale budget suppliers. Consolidation pressure concentrates among e-bike entrants facing SIRIM certification barriers, while geographic expansion and backward integration into carbon fiber sourcing represent dominant competitive vectors.
Within the premium-tier specialist segment, Trek Bikes and Giant Bicycles occupy positions defined by dealer network depth and in-house carbon fiber production capability respectively. Hero Cycles Ltd exemplifies the volume-driven archetype, supplying mass-market units through supermarket partnerships with simplified SKU management. These three entities represent divergent strategic postures on certification compliance, channel control, and domestic content integration.
| Leading Market Players |
|---|
| Glory Bicycle Sdn Bhd |
| Accell Group |
| Firefox |
| Liv |
| Canyon |
| Trek Bikes |
| Hero Cycles Ltd |
| Merida Bikes |
| Giant Bicycles |
| Others |
Value Chain & Pricing Dynamics
JPJ-mandated lane infrastructure specifications are forcing procurement officers toward locally assembled hybrids and folding frames, compressing import-heavy supply chains and elevating domestic content premiums against fully imported carbon fiber units.
Pricing Analysis
Margin tightening in the premium tier reflects SIRIM certification backlogs at Shah Alam that extend product launch windows and protect incumbent assemblers with established pathways. Three-tier pricing structure across premium, mid-range, and budget levels stratifies by certification grade and volume scale, with battery-safety protocols creating compliance cost barriers. Cost-down pressure on e-bike configurations accelerates because food delivery platforms standardize fleet procurement around 250W pedal-assist specifications. Budget-tier buyers through supermarket channels exhibit highest price sensitivity; competitive professionals seeking custom geometry show lowest.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion pack refurbishment are emerging around Penang Free Industrial Zone operations, with battery health monitoring enabling predictive component swaps rather than reactive disposal. Manufacturing concentration centers on Taiwan and China for carbon fiber frame tubing, with domestic assembly in Selangor and Penang for SIRIM-certified e-bikes. Raw material dependencies span lithium carbonate, aluminum alloys, and rubber compounds for tires and grips. Single-source vulnerability concentrates in Taiwanese carbon fiber suppliers. Distribution runs through specialty retail channels with test-ride experiences, direct-to-consumer digital platforms, and supermarket mass-market partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's bicycle sector is becoming a vertical-integration race where control over carbon fiber sourcing and battery pack assembly determines margin capture against import-dependent competitors.
For Market Incumbents: Deploy in-house carbon fiber production capability to offset shipping rate volatility from Taiwanese suppliers and compress landed cost exposure. Deepen certification investment at SIRIM Shah Alam to accelerate product launch windows against new e-bike entrants facing thermal runaway testing bottlenecks. Anchor dealer network control through bundled maintenance contracts that shift revenue from transactional frame sales to recurring service streams. For New Entrants and Emerging Players: Begin with East Malaysian terrain markets where Sarawak and Sabah trail networks remain underserved by full-suspension mountain bike distribution. Target Kuching and Kota Kinabalu retailers with 27.5-inch and 29-inch wheel variants suited to tropical mud conditions. Pursue dockless bicycle parking concessions at RapidKL rail stations for intermodal transit integration. For Investors and Strategic Acquirers: Re-rating potential sits with locally assembled e-bike specialists given National Cycling Policy domestic content thresholds tightening federal procurement eligibility. Long-term viability favors operators with captive lithium-ion pack assembly in Penang industrial zones. Monitor SIRIM battery safety protocol revisions as inflection indicator for compliance cost barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Sourcing | Captive supply from Taiwanese factories reduces shipping rate volatility exposure for premium road bike assemblers. |
| Battery Pack Localization | Penang Free Industrial Zone assembly operations meet SIRIM certification requirements and federal domestic content thresholds. |
| Subscription Maintenance Model Launch | Per-kilometer service contracts replace upfront component sales for food delivery fleet operators in Kuala Lumpur. |
| Direct-to-Consumer Digital Channel Expansion | Giant Bicycles leverages in-house carbon fiber production to compress margins against specialty retail markups. |
| East Malaysian Distribution Network Buildout | Kuching and Kota Kinabalu trail network access captures underserved full-suspension mountain bike demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with bicycle assemblers, specialty retail operators, fleet procurement managers, and SIRIM certification officers alongside bottom-up and top-down triangulation. Secondary sources encompassed JPJ infrastructure commitment disclosures, National Cycling Policy framework documents, SIRIM Bhd testing protocols, and Malaysia External Trade Development Corporation import statistics.
Reconciliation across production volume databases, retail audit channels, and fleet operator procurement records shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product type, end user archetype, distribution channel, and price tier, with CAGRs derived from trend extrapolation against infrastructure investment trajectories. Forecast inputs incorporated JPJ lane mileage targets and SIRIM testing capacity expansion assumptions.
Underlying measurement precision varies by segment; e-bike and subscription service categories carry tighter precision than luxury custom geometry tiers given certification documentation density. Forecasts reflect documented assumptions about regulatory enforcement timelines and battery technology cost curves. Practitioners should monitor SIRIM protocol revisions and JPJ infrastructure disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Connected Motorcycle Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Motorcycle Tubeless Tire Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Motorcycle Headlight Market