
 Communication Test and Measurement (Ctandm) Market | 2026-2036
Communication Test and Measurement (Ctandm) Market Size, Share, and Industry Trends Forecast 2026-2036
Communication Test and Measurement (Ctandm) Market Analysis
The capital-intensity divergence between benchtop instrument specialists and software-centric test platform vendors is collapsing as cloud-native architectures commoditize hardware layers. Keysight Technologies leverages its mmWave measurement libraries to sustain premium positioning in 5G base station validation. Rohde & Schwarz anchors European defense and aerospace test programs through calibrated secure-facility supply chains. Anritsu competes aggressively in fiber optic field test sets for undersea cable commissioning across Asia-Pacific littoral markets.
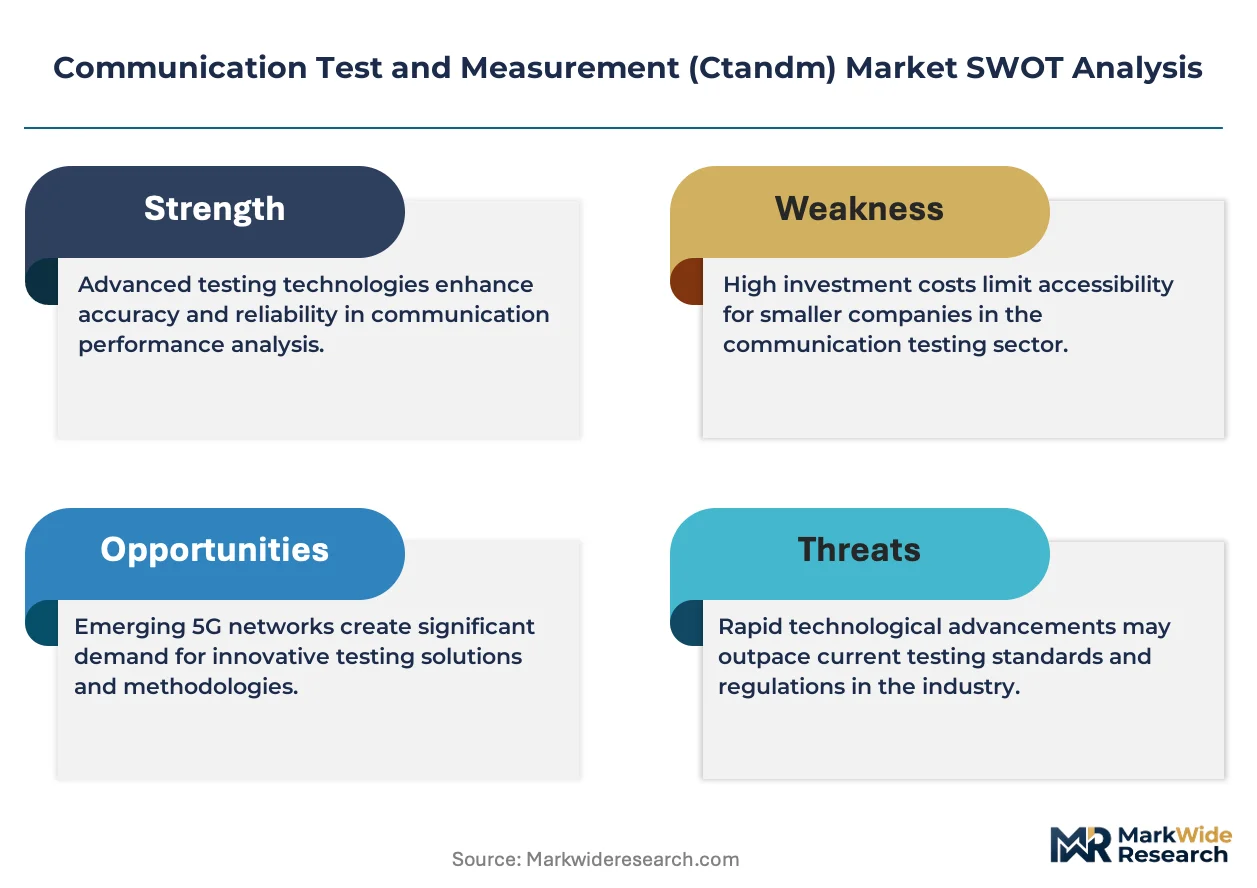
Communication Test and Measurement encompasses instruments and systems that characterize, verify, and certify performance parameters of wired and wireless communication equipment, typically operating across frequency ranges from sub-6 GHz to millimeter-wave bands with resolution bandwidths down to 1 Hz. These systems validate protocol conformance, signal integrity, and electromagnetic compliance before network elements enter commercial service. Spectrum Analyzers and Network Performance Analyzers command the largest installed bases due to their ubiquity in cellular base station deployment workflows. 5G test technology is expanding fastest as massive MIMO beamforming validation requires new over-the-air test methodologies that obsolete conventional conducted measurement approaches. Fiber Optics instrumentation retains mature margin pools in submarine cable maintenance despite slower unit growth.
FCC Part 27 spectrum rules, ETSI EN 303 567 5G conformance standards, and MIIT radio transmission equipment type-approval requirements collectively shape product development roadmaps and market access preconditions for test equipment vendors. FDA electromagnetic compatibility standards for wireless medical devices create adjacent demand for specialized anechoic chamber test configurations. Stakeholders must monitor Open RAN security certification timelines and corresponding test scope expansion at national telecom laboratories.
Market Dynamics
The Communication Test and Measurement market is experiencing a fundamental restructuring as cloud-native test architectures erode the traditional hardware-software boundary that once protected benchtop instrument margins. This collapse of the capital-intensity divergence between legacy vendors and software-centric entrants is forcing incumbents to defend positioning through specialized measurement libraries and calibrated supply chains.
Growth Catalysts
- 5G Standalone Network Mandates:Telecom service providers in Germany, Japan, and the United States must validate beamforming performance under FCC Part 27 spectrum rules and ETSI EN 303 567 conformance standards, expanding procurement of over-the-air test chambers.
- Open RAN Interoperability Requirements:Regulator-mandated security certification timelines at national telecom laboratories in South Korea and the United States are broadening protocol conformance testing scope for disaggregated radio units.
- Submarine Cable Commissioning:Asia-Pacific littoral markets are driving fiber optic field test set demand for undersea cable maintenance and new route activation.
Market Restraints
- Millimeter-Wave Component Scarcity:Specialized RF front-end modules for 5G test equipment face supply concentration among Japanese and German precision component suppliers, creating input cost volatility.
- Calibrated Facility Access:Secure-facility supply chains for defense and aerospace test programs require government-cleared personnel and infrastructure, limiting vendor expansion.
- Legacy Conducted Test Obsolescence:Conventional cable-connected measurement approaches cannot validate massive MIMO beamforming, forcing premature equipment retirement.
Strategic Opportunities
- Wireless Medical Device Certification:FDA electromagnetic compatibility standards for connected health equipment create adjacent demand for specialized anechoic chamber configurations in the United States.
- India Manufacturing Incentives:PLI scheme benefits for telecom equipment production are attracting test equipment vendors to establish local calibration and service capabilities.
- AI-Driven Test Automation:Convergence of machine learning inference with real-time spectrum analysis enables predictive fault detection in cellular base station deployment workflows.
Industry Challenges
- Millimeter-Wave Engineering Talent:Shortage of RF engineers proficient in over-the-air test methodology design delays customer deployment timelines and extends commissioning cycles.
- Multi-Standard Certification Complexity:Simultaneous compliance with MIIT radio transmission equipment type-approval, FCC Part 27 rules, and ETSI EN 303 567 standards fragments product development roadmaps.
- Cloud-Native Integration Friction:Legacy test hardware architectures resist API-based orchestration, complicating hybrid deployments for operators transitioning to software-defined validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Communication Test and Measurement (Ctandm) Market |
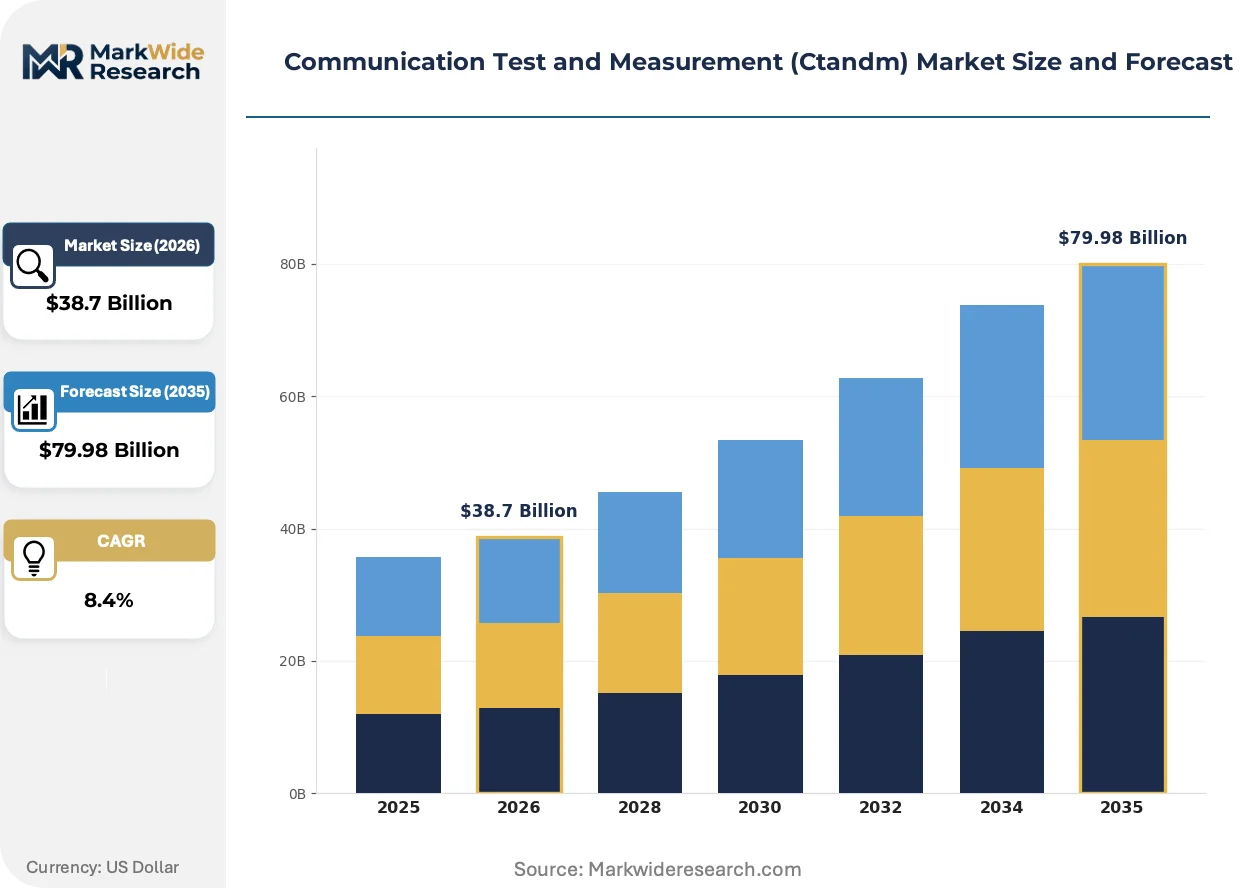
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Performance Analyzers, Signal Generators, Spectrum Analyzers, Cable Testers Technology: 5G, LTE, Wi-Fi, Fiber Optics Application: Telecommunications, Automotive, Aerospace, Industrial Automation End User: Service Providers, Enterprises, Government Agencies, Academic Institutions |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu, Fortive, EXFO, VIAVI Solutions, Yokogawa, Spirent Communications, Tektronix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Communication Test and Measurement (Ctandm) Market Emerging Trajectories
Test methodology is fragmenting along hardware-software lines as cloud architectures commoditize underlying instrument layers while premium value concentrates in specialized measurement intellectual property and secure supply chains.
Over-the-air test systems for 5G massive MIMO validation are bifurcating the market between conducted and radiated measurement approaches. Base station manufacturers in South Korea and the United States are adopting these systems at accelerated procurement cycles. This technology shift is compressing margins for traditional cable-based network analyzers while expanding addressable market for anechoic chamber integrators.
ETSI EN 303 567 5G conformance standards and FCC Part 27 spectrum rules are tightening electromagnetic exposure and protocol interoperability requirements simultaneously. Equipment vendors must now maintain parallel certification tracks for European and American market access. Test scope expansion at national telecom laboratories is most pronounced in Germany and Japan, where Open RAN security mandates are adding penetration testing to traditional radio conformance workflows.
Service contract unbundling is altering how operators acquire test capability. Tier-one carriers in the United States and South Korea are separating hardware procurement from calibration and software maintenance, pressuring vendors to defend recurring revenue through measurement-as-a-service platforms. This pattern is most visible in 5G base station deployment programs where capital constraints favor operational expenditure models over instrument ownership.
Communication Test and Measurement (Ctandm) Market Segmentation
Test equipment procurement patterns diverge sharply across deployment contexts, with margin pools concentrating in technologies serving 5G standalone validation and fiber optic submarine commissioning. Understanding segment-level demand drivers enables vendors to calibrate R&D investment and service contract structures against actual deployment workflows.
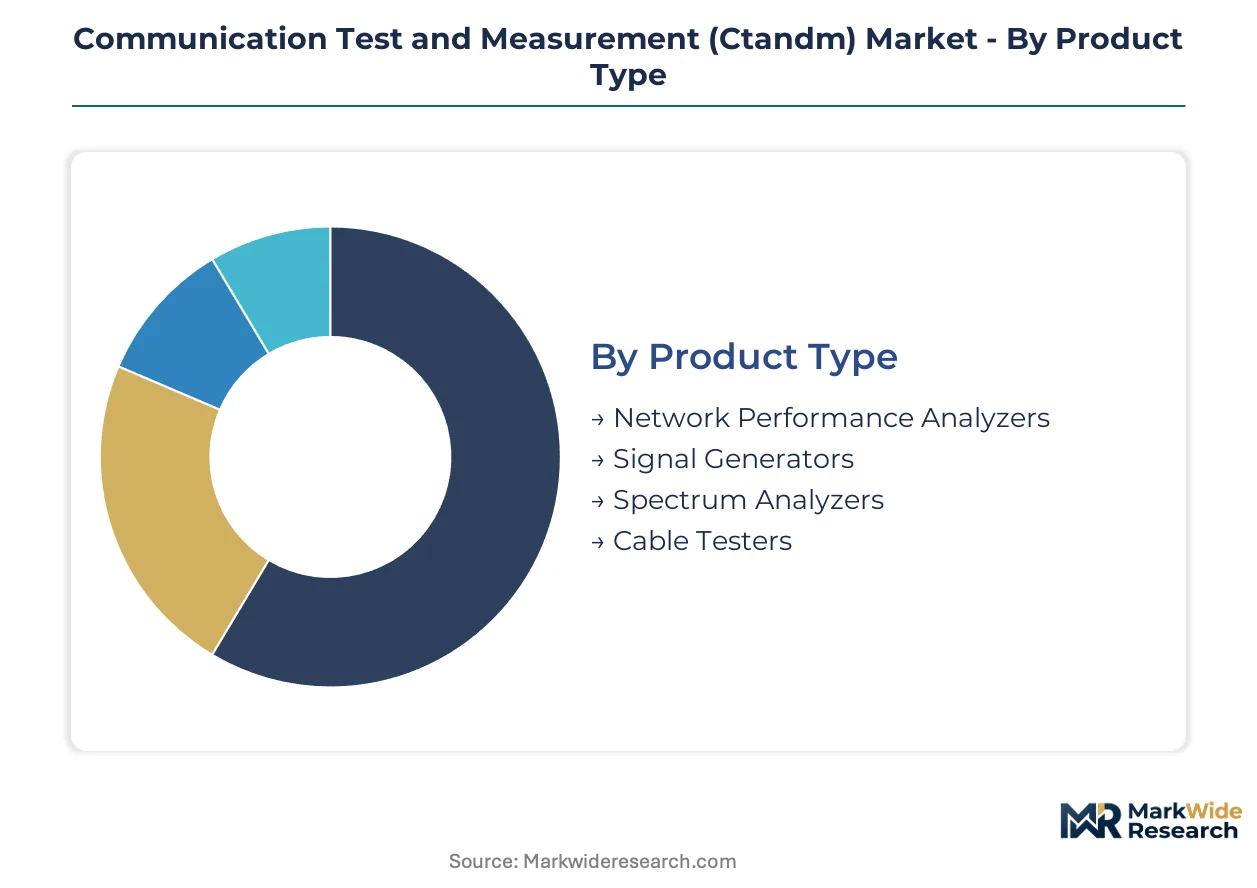
Product Type:
Premium positioning concentrates in instruments supporting millimeter-wave characterization, where specialized measurement libraries sustain pricing power against commoditized entry-level units.
- Spectrum Analyzers:These instruments characterize frequency-domain signal parameters across sub-6 GHz to millimeter-wave bands with resolution bandwidths down to 1 Hz. Demand concentrates in South Korea and the United States where FCC Part 27 spectrum rules and ETSI EN 303 567 conformance standards mandate rigorous electromagnetic compliance validation before base station commercialization.
- Network Performance Analyzers:Systems verifying protocol conformance and end-to-end latency in live network environments. Procurement is accelerating among German and Japanese telecom service providers facing Open RAN interoperability mandates that expand test scope beyond traditional radio conformance.
- Signal Generators:Precision RF sources enabling receiver sensitivity and selectivity testing across cellular and satellite communication bands.
- Cable Testers:Portable instruments for coaxial and twisted-pair infrastructure verification in field deployment scenarios.
The dominant share belongs to Spectrum Analyzers, while Network Performance Analyzers are closing the gap fastest.
Technology:
Deployment velocity varies by standard maturity, with newest specifications commanding premium pricing despite smaller installed bases.
- 5G:Over-the-air test methodologies for massive MIMO beamforming validation have displaced conventional conducted measurement approaches. South Korean national spectrum auctions accelerated base station rollout timelines, compressing procurement cycles for anechoic chamber integrators serving Samsung and LG Uplus deployment programs.
- Fiber Optics:Submarine cable commissioning across Asia-Pacific littoral markets sustains mature margin pools in optical time-domain reflectometry and spectral analysis instruments. Japanese precision component suppliers concentrate supply of specialized photodetector modules, creating input cost volatility for test equipment vendors.
- LTE:Legacy network maintenance and interworking test requirements in emerging markets.
- Wi-Fi:Enterprise access point certification and residential gateway validation protocols.
5G commands the steepest expansion trajectory, though Fiber Optics retains the most stable recurring revenue profile.
Application:
End-use concentration determines calibration infrastructure requirements and security clearance thresholds for vendor personnel.
- Telecommunications:Base station manufacturing and network deployment workflows dominate procurement volume. Tier-one carriers in the United States and South Korea are unbundling hardware acquisition from software maintenance, pressuring vendors to defend recurring revenue through measurement-as-a-service platforms.
- Aerospace:Defense test programs require calibrated secure-facility supply chains with government-cleared personnel. Rohde & Schwarz anchors European positioning through these restricted-access relationships.
- Automotive:Connected vehicle electromagnetic compatibility validation and V2X protocol conformance testing.
- Industrial Automation:Private 5G network deployment in manufacturing facilities and warehouse robotics systems.
Telecommunications captures the largest revenue pool, while Aerospace delivers the highest margin per unit.
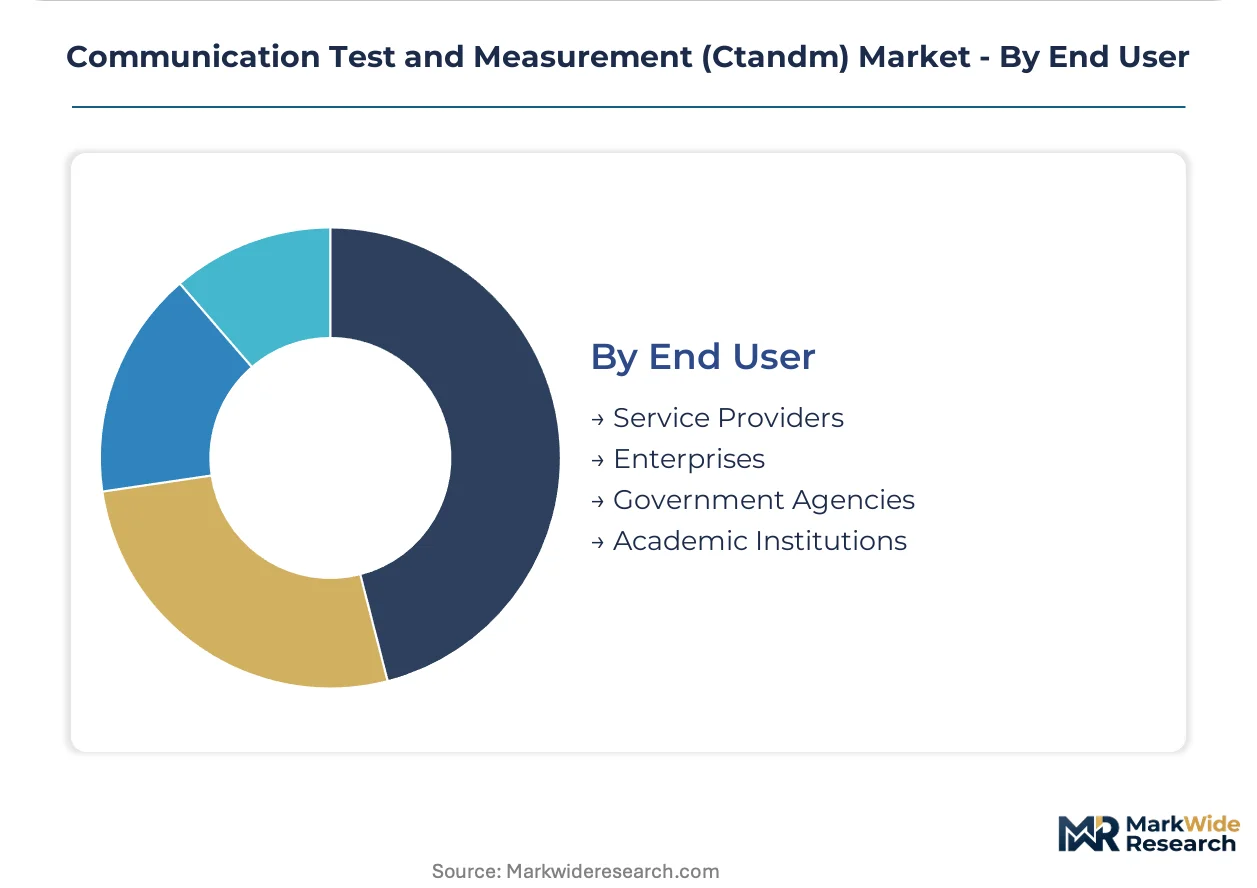
End User:
Procurement authority fragmentation shapes sales cycle complexity and contract structuring options.
- Service Providers:Capital constraints at tier-one carriers favor operational expenditure models over instrument ownership. Cloud-native test architectures enable API-based orchestration for operators transitioning to software-defined validation, though legacy hardware resists integration.
- Government Agencies:National telecom laboratories in Germany, Japan, and the United States administer Open RAN security certification timelines that broaden protocol conformance testing scope. FDA electromagnetic compatibility standards for wireless medical devices create adjacent demand for specialized anechoic chamber configurations.
- Enterprises:Private network deployment and in-house equipment certification programs.
- Academic Institutions:Research programs and engineering curriculum support with limited procurement budgets.
Service Providers generate the highest absolute demand, while Government Agencies impose the most stringent qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test equipment procurement patterns diverge sharply by geography. South Korean carriers prioritize over-the-air validation systems for massive MIMO beamforming, while German and Japanese regulators drive protocol conformance expansion through Open RAN security mandates.
United States
FCC Part 27 spectrum rules and Open RAN interoperability mandates from national telecom laboratories are broadening test scope for disaggregated radio units. Tier-one carriers in the United States are unbundling hardware acquisition from software maintenance, pressuring vendors to defend recurring revenue through measurement-as-a-service platforms. Silicon Valley and Boston clusters concentrate 5G base station validation R&D.
Germany
ETSI EN 303 567 conformance standards and national telecom laboratory security certification timelines are expanding protocol conformance testing requirements. German defense and aerospace test programs require calibrated secure-facility supply chains with government-cleared personnel. Munich and Stuttgart industrial corridors anchor European test equipment demand.
Japan
MIIT radio transmission equipment type-approval requirements and METI-directed Open RAN interoperability mandates are fragmenting product development roadmaps. Japanese precision component suppliers concentrate supply of specialized RF front-end modules, creating input cost volatility for test equipment vendors. Tokyo and Osaka metropolitan areas drive fiber optic field test set procurement.
South Korea
National 5G spectrum auctions have accelerated base station rollout timelines, compressing procurement cycles for anechoic chamber integrators serving Samsung and LG Uplus deployment programs. Korean regulators administer expanded Open RAN security certification timelines at national telecom laboratories. Seoul Capital Area concentrates massive MIMO beamforming validation demand.
India
PLI scheme benefits for telecom equipment production are attracting test equipment vendors to establish local calibration and service capabilities. TRAI spectrum allocation frameworks and national 5G deployment targets are expanding test equipment procurement among emerging service providers. Maharashtra and Karnataka industrial corridors concentrate manufacturing investment.
Communication Test and Measurement (Ctandm) Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Communication Test and Measurement market. The upper tier commands premium positioning through specialized measurement libraries and calibrated supply chains, while mid-scale specialists compete on fiber optic field test sets and software-centric platforms. Two dominant competitive moves are reshaping positioning: strategic partnerships for cloud-native test architecture integration and geographic expansion into India through PLI-linked local calibration facilities.
Within the integrated measurement systems tier, Keysight Technologies and Rohde & Schwarz exemplify archetypes sustaining premium positioning through specialized intellectual property and secure-facility relationships. Anritsu occupies a position among Asia-Pacific-focused specialists competing aggressively in fiber optic instrumentation. These three companies represent the concentration of technical capability and customer access that defines competitive boundaries in 5G validation and submarine cable commissioning workflows.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu |
| Fortive |
| EXFO |
| VIAVI Solutions |
| Yokogawa |
| Spirent Communications |
| Tektronix |
| Others |
Supply Flow & Price Mechanics
Millimeter-wave measurement capacity utilization at Japanese and German precision component suppliers creates scale economies that simultaneously concentrate supply and elevate price floors for RF front-end modules. Cloud-native test architectures are compressing hardware margins while expanding after-sales service revenue pools, reshaping how vendors structure lifetime value capture across calibration and software maintenance contracts.
Pricing Analysis
After-sales revenue from calibration contracts and software maintenance drives lifetime value for test equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates Keysight's mmWave measurement libraries from mid-tier fiber optic field test sets and entry-level cable verification instruments. Price differentiation rests on certification grade for FCC Part 27 and ETSI EN 303 567 compliance plus geographic delivery cost for secure-facility supply chains. Cost compression in economy-tier benchtop instruments is intensifying because cloud-native platforms commoditize underlying hardware layers. Emerging service providers in India exhibit highest price sensitivity, while aerospace defense programs demonstrate lowest sensitivity due to mandated secure-facility requirements.
Supply Chain Analysis
Extended lead times for specialized RF front-end modules from Japanese precision component suppliers strain inventory buffers across anechoic chamber integrators. Supply concentrates in Japan, Germany, and the United States for millimeter-wave components, photodetector modules, and calibrated secure-facility infrastructure respectively. Raw material dependencies include precision-machined waveguide assemblies, high-purity optical fiber, and temperature-stable reference oscillators. Single-source vulnerability in Japanese RF front-end supply creates structural risk for vendors serving accelerated South Korean base station deployment timelines. Distribution runs through direct field service organizations for tier-one carriers and authorized calibration laboratories for government agency procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from software-centric test platforms that commoditize hardware layers through API-based orchestration. Defense of market positioning requires strategic consolidation around specialized measurement intellectual property and secure supply chain relationships.
For Market Incumbents: Consolidate around calibrated secure-facility supply chains with government-cleared personnel to anchor European and United States defense test program relationships. Deepen backward integration into precision RF front-end module design to reduce exposure to Japanese component supplier concentration. Prioritize measurement-as-a-service platform development to capture recurring revenue from tier-one carriers unbundling hardware acquisition from software maintenance.
For New Entrants and Emerging Players: Differentiate on AI-driven test automation for predictive fault detection in cellular base station deployment workflows. Target private 5G network deployment in industrial automation as the most penetrable application segment, where capital constraints favor operational expenditure models over instrument ownership. Pursue channel partnerships with anechoic chamber integrators serving accelerated South Korean rollout timelines as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with established calibration infrastructure and long-term service contracts at national telecom laboratories. Long-term viability favors companies with defensible measurement libraries and secure-facility relationships over hardware-centric competitors facing cloud-native commoditization. Acquisition target archetype: Asia-Pacific-focused fiber optic specialists with submarine cable commissioning relationships. Signal to watch: Open RAN security certification timeline expansion at German and Japanese national telecom laboratories as inflection indicator for protocol conformance testing scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Measurement-as-a-Service Platform Launch | Captures recurring revenue from tier-one carriers in South Korea and the United States favoring operational expenditure models. |
| Backward Integration into RF Front-End Design | Reduces input cost volatility from Japanese precision component supplier concentration for millimeter-wave modules. |
| Secure-Facility Calibration Expansion | Strengthens positioning in European defense test programs requiring government-cleared personnel and infrastructure. |
| AI-Driven Test Automation Development | Enables predictive fault detection in massive MIMO beamforming validation workflows for 5G standalone networks. |
| India Local Calibration Facility Establishment | Captures PLI scheme benefits for telecom equipment production and serves emerging service provider procurement. |
Methodological Framework
The analysis maps spectrum analyzers, network performance analyzers, signal generators, and fiber optic instrumentation, each validated through test equipment procurement managers at tier-one carriers and calibration service directors. Primary interviews with base station manufacturing engineers, national telecom laboratory certification leads, and defense program procurement officers combined with secondary validation from FCC Part 27 rulemaking dockets, ETSI EN 303 567 conformance documentation, and MIIT radio transmission equipment type-approval filings. Bottom-up instrument shipment tracking and top-down telecom capital expenditure analysis provided triangulation across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. The analytical framework modeled product type, technology generation, application vertical, and end-user procurement authority as core segmentation dimensions. CAGRs were derived from deployment timeline compression in South Korea, Open RAN mandate expansion in Germany and Japan, and cloud-native platform adoption curves. Industry-specific forecast inputs included national 5G spectrum auction schedules and submarine cable commissioning pipelines across Asia-Pacific littoral markets.
Material uncertainties — millimeter-wave component supply disruptions, Open RAN security certification timeline delays, and cloud-native platform adoption rate variance — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory mandate enforcement and carrier capital commitment levels. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Data Loggers Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Global Reference Thermometer Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
Global Data Acquisition (DAQ) System Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
Global Container Weighing Systems Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Communication Test Equipment (CTE) Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Moisture Meter Market