
 AI Powered Home Solution Market | 2026-2036
AI Powered Home Solution Market Size, Share, and Industry Trends Forecast 2026-2036
AI Powered Home Solution Market Outlook
Market Context
Edge AI silicon is realigning cost structures across home automation hardware by displacing cloud-dependent processing modules with on-device inference engines. Amazon.com, Inc. leverages its Alexa ecosystem to anchor voice-first home control across multiple appliance categories. Google LLC competes through Nest's deep integration with its Tensor chip architecture and ambient computing platform. Apple Inc. differentiates via its HomeKit Secure Video standard and privacy-centric local processing approach.
Technical Definition and Segment Structure
AI Powered Home Solutions encompass residential systems that deploy machine learning algorithms, computer vision, and natural language processing to automate climate control, security monitoring, lighting management, and appliance coordination through interconnected sensor networks and edge computing nodes. Natural Language Processing dominates current product roadmaps as voice interfaces become the primary human-machine interaction layer for homeowners, while Computer Vision segments in home security systems capture expanding margin pools through subscription-based AI analytics. DIY Installation categories accelerate fastest among renters seeking non-permanent smart home upgrades, though Professional Installation retains structural importance for new construction builds targeting property managers and institutional buyers.
Regulatory Environment
The EU AI Act classifies certain biometric home security applications as high-risk AI systems, mandating conformity assessments that reshape product development priorities for vendors targeting European homeowners. In the United States, FCC spectrum allocations for IoT devices and emerging FDA oversight of AI-enabled health monitoring home products create dual compliance pathways that influence market access strategies. Stakeholders must monitor evolving data localization requirements across jurisdictions as cloud-to-edge migration in home AI architectures triggers fragmented regulatory responses.
Market Dynamics
Edge AI silicon migration is compressing cloud dependency costs while fragmenting vendor control over home data pipelines. Residential property managers now demand localized inference to satisfy GDPR and EU AI Act mandates.
Growth Catalysts
- EU AI Act high-risk classification:Biometric security vendors face mandatory conformity assessments that favor established players with compliance infrastructure, accelerating consolidation among privacy-certified architecture providers.
- Natural Language Processing voice interfaces:Homeowners increasingly expect ambient conversational control across climate, lighting, and entertainment systems without dedicated hardware per function.
- Japan METI smart home standards:Interoperability mandates under the Society 5.0 framework reduce ecosystem lock-in friction and expand addressable hardware markets for cross-platform device manufacturers.
Market Restraints
- Edge AI chip supply concentration:Advanced inference silicon fabrication depends on Taiwan-based foundry capacity, exposing hardware vendors to geopolitical disruption risk and allocation constraints.
- GDPR data localization friction:Cross-border cloud processing for AI training datasets triggers regulatory review timelines that delay product launches in European markets by quarters.
- Lithium-ion battery cost volatility:Wireless sensor and camera backup power systems face input price instability that compresses hardware margin pools at the entry tier.
Strategic Opportunities
- Germany building renovation wave:Federal efficiency mandates for existing residential stock create retrofit demand for AI-integrated HVAC and energy management systems without new construction dependency.
- Matter protocol convergence:Thread and Wi-Fi unified connectivity standards collapse ecosystem fragmentation, enabling single-device SKUs to serve Apple, Amazon, and Google platforms simultaneously.
- India BIS smart device certification:Mandatory safety and interoperability testing creates first-mover advantage for vendors establishing local testing partnerships ahead of enforcement deadlines.
Industry Challenges
- Embedded systems ML engineering scarcity:On-device model optimization for ARM Cortex-M class silicon requires specialized firmware talent that commands premium compensation and extends development cycles.
- Legacy HVAC integration complexity:Proprietary control bus protocols in installed base equipment force custom gateway development per property, inflating professional installation costs and support burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Powered Home Solution Market |
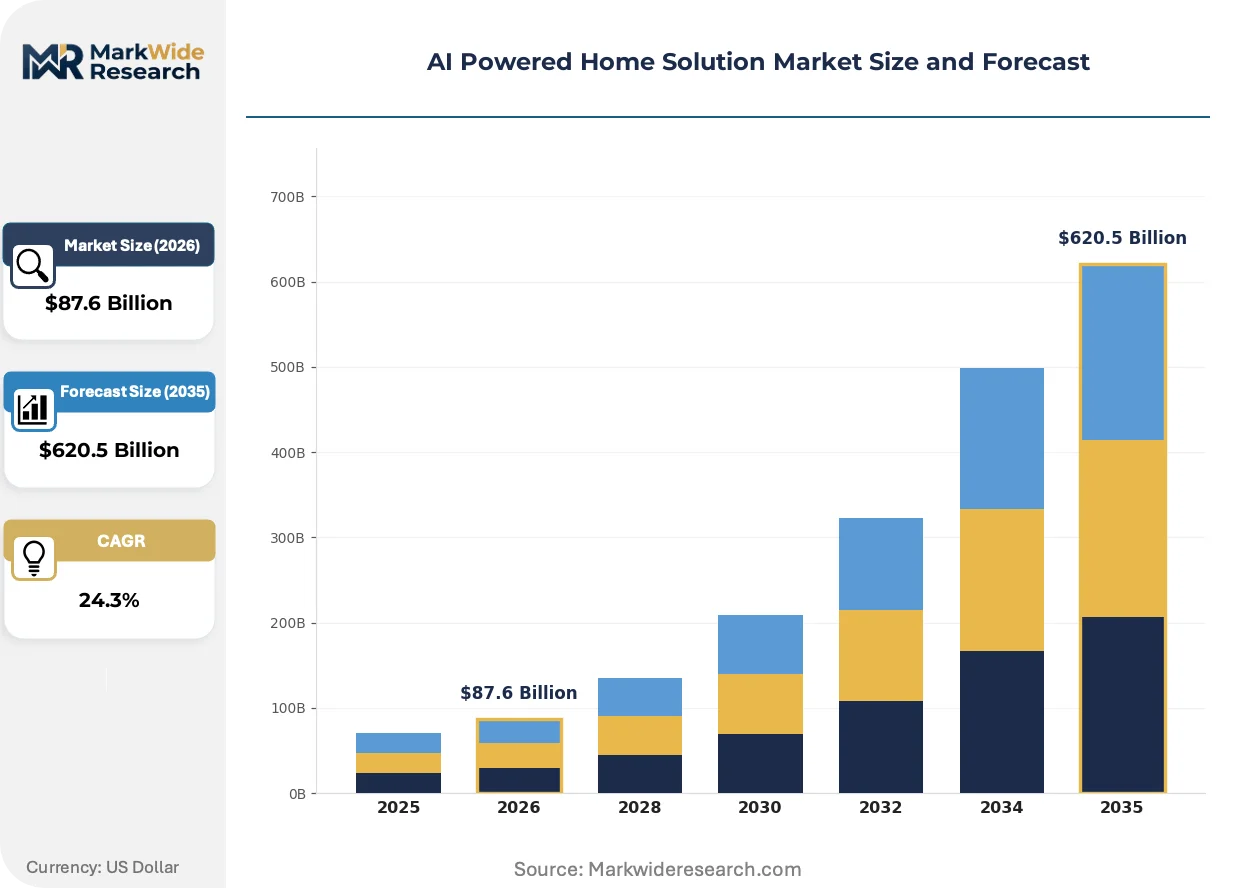
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $620.5 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Speakers, Home Security Systems, Thermostats, Lighting Controls Technology: Natural Language Processing, Machine Learning, Computer Vision, IoT Integration End User: Homeowners, Renters, Property Managers, Builders Installation Type: DIY, Professional, Retrofits, New Construction |
| Companies Covered | Amazon.com, Inc., Apple Inc., Google LLC, Samsung Electronics, Honeywell International Inc., Schneider Electric, Johnson Controls Inc., Siemens, ADT Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Powered Home Solution Market Strategic Shifts
Multimodal AI architectures are collapsing separate voice, vision, and sensor processing stacks into unified edge inference engines. This convergence compresses hardware BOM while enabling context-aware automation that single-modality systems cannot match.
Neural processing units with sub-watt power envelopes are electrifying battery-powered security camera design. Property managers deploying wireless perimeter systems now expect months of continuous computer vision analytics without wired power or frequent maintenance cycles. This capability is compressing total cost of ownership gaps versus PoE alternatives in retrofit scenarios.
The EU AI Act's high-risk system classification for biometric identification in residential settings is reshaping product roadmaps. Vendors targeting European homeowners must implement human oversight mechanisms and algorithmic transparency documentation that add development overhead. Computer vision segments are responding with privacy-preserving edge architectures that process facial data without cloud transmission.
Renters seeking non-permanent smart home upgrades are fragmenting traditional professional installation channels. DIY Installation categories now capture growing volume through retail partnerships and subscription-activated feature unlocking that monetizes over the device lifecycle rather than at point of sale. This behavior is most visible in United States urban markets with high tenant turnover and security deposit sensitivity.
AI Powered Home Solution Market Segmentation
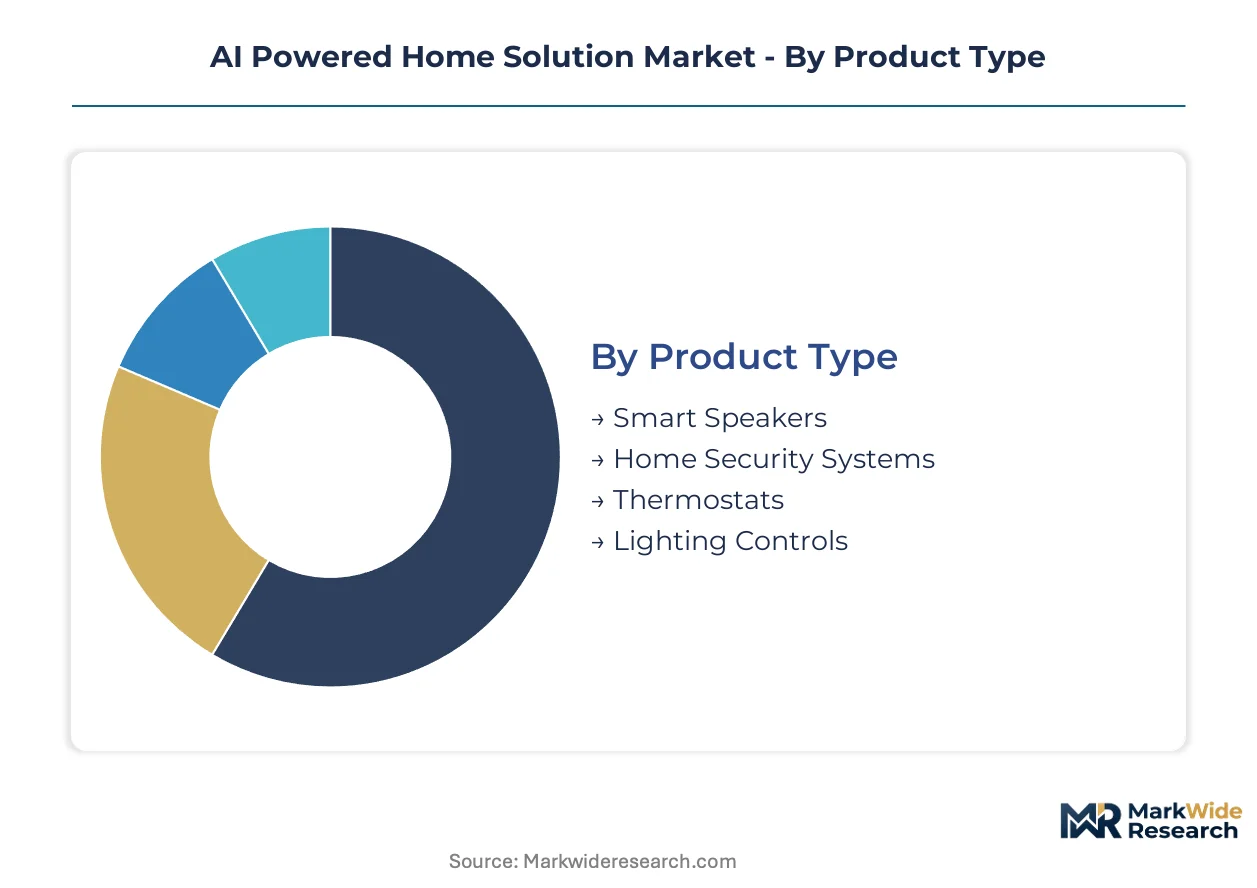
AI powered home solutions fragment across four critical dimensions that determine pricing architecture, channel strategy, and compliance burden. Product type and technology stack choices cascade into installation complexity and end-user economics.
Product Type:
Volume concentrates in entry-tier smart speakers while premium pools concentrate in integrated security systems with AI analytics subscriptions.
- Smart Speakers:Voice-first control hubs processing natural language commands through edge or cloud inference. Demand clusters in United States urban households seeking ambient home control without dedicated hardware proliferation. Amazon Alexa and Google Assistant ecosystems anchor this segment through retail channel dominance.
- Home Security Systems:Camera networks and sensor arrays deploying computer vision for intrusion detection and behavioral analytics. Property managers in Germany and Japan drive professional installation volume as GDPR and METI compliance requirements mandate localized data processing. Subscription monetization models capture recurring revenue streams.
- Thermostats:Climate control units with occupancy sensing and predictive energy optimization algorithms.
- Lighting Controls:Ambient and task lighting systems with circadian rhythm adaptation and presence-based automation.
Mature deployment sits with Thermostats. Newer deployment is concentrated in Home Security Systems.
Technology:
Natural Language Processing commands current R&D investment while Computer Vision captures expanding margin through subscription-tier feature unlocking.
- Natural Language Processing:Speech recognition and intent classification engines enabling conversational home control. United States homeowners expect cross-device command continuity that drives silicon vendors toward unified NLP accelerators. Edge migration reduces latency for command execution.
- Computer Vision:On-device image and video analysis for security, occupancy detection, and elderly care monitoring. EU AI Act high-risk classification for biometric applications forces architectural pivots toward privacy-preserving edge inference without cloud transmission. Vendors absorb conformity assessment costs.
- Machine Learning:Predictive models for energy optimization, appliance failure prediction, and behavioral pattern recognition.
- IoT Integration:Connectivity protocols and device mesh networking enabling cross-vendor interoperability.
Technology maturation is deepest in Machine Learning. Steepest expansion trajectory belongs to Computer Vision.
End User:
Homeowners dominate unit volume while Property Managers concentrate value through building-scale procurement and managed service contracts.
- Homeowners:Individual residents purchasing devices through retail channels or builder specifications. United States demand concentrates in suburban single-family dwellings with strong Wi-Fi infrastructure and disposable income for premium ecosystem integration. Voice control and mobile app management drive purchase decisions.
- Property Managers:Institutional operators of multi-unit residential buildings deploying centralized building management platforms. Germany's building renovation wave creates retrofit demand for AI-integrated HVAC and access control without new construction dependency. GDPR compliance mandates shape vendor selection criteria.
- Renters:Tenants seeking non-permanent smart home upgrades without structural modifications or landlord negotiations.
- Builders:New construction developers specifying pre-installed smart home infrastructure as competitive differentiation.
Established procurement patterns sit with Homeowners. Emerging volume is concentrating in Renters.
Installation Type:
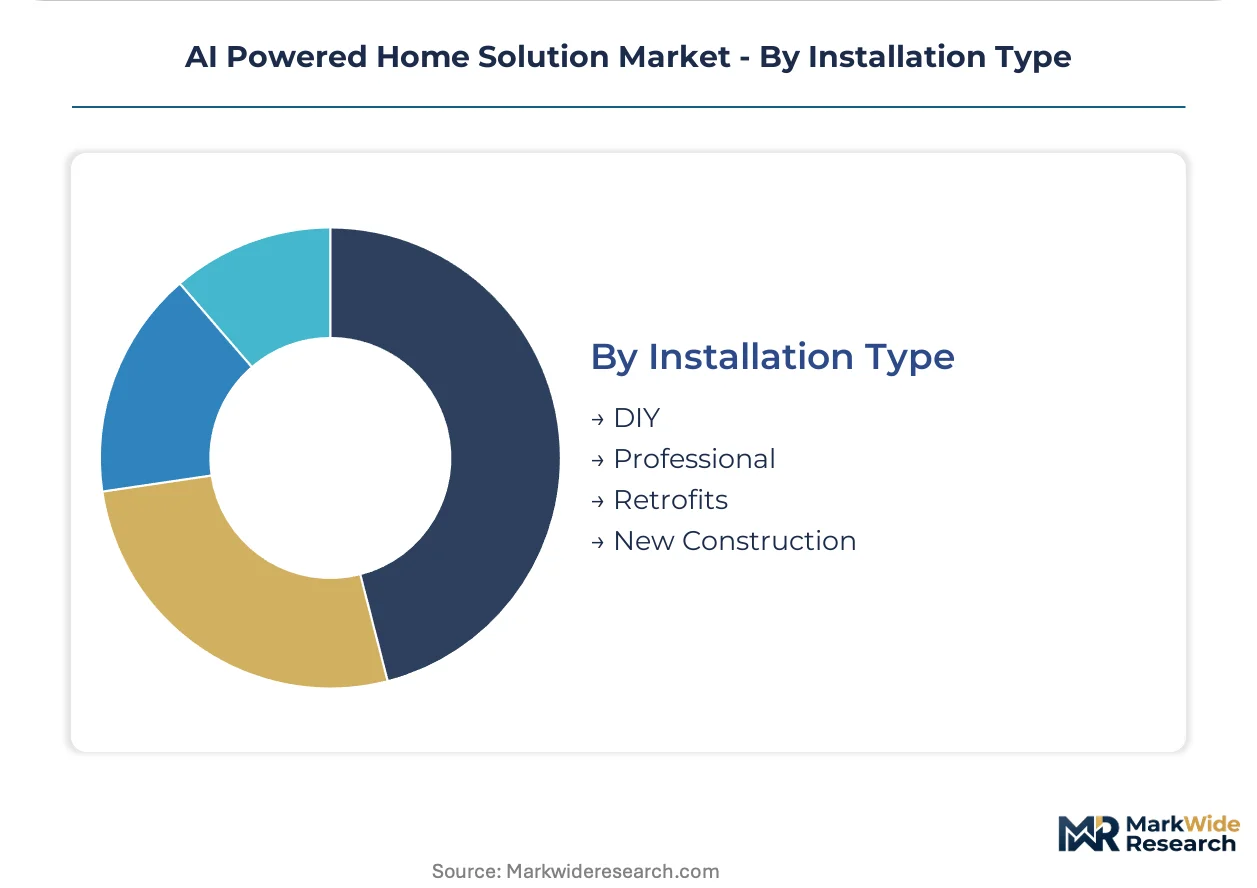
Professional installation retains structural importance for new construction while DIY channels accelerate fastest among cost-sensitive and mobile customer segments.
- DIY:Consumer self-installation through retail purchase with app-guided setup and subscription-activated feature unlocking. United States urban renters with high turnover rates and security deposit sensitivity drive volume through Amazon and Best Buy channels. Matter protocol convergence reduces ecosystem lock-in friction.
- Professional:Certified technician deployment for new construction builds and complex retrofit integrations. Builders in Japan target Society 5.0 compliance through METI-standardized interoperability. Custom gateway development for legacy HVAC bus protocols inflates project costs.
- Retrofits:Installation into existing residential stock without structural modification or electrical rewiring.
- New Construction:Pre-wired smart home infrastructure specified during architectural design and build phases.
Installation volume concentrates in Professional channels. Fastest share gain belongs to DIY.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential property managers in the United States, Germany, and Japan concentrate procurement of AI-driven building management platforms. Smart home infrastructure investments in these markets are accelerating as EU AI Act and GDPR compliance requirements reshape vendor selection criteria.
United States
FCC spectrum allocations for IoT devices enable dense sensor network deployment in suburban single-family dwellings. The IRA energy efficiency incentives accelerate thermostat and HVAC control upgrades. Silicon Valley and Seattle clusters anchor voice-first ecosystem development through Alexa and Nest engineering centers.
Germany
Federal building renovation mandates for existing residential stock create retrofit demand for AI-integrated energy management. The EU AI Act high-risk classification for biometric security forces architectural pivots toward privacy-preserving edge inference. Munich and Berlin engineering clusters concentrate conformity assessment expertise for GDPR-certified home automation architectures.
Japan
METI smart home standards under the Society 5.0 framework reduce ecosystem lock-in friction for cross-platform device manufacturers. Aging demographics drive computer vision adoption for elderly care monitoring in multi-generational households. Tokyo and Osaka metropolitan areas anchor interoperability testing and certification infrastructure.
United Kingdom
GDPR data localization requirements trigger regulatory review timelines that delay cloud-dependent product launches. London's property technology sector concentrates demand for professional installation channels in multi-unit residential buildings. Manchester and Birmingham emerging clusters focus on DIY retail distribution partnerships.
India
BIS smart device certification creates first-mover advantage for vendors establishing local testing partnerships. Rising disposable income in urban households drives voice interface adoption through affordable smart speaker categories. Bangalore and Hyderabad technology corridors concentrate firmware engineering talent for on-device ML optimization.
AI Powered Home Solution Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-anchored technology companies commanding premium positioning in voice and vision interfaces while industrial conglomerates dominate building-scale professional installations. The vendor base separates into three strategic archetypes: consumer technology platforms with retail channel dominance, industrial automation specialists with property manager relationships, and security-focused providers with subscription monetization expertise. Competitive moves concentrate on Matter protocol certification races and edge AI silicon partnerships that collapse ecosystem fragmentation.
Within the consumer technology platform tier, Amazon.com, Inc. and Apple Inc. represent contrasting architectural philosophies—cloud-dependent voice-first control versus privacy-centric local processing. Google LLC occupies a position between these approaches through its Tensor chip integration. Among industrial conglomerates, Siemens and Schneider Electric exemplify building-scale HVAC and energy management specialization for European property managers facing EU AI Act compliance mandates.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Apple Inc. |
| Google LLC |
| Samsung Electronics |
| Honeywell International Inc. |
| Schneider Electric |
| Johnson Controls Inc. |
| Siemens |
| ADT Inc. |
| Others |
Value Chain & Pricing Dynamics
Edge AI silicon fabrication costs cascade through hardware BOM structures, compressing margins at the entry tier while premium computer vision segments absorb chip premiums through subscription monetization. Lithium-ion battery volatility for wireless sensors and Taiwan foundry allocation constraints feed pricing tier stratification across DIY retail and professional installation channels.
Pricing Analysis
Volume concentrates in entry-tier smart speakers with thin hardware margins offset by ecosystem lock-in, while integrated security systems capture premium pools through recurring AI analytics subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates HomeKit Secure Video certification from uncertified alternatives from privacy-preserving edge inference. Cost compression in entry-tier wireless sensors is intensifying because lithium-ion battery input volatility and ARM Cortex-M silicon scarcity compress manufacturer margins. Renters in United States urban markets exhibit highest price sensitivity due to security deposit constraints and turnover frequency, while German property managers demonstrate lowest sensitivity given federal renovation mandate funding and compliance-driven procurement.
Supply Chain Analysis
GDPR and EU AI Act certification gating forces vendors toward privacy-certified component sourcing that fragments traditional procurement channels. Advanced inference silicon fabrication draws from Taiwan, South Korea, and United States foundry capacity, while lithium-ion cells for wireless backup power rest on China, South Korea, and Japan chemical processing. Single-source vulnerability concentrates in Taiwan-based TSMC advanced node allocation for neural processing units. Distribution runs through Amazon and Best Buy retail partnerships for DIY segments, alongside direct-to-builder specifications for new construction professional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into edge AI silicon design and captive cloud-to-edge data pipeline control is reshaping competitive positioning as vendors race to capture margin pools and compliance autonomy.
For Market Incumbents: Cement ecosystem dominance by acquiring ARM Cortex-M firmware engineering talent pools in Bangalore and Hyderabad to compress on-device ML optimization cycles. Deepen upstream control over Taiwan foundry allocation agreements to secure NPU supply against geopolitical disruption, while expanding Matter protocol certification breadth to collapse ecosystem fragmentation for property manager procurement. For New Entrants and Emerging Players: Begin with Germany's building renovation wave for AI-integrated HVAC retrofits, where federal efficiency mandates create demand without new construction dependency. Target India's BIS certification window ahead of enforcement deadlines through local testing partnerships in technology corridors. Pursue voice-first control hub positioning for affordable smart speaker tiers in urban Indian households with rising disposable income. For Investors and Strategic Acquirers: METI interoperability standard adoption velocity in Japan is the leading indicator that cross-platform device manufacturers will capture building-scale procurement from ecosystem-locked incumbents. Prioritize acquisition targets with edge AI silicon partnerships and GDPR conformity assessment infrastructure. Watch for EU AI Act high-risk system classification expansion beyond biometric security as the signal for privacy-preserving architecture premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Silicon Partnership | Secures Taiwan foundry allocation for neural processing units amid geopolitical supply risk. |
| GDPR Conformity Assessment Investment | Enables European market access under EU AI Act high-risk system mandates for biometric applications. |
| Matter Protocol Certification | Collapses ecosystem lock-in friction for single-SKU distribution across Amazon, Apple, and Google platforms. |
| Subscription Feature Unlocking Model | Monetizes DIY installation volume over device lifecycle rather than point-of-sale in United States urban renter markets. |
| India BIS Testing Partnership | Creates first-mover advantage ahead of mandatory smart device safety and interoperability enforcement deadlines. |
Study Parameters
Multi-period observation of FCC spectrum allocation timelines, EU AI Act implementation phases, and METI standard adoption curves anchored the trend analysis, supplemented by interviews with smart home platform engineers, residential property managers, semiconductor procurement leads, and BIS certification specialists. Secondary validation drew from SEC 10-K ecosystem revenue disclosures, hyperscaler smart home capex announcements, and customs records for edge AI silicon trade flows. Bottom-up device shipment modeling and top-down building automation spend estimates were triangulated to constrain forecast variance.
Input-output matrix framing mapped natural language processing and computer vision technology penetration against installation type economics and end-user procurement patterns across the analysis window. Segmentation dimensions included product type, technology stack, end-user archetype, and installation channel. CAGRs were derived from installed base growth rates and replacement cycle compression in retrofit scenarios, with edge AI silicon cost curves and GDPR compliance cost absorption as key forecast inputs.
Taiwan foundry allocation disruption, EU AI Act high-risk classification expansion, and lithium-ion battery commodity spikes are the dominant revision risks to hardware shipment and pricing assumptions. A model refresh is warranted upon material change in Matter protocol adoption velocity across major ecosystem platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Library Software Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Electronic Document Management System (EDMS) Market
Digital Solutions
Big Data Technology Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Europe ICT Market
Digital Solutions
Contact Tracing Application Market
Digital Solutions
Online Home Service Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Utility Bill Management System Market