
 Global E-Passport and E-Visa Market | 2026-2036
Global E-Passport and E-Visa Market Size, Share, and Industry Trends Forecast 2026-2036
Global E-Passport and E-Visa Market Foresight
Forensic document examiner staffing is collapsing across multiple national passport agencies, forcing governments to outsource biometric enrollment and personalization to specialized vendors. Thales Group leverages its semiconductor-to-system integration to capture turnkey e-passport contracts. IDEMIA anchors its position through dedicated security printing facilities on four continents. Vision-Box competes aggressively in automated border control gates, extending its hardware footprint into consular visa processing.
E-passports and e-visas constitute machine-readable travel documents embedded with secure integrated circuits that store biometric identifiers, cryptographic keys, and digital signatures per ICAO Doc 9303 standards; these systems authenticate traveler identity at issuance and verification points without persistent network connectivity. Biometric passports dominate procurement volumes due to ICAO mandate deadlines, while digital visa platforms represent the fastest-expanding margin pool as consulates abandon sticker-based workflows. Contactless chip technology leads hardware attachment rates, though NFC-enabled mobile visa credentials are gaining traction among airlines prioritizing seamless passenger processing.
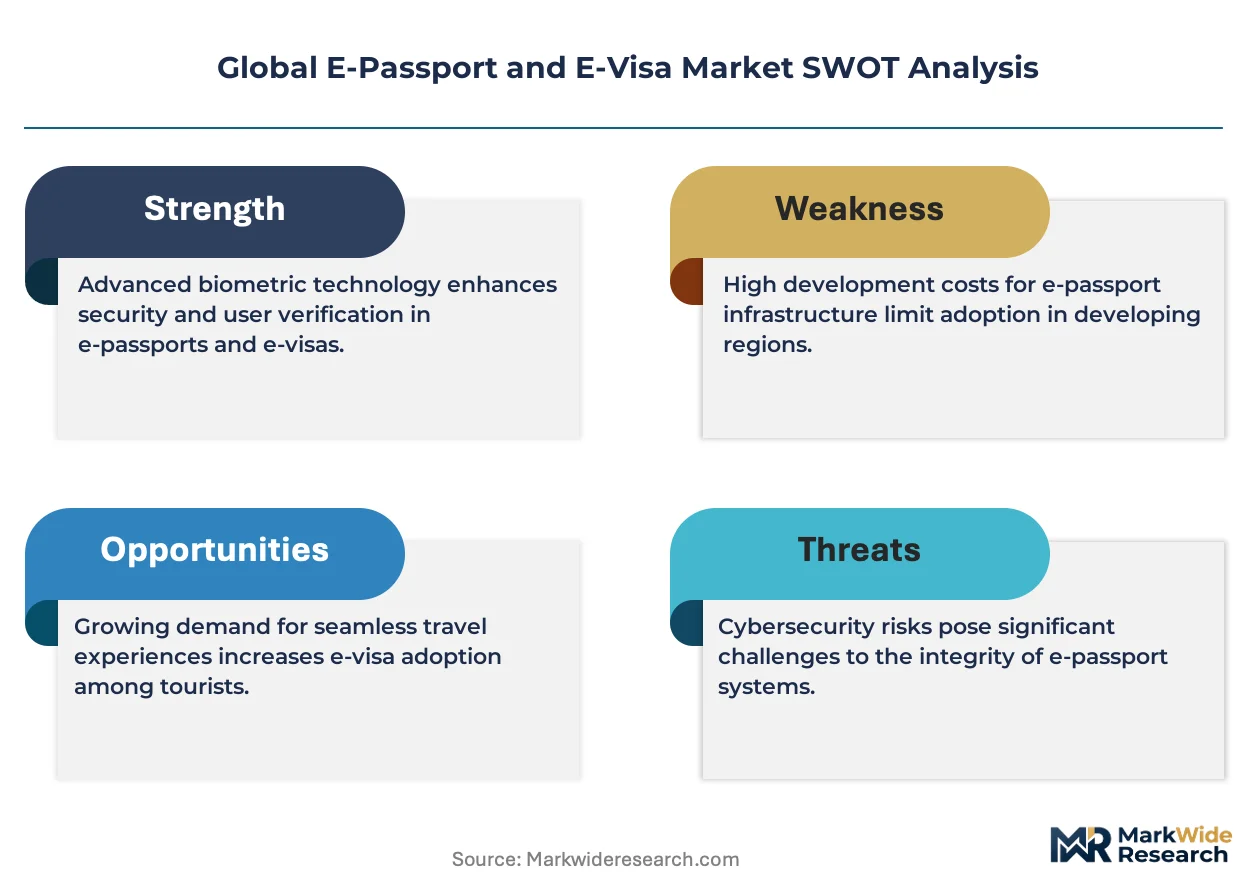
ICAO sets baseline cryptographic and data structure standards that all member states must implement for visa-free travel program eligibility, while the EU Entry/Exit System and US REAL ID Act impose additional biometric capture requirements that filter vendor participation. India's BIS certification and the EU's GDPR framework govern data handling protocols, constraining cloud-hosted visa architectures. Stakeholders must monitor which regulatory convergence patterns between identity issuance and border automation create captive procurement channels versus commoditized hardware supply.
Market Dynamics
Contactless chip architectures are forcing a wholesale requalification of e-passport vendors as ICAO Doc 9303 mandates phase out legacy contact-based interfaces, compressing procurement timelines and concentrating contract awards among semiconductor-to-system integrators.
Growth Catalysts
- EU Entry/Exit System mandates:Biometric capture requirements for third-country nationals are driving border infrastructure upgrades across Schengen states, expanding automated gate deployments at major airports.
- India:The country's national identity authority is modernizing passport issuance infrastructure to meet ICAO compliance deadlines, creating sustained demand for personalization bureaus and secure printing capacity.
- Mobile visa credentialing:Airlines are prioritizing NFC-enabled boarding workflows, accelerating consular adoption of digital visa platforms over traditional sticker-based processing.
Market Restraints
- Polysilicon supply concentration:Secure microcontroller fabrication depends on concentrated semiconductor foundry capacity in East Asia, exposing e-passport programs to single-source vulnerability.
- GDPR data localization:The EU framework constrains cloud-hosted visa architectures, forcing consulates to maintain expensive on-premise biometric storage infrastructure.
- Optical document verification:Forensic examiner staffing collapses across multiple national passport agencies, creating bottlenecks that delay personalization throughput regardless of equipment availability.
Strategic Opportunities
- Vietnam:The country's border modernization program remains underpenetrated by turnkey system vendors, offering first-mover positioning in automated gate and e-visa platform deployment.
- Blockchain-verifiable credentials:Convergence of distributed ledger technology with ICAO-compliant data structures creates pathways for self-sovereign travel identity pilots.
- Indonesia's visa liberalization:Policy expansion of electronic visa-on-arrival programs generates demand for integrated consular-border data exchange platforms.
Industry Challenges
- Cryptographic key management expertise:Forensic document examiners with PKI and secure chip personalization skills are exiting national agencies faster than training pipelines can replenish.
- Legacy system integration:Border control authorities face complex middleware requirements when connecting new contactless readers to decades-old watchlist databases.
- Common Criteria certification timelines:EAL4+ evaluation periods for secure operating systems now exceed 18 months, delaying program launches regardless of hardware readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global E-Passport and E-Visa Market |
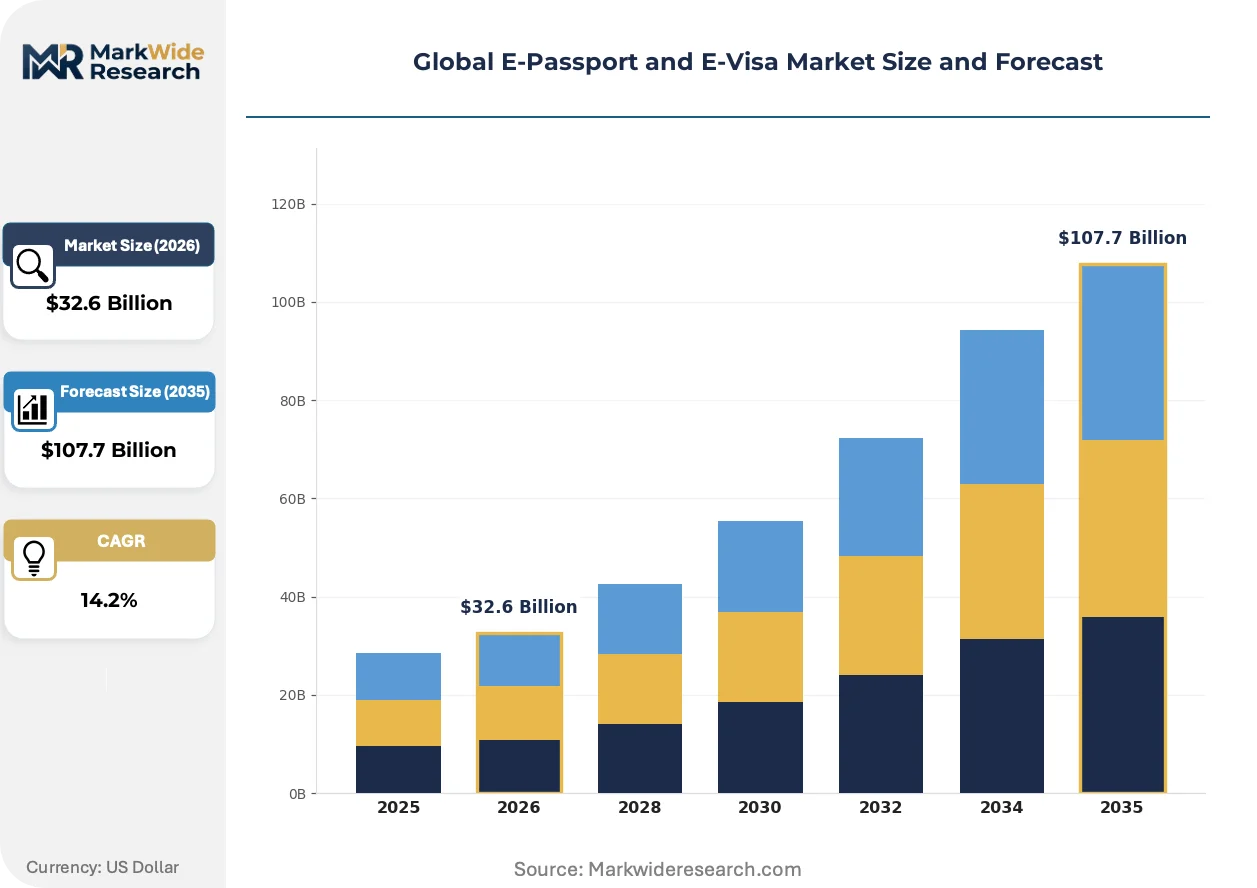
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $107.7 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Passports, Digital Visa, RFID Passports, Smartcard Visas Technology: Contactless Chip, Optical Scan, QR Code, NFC, Barcode Recognition Application: International Travel, Border Security, Customs Clearance, Immigration Control, Visa Management End User: Government Authorities, Customs Agencies, Airlines, Consulates, Immigration Services |
| Companies Covered | Veridos, Muhlbauer Group, Thales Group, Infineon Technologies AG, HID Global Corporation, IDEMIA, Vision-Box, Safran, Entrust Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global E-Passport and E-Visa Market Shifts & Advancements
Biometric authentication architectures are fragmenting across hardware, mobile, and cloud-native implementations, creating divergent vendor competency requirements that favor integrated platform providers over component specialists.
Polycarbonate data pages embedded with RFID inlays are supplanting traditional paper-laminate passport constructions as the default procurement specification. National printing authorities in Germany and France have mandated polycarbonate substrates for all new e-passport tenders. This material shift is compressing margins for security printers lacking in-house lamination and chip embedding capabilities.
REACH chemical restrictions are reshaping substrate and adhesive supply chains for European passport manufacturers. The regulation's Substances of Very High Concern list now captures several legacy optical security varnishes, forcing reformulation of holographic features. German and Dutch security printers are accelerating qualification of bio-based laminate alternatives to maintain CE marking compliance for export documents.
Airline-led consortiums are consolidating passenger identity verification around IATA One ID standards, displacing bilateral airline-government data sharing agreements. This behavioral shift concentrates negotiating power with carrier alliances rather than individual flag carriers. The transformation is most visible in Southeast Asia, where Singapore Changi and Bangkok Suvarnabhumi have aligned biometric boarding gate specifications to common vendor platforms.
Global E-Passport and E-Visa Market Segmentation
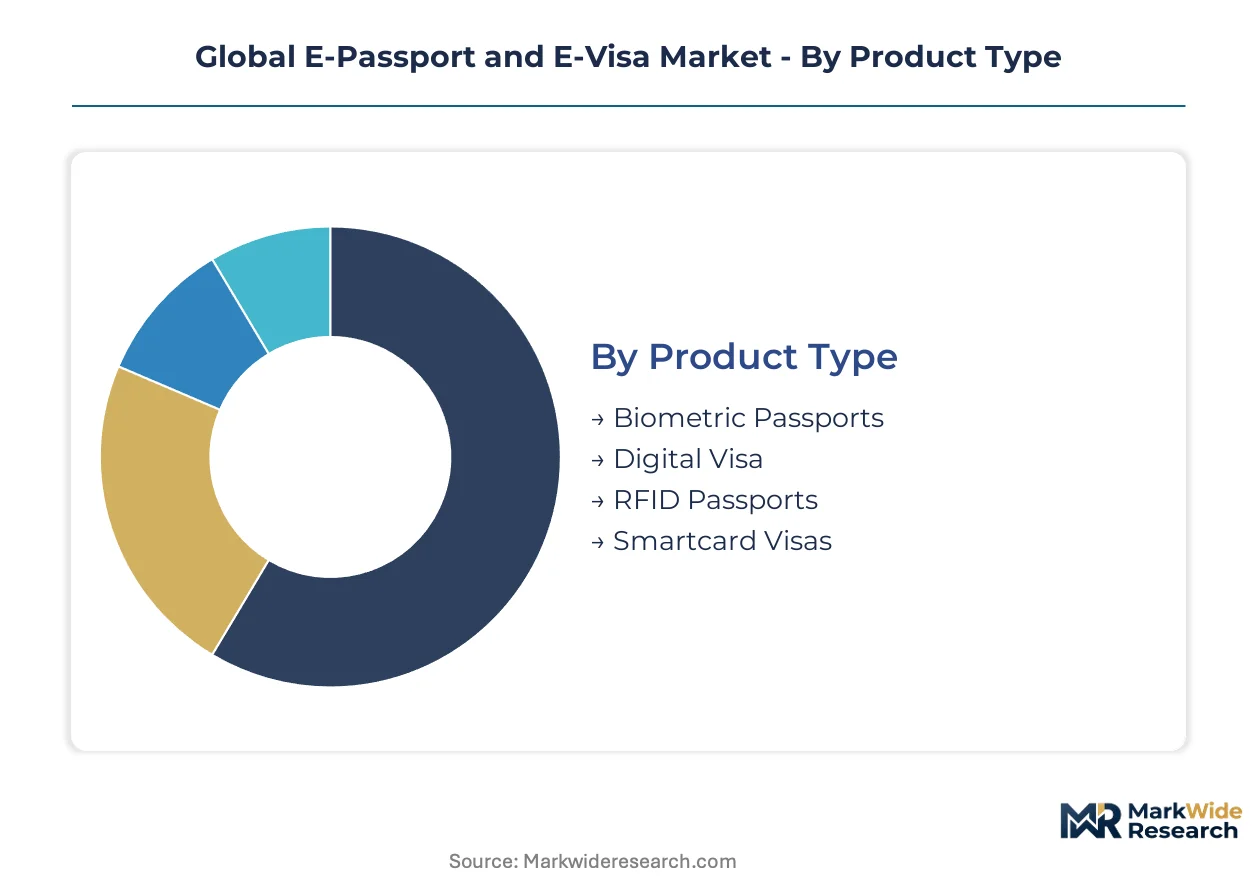
Segmentation in the Global E-Passport and E-Visa Market reveals how procurement authority and technical specifications diverge across issuance channels. Government buyers prioritize ICAO-compliant biometric architectures while airlines and consulates drive mobile credential adoption. Understanding these splits exposes where vendor specialization yields margin versus where integrated platforms capture volume.
Product Type:
Domestic procurement concentrates on biometric passports with embedded secure elements, while export-oriented demand flows toward modular digital visa platforms that consulates can deploy without hardware personalization infrastructure.
- Biometric Passports:Polycarbonate data pages integrate RFID inlays storing facial recognition templates and cryptographic keys per ICAO Doc 9303 standards. India's passport modernization program and Germany's federal printing authority drive concentrated demand for turnkey personalization bureaus with in-house lamination capabilities.
- Digital Visa:Cloud-hosted credentialing platforms enable stickerless visa issuance through API integration with airline reservation systems. Singapore's Immigration and Checkpoints Authority and UAE's Federal Authority for Identity and Citizenship are accelerating procurement of mobile-verifiable visa architectures.
- RFID Passports:Legacy contact-based chip implementations remain in circulation across states with extended ICAO compliance deadlines. Replacement cycles in Indonesia and Vietnam sustain residual demand for transitional hardware configurations.
- Smartcard Visas:Physical card formats with embedded secure microcontrollers serve long-stay visa categories requiring offline authentication. France's OFII and Canada's IRCC utilize these for work permit and permanent resident visa documentation.
Biometric passports command the established base. The steepest expansion runs through digital visa platforms.
Technology:
Cost tiering separates premium contactless implementations from commodity optical and barcode alternatives, with pricing stratifying across hardware-integrated, middleware-dependent, and software-only deployment models.
- Contactless Chip:ISO/IEC 14443-compliant RF interfaces enable tap-and-go authentication at automated border gates without physical document insertion. EU Entry/Exit System mandates across Schengen airports are forcing wholesale infrastructure replacement of legacy contact readers.
- NFC:Near-field communication protocols support smartphone-based credential verification for airline boarding and hotel check-in workflows. IATA One ID consortium specifications are standardizing NFC-enabled mobile travel credential acceptance across Southeast Asian hub airports.
- Optical Scan:Machine-readable zone verification remains the fallback authentication layer for degraded or damaged chip documents. Secondary inspection lanes at US CBP ports of entry and UK Border Force facilities retain optical verification as contingency infrastructure.
- QR Code:Two-dimensional barcode encoding supports temporary visa authorizations and transit permits with minimal issuance infrastructure. Turkey's e-Visa portal and Australia's ETA system leverage QR-based credentials for short-stay tourist categories.
- Barcode Recognition:Linear barcode formats persist in legacy visa stickers and emergency travel documents. Humanitarian visa programs administered by UNHCR and ICRC utilize barcode-based credentials where chip personalization capacity is unavailable.
Contactless chip technology anchors premium procurement budgets. NFC implementations are climbing the fastest as airline consortiums consolidate passenger processing standards.
Application:
Volume concentration tracks border infrastructure investment cycles, with international travel and immigration control consuming the bulk of credential issuance capacity while customs clearance represents an emerging automation frontier.
- International Travel:Machine-readable travel documents enabling visa-free program eligibility constitute the core issuance mandate for national passport authorities. Japan's Ministry of Foreign Affairs and South Korea's Ministry of Foreign Affairs prioritize biometric passport procurement to maintain US Visa Waiver Program and EU visa-free access.
- Immigration Control:Biometric enrollment and verification systems for resident permit issuance and status management require persistent identity registries. Italy's Questura and Spain's National Police Corps are modernizing immigration control platforms with centralized biometric repositories.
- Border Security:Automated gate deployments and watchlist screening infrastructure demand high-throughput authentication with sub-second response times. Poland's Border Guard and Hungary's National Police Headquarters are expanding automated gate corridors at Budapest Ferenc Liszt and Warsaw Chopin airports.
- Visa Management:Consular workflow automation spans application intake, biometric enrollment, adjudication support, and credential production. Brazil's Ministry of Foreign Affairs and Mexico's Secretariat of Foreign Relations are consolidating visa management onto integrated digital platforms.
- Customs Clearance:Traveler identity verification at customs checkpoints remains underpenetrated by biometric automation. Australia's Department of Home Affairs and New Zealand's Customs Service are piloting integrated passenger processing combining immigration and customs clearance into single biometric touchpoints.
International travel applications dominate issuance volumes. Customs clearance integration represents the fastest-climbing automation priority as border agencies pursue consolidated passenger processing.
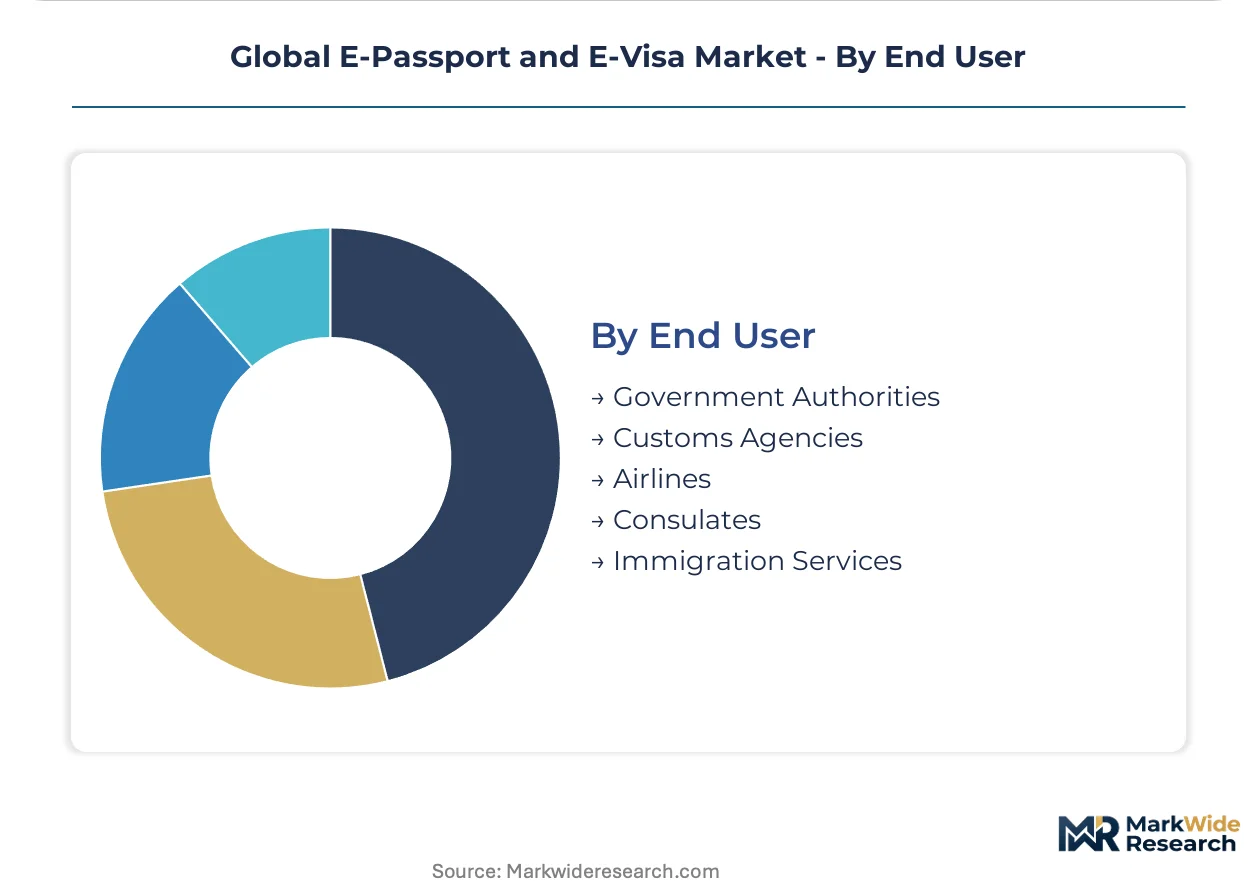
End User:
Customer type determines procurement authority fragmentation, with government authorities and immigration services controlling long-term credential contracts while airlines and consulates drive incremental platform adoption with shorter decision cycles.
- Government Authorities:National passport agencies and interior ministries issue ICAO-compliant travel documents with 5-10 year validity periods. The UK's HM Passport Office and France's National Agency for Food, Environmental and Occupational Health Safety govern procurement of secure personalization infrastructure with multi-year framework agreements.
- Consulates:Foreign ministry outposts require lightweight visa issuance platforms deployable without dedicated IT infrastructure. Italy's consular network in China and India's visa application centers in the UAE exemplify demand for centralized processing with distributed biometric enrollment.
- Customs Agencies:Border control authorities operate verification infrastructure at ports of entry with real-time watchlist connectivity. US CBP and UK Border Force procure automated gate hardware with middleware integration to legacy threat databases.
- Airlines:Carrier alliances drive passenger identity verification standards through IATA governance rather than bilateral government negotiation. Star Alliance and oneworld members at Frankfurt Airport and Heathrow Airport are aligning biometric boarding gate specifications to common vendor platforms.
- Immigration Services:Asylum and refugee processing agencies require credential issuance outside standard consular channels. Germany's Federal Office for Migration and Refugees and Sweden's Migration Agency utilize specialized enrollment workflows for protection visa categories.
Government authorities anchor the established procurement base. Airline consortiums are gaining share fastest as passenger processing standards consolidate around carrier-led specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification requirements anchor the Asia-Pacific procurement landscape, driving standardization across biometric travel document programs. Government modernization mandates in Delhi, Jakarta, and Hanoi concentrate contract awards among semiconductor-to-system integrators with turnkey personalization capabilities.
India
The Ministry of External Affairs is expanding passport issuance capacity to meet ICAO Doc 9303 compliance deadlines for visa-free program eligibility. BIS certification mandates constrain vendor qualification to domestic personalization bureaus with secure printing infrastructure. Hyderabad and Bengaluru host concentrated chip embedding and lamination facilities serving federal procurement frameworks.
Germany
The Federal Printing Authority mandates polycarbonate substrates for all new e-passport tenders, eliminating paper-laminate suppliers from qualification pools. REACH chemical restrictions force reformulation of holographic security varnishes among domestic security printers. Berlin and Munich anchor secure document personalization clusters with in-house semiconductor integration capabilities.
United States
CBP is deploying automated border gates with sub-second biometric response times at major international airports. The REAL ID Act imposes additional biometric capture requirements that filter vendor participation in federal credentialing programs. Washington Dulles and Atlanta Hartsfield-Jackson concentrate procurement of contactless reader infrastructure with legacy watchlist database connectivity.
Vietnam
The Immigration Department is modernizing border infrastructure with automated gate corridors at Noi Bai and Tan Son Nhat airports. National procurement frameworks favor turnkey system vendors capable of integrated consular-border data exchange. Ho Chi Minh City and Hanoi represent underpenetrated demand centers for e-visa platform deployment.
United Arab Emirates
The Federal Authority for Identity and Citizenship is accelerating mobile-verifiable visa architectures for airline-integrated passenger processing. MOHAP data governance frameworks constrain cloud-hosted biometric storage to on-premise infrastructure. Dubai International Airport anchors the Gulf's most concentrated automated gate deployment, with Abu Dhabi following on IATA One ID alignment.
Global E-Passport and E-Visa Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with semiconductor-to-system integrators capturing turnkey e-passport contracts while component suppliers compete on price for legacy chip replacements. The vendor base stratifies across three archetypes: secure document personalization bureaus with in-house lamination, automated border control hardware specialists, and cloud-native digital visa platform providers. Consolidation pressure runs through vertical integration into secure microcontroller supply and strategic partnerships with national printing authorities.
Among European-integrated leaders, Thales Group and IDEMIA exemplify the semiconductor-to-system archetype, occupying positions that span secure chip design through personalization bureau operation. Vision-Box represents the automated gate specialization vector, anchoring hardware deployment at major hub airports. Veridos and Entrust Corporation sit within the secure document tier, with geographic naming indicating German and North American origins respectively. These five entities collectively illustrate how vendor qualification requirements favor integrated platform providers over component specialists in premium procurement channels.
| Leading Market Players |
|---|
| Veridos |
| Muhlbauer Group |
| Thales Group |
| Infineon Technologies AG |
| HID Global Corporation |
| IDEMIA |
| Vision-Box |
| Safran |
| Entrust Corporation |
| Others |
Supply & Pricing Matrix
Long-term framework agreements between national passport authorities and turnkey system vendors lock in semiconductor supply access while capping unit pricing visibility across multi-year personalization bureau contracts. India's BIS certification requirements and Germany's Federal Printing Authority substrate mandates constrain vendor pools, concentrating pricing power among integrated providers with captive lamination and chip embedding capabilities.
Pricing Analysis
Price spreads between European and Asia-Pacific procurement markets reflect divergent certification burdens and local content requirements. Three-tier pricing structure across premium, standard, and economy levels separates turnkey personalization bureaus with in-house semiconductor integration from modular component suppliers and legacy optical-only vendors. Cost compression in standard-tier contactless chip modules is intensifying because polycarbonate substrate shortages are forcing security printers to absorb material escalations. Government authorities exhibit lowest price sensitivity due to ICAO compliance deadlines, while consular visa platforms face acute budget constraints from foreign ministry austerity mandates.
Supply Chain Analysis
East Asian foundry clusters in Taiwan and South Korea anchor secure microcontroller wafer fabrication for e-passport programs worldwide. Polysilicon feedstock, photoresist chemicals, and polycarbonate substrate resins constitute critical input dependencies with limited qualified alternative sources. Single-source vulnerability concentrates in advanced node semiconductor capacity below 40 nanometers, where Common Criteria EAL4+ certification requirements filter out second-tier foundries. Distribution runs through national printing authorities and designated personalization bureaus rather than open commercial channels, with turnkey vendors maintaining direct contractual relationships with interior ministries and passport agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as contactless chip mandates displace legacy contact-based architectures across remaining ICAO non-compliant jurisdictions. Mobile visa credentialing and automated border gate deployment represent penetration tailwinds with sustained runway.
For Market Incumbents: Compound defensive positioning through backward integration into secure microcontroller supply and captive polycarbonate lamination capacity. Cloud-native digital visa platforms from specialized software vendors threaten margin pools in consular automation; counter by acquiring API-first credentialing startups with airline system integrations. Certification investment in India's BIS framework and Germany's REACH-compliant substrate formulations secures framework agreement renewal priority. For New Entrants and Emerging Players: Post-issuance biometric verification services present a service-layer gap where incumbents under-serve with hardware-centric business models. Vietnam's Immigration Department and Indonesia's visa liberalization programs offer the most penetrable demand centers for turnkey e-visa platform deployment. Pursue consular workflow automation through software-only SaaS architectures that bypass capital-intensive personalization infrastructure requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automated border control hardware vendors with long-term maintenance contracts at major hub airports. Long-term viability favors semiconductor-to-system integrators with demonstrated ICAO compliance track records and multi-continental security printing footprints. Monitor IATA One ID consortium specification releases as the critical inflection signal for mobile credential adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Secure Microcontroller Backward Integration | Captive wafer supply insulates against East Asian foundry concentration risk for Thales and IDEMIA. |
| Polycarbonate Lamination Capacity Expansion | German and French security printers meet Federal Printing Authority substrate mandates while blocking paper-laminate competitors. |
| API-First Digital Visa Platform Launch | Cloud-native architectures enable Singapore ICA and UAE ICP to bypass hardware personalization infrastructure. |
| Automated Border Gate Hardware Deployment | Vision-Box and competitors capture EU Entry/Exit System upgrade cycles at Schengen hub airports. |
| Mobile Credential Consortium Partnership | IATA One ID alignment at Changi and Suvarnabhumi concentrates airline negotiating power with common vendor platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with passport agency procurement directors, consular IT modernization leads, automated border control hardware engineers, and secure document personalization bureau managers. Secondary validation drew from ICAO Doc 9303 implementation reports, EU Entry/Exit System regulatory filings, BIS certification registries, and national printing authority tender documentation. Bottom-up unit deployment estimates triangulated against top-down government budget appropriations for border infrastructure modernization.
Across the analysis window, volume and value outputs reflect segmentation modeling across product type, technology tier, application channel, and end-user procurement authority. CAGRs were derived from logistic diffusion curves fitted to ICAO compliance deadline schedules and national identity program modernization trajectories. Forecast inputs incorporated polycarbonate substrate supply constraints, Common Criteria certification queue lengths, and forensic examiner staffing trajectories at major passport agencies.
Underlying assumptions cover sustained government commitment to ICAO Doc 9303 compliance, stable semiconductor foundry capacity allocation for secure microcontrollers, and continued airline consortium prioritization of IATA One ID standards, with deviation risk concentrated in geopolitical disruption to East Asian wafer supply and GDPR enforcement actions against cloud-hosted biometric architectures. Recalibration cycles align with material shifts in ICAO specification releases, EU Entry/Exit System deployment milestones, and major national e-passport program tender awards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Digital Business Support System Market
Digital Solutions
India PLM Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Inventory Management Market
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Global Referral Management Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Data Integration Market
Digital Solutions
Mexico Online Gambling Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Europe Digital Pen Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
IPTV Market