

Residential Space Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Space Heater Market Insights
Heating appliance engineering talent is bifurcating between legacy combustion expertise and emerging electromechanical systems design, creating workforce gaps that slow product development cycles. Honeywell International leverages its controls heritage to dominate smart thermostat integration with connected heater platforms. Midea Group anchors high-volume manufacturing across ceramic and fan heater categories through vertically integrated component production. De'Longhi Appliances differentiates within European markets via design-led oil-filled and convection portfolios.
Residential space heaters convert electrical energy or combustible fuel into radiant, convective, or forced-air thermal output for localized warming of enclosed living spaces, typically rated between 400 and 1,500 watts for electric units with overheat protection and tip-switch safety mechanisms mandatory in most jurisdictions. The technology dimension shows electric heating commanding volume leadership while infrared systems capture premium positioning through zonal efficiency claims; ceramic heaters sustain the fastest expansion trajectory due to rapid heat-up performance and falling PTC element costs. Application concentration tilts toward indoor heating as primary revenue pool, though garage and basement segments attract specialized high-BTU gas and infrared units with margin profiles above standard room heaters.
US DOE efficiency standards and EPA indoor air quality guidelines constrain combustion heater specifications while pushing electric alternatives toward ENERGY STAR qualification thresholds. Europe's Ecodesign Directive and REACH chemical compliance add layer costs for imported units, effectively filtering non-compliant suppliers from shelf access. Stakeholders must monitor evolving minimum efficiency performance standards and carbon-border adjustment mechanisms to determine manufacturing location and product mix commitments.
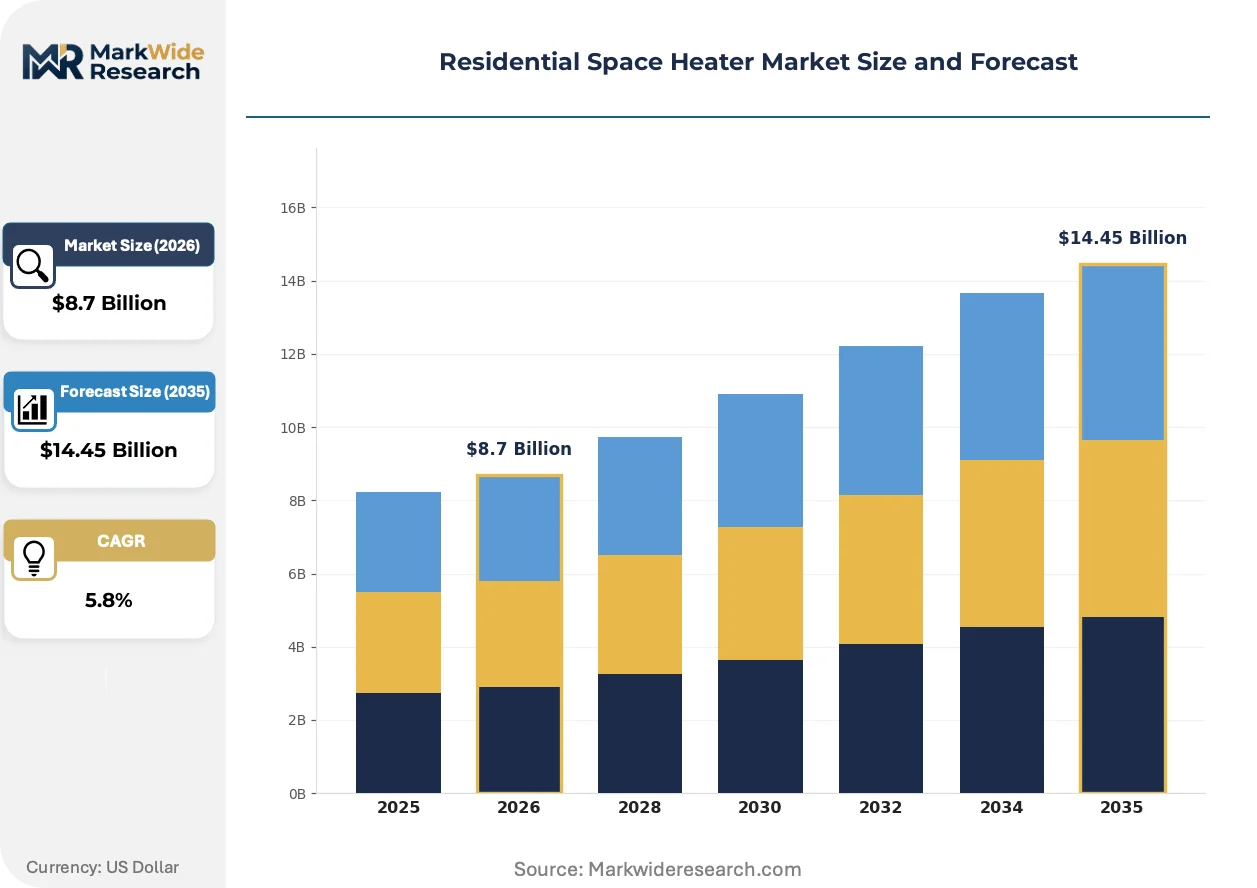
Market Dynamics
Energy efficiency mandates from the US Department of Energy and Europe's Ecodesign Directive are forcing manufacturers to redesign thermal output systems, compressing wattage ceilings while preserving heat delivery performance across electric and combustion platforms.
Growth Catalysts
- PTC ceramic element cost reduction:Falling prices for positive temperature coefficient heating components enable rapid heat-up functionality at mass-market price points, accelerating replacement of wire-coil resistive units in residential applications.
- Europe's Ecodesign Directive:Minimum efficiency performance standards for local space heaters mandate programmable controls and seasonal efficiency metrics, creating compliance-driven upgrade cycles across Germany, France, and Italy.
- Single-family homeowner segment:Aging housing stock in the United States and Germany generates sustained replacement demand for supplemental heating equipment as primary systems degrade and energy costs escalate.
Market Restraints
- Copper and aluminum input volatility:Heating element substrates and heat exchanger materials face commodity price swings that compress margin stability for manufacturers without captive metal sourcing.
- Combustion heater regulatory friction:EPA indoor air quality guidelines and state-level emissions restrictions constrain gas and kerosene unit specifications, limiting product line extensions in North American markets.
- Heat pump substitution threat:Ductless mini-split systems and whole-home electrification retrofits capture households seeking primary heating solutions, narrowing the addressable market for standalone space heaters.
Strategic Opportunities
- Smart thermostat convergence:Integration with connected home platforms enables demand-response participation and utility rebate capture, opening premium positioning beyond basic thermal output.
- Garage and basement specialization:High-BTU gas and infrared units for unfinished spaces command margin premiums above standard room heaters, with limited incumbent competition in this application niche.
- India's Bureau of Energy Efficiency standards:Emerging mandatory labeling for heating appliances creates first-mover advantage for compliant suppliers as electrification expands beyond urban cores.
Industry Challenges
- Electromechanical systems engineering scarcity:Workforce gaps between legacy combustion expertise and connected controls development slow product development cycles and firmware integration timelines.
- Multi-jurisdiction certification complexity:Overheat protection and tip-switch safety mechanisms require divergent testing protocols across UL, CE, and BIS frameworks, extending time-to-market for global product launches.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Space Heater Market Trends and Innovations
Product development trajectories center on thermal efficiency gains, embedded connectivity, and safety system miniaturization as manufacturers navigate tightening energy standards and elevated consumer expectations for smart home compatibility.
Infrared quartz and carbon fiber heating elements is supplanting conventional wire-coil resistive technology in premium residential segments. Single-family homeowners seeking zonal warmth without air circulation are adopting these systems at accelerating rates. This transition is compressing market share for forced-air ceramic units in living room and bedroom applications while opening margin expansion for radiant product lines.
Europe's F-Gas Regulation constrains refrigerant-based heating technologies and indirectly elevates electric resistance and infrared alternatives in regulatory standing. Manufacturers are reallocating R&D resources toward solid-state thermal solutions and away from heat pump adjunct systems. Germany's Federal Environment Agency enforcement actions are accelerating this portfolio pivot among exporters serving the EU market.
Direct-to-consumer channel expansion through utility rebate portals and home improvement retailer online platforms is fragmenting traditional wholesale distribution. Big-box retailers and electrical distributors are responding with private-label connected heater programs and installation service bundling. This pattern is most pronounced in the United States, where IRA home energy rebates create digital redemption pathways that bypass conventional contractor channels.
Residential Space Heater Market Segmentation
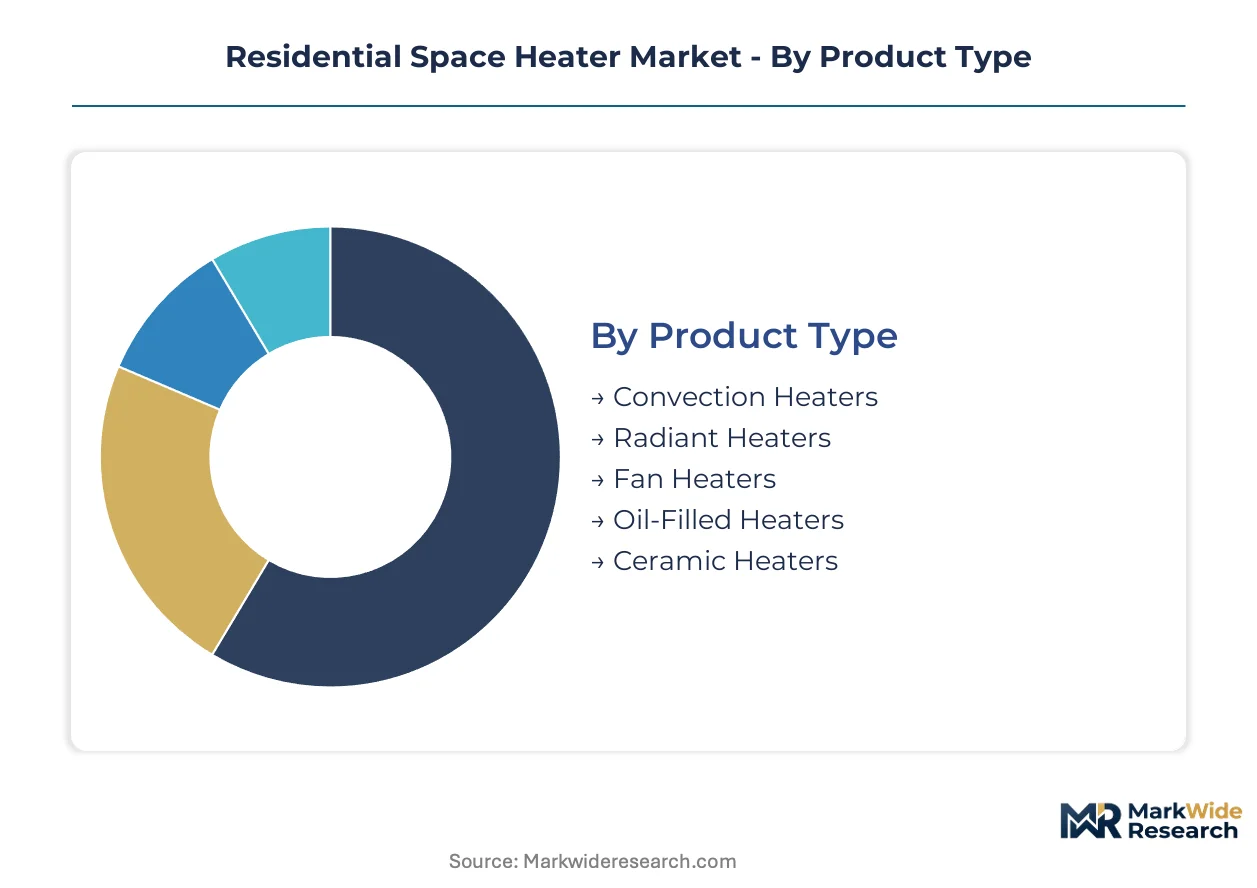
Segmentation in the residential space heater market reveals divergent margin structures across heating technologies and use cases. Product positioning strategies must account for regulatory compliance costs, installation complexity, and the shift toward connected home integration.
Product Type:
Margin pools concentrate in ceramic and infrared platforms where material cost reductions meet premium pricing power.
- Ceramic Heaters:PTC ceramic elements enable rapid thermal cycling with self-regulating temperature control. Demand concentrates in Germany and the United States where Ecodesign and DOE efficiency standards reward programmable units with lower standby losses.
- Radiant Heaters:Quartz and carbon fiber elements deliver directional infrared output without air circulation. Single-family homeowners in aging housing stock adopt these for zonal warming in living spaces where ductwork modifications prove cost-prohibitive.
- Convection Heaters:Natural air circulation through heated coils serves baseline residential needs across rental properties.
- Fan Heaters:Forced-air ceramic or wire-coil units dominate entry-level price points with rapid heat distribution.
- Oil-Filled Heaters:Thermal mass design provides extended radiant output with silent operation for bedroom applications.
The dominant share belongs to ceramic heaters, while radiant heaters are closing the gap fastest.
Technology:
Volume leadership sits with electric resistance platforms, though infrared systems command pricing premiums through efficiency claims.
- Electric Heating:Resistive wire and PTC ceramic elements convert grid electricity to thermal output with near-unity efficiency. Regulatory pressure from EPA indoor air quality guidelines and Europe's Ecodesign Directive accelerates displacement of combustion alternatives in Germany, France, and Italy.
- Infrared Heating:Solid-state quartz and carbon fiber emitters generate radiant warmth without heating intermediate air. Garage and basement applications in the United States favor high-BTU infrared units for unfinished spaces where forced-air distribution is impractical.
- Gas Heating:Propane and natural gas combustion serves off-grid locations with high thermal output density.
- Quartz Heating:Short-wave infrared elements provide instant radiant warmth with minimal thermal lag.
- Micathermic Heating:Mica substrate heating combines convection and radiant output in slim form factors.
Electric heating retains volume leadership, though infrared platforms are expanding most quickly into premium residential segments.
Application:
Revenue concentration skews toward indoor residential heating, though specialized outdoor and utility spaces sustain margin premiums.
- Indoor Heating:Living room, bedroom, and home office deployments constitute the core revenue pool for portable and fixed space heaters. Single-family homeowners facing rising utility rates in the United States and Germany drive replacement cycles for aging primary heating systems with supplemental electric units.
- Garage Heating:High-BTU gas and infrared units serve unfinished spaces with intermittent occupancy patterns. Limited incumbent competition in this niche supports margin structures above standard room heaters.
- Basement Heating:Moisture-resistant electric and gas units address below-grade thermal loads.
- Patio Heating:Outdoor radiant and propane towers extend seasonal use of residential outdoor spaces.
- Workshop Heating:Industrial-grade portable units serve DIY enthusiasts and small-scale craft operations.
Indoor heating commands the dominant revenue share, while garage heating is gaining share fastest through specialized product development.
Customer Type:
Purchasing authority and upgrade frequency vary sharply across owner-occupied and rental housing segments.
- Homeowners:Single-family owner-occupiers control equipment selection for primary residences with full capital authority. Aging housing stock in the United States and Germany generates sustained replacement demand as envelope degradation and primary system failures elevate supplemental heating needs.
- Rental Property Owners:Portfolio landlords and small-scale investors specify heating equipment for tenant-occupied units. IRA home energy rebates in the United States create digital redemption pathways that accelerate connected heater adoption through utility rebate portals.
- Property Managers:Multi-unit residential operators balance capital constraints with tenant comfort mandates.
- Renovators:Owner-occupiers undertaking systematic home improvements integrate space heaters during primary system upgrades.
- Tenants:Renter-purchased portable units represent a price-sensitive, low-loyalty segment with minimal service attachment.
Homeowners retain the dominant purchasing volume, while rental property owners are climbing the fastest as rebate programs lower acquisition barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential space heater consumption patterns diverge sharply between mature markets seeking efficiency upgrades and emerging economies prioritizing basic thermal access. Germany and the United States drive premium electric replacement cycles, while India and Southeast Asia concentrate on first-time electrification of heating infrastructure.
United States
Aging single-family housing stock and escalating utility rates propel supplemental heating demand across the Northeast and Midwest. The Department of Energy's appliance efficiency standards and IRA home energy rebates accelerate displacement of resistive wire-coil units with programmable ceramic systems. Chicago and Detroit metropolitan areas concentrate replacement activity where envelope degradation elevates secondary heating needs.
Germany
Europe's Ecodesign Directive and Federal Environment Agency enforcement reshape product specifications toward lower-wattage, higher-efficiency platforms. The country's aging building stock generates sustained demand for zonal warming solutions where ductwork modifications prove cost-prohibitive. Industrial clusters around Frankfurt and Stuttgart concentrate controls engineering talent for smart thermostat integration.
China
Rapid urbanization and rising disposable incomes expand addressable markets for portable heating appliances beyond traditional coal-dependent regions. The Bureau of Energy Efficiency's emerging labeling standards and MIIT industrial policy accelerate domestic manufacturing scale-up. Guangdong and Zhejiang provinces anchor high-volume production of PTC ceramic elements with falling unit costs.
India
Electrification expansion beyond urban cores and Bureau of Energy Efficiency mandatory labeling create compliance-driven upgrade pathways for heating appliances. Northern states facing winter temperature drops drive first-time adoption of electric resistance units. Maharashtra and Gujarat industrial corridors concentrate assembly operations for price-sensitive consumer segments.
Japan
Space-constrained residential architecture and METI energy conservation standards favor compact, high-efficiency heating solutions. Kanto and Kansai metropolitan areas concentrate demand for silent-operation oil-filled and micathermic systems. Aging population demographics elevate safety mechanism requirements including tip-switch and overheat protection specifications.
Residential Space Heater Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in residential space heater manufacturing. Controls-heritage conglomerates and vertically integrated appliance conglomerates occupy distinct competitive positions, while mid-scale specialists concentrate on design-led or application-specific segments. Strategic moves center on smart home platform integration and geographic manufacturing relocation to navigate carbon-border adjustment mechanisms and multi-jurisdiction certification complexity.
Among diversified controls and appliance conglomerates, Honeywell International and Midea Group exemplify contrasting scale archetypes. Honeywell leverages its North American heritage in thermostat and building automation systems to anchor connected heater platform development. Midea Group represents the vertically integrated volume manufacturer archetype, with in-house production of PTC ceramic elements and fan motor assemblies. De'Longhi Appliances occupies the European design-specialist position, with Italian heritage signaling premium positioning in oil-filled and convection portfolios. These three anchors illustrate how competitive positioning fragments across technology integration, manufacturing scale, and regional brand equity vectors.
| Leading Market Players |
|---|
| De'Longhi Appliances |
| Honeywell International |
| Dyson |
| Lasko Products |
| Vornado Air |
| Newell Brands |
| Midea Group |
| Rinnai |
| Stiebel Eltron |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day component lead times for PTC ceramic elements and microcontroller chips concentrate pricing power among vertically integrated manufacturers in China and Germany, while spot-market buyers face margin compression from aluminum and copper volatility. This inventory-to-pricing linkage shapes how OEMs negotiate long-term offtake versus project-based procurement across the residential heating value chain.
Pricing Analysis
Long-term offtake contracts dominate procurement for high-volume PTC ceramic elements and heat exchanger substrates, insulating tier-one manufacturers from spot aluminum volatility. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier differentiation—UL-listed and ENERGY STAR-qualified units command 15-25% premiums over baseline CE-marked products. Cost compression in economy wire-coil segments is intensifying because Chinese producers are flooding European markets with non-programmable units. Rental property owners and tenant-purchasers exhibit highest price sensitivity, while single-family homeowners prioritize efficiency ratings over upfront acquisition cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints at Ningbo and Shenzhen elevate inbound logistics costs for European and North American distributors sourcing finished heaters. Manufacturing concentrates in China, Germany, and Mexico—Guangdong province anchors PTC element and fan motor production, while German industrial clusters around Frankfurt supply control systems and safety mechanisms. Supply chains draw from copper wire, aluminum heat sinks, and ABS plastic housings. Single-source vulnerability in semiconductor-based thermostat controllers creates disruption risk. Distribution runs through big-box retailers, electrical distributors, and direct-to-consumer utility rebate portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical systems engineering talent gaps between legacy combustion expertise and connected controls development constrain product development velocity, creating asymmetric advantage for firms with captive firmware capabilities.
For Market Incumbents: Fortify smart thermostat integration capabilities through backward integration into sensor and control module production, defending against heat pump substitution threats from ductless mini-split manufacturers. Prioritize certification investment for ENERGY STAR and Ecodesign compliance to maintain shelf access in Germany and the United States as efficiency thresholds tighten. Channel control through utility rebate portal partnerships protects margin position against private-label entrants. For New Entrants and Emerging Players: Anchor in India's Bureau of Energy Efficiency labeling transition and Southeast Asia's first-time electrification corridors, where compliance-driven upgrade cycles favor agile suppliers over legacy incumbents. Garage and basement specialization offers the most penetrable application niche—high-BTU gas and infrared units command premium positioning with limited competition. Direct-to-consumer digital redemption pathways through IRA-aligned platforms bypass established wholesale relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance conglomerates seeking to divest non-core heating portfolios amid carbon-border adjustment uncertainty. Long-term viability hinges on electrification tailwinds and regulatory displacement of combustion alternatives. Signal to monitor: enforcement actions from Germany's Federal Environment Agency and EPA indoor air quality guideline revisions as inflection indicators for portfolio reallocation toward solid-state thermal solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Thermostat Platform Integration | Enables demand-response participation and utility rebate capture in IRA-aligned US markets. |
| Backward Integration into PTC Elements | Secures supply continuity and cost control as ceramic heating demand accelerates in Germany. |
| Ecodesign Compliance Certification | Maintains EU market access as seasonal efficiency mandates reshape product specifications. |
| Garage/Basement Product Line Extension | Captures margin premiums in underserved high-BTU unfinished space applications. |
| Direct-to-Consumer Channel Development | Bypasses wholesale intermediaries through utility rebate portal and home improvement retailer platforms. |
Research Methodology
Cross-validation between primary interviews with product development executives at heating appliance manufacturers and secondary analysis of US Department of Energy appliance efficiency filings anchors the qualitative findings. Conversations with procurement leads at big-box retailers, controls engineering directors, and regulatory affairs specialists at multi-jurisdiction exporters provided forward-looking demand signals. Secondary sources include EPA indoor air quality guideline documents, Ecodesign Directive implementing measures, Bureau of Energy Efficiency labeling notifications, and customs trade data for heating appliance imports. Bottom-up unit shipment estimates triangulate against top-down energy consumption projections across the analysis window.
Sensitivity analysis around PTC ceramic element cost trajectories and copper price scenarios shapes the forecast envelope. The analytical framework segments by heating technology, application use case, and customer purchasing authority across the projection horizon. CAGRs derive from regression against historical replacement cycles, housing stock age distributions, and regulatory compliance deadlines. Industry-specific inputs include Ecodesign seasonal efficiency metric adoption curves and IRA rebate redemption velocity through utility portals.
Material uncertainties—commodity price spikes, regulatory enforcement intensity variations, and heat pump substitution acceleration—sit outside the modeled envelope. Forecasts reflect assumptions about efficiency standard implementation timelines and electrification subsidy continuity. Practitioners should keep alternative scenarios live as carbon-border adjustment mechanisms and REACH chemical compliance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.