
 Refrigerated Cabinet Market | 2026-2036
Refrigerated Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Cabinet Market Outlook
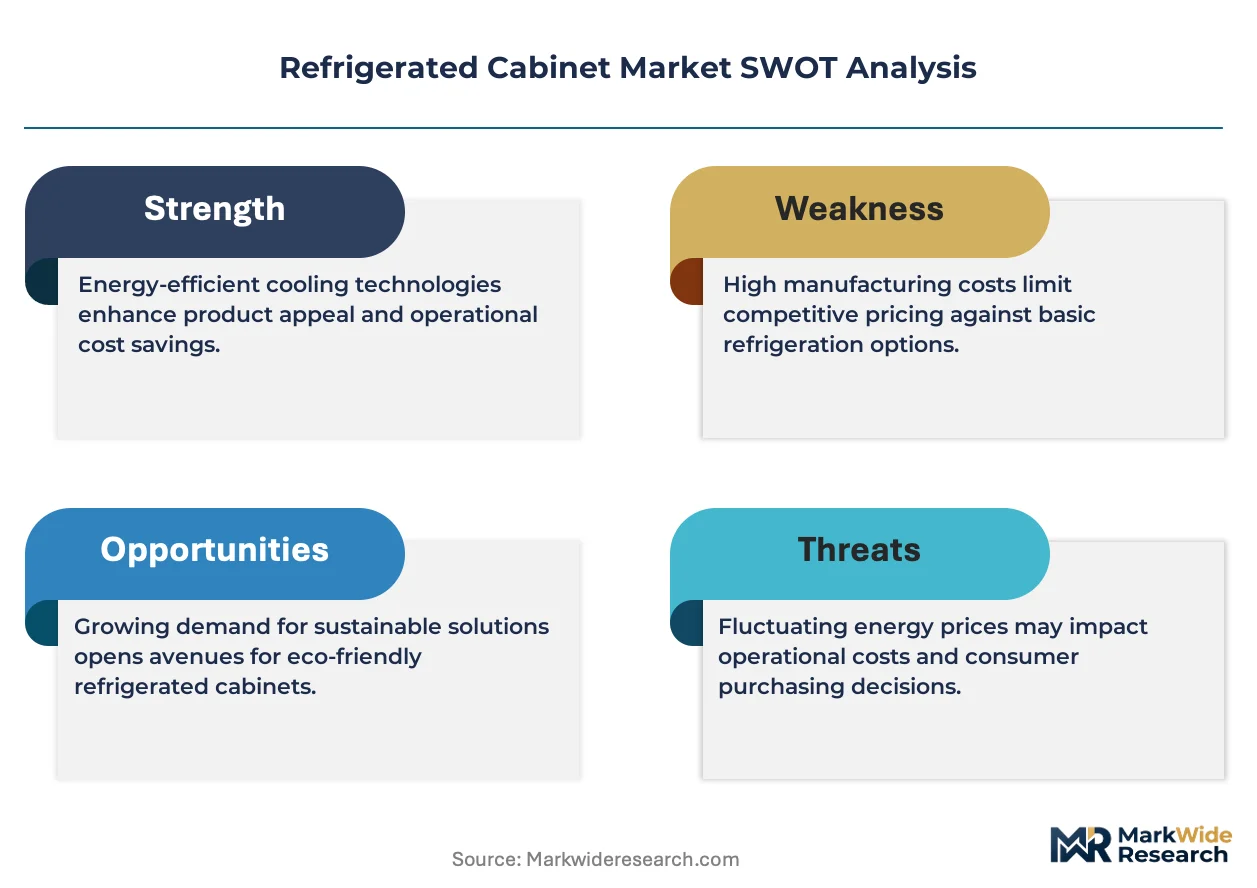
The EU F-Gas Regulation is consolidating demand for low-GWP refrigerated cabinet systems across European food retail chains. Carrier Global Corp. leverages its compressor technology leadership to sustain specification wins in supermarket retrofit programs. Daikin Industries Ltd. anchors its position through backward integration into refrigerant chemistry and controls engineering.
Refrigerated cabinets are insulated, temperature-controlled enclosures engineered to maintain precise thermal conditions between -25°C and +10°C for perishable goods storage and display. These systems employ polyurethane foam insulation, hermetic or semi-hermetic compressor circuits, and forced-air or gravity-coil heat exchange architectures to preserve food safety and extend shelf life. Glass door cabinets dominate replacement cycles in grocery stores where energy visibility drives purchasing decisions, while walk-in cabinets capture the highest margin pools in warehouse and distribution applications where custom sizing and remote monitoring integration command premium positioning. Thermoelectric systems remain niche but are gaining specification in small-format undercounter deployments where noise reduction and vibration-free operation outweigh efficiency trade-offs.
EPA SNAP rules in the United States restrict hydrofluorocarbon refrigerants in new commercial refrigeration equipment, while the EU F-Gas Regulation mandates phasedown quotas that reshape product roadmaps for manufacturers selling into Europe. BIS energy labeling requirements in India are tightening test protocols for imported cabinet systems, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor refrigerant transition timelines and certification reciprocity agreements to avoid stranded inventory in cross-border supply chains.
Market Dynamics
The refrigerated cabinet market is restructuring around refrigerant chemistry transitions mandated by the EU F-Gas Regulation and EPA SNAP rules, compressing product development cycles while expanding specification complexity for food retail chains and cold storage operators.
Growth Catalysts
- Natural refrigerant mandates:The EU F-Gas Regulation's phasedown quotas are forcing supermarket retrofit programs across Germany, France, and Italy, pulling forward replacement demand for CO₂ and hydrocarbon-based systems.
- Cold storage expansion:Food processing facilities in the United States and Brazil are adding capacity to buffer supply chain volatility, driving walk-in cabinet specifications with integrated remote monitoring.
- Energy labeling tightening:India's BIS requirements are raising performance floors for imported equipment, creating specification windows for domestic manufacturers with certified test protocols.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger materials face price swings that compress margin pools for mid-tier cabinet producers without captive metal sourcing.
- Compressor supply concentration:Semi-hermetic compressor production clusters in Germany and Japan, exposing buyers to lead time extensions during capacity constraints.
- Thermoelectric efficiency ceiling:Peltier systems remain confined to undercounter niches where cooling load demands stay below 500W, blocking penetration into full-size vertical cabinets.
Strategic Opportunities
- Small-format retail underpenetration:Convenience stores in Southeast Asia lack standardized cold chain infrastructure, creating specification openings for compact plug-in cabinets with modular shelving.
- Pharmaceutical cold chain extension:Vaccine distribution networks require validated temperature logging, merging refrigerated cabinet specifications with data integrity requirements from FDA 21 CFR Part 11.
- Service unbundling:Predictive maintenance contracts are separating from hardware sales, allowing controls specialists to capture recurring revenue streams independent of cabinet OEMs.
Industry Challenges
- Refrigerant handling certification gaps:CO₂ transcritical systems require pressure-qualified technicians that remain scarce in secondary cities across the United States and Southern Europe.
- Legacy control integration friction:Smart cabinet retrofits must interface with existing building management systems using proprietary protocols from 1990s-era installations.
- Test protocol reciprocity delays:Certification bodies in India and Brazil lack mutual recognition agreements with EU notified bodies, extending product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Cabinet Market |
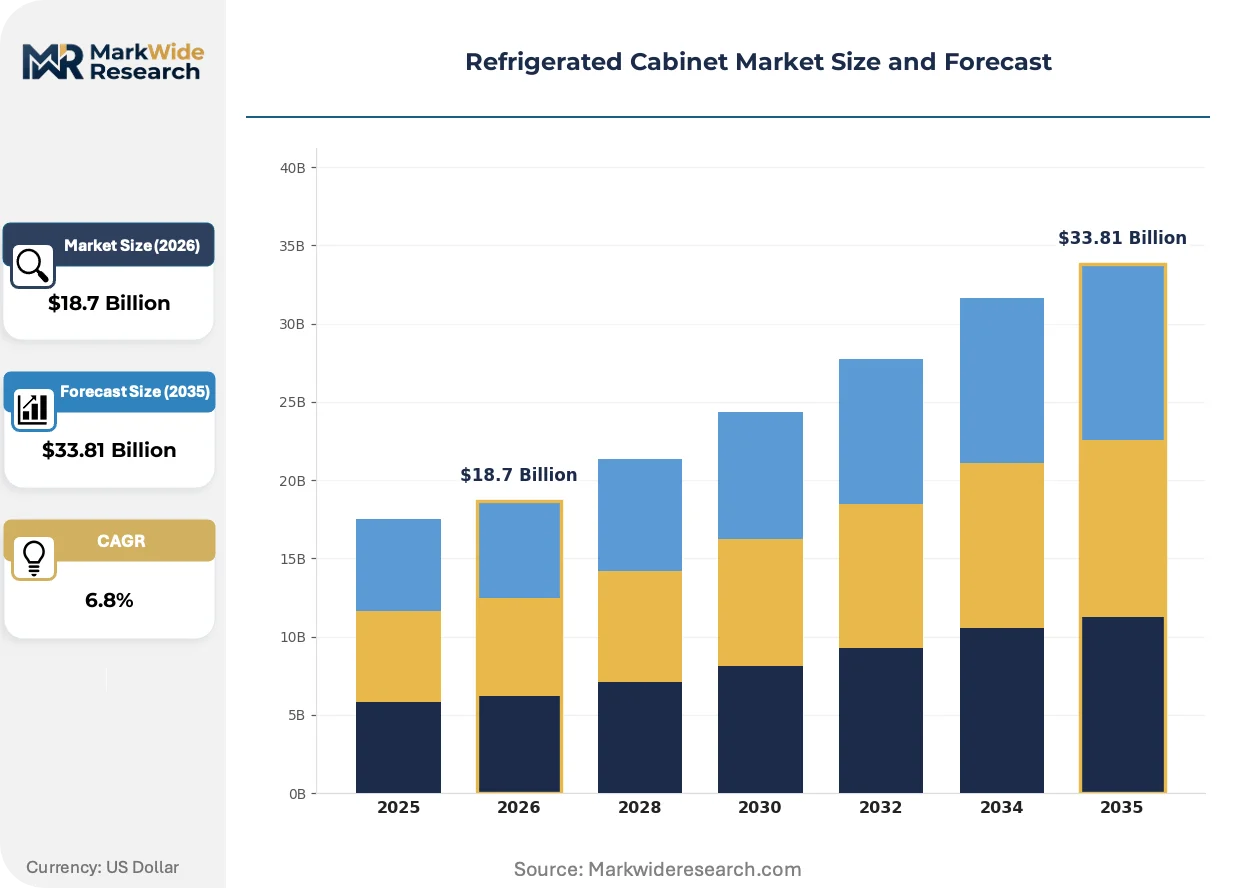
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Door Cabinets, Reach-in Cabinets, Undercounter Cabinets, Walk-in Cabinets End User: Restaurants, Grocery Stores, Warehouses, Food Processing Facilities Technology: Refrigeration Compressors, Thermoelectric Systems, Variable Frequency Drive, Eco-Friendly Solutions Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | Carrier Global Corp., Daikin Industries Ltd., Haier Smart Home Co. Ltd., Liebherr International AG, Panasonic Holdings Corp., Ali Group S.r.l., HOSHIZAKI Corp., Dover Corp., Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Cabinet Market Strategic Shifts
Refrigerated cabinet engineering is converging around three vectors: refrigerant chemistry substitution, embedded intelligence for energy optimization, and procurement model restructuring that separates hardware ownership from thermal performance outcomes.
Variable-speed compressor technology is integrating with adaptive defrost algorithms to cut energy consumption in glass-door vertical cabinets by modulating cooling output against real-time load conditions. German supermarket chains are specifying these systems in retrofit programs to meet EU Green Deal reporting requirements. The technology is integrating predictive failure detection that compresses unplanned downtime costs for 24-hour retail formats.
The EPA SNAP program's final rule on HFC refrigerants is prohibiting R-404A and R-507A in new commercial refrigeration equipment, forcing manufacturers to validate alternative chemistries across expanded temperature ranges. This regulatory pressure is accelerating R-290 (propane) system development for self-contained units under 150g charge limits. Small-format grocery operators in California and New York are absorbing first-mover compliance costs to avoid stranded asset risk.
Leasing structures for refrigerated assets are displacing outright purchase in foodservice channels, transferring efficiency risk from restaurant operators to equipment financiers. Contract terms now tie payment obligations to measured energy performance against baseline guarantees. This model is concentrating in the United Kingdom and Netherlands where energy price volatility has made operational cost certainty a priority procurement criterion.
Refrigerated Cabinet Market Segmentation
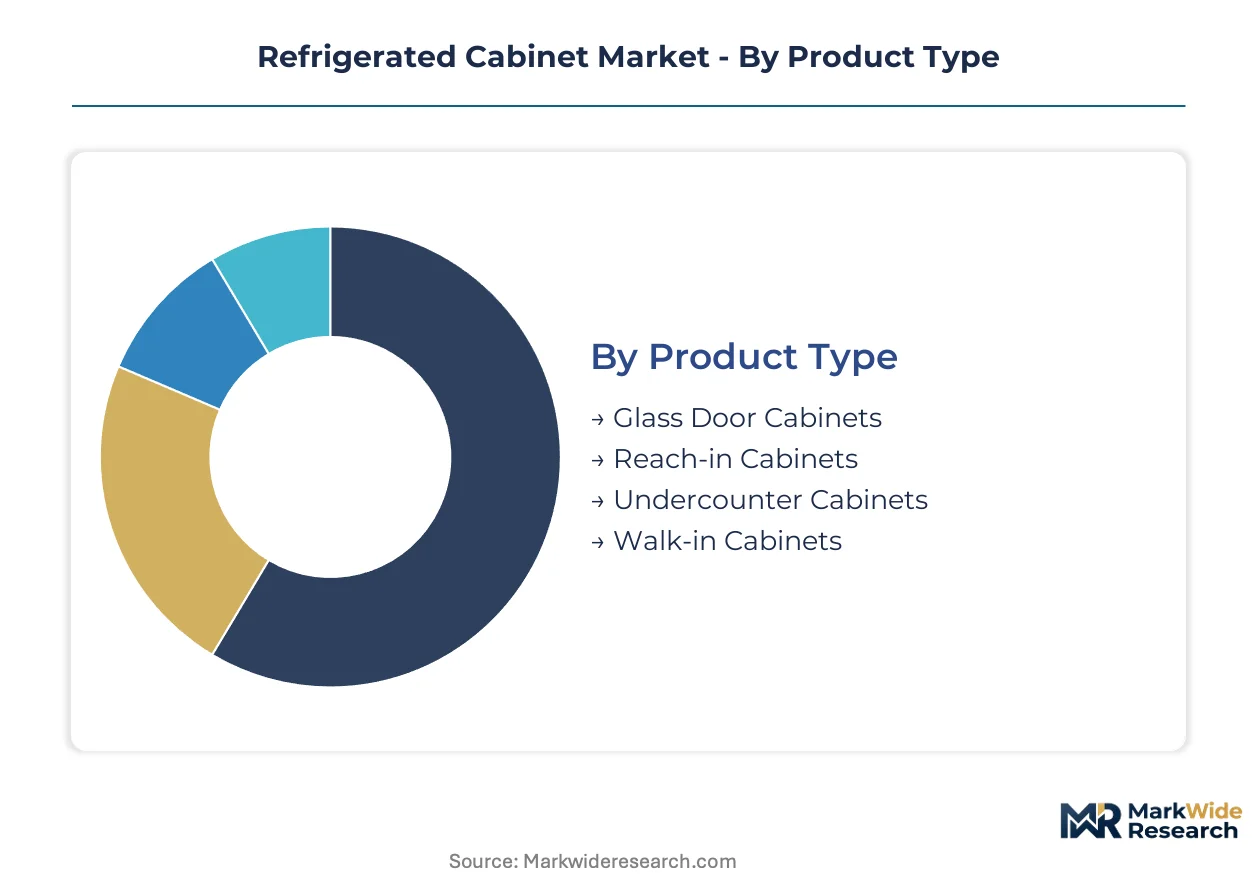
Refrigerated cabinet segmentation reveals how replacement cycles, regulatory mandates, and operational requirements fragment demand across equipment categories. Understanding these divisions exposes where specification power concentrates and which technology transitions will reshape procurement patterns.
Product Type:
Upgrade cycles vary dramatically by enclosure architecture, with energy visibility and custom engineering demands driving divergent replacement timelines and margin structures.
- Glass Door Cabinets:Vertical display units with double-glazed argon-filled panels and LED illumination dominate supermarket retrofit programs. German food retail chains specify these systems to meet EU Green Deal reporting requirements while maintaining product visibility. Energy labeling visibility pulls replacement demand forward in France and Italy.
- Walk-in Cabinets:Modular insulated enclosures with remote compressor racks capture premium positioning in cold storage expansion. Food processing facilities in Brazil and the United States specify these for supply chain buffering capacity, with integrated monitoring commanding price premiums.
- Reach-in Cabinets:Solid-door units with forced-air circulation serve high-turnover foodservice operations.
- Undercounter Cabinets:Compact worktop-integrated systems fit space-constrained kitchen layouts.
Glass Door Cabinets sits at the top of the volume ranking, with Walk-in Cabinets climbing the fastest.
End User:
Operational scale and regulatory exposure segment demand by facility type, with cold chain reliability requirements and energy cost structures determining specification priorities.
- Grocery Stores:Multi-zone display requirements and 24-hour operational demands drive specification complexity. EPA SNAP compliance deadlines in California and New York accelerate retrofit investment, with natural refrigerant systems absorbing first-mover premiums.
- Food Processing Facilities:Large-scale buffer storage and batch processing workflows require validated temperature uniformity. Expansion in the United States and Brazil pulls walk-in cabinet demand with remote monitoring integration.
- Restaurants:Space constraints and noise sensitivity prioritize compact undercounter and reach-in formats.
- Warehouses:Distribution consolidation drives demand for high-capacity modular systems with fleet management compatibility.
Grocery Stores commands the largest installed base, though Food Processing Facilities is expanding most quickly.
Technology:
Refrigerant chemistry transitions and control intelligence are restructuring technology adoption curves, with regulatory deadlines compressing validation timelines for alternative systems.
- Eco-Friendly Solutions:CO₂ transcritical and hydrocarbon-based systems face EU F-Gas Regulation phasedown quotas. German supermarket retrofit programs validate these technologies across expanded temperature ranges, with pressure-qualified technician scarcity creating installation bottlenecks in Southern Europe.
- Variable Frequency Drive:Adaptive compressor modulation integrates with predictive defrost algorithms. German chains specify these for energy reporting compliance, with failure detection capabilities reducing downtime costs.
- Refrigeration Compressors:Hermetic and semi-hermetic circuits remain the baseline for most commercial applications.
- Thermoelectric Systems:Peltier cooling stays confined to sub-500W undercounter niches where vibration-free operation outweighs efficiency penalties.
Refrigeration Compressors maintains volume leadership, while Eco-Friendly Solutions gains share fastest.
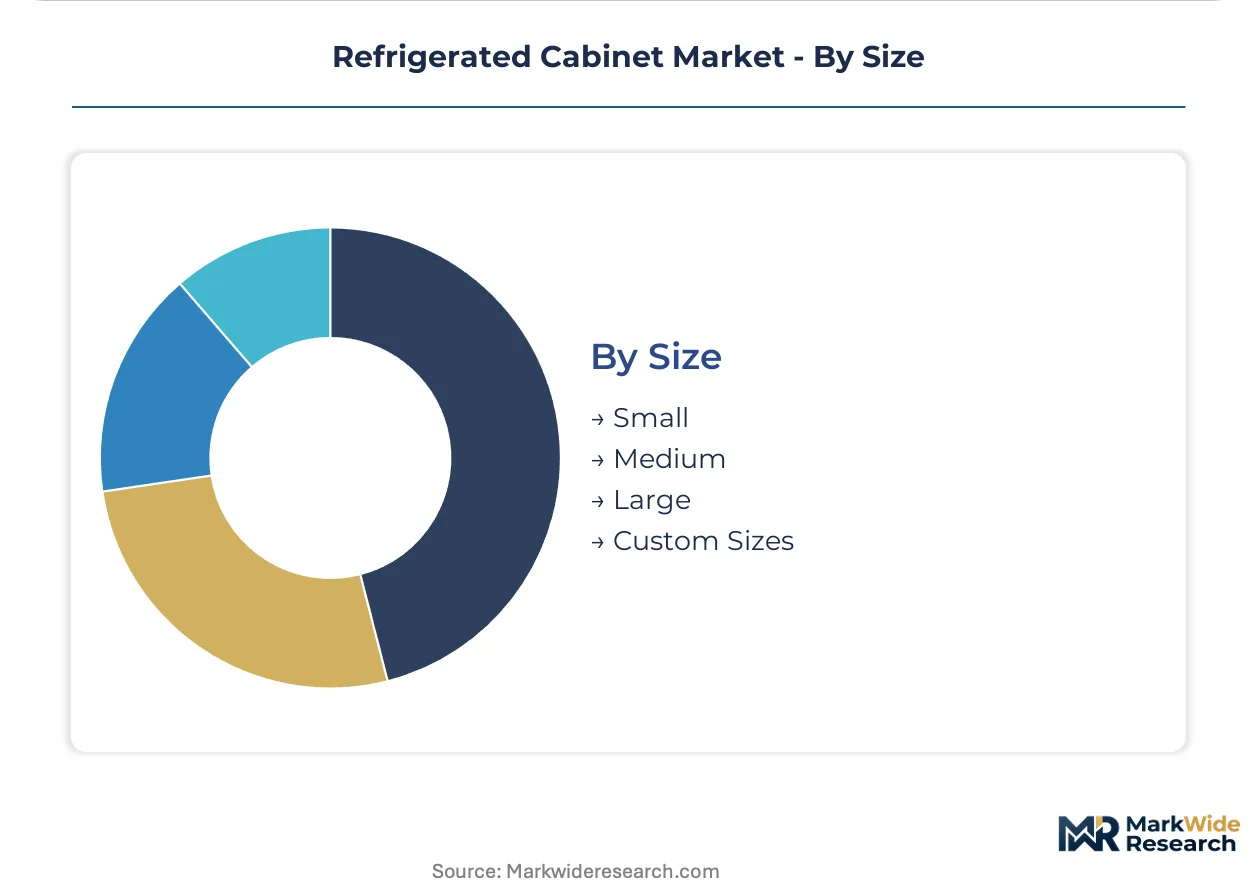
Size:
Footprint constraints and thermal load requirements segment demand by physical scale, with standardization pressures conflicting against custom engineering premiums.
- Large:Walk-in and multi-deck vertical systems serve centralized cold storage and high-traffic retail. Custom sizing commands premium positioning in warehouse and distribution applications where remote monitoring integration justifies engineering investment.
- Custom Sizes:Non-standard dimensions address facility-specific layout constraints. Food processing facilities and specialized retail formats specify these for workflow optimization, extending lead times but capturing margin pools unavailable to standard catalog products.
- Medium:Standard reach-in and double-door units balance capacity against space efficiency.
- Small:Undercounter and countertop units serve convenience stores and foodservice operations with severe space limitations.
Medium holds the broadest installed base, with Custom Sizes showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refrigerated cabinet manufacturing originated in Germany's industrial corridor during the post-war cold chain modernization, with engineering clusters in Bavaria and North Rhine-Westphalia establishing the technical foundations for commercial refrigeration systems that spread across European food retail networks.
United States
Food processing facilities in Texas and California are expanding walk-in cabinet capacity to buffer supply chain volatility. EPA SNAP rules prohibit R-404A and R-507A in new commercial equipment, forcing supermarket operators in New York and California to absorb first-mover compliance costs for natural refrigerant retrofits.
Germany
Supermarket chains across Bavaria and North Rhine-Westphalia specify glass-door vertical cabinets with variable-speed compressors to meet EU Green Deal reporting requirements. The EU F-Gas Regulation's phasedown quotas are accelerating CO₂ transcritical system validation in Berlin and Hamburg retrofit programs.
Brazil
Food processing facilities in São Paulo and Minas Gerais are driving walk-in cabinet demand with integrated remote monitoring for supply chain buffering. ANVISA cold chain regulations for perishable distribution are tightening temperature validation protocols for equipment specifications.
India
BIS energy labeling requirements are raising performance floors for imported cabinet systems, creating specification windows for domestic manufacturers with certified test protocols in Maharashtra and Gujarat. Cold storage expansion in Haryana and Karnataka is pulling medium-format reach-in demand from food processing investors.
Japan
Convenience store operators in Tokyo and Osaka are specifying compact undercounter cabinets with thermoelectric systems where noise reduction outweighs efficiency trade-offs. METI energy efficiency standards are accelerating variable frequency drive adoption in Kansai retail retrofit programs.
Refrigerated Cabinet Market Competitive Environment
Premium-margin players sit above commodity-margin players across refrigerant technology sophistication and control system integration depth. The vendor base clusters around three strategic archetypes: full-system integrators with compressor technology leadership, controls specialists with predictive maintenance platforms, and regional fabricators with cost-optimized standard catalogs. Competitive moves concentrate on backward integration into refrigerant chemistry and strategic partnerships for remote monitoring data platforms.
Among diversified industrial conglomerates, Carrier Global Corp. and Daikin Industries Ltd. occupy positions exemplifying full-system integration archetypes, while Liebherr International AG represents specialized engineering depth in custom walk-in applications. Haier Smart Home Co. Ltd. anchors the scale-driven tier with manufacturing concentration in Asia-Pacific supply chains. Panasonic Holdings Corp. sits within the controls-electronics convergence vector, leveraging sensor integration capabilities developed in adjacent appliance categories.
| Leading Market Players |
|---|
| Carrier Global Corp. |
| Daikin Industries Ltd. |
| Haier Smart Home Co. Ltd. |
| Liebherr International AG |
| Panasonic Holdings Corp. |
| Ali Group S.r.l. |
| HOSHIZAKI Corp. |
| Dover Corp. |
| Illinois Tool Works Inc. |
| Others |
Value Chain & Pricing Dynamics
Copper and aluminum price indices on the London Metal Exchange cascade through refrigerated cabinet manufacturing into three-tier pricing structures across premium, standard, and economy levels, with EU F-Gas Regulation compliance costs compressing margins for mid-tier producers lacking captive metal sourcing or backward integration into compressor technology.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates natural refrigerant-certified systems from conventional HFC-based units from basic catalog products without remote monitoring integration. Price differentiation rests on certification grade for EU F-Gas and EPA SNAP compliance plus customization level for walk-in dimensions. Pricing pressure stems from copper and aluminum input volatility squeezing heat exchanger margins. Food processing facilities show least price sensitivity due to total-cost-of-ownership framing, while small-format convenience stores in Southeast Asia absorb highest price elasticity.
Supply Chain Analysis
Certification gating through EU notified bodies and India's BIS test protocols fragments supplier eligibility, compressing qualified vendor pools for cross-border shipments. Manufacturing concentrates in Germany, Japan, and China, with semi-hermetic compressor production anchored in Bavaria and Osaka industrial corridors. Raw material dependencies draw from copper coil stock, polyurethane foam chemicals, and hermetic compressor castings. Single-source vulnerability concentrates in German compressor engineering clusters. Distribution runs through food retail chain procurement consortiums and cold storage EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between India's tightening BIS energy labeling requirements and Southeast Asia's underpenetrated convenience store infrastructure, with compliance cost differentials creating specification windows for domestic Indian manufacturers versus import-dependent ASEAN distributors.
For Market Incumbents: Cement specification dominance in German supermarket retrofit programs by deepening backward integration into CO₂ transcritical compressor technology before EU F-Gas phasedown quotas accelerate. Counter emerging controls specialists by bundling predictive maintenance platforms with hardware contracts, capturing recurring revenue streams that separate from pure equipment sales. For New Entrants and Emerging Players: Begin with compact plug-in cabinets for Southeast Asian convenience stores, where standardized cold chain infrastructure gaps create specification openings without incumbent entrenched relationships. Target ANVISA cold chain validation requirements in Brazilian food processing as the most penetrable regulatory entry point, leveraging modular shelving configurations absent from legacy walk-in catalog offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with controls-electronics convergence specialists possessing FDA 21 CFR Part 11 temperature logging capabilities for pharmaceutical cold chain extension. Long-term viability favors platforms integrating hardware ownership with outcome-based thermal performance contracts, particularly in UK and Netherlands foodservice channels where energy price volatility has made operational cost certainty a priority procurement criterion. Watch for inflection when leasing penetration in foodservice crosses threshold to displace outright purchase as dominant procurement model.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Technology | Captures margin pools in German supermarket retrofit programs facing EU F-Gas quotas. |
| Predictive Maintenance Platform Development | Separates recurring revenue from hardware sales for 24-hour retail formats. |
| CO₂ Transcritical System Validation | Unlocks specification wins in California and New York EPA SNAP compliance deadlines. |
| Pharmaceutical Cold Chain Certification | Merges cabinet specifications with FDA 21 CFR Part 11 data integrity requirements. |
| Outcome-Based Leasing Structure | Transfers efficiency risk to equipment financiers in UK and Netherlands foodservice channels. |
Study Parameters
Direct dialogue with supermarket procurement directors, cold storage facility engineers, compressor OEM technical leads, and food processing plant managers grounded qualitative findings, cross-referenced against EU F-Gas Regulation filings, EPA SNAP rule dockets, BIS certification registries, and customs trade data for refrigeration equipment. Bottom-up and top-down triangulation validated volume estimates across product type, end user, technology, and size segmentation dimensions.
Bottom-up modeling built from named country-level replacement cycles and retrofit program timelines, while top-down analysis cross-checked against food retail square footage expansion and cold storage capacity additions. CAGRs derived from regression against refrigerant transition deadlines and energy labeling tightening schedules. Forecast inputs incorporated EU Green Deal reporting requirement adoption curves and natural refrigerant technician certification bottlenecks.
Several conditions sit outside the modeled scope, including unforeseen delays in India-Brazil test protocol reciprocity agreements and abrupt copper price shocks exceeding historical volatility bands. Forecasts reflect assumptions around phased regulatory implementation without enforcement disruption. A model refresh is warranted upon material change in EPA SNAP final rule timelines or EU F-Gas quota acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Dryers Market
Appliances
Germany Consumer Appliances Market
Appliances
North America Personal Care Appliances Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Mobile Refrigerators Market
Appliances
Glass Ceramic Cooktop Market
Appliances
Water Dispenser Market
Appliances
North America Compact Dishwasher Market
Appliances
Japan Laundry Appliances Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Fully Integrated Dishwasher Market
Appliances
UAE Gas Hobs Market
Appliances
Washing Appliances Market
Appliances
Turkey Washing Machine Market
Appliances
Residential Space Heater Market