
 Europe Smart TV Market | 2026-2036
Europe Smart TV Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart TV Market Analysis
The display panel fabrication gap between in-house semiconductor foundries and third-party procurement is rotating competitive advantage toward vertically integrated manufacturers. Samsung Electronics leverages captive OLED production to sustain margin control across premium tiers. LG Electronics anchors its position through advanced evaporation deposition expertise in large-format panels. TCL Electronics Holdings Limited competes aggressively on cost-engineered QLED assemblies sourced from consolidated Chinese supply bases.
A smart television integrates broadcast reception, internet protocol streaming, and embedded application processing within a single display unit, typically incorporating system-on-chip architectures with dedicated neural processing engines for upscaling and voice recognition. LED-backlit LCD configurations retain volume leadership across European mass-market retail channels due to manufacturing scale and price accessibility. OLED segments command premium positioning in Germany and the United Kingdom where image quality sensitivity runs highest. Ultra HD resolution now serves as baseline specification rather than differentiator across households and hotel deployment categories.
The EU Ecodesign Directive and CE marking framework mandate stringent energy efficiency thresholds and electromagnetic compatibility certification for all connected displays sold within member states, effectively filtering out non-compliant import channels. The EU AI Act introduces forthcoming transparency obligations for biometric and emotion recognition features embedded in voice control systems. Stakeholders must evaluate how evolving material disclosure requirements under REACH will affect semiconductor substrate sourcing and panel recycling obligations.
Market Dynamics
The EU Ecodesign Directive's standby power limits are compressing margins for import-dependent assemblers while rewarding captive OLED fabrication. Panel supply concentration in East Asia creates procurement vulnerability for European brands lacking backward integration into semiconductor foundries.
Growth Catalysts
- Hospitality digitalization:German, French, and Italian hotel operators are replacing conventional displays with internet-connected screens to enable personalized guest streaming and targeted property services.
- CE marking harmonization:The unified electromagnetic compatibility certification framework eliminates country-by-country approval costs, accelerating cross-border retail distribution for compliant manufacturers.
- AI upscaling engines:Neural processing units embedded in system-on-chip architectures enable real-time content enhancement, driving replacement cycles among image-quality-sensitive households in Nordic markets.
Market Restraints
- Substrate supply concentration:Advanced OLED evaporation deposition equipment and driver IC fabrication remain concentrated in Korean and Taiwanese supply bases, creating single-source vulnerability.
- REACH material disclosure:Evolving semiconductor substrate sourcing obligations under ECHA regulations are extending compliance timelines and raising due diligence costs for non-vertically integrated brands.
- QLED price compression:Cost-engineered quantum dot assemblies sourced from consolidated Chinese manufacturing bases are commoditizing mid-tier segments and compressing margin pools for European incumbents.
Strategic Opportunities
- EU AI Act transparency:The forthcoming biometric and emotion recognition disclosure mandate creates first-mover advantage for voice control systems with embedded privacy-by-design architectures.
- Polish and Romanian retail:Underpenetrated mass-market channels in Central European member states offer volume expansion potential as Ultra HD resolution becomes baseline specification rather than premium differentiator.
- Panel recycling infrastructure:Extended producer responsibility frameworks under EU Green Deal implementation are creating service revenue streams for manufacturers with closed-loop rare earth recovery capabilities.
Industry Challenges
- Evaporation deposition expertise scarcity:Large-format OLED manufacturing requires specialized vacuum chamber engineering talent that European labor markets currently underproduce relative to expansion plans.
- Legacy hotel system integration:Property management system compatibility requirements in established German and French hospitality chains extend deployment timelines and increase customization costs for smart TV installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart TV Market |
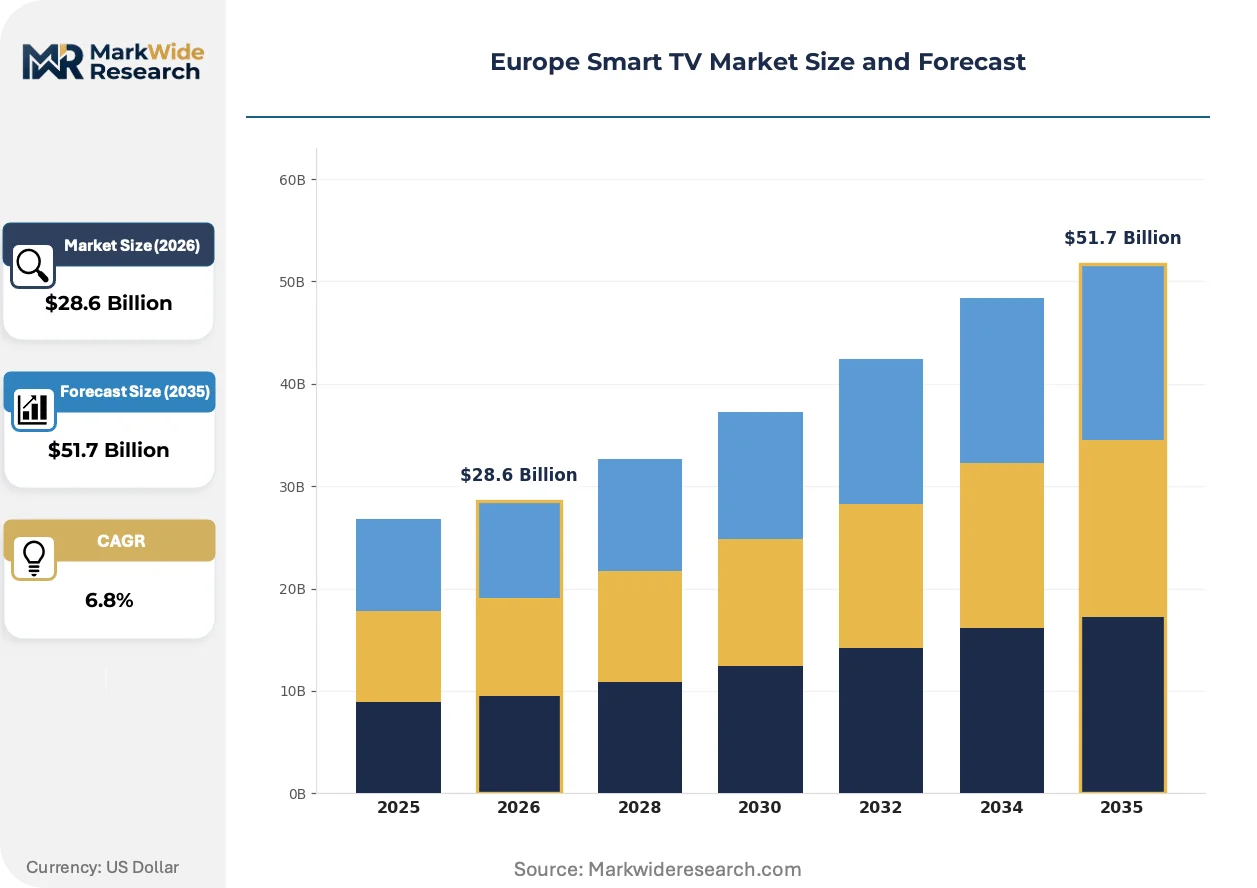
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, Ultra HD Screen Size: 32 inches, 43 inches, 55 inches, 65 inches Technology: Wi-Fi, Bluetooth, Streaming, Voice Control End User: Households, Hotels, Corporate, Educational Institutions |
| Companies Covered | Sony Corporation, Xiaomi Corporation, Samsung Electronics, Hisense International, Haier, LG Electronics, Koninklijke Philips, Panasonic Holdings Corporation, TCL Electronics Holdings Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart TV Market Emerging Trajectories
Voice recognition architectures are bifurcating between cloud-dependent and edge-processing implementations, reshaping how biometric data traverses European networks. This divergence is compressing design cycles and forcing chipset selection decisions earlier in product development.
Mini-LED backlighting is fragmenting the premium LCD segment. German and British retailers are adopting the technology for mid-premium tiers where OLED price points remain prohibitive. The diffusion is fragmenting manufacturer R&D budgets across multiple display technologies rather than consolidating behind single premium standards.
The EU AI Act's transparency obligations for biometric recognition are accelerating documentation requirements. Voice control system vendors must now maintain technical files demonstrating compliance with emotion recognition disclosure rules. Nordic markets with stronger privacy enforcement are experiencing faster procurement specification updates than Southern European channels.
After-sales service unbundling is altering distribution economics. French and Italian electronics retailers are separating installation, extended warranty, and content platform activation into distinct revenue lines. This unbundling is visible most acutely in hospitality procurement, where hotel operators now negotiate display hardware, connectivity provisioning, and guest interface management as separate contracts.
Europe Smart TV Market Segmentation
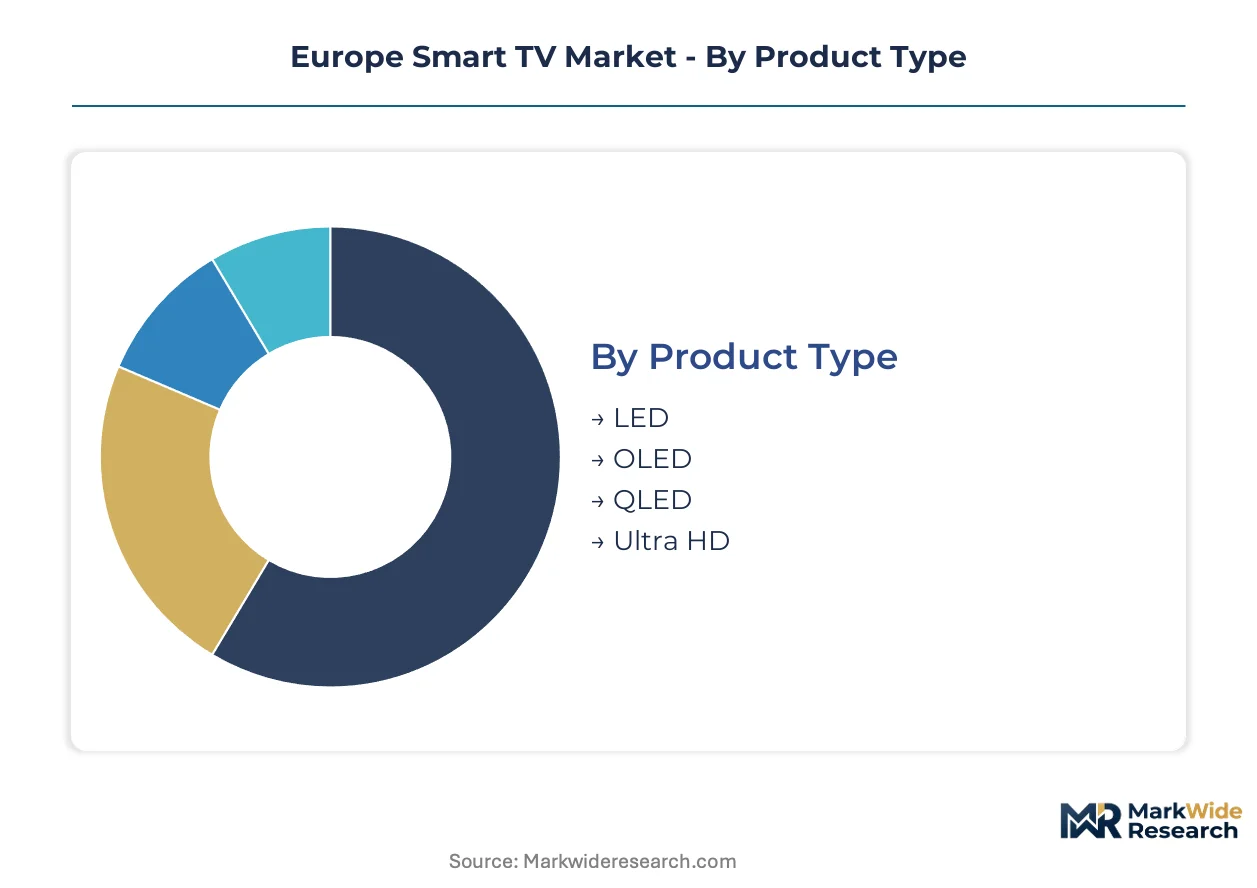
Display technology substitution pressures and hospitality procurement shifts are fragmenting competitive positioning across European distribution channels. Segmentation clarity exposes where margin compression concentrates versus where premium positioning endures.
Product Type:
LED-backlit LCD configurations face the most acute substitution pressure from quantum dot and self-emissive alternatives as price-performance ratios compress across German and French retail floors.
- LED:Edge-lit and direct-lit LED-backlit LCD panels dominate mass-market volume through manufacturing scale and supply chain maturity. German and Italian retailers stock these configurations most heavily in sub-55-inch categories where hospitality procurement concentrates on total cost of ownership rather than image quality differentiation.
- OLED:Self-emissive organic light-emitting diode panels eliminate backlighting layers entirely, enabling infinite contrast ratios and sub-millimeter form factors. Nordic markets in Sweden and Denmark absorb disproportionate OLED share where household willingness-to-pay for image fidelity runs highest and CE marking harmonization accelerates cross-border premium distribution.
- QLED:Quantum dot-enhanced LED assemblies layer nanocrystal films over blue LED backlights to expand color gamut coverage.
- Ultra HD:3840×2160 resolution specification now serves as baseline rather than differentiator across European retail and hospitality deployment categories.
LED retains volume leadership; OLED holds the steepest expansion curve.
Screen Size:
Cost tier stratification across European retail channels concentrates procurement specification divergence between household replacement cycles and hospitality standardization mandates.
- 32 inches:Compact form factor dominates secondary room installations and budget hospitality deployments where space constraints and procurement cost ceilings align. Polish and Romanian retail channels move disproportionate 32-inch volume as Ultra HD baseline specification penetrates mass-market tiers.
- 43 inches:Mid-size configuration balances viewing distance flexibility with freight and installation economics. French hotel operators standardize on 43-inch displays for mid-tier property renovations where property management system integration costs must be contained across multi-unit rollouts.
- 55 inches:Primary living room specification for German and British households upgrading from 1080p legacy sets.
- 65 inches:Premium residential and executive hospitality format where OLED panel economics become competitive with large-format LED alternatives.
43 inches anchors hospitality procurement standardization; 65 inches climbs fastest in Nordic premium residential channels.
Technology:
Application-driven connectivity requirements are forcing chipset architecture decisions earlier in product development cycles as edge-versus-cloud processing trade-offs harden.
- Wi-Fi:802.11ac and Wi-Fi 6 embedded modules enable over-the-top streaming without dedicated Ethernet infrastructure. German hospitality chains mandate Wi-Fi connectivity as standard for guest streaming authentication integration with property management systems.
- Bluetooth:Low-energy peripheral pairing supports wireless audio output and remote control alternatives. Italian retail channels bundle Bluetooth-enabled soundbars with mid-tier smart TV configurations to differentiate against pure-play display competitors.
- Streaming:Pre-certified application platforms reduce content licensing friction for manufacturers.
- Voice Control:Far-field microphone arrays and neural processing engines enable hands-free navigation. EU AI Act transparency obligations for biometric recognition are accelerating documentation requirements for voice control system vendors serving Nordic markets with stronger privacy enforcement.
Wi-Fi retains baseline ubiquity; voice control gains share fastest where regulatory compliance creates first-mover differentiation.
End User:
Customer type divergence in procurement sophistication separates volume-driven replacement cycles from solution-integrated deployment timelines.
- Households:Individual consumer replacement decisions prioritize streaming application availability and voice control convenience over display technology specifications. British households demonstrate highest image quality sensitivity, driving OLED penetration in premium tiers.
- Hotels:German, French, and Italian hospitality operators negotiate display hardware, connectivity provisioning, and guest interface management as separate contracts. Property management system compatibility requirements extend deployment timelines and increase customization costs for installers.
- Corporate:Meeting room and digital signage deployments prioritize network manageability and centralized firmware update capabilities.
- Educational Institutions:Public sector procurement frameworks emphasize energy efficiency certification and extended warranty terms.
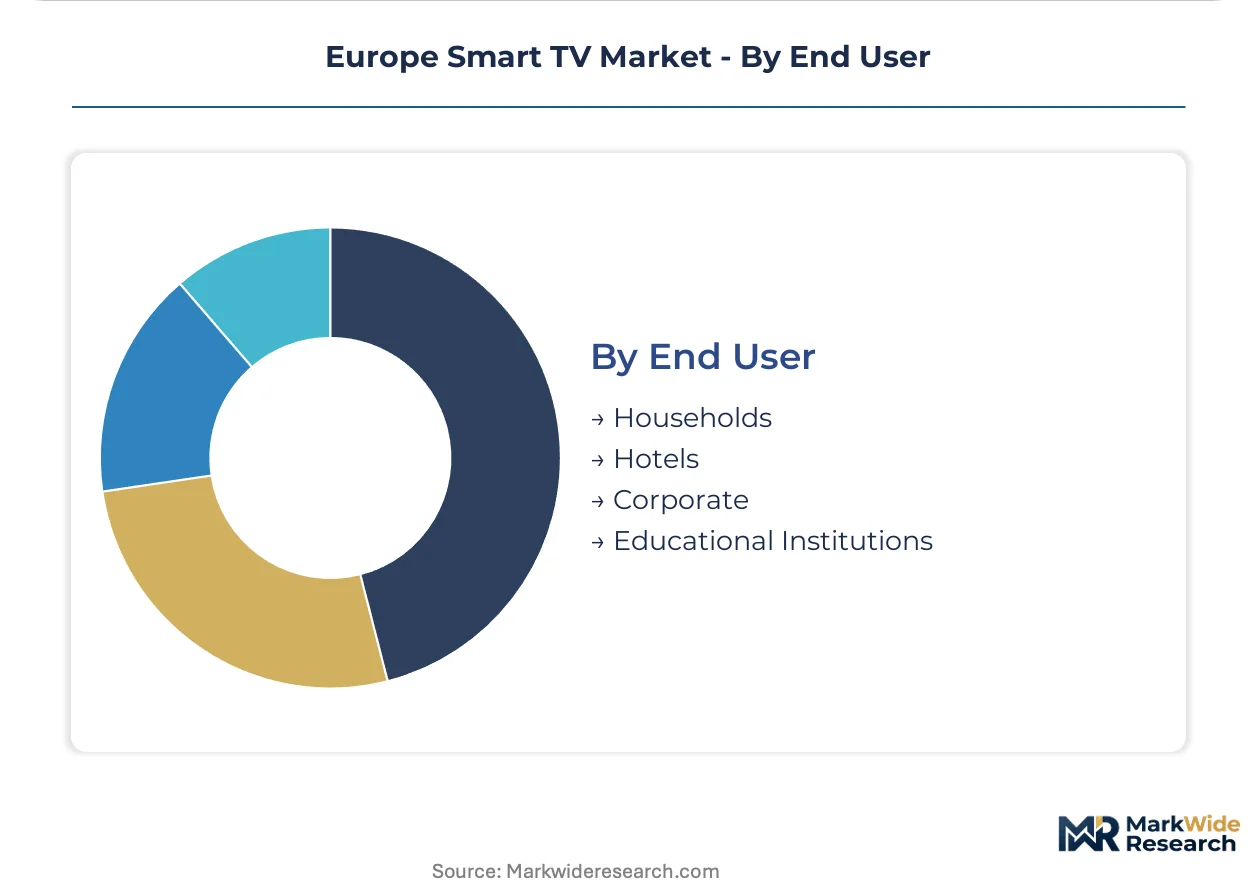
Households dominate unit volume; hotels expand most quickly as digitalization mandates replace conventional displays across European hospitality portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Nordic markets where households absorb premium OLED tiers, while Polish and Romanian retail channels compete on volume-accessible LED configurations. This asymmetry shapes manufacturer portfolio allocation across the continent.
Germany
Hotel operators in Berlin and Munich drive hospitality procurement standardization around 43-inch internet-connected displays with property management system integration. The EU Ecodesign Directive's standby power limits filter non-compliant imports from mass-market channels. Bavarian industrial clusters around Munich anchor display assembly operations serving Central European distribution networks.
United Kingdom
British households demonstrate the region's highest image quality sensitivity, accelerating OLED penetration in premium residential tiers. CE marking harmonization eliminates cross-border approval friction for compliant manufacturers entering UK retail post-regulatory realignment. Greater London's electronics distribution hubs concentrate import logistics for Northern European markets.
France
French hotel chains in Paris and Lyon negotiate display hardware, connectivity provisioning, and guest interface management as separate procurement contracts. The EU AI Act's transparency obligations for biometric recognition accelerate documentation requirements for voice control system vendors. Île-de-France's hospitality technology integrators specialize in legacy property management system compatibility solutions.
Italy
Italian mid-tier hotel renovations standardize on 43-inch displays where total cost of ownership constraints override image quality differentiation. REACH material disclosure obligations extend compliance timelines for semiconductor substrate sourcing. Milan's retail electronics corridors bundle Bluetooth-enabled soundbars with smart TV configurations to differentiate against pure-play display competitors.
Sweden
Swedish households in Stockholm and Gothenburg absorb disproportionate OLED share in 55-inch and 65-inch formats where willingness-to-pay for image fidelity runs highest. GDPR enforcement in Nordic markets drives faster procurement specification updates for privacy-by-design voice control architectures. Scandinavian retail channels leverage CE marking harmonization to accelerate cross-border premium distribution.
Europe Smart TV Market Vendor Landscape
Concentration sits with vertically integrated display panel fabricators who control captive OLED production and advanced evaporation deposition expertise. The vendor base stratifies across three tiers: Korean and Japanese conglomerates with in-house semiconductor foundries, Chinese cost-engineered assemblers leveraging consolidated supply bases, and European heritage brands dependent on third-party panel procurement. Strategic moves center on backward integration into driver IC fabrication and hospitality-focused solution bundling.
Among Korean conglomerates, Samsung Electronics and LG Electronics exemplify the vertically integrated archetype with captive OLED production capabilities. TCL Electronics Holdings Limited anchors the cost-engineered tier sourced from consolidated Chinese manufacturing bases. Sony Corporation occupies a position representing Japanese heritage brands navigating third-party panel procurement dependencies.
| Leading Market Players |
|---|
| Sony Corporation |
| Xiaomi Corporation |
| Samsung Electronics |
| Hisense International |
| Haier |
| LG Electronics |
| Koninklijke Philips |
| Panasonic Holdings Corporation |
| TCL Electronics Holdings Limited |
| Others |
Supply Flow & Price Mechanics
Ninety-day panel inventory cycles at Korean foundries concentrate pricing power with vertically integrated OLED producers while compressing margins for third-party procurement brands across European distribution channels.
Pricing Analysis
The customization-premium spread between property management system-integrated hospitality deployments and standard retail configurations widens as French and German hotel chains negotiate connectivity provisioning separately from display hardware. Three-tier pricing structure across premium OLED, standard QLED, and economy LED levels stratifies by image quality certification and after-sales service bundling. Cost compression in mid-tier QLED segments intensifies because Chinese quantum dot assemblies flood European retail floors. Budget hospitality operators in Italy and Poland exhibit highest price sensitivity; Nordic residential buyers demonstrate lowest.
Supply Chain Analysis
Evaporation deposition equipment chokepoints in Korean and Taiwanese fabrication facilities tether European brand procurement to single-source OLED panel supply. Driver IC fabrication concentrates in South Korea, Taiwan, and China; rare earth phosphors for quantum dot films and indium tin oxide substrates feed from consolidated East Asian chemical processing. Single-source vulnerability in advanced OLED vacuum chamber engineering exposes non-integrated brands to allocation risk. Distribution runs through Rotterdam and Hamburg port hubs into Central European retail corridors and hospitality integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against QLED commoditization from cost-engineered Chinese assemblies that threaten premium positioning through aggressive price undercutting in mid-tier European retail.
For Market Incumbents: Secure captive OLED production capacity through backward integration into driver IC fabrication or long-term foundry offtake agreements with Korean semiconductor suppliers. Anchor hospitality solution bundling with property management system certification to raise switching costs against low-cost QLED alternatives. CE marking harmonization and EU Ecodesign Directive compliance investments create regulatory moats that import-dependent assemblers cannot easily replicate. For New Entrants and Emerging Players: Hospitality after-sales service unbundling exposes installation and connectivity provisioning gaps where incumbents under-serve mid-tier French and Italian hotel operators. Target Polish and Romanian retail channels for volume-accessible LED configurations as Ultra HD baseline specification penetrates mass-market tiers. Pursue white-label voice control system partnerships with privacy-by-design architectures that satisfy EU AI Act transparency obligations ahead of enforcement. For Investors and Strategic Acquirers: Carve-out targets emerge from European heritage brands with distribution relationships but lacking backward integration into panel fabrication. Long-term viability hinges on captive OLED supply or differentiated hospitality software integration capabilities. Watch for inflection signals in REACH material disclosure enforcement timelines that would accelerate consolidation among non-compliant import-dependent assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Fabrication | Captive semiconductor supply insulates margin control from Korean and Taiwanese foundry allocation decisions. |
| Hospitality Solution Bundling | Property management system certification raises switching costs and extends contract duration with German and French hotel chains. |
| Privacy-by-Design Voice Control Development | EU AI Act transparency compliance creates first-mover differentiation in Nordic markets with stronger GDPR enforcement. |
| Central European Retail Expansion | Underpenetrated Polish and Romanian channels offer volume growth as Ultra HD specification commoditizes across mass-market tiers. |
| Closed-Loop Panel Recycling Infrastructure | Extended producer responsibility frameworks under EU Green Deal implementation generate service revenue from rare earth recovery. |
Methodological Framework
Desk research of customs trade records, SEC and KRX exchange filings, and EU regulatory databases preceded structured interviews with display panel procurement directors, hospitality technology integrators, retail category buyers, semiconductor foundry planning officers, and Ecodesign compliance consultants. Primary fieldwork captured procurement specification divergence between household replacement cycles and hospitality deployment timelines. Secondary validation drew from CE marking certification registries, REACH material disclosure filings, and hospitality property management system vendor documentation. Bottom-up unit shipment estimates triangulated against top-down value projections.
Variance decomposition across display technology, screen size tier, end-user segment, and national regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate blending and technology substitution curve modeling. Forecast inputs incorporated EU Ecodesign Directive standby power limit phase-in schedules and OLED panel yield improvement trajectories at Korean fabrication facilities.
Forecasts assume regulatory continuity in EU Ecodesign Directive enforcement and REACH material disclosure timelines; material policy acceleration or trade restriction expansion would require re-modeling. Specific risks include evaporation deposition equipment export controls, rare earth supply disruption, and hospitality capital expenditure contraction. Practitioners should keep alternative scenarios live as EU AI Act implementation guidance and F-Gas Regulation panel manufacturing requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Mirror TV Market
Consumer Electronics
Ergonomic Mouse Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
North America Smartphone Accessories Market
Consumer Electronics
LAMEA Refurbished and Used Mobile Phones Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Foldable Phone Market
Consumer Electronics
Smart Audio Devices Market