
 Ergonomic Mouse Market | 2026-2036
Ergonomic Mouse Market Size, Share, and Industry Trends Forecast 2026-2036
Ergonomic Mouse Market Insights
Multi-source component procurement is recalibrating how ergonomic mouse manufacturers balance cost control with design flexibility. Logitech leverages its Swiss engineering heritage to dominate premium wireless vertical models. Razer competes in the gaming-ergonomics crossover segment with high-DPI optical sensors. Posturite anchors the corporate wellness channel through direct occupational health contracts.
An ergonomic mouse is a computer peripheral engineered with angled grips, contoured palm rests, and reduced wrist pronation to mitigate carpal tunnel syndrome and repetitive strain injury during extended use. Devices typically incorporate adjustable DPI settings between 800 and 3200, with vertical orientations rotating the hand position to a neutral handshake posture. The vertical mouse category leads absolute volume due to clinical validation in occupational therapy protocols, while Bluetooth connectivity represents the fastest-expanding technology segment as enterprises eliminate USB receiver inventory. Office professionals generate the deepest margin pools through bulk corporate purchasing agreements negotiated by facilities management departments.
OSHA enforces workplace ergonomics standards that incentivize employer investment in certified peripheral equipment, while the EU Machinery Directive mandates CE marking for input devices marketed as injury-prevention tools. REACH compliance constrains polymer and coating selections for housings sold across European member states. Stakeholders must monitor how FDA device-classification discussions for computer peripherals evolve, as reclassification would trigger premarket submission requirements for ergonomic health claims.
Market Dynamics
Enterprise fleet procurement is compressing supplier margins while elevating certification requirements as the dominant structural force reshaping competitive positioning in ergonomic peripherals.
Growth Catalysts
- OSHA workplace ergonomics enforcement:US employers face rising injury claim costs that accelerate bulk purchasing of certified vertical mice for office deployments.
- Germany's health insurance subsidies:Industrial health funds in Baden-Württemberg and Bavaria reimburse remote workers for ergonomic peripheral purchases, concentrating demand.
- Bluetooth Low Energy adoption:Enterprises eliminating USB receiver inventory drives wireless refresh cycles in financial services and legal sectors.
Market Restraints
- Polymer input cost volatility:ABS and polycarbonate resin prices fluctuate with crude oil indices, squeezing housing margin pools for injection-molded components.
- Optical sensor supply concentration:High-precision DPI modules depend on Taiwanese and South Korean fab capacity, creating single-source vulnerability.
- REACH compliance friction:ECHA restrictions on phthalate plasticizers and flame retardants force reformulation of rubberized grips for European market access.
Strategic Opportunities
- Underpenetrated SME channel:Mid-size professional services firms in France and Italy lack occupational health procurement infrastructure, creating direct sales white space.
- Gaming-ergonomics convergence:Esports athletes and streamers adopt vertical grips for marathon sessions, opening premium positioning above standard office tiers.
- EU Machinery Directive expansion:Pending amendments may mandate CE marking for all injury-prevention peripherals, accelerating replacement demand.
Industry Challenges
- Biomechanical certification timelines:Clinical validation studies for carpal tunnel syndrome claims require 18-24 month occupational therapy trials, delaying product launches.
- Legacy system integration:Enterprise IT departments struggle to deploy Bluetooth mice across mixed Windows-macOS environments with inconsistent driver support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ergonomic Mouse Market |
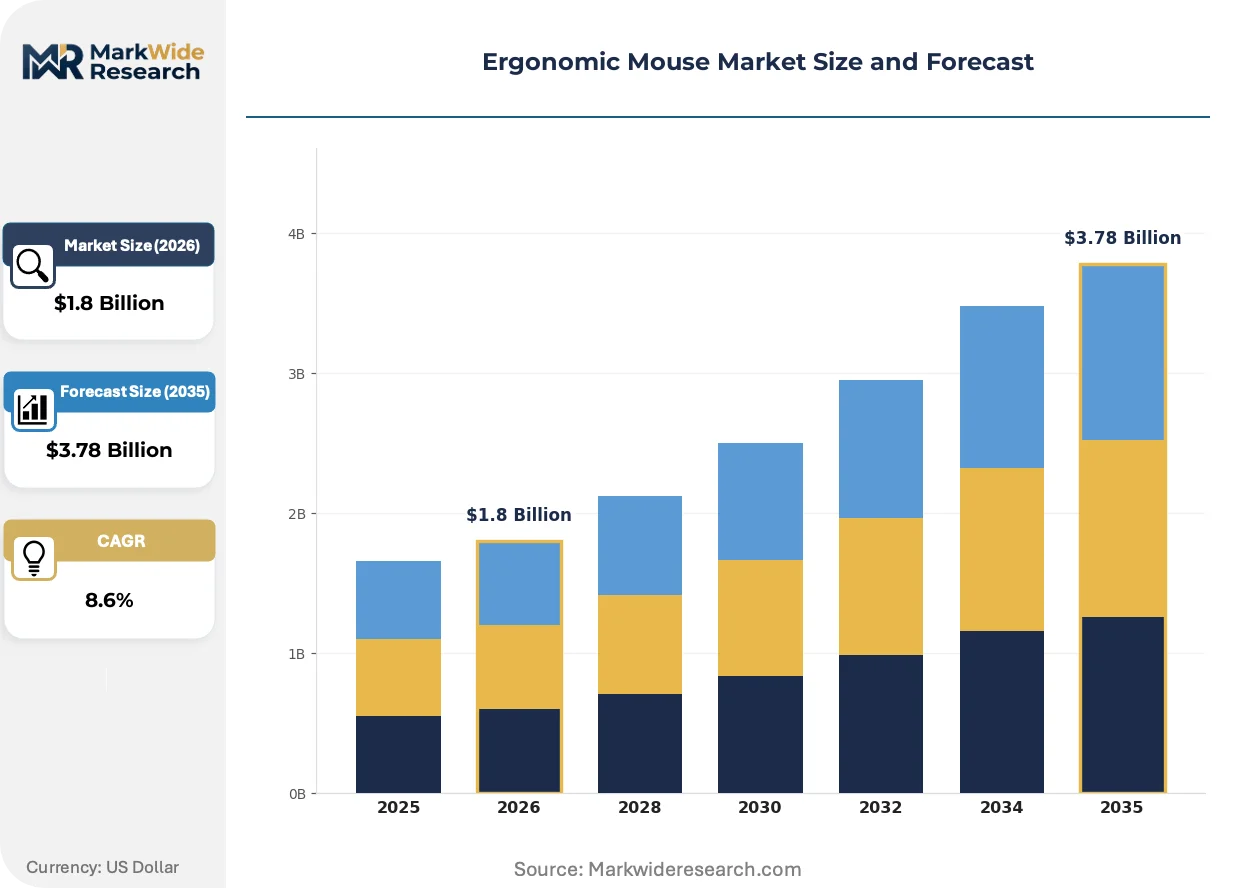
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Mouse, Trackball Mouse, Wireless Mouse, Wired Mouse End User: Office Professionals, Gamers, Designers, Students Technology: Bluetooth, Optical, Laser, Infrared Size: Small, Medium, Large, Extra Large |
| Companies Covered | Posturite, Razer, Delux, Microsoft, Anker, Contour Design, Logitech, Kensington, Evoluent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ergonomic Mouse Market Trends and Innovations
Wireless charging integration and AI-driven posture feedback are compressing product refresh cycles while elevating the technical bar for category entry.
Multi-protocol wireless chipsets is unifying 2.4GHz, Bluetooth 5.3, and wired USB-C connectivity into single-sku designs. Financial services procurement teams in Frankfurt and Singapore prioritize these tri-mode devices to simplify fleet management. This convergence is unifying previously fragmented inventory pools and forcing pure-play Bluetooth vendors toward obsolescence.
REACH authorization timelines for restricted substances are tightening polymer selection windows for housing manufacturers. ECHA's 2024 candidate list expansion adds two brominated flame retardants used in PC/ABS blends, compelling reformulation of textured grip surfaces. German industrial insurers now require REACH compliance documentation before reimbursing peripheral purchases, shifting buying criteria toward certified suppliers.
Direct occupational health contracting is displacing traditional electronics distribution for enterprise accounts. Facilities management departments at London law firms and Zurich banks negotiate multi-year ergonomic peripheral agreements with biometric assessment bundled into pricing. This channel compression is most visible in German-speaking Europe, where Betriebskrankenkassen health funds steer purchasing decisions through approved vendor lists.
Ergonomic Mouse Market Segmentation
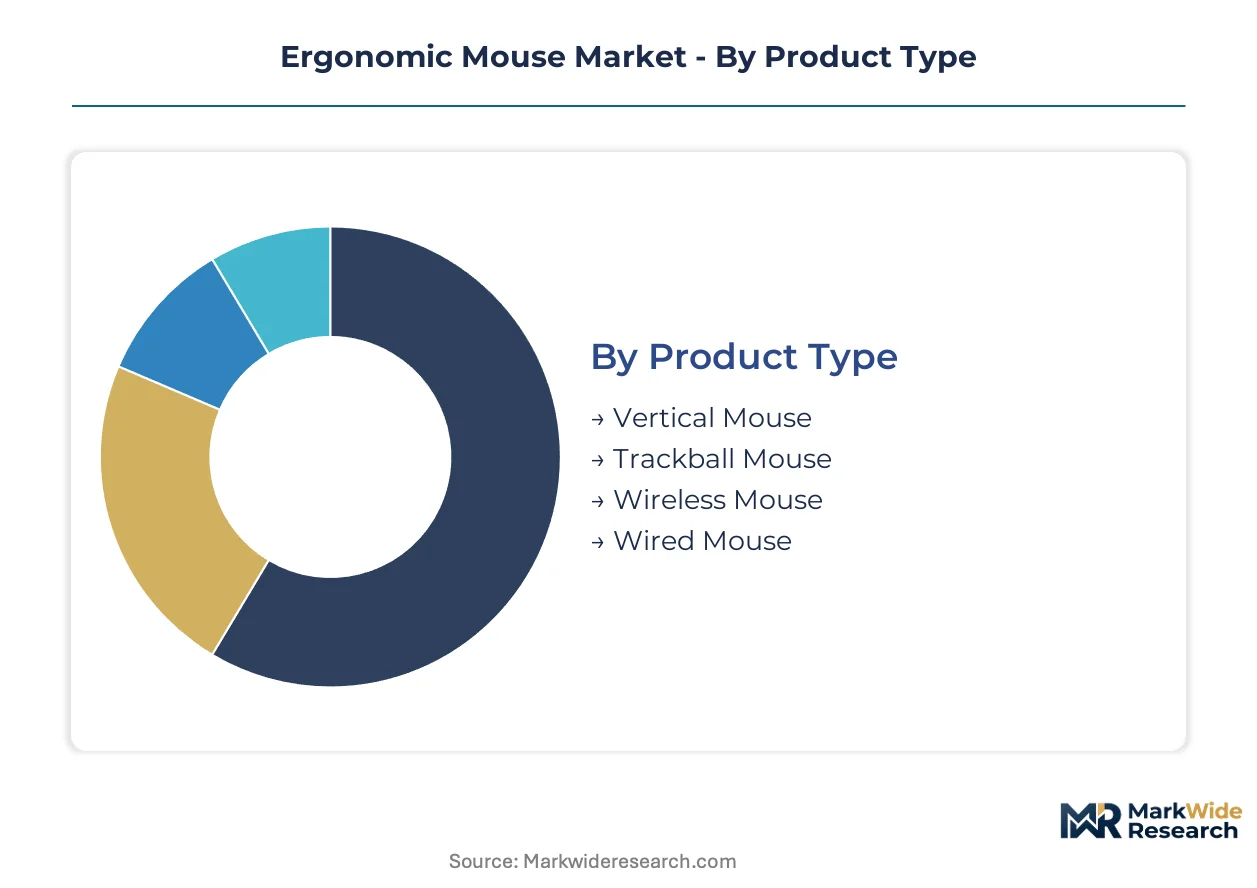
Ergonomic mouse procurement patterns diverge sharply across user profiles and connectivity standards, with certification requirements and reimbursement eligibility creating distinct purchasing corridors for each segment cluster.
Product Type:
OSHA workplace ergonomics guidelines and EU Machinery Directive CE marking requirements apply differentially across form factors, with clinical validation studies determining insurance subsidy eligibility in key markets.
- Vertical Mouse:Handshake-position orientation rotates the wrist to neutral pronation, reducing carpal tunnel syndrome risk in extended use. Demand concentrates in German-speaking Europe where Betriebskrankenkassen health funds mandate this design for remote worker reimbursement claims.
- Trackball Mouse:Stationary base with thumb-operated ball eliminates arm movement entirely, suiting confined workstations. Financial services trading floors in Frankfurt and Zurich deploy these for space-constrained multi-screen setups where precision outweighs speed.
- Wireless Mouse:Radio-frequency or Bluetooth connectivity eliminates cable drag and enables flexible positioning.
- Wired Mouse:USB-C or USB-A tethered connection delivers zero-latency input for latency-sensitive applications.
Leading the category by volume: Vertical Mouse. Growing fastest: Wireless Mouse.
End User:
Procurement authority and margin capture vary dramatically across user types, from bulk corporate fleet purchasing to individual premium self-selection.
- Office Professionals:Enterprise facilities management departments negotiate multi-year agreements with biometric assessment bundled into pricing. Bulk purchasing agreements in London law firms and Zurich banks generate the deepest margin pools through certified vendor lists.
- Gamers:Esports athletes and streamers adopt vertical grips for marathon sessions, creating premium positioning above standard office tiers. High-DPI optical sensors and programmable buttons command price multiples over corporate equivalents.
- Designers:Precision-dependent creative workflows demand adjustable sensitivity and ergonomic contouring for extended Adobe Creative Suite sessions.
- Students:Price-sensitive individual purchasers with limited reimbursement access drive economy-tier volume through educational channel partnerships.
Deepest margin capture: Office Professionals. Steepest expansion trajectory: Gamers.
Technology:
Connectivity protocols and sensor architectures determine enterprise IT compatibility and manufacturing cost structures.
- Bluetooth:Low Energy 5.3 protocol eliminates USB receiver inventory and simplifies mixed-device fleet management. Financial services procurement teams in Frankfurt and Singapore prioritize tri-mode chipsets unifying 2.4GHz, Bluetooth 5.3, and wired USB-C.
- Optical:LED-illuminated imaging sensors dominate mainstream office deployments with 800-3200 DPI adjustability.
- Laser:Higher-resolution tracking on glossy surfaces suits design and gaming applications requiring sub-pixel precision.
- Infrared:Specialized wavelength operation reduces power consumption in battery-dependent portable configurations.
Widest enterprise deployment: Optical. Climbing the fastest: Bluetooth.
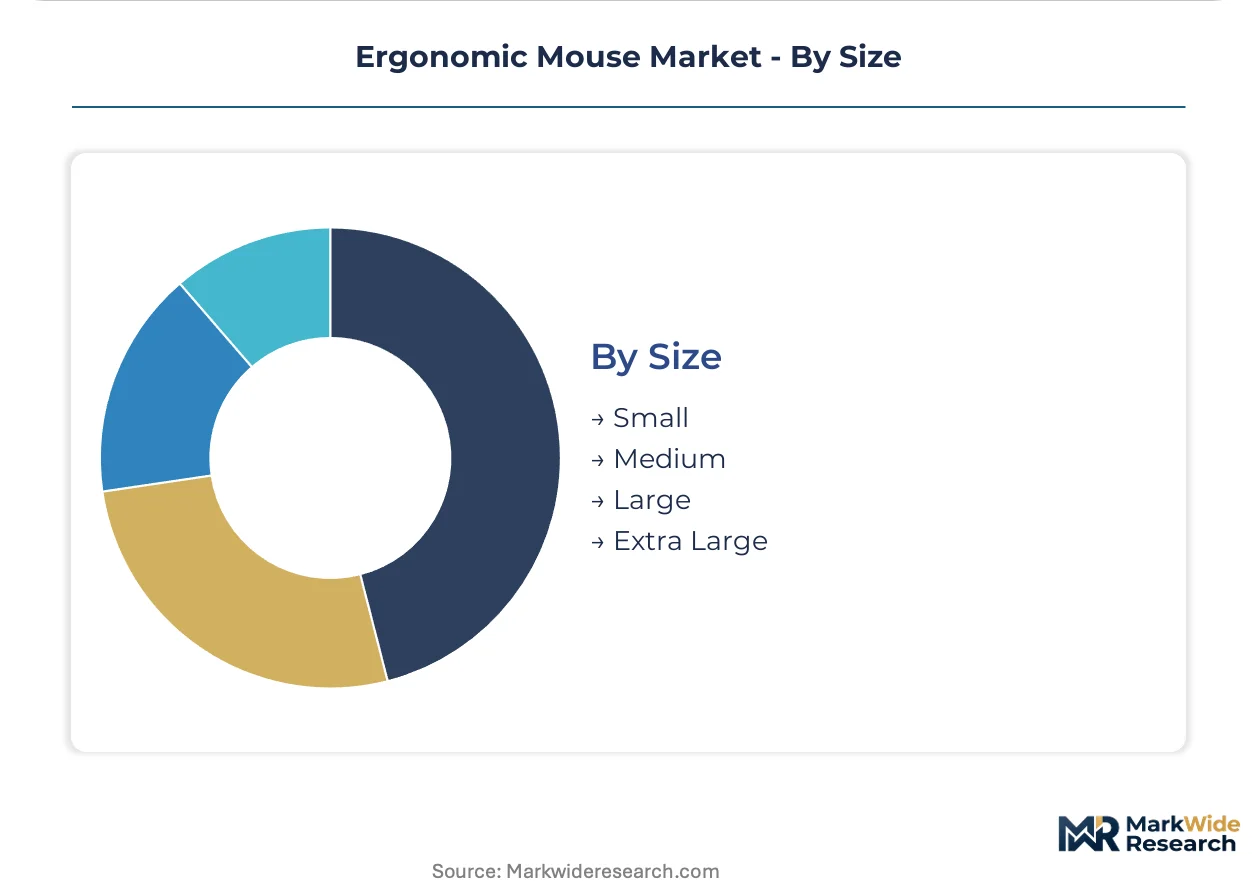
Size:
Hand dimension matching determines therapeutic efficacy and return rates, with biometric assessment increasingly standard in occupational health procurement.
- Small:Compact housings for hand lengths under 17cm, prevalent in East Asian markets and female-dominated professional services cohorts.
- Medium:Standard 17-19cm hand length accommodation captures majority volume in Western European and North American corporate deployments.
- Large:Extended palm rests and wider grip spans for 19-21cm hand measurements, concentrated in male-skewed engineering and financial trading populations.
- Extra Large:Specialized configurations for 21cm+ hand lengths, primarily serving Northern European and North American demographics with limited SKU availability.
Highest shipment volume: Medium. Fastest-growing specification: Small.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycarbonate resin production in the Rhine-Ruhr industrial corridor supplies housing manufacturers serving ergonomic peripheral assembly plants across Western Europe. German industrial health insurance funds subsidize remote worker purchases, concentrating procurement authority in Frankfurt, Munich, and Stuttgart. Supply chain nodes in Shenzhen and Dongguan feed optical sensor modules to assembly facilities in Malaysia and Vietnam.
United States
OSHA workplace ergonomics enforcement drives bulk fleet procurement by financial services firms in New York and Chicago seeking to reduce repetitive strain injury claims. The Department of Labor's injury cost documentation requirements incentivize certified vertical mouse deployment across Fortune 500 headquarters. Austin and Seattle tech campuses anchor demand for tri-mode wireless peripherals with biometric assessment bundled into facilities contracts.
Germany
Betriebskrankenkassen health funds in Baden-Württemberg and Bavaria reimburse remote workers for ergonomic peripheral purchases, creating the world's most concentrated demand corridor. REACH compliance documentation requirements from ECHA now precede insurance approval, shifting procurement toward certified suppliers. Munich's corporate headquarters cluster generates premium-tier volume through direct occupational health contracting with biometric assessment services.
United Kingdom
London law firms and insurance underwriters negotiate multi-year ergonomic peripheral agreements with bundled workplace assessment services. The Health and Safety Executive's Display Screen Equipment regulations mandate employer-funded equipment for remote workers. The Thames Valley corporate corridor drives standardization around Bluetooth Low Energy 5.3 protocols to eliminate USB receiver inventory management.
Japan
METI guidelines on telework infrastructure subsidize ergonomic equipment purchases for small and medium enterprises in Tokyo and Osaka. JIS standards for input device safety certification create compliance barriers for non-domestic suppliers. Nagoya's precision manufacturing base supplies high-DPI optical sensor modules to peripheral assemblers serving domestic gaming and professional markets.
Singapore
Financial services procurement teams in the Marina Bay district prioritize tri-mode wireless chipsets unifying 2.4GHz, Bluetooth 5.3, and wired USB-C connectivity. The Infocomm Media Development Authority's workplace technology grants support ergonomic equipment deployment in fintech and legal services. Regional headquarters operations drive standardization across ASEAN subsidiary networks.
Ergonomic Mouse Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel access, producing a tiered structure where premium positioning requires clinical validation documentation. Market concentration sits at the high end, with three to four Swiss and American engineering-led firms capturing enterprise fleet contracts. Two strategic archetypes dominate: vertically integrated peripheral specialists with in-house sensor fabrication, and occupational health service bundlers with direct insurer relationships. Competitive moves center on REACH compliance pre-certification to unlock German reimbursement channels, and biometric assessment integration to displace traditional electronics distribution.
Within the occupational health bundler tier, Posturite and Evoluent exemplify the direct-contracting model that has displaced traditional distribution in German-speaking Europe. Logitech anchors the premium engineering segment through Swiss heritage positioning in wireless vertical designs. These three occupy distinct competitive spaces: Posturite through Betriebskrankenkassen-approved vendor lists, Evoluent through clinical therapy protocol validation, and Logitech through enterprise IT standardization at financial services headquarters.
| Leading Market Players |
|---|
| Posturite |
| Razer |
| Delux |
| Microsoft |
| Anker |
| Contour Design |
| Logitech |
| Kensington |
| Evoluent |
| Others |
Pricing and Supply Chain Analysis
REACH authorization timelines for restricted substances gate both qualified supply and premium-tier pricing access, as ECHA's 2024 candidate list expansion forces reformulation of rubberized grips before German industrial insurers approve reimbursement claims.
Pricing Analysis
Warranty and biometric assessment bundling separates enterprise fleet contracts from unbundled retail purchases, with occupational health service inclusion commanding price multiples. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and REACH compliance documentation. Price differentiation rests on CE marking tier and volume scale, with bulk corporate agreements compressing per-unit margins. Cost compression in economy tiers is intensifying because polymer input volatility squeezes housing manufacturers.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese and South Korean fab capacity for high-precision DPI optical sensor modules. Manufacturing concentrates in China, Malaysia, and Vietnam for final assembly, drawing from polycarbonate resin production in the Rhine-Ruhr corridor. Raw material dependencies include ABS housings, rubberized grip compounds, and LED illumination components. Tariff exposure on Chinese-assembled electronics threatens margin stability. Distribution runs through direct occupational health contracting and traditional electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical sensor fab capacity constraints prop pricing power for qualified suppliers, creating supply-constrained dynamics that favor incumbents with established foundry relationships.
For Market Incumbents: Acquire clinical validation documentation assets to defend against emerging therapy-protocol competitors. Secure backward integration into sensor module sourcing to reduce Taiwanese fab dependency. Deepen Betriebskrankenkassen-approved vendor list positioning before EU Machinery Directive amendments tighten certification requirements. For New Entrants and Emerging Players: Occupational health service bundlers represent the most penetrable channel partner type for SME professional services firms in France and Italy. Target direct sales infrastructure for mid-size legal and accounting practices lacking procurement departments. Pursue gaming-ergonomics crossover positioning with high-DPI specifications to command premium tiers above standard office equipment. For Investors and Strategic Acquirers: ECHA candidate list expansions are the leading indicator that REACH compliance depth will determine acquisition viability across the analysis window. Long-term viability favors targets with pre-certified polymer formulations and established German reimbursement channel access. Monitor EU Machinery Directive amendment timing as the inflection signal for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | ECHA compliance documentation unlocks German industrial insurance reimbursement channels before competitors. |
| Tri-Mode Wireless Chipset Integration | Unified 2.4GHz, Bluetooth 5.3, and USB-C connectivity captures financial services fleet standardization mandates. |
| Biometric Assessment Service Bundling | Direct occupational health contracts displace traditional electronics distribution in London and Zurich corporate accounts. |
| Clinical Validation Study Sponsorship | 18-24 month occupational therapy trials establish carpal tunnel syndrome claim credibility for insurance subsidy eligibility. |
| Polymer Formulation Partnership | PC/ABS blend reformulation secures supply continuity as brominated flame retardants face ECHA authorization restrictions. |
Research Methodology
Document review covered SEC filings from peripheral manufacturers, ECHA REACH candidate list updates, and OSHA workplace ergonomics enforcement records, complemented by interviews with enterprise facilities management directors, occupational health procurement officers, Betriebskrankenkassen reimbursement administrators, and optical sensor module suppliers. Secondary validation drew from customs trade data, EU Machinery Directive amendment tracking, and hospital procurement database analysis. Bottom-up shipment estimates triangulated against top-down market sizing across connectivity protocol and end-user segments.
Segment-level projections across product type, end user, technology, and size dimensions fed into consolidated value estimates over the projection horizon. CAGRs were derived from weighted average growth trajectories across German reimbursement expansion, US OSHA enforcement intensity, and Bluetooth Low Energy enterprise adoption curves. Modeling incorporated polymer input cost indices, optical sensor fab capacity utilization, and CE marking timeline assumptions specific to injury-prevention peripheral classification.
Caveats apply where ECHA substance restriction accelerations, FDA device reclassification decisions, or optical sensor supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions about reimbursement policy continuity and enterprise fleet refresh cycle timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Smart Speaker Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
Electric Water Bottle Market
Consumer Electronics
Ultra-Portable Speakers Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Zipline Kits Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Smartphone Sanitizer Market
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Gaming Laptop Market