
 Radar Warning Receiver Market | 2026-2036
Radar Warning Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Warning Receiver Market Analytics
Defense leasing and performance-based sustainment contracts are narrowing the competitive field for radar warning receiver programs. Northrop Grumman leverages its position on the F-35 distributed aperture system to anchor long-term electronic warfare integration. Saab AB competes through sovereign European production lines that sustain national security autonomy. Raytheon Technologies Corporation dominates US naval platform retrofits with manufacturing scale that controls lifecycle cost structures.
A radar warning receiver detects and analyzes incoming radio frequency emissions from hostile radar systems, typically operating across 0.5 to 40 GHz bands to provide threat classification and azimuth data to platform crews. The device functions as a critical survivability subsystem for combat aircraft, surface vessels, and ground vehicles by enabling timely countermeasure deployment or evasive maneuvering. Airborne platforms lead procurement volume due to fifth-generation fighter integration requirements, while software-defined technology represents the fastest-growing architecture as militaries demand programmable threat libraries and rapid firmware updates. Ground-based systems occupy mature replacement cycles with concentrated margin pools in depot-level overhaul services.
The US Department of Defense mandates MIL-STD-461G electromagnetic compatibility and MIL-STD-464C system-level survivability standards that shape receiver design architectures and testing protocols. European procurement aligns with NATO STANAG 4370 environmental testing and the EU's developing defense industrial readiness benchmarks, which condition cross-border collaborative program eligibility. Stakeholders must monitor spectrum allocation decisions by national regulators and the pace of gallium nitride transmitter adoption in adversary radar systems, as these factors determine receiver sensitivity requirements and platform retrofit priorities.
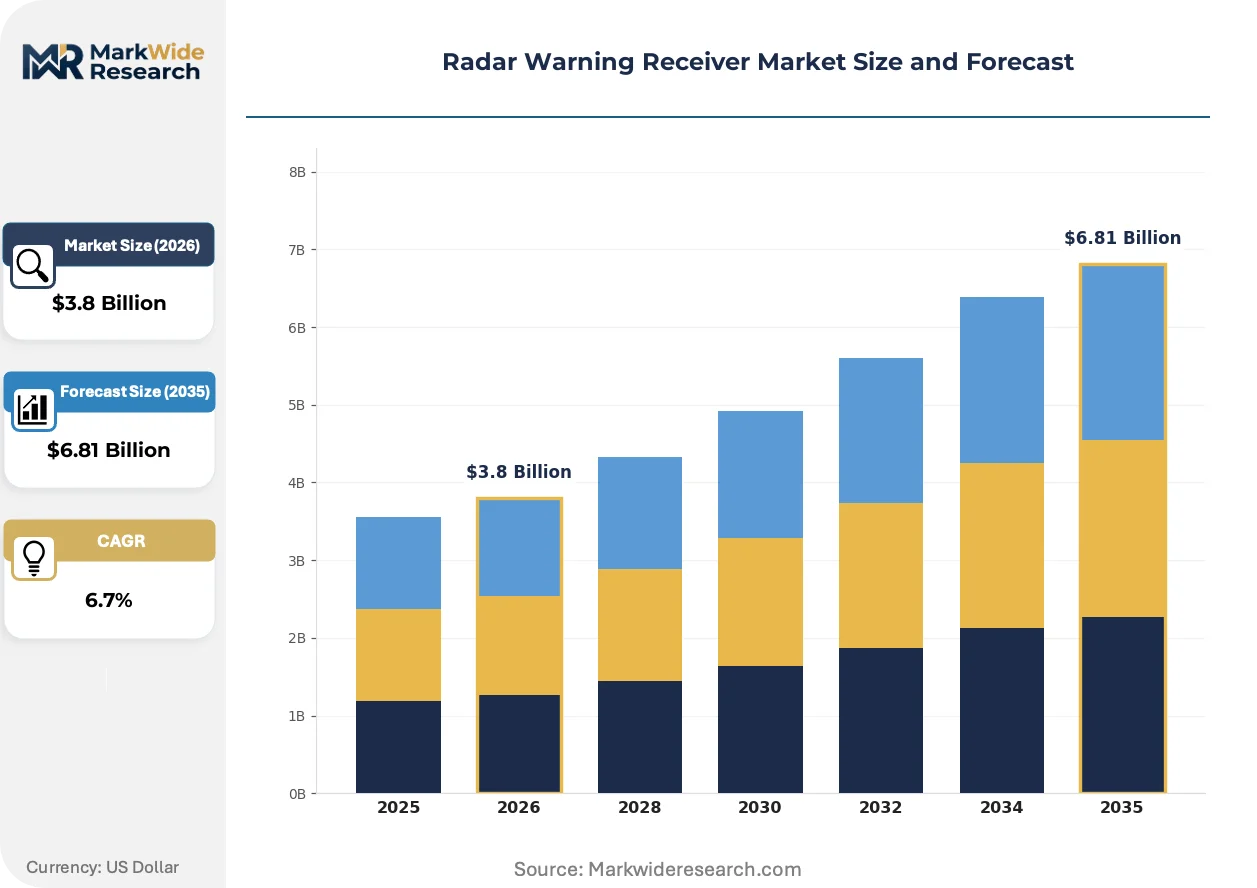
Market Dynamics
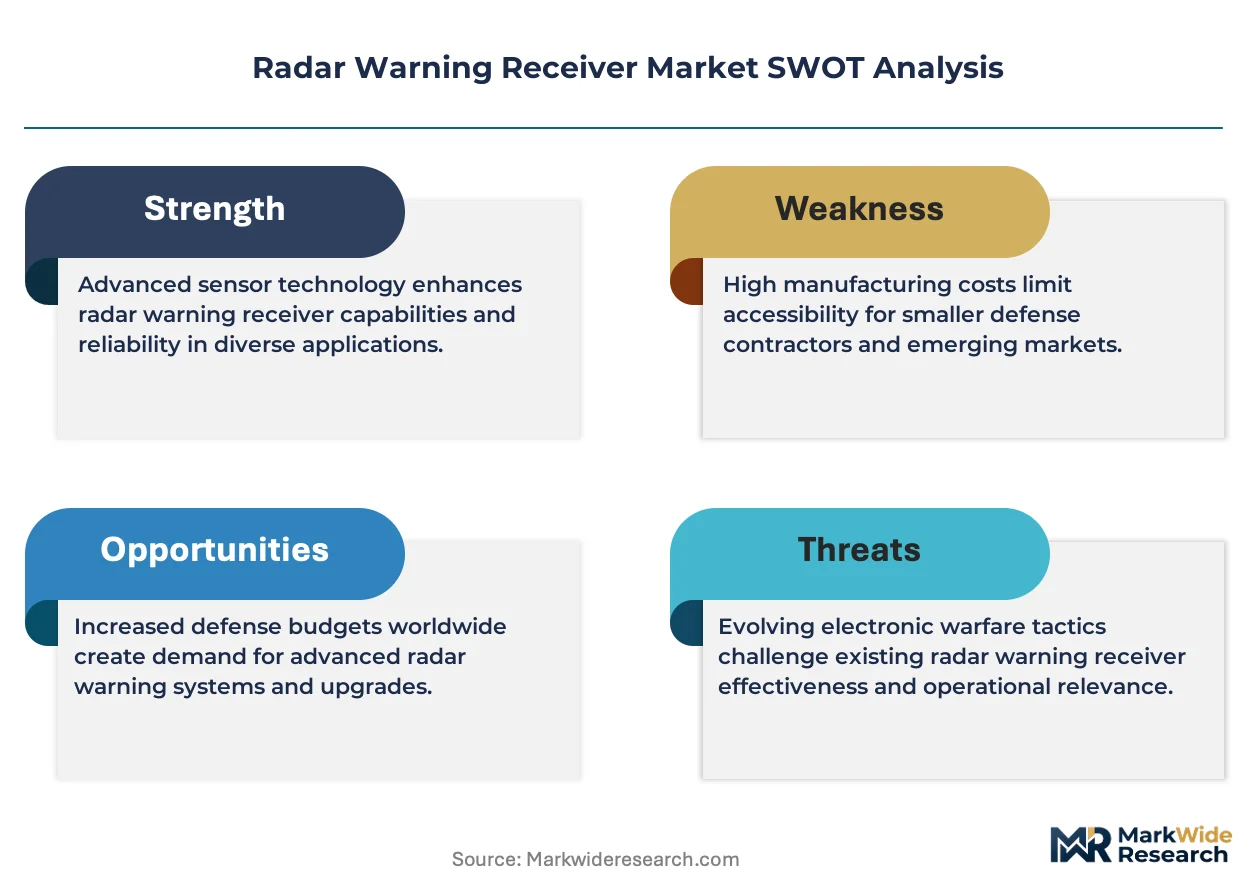
The Radar Warning Receiver Market is being fundamentally restructured by gallium nitride transmitter proliferation in adversary radar systems, which demands receiver sensitivity upgrades across NATO and allied platforms. This technical pressure cascades through procurement specifications, testing protocols, and platform retrofit priorities.
Growth Catalysts
- F-35 Distributed Aperture Integration:The fighter's electronic warfare architecture mandates receiver compatibility with sensor fusion networks, creating sustained procurement volume for qualified suppliers.
- MIL-STD-464C Survivability Mandates:US Department of Defense system-level electromagnetic protection standards require receiver architectures that withstand high-power microwave threats and directed energy environments.
- Software-Defined Radio Architectures:Programmable threat libraries enable rapid firmware updates without hardware replacement, compressing operational testing cycles and extending platform service life.
Market Restraints
- Gallium Arsenide Component Supply Concentration:Specialized semiconductor foundries in Taiwan and the United States control high-frequency receiver front-end manufacturing, creating single-source vulnerability.
- ITAR Export Control Friction:US International Traffic in Arms Regulations restrict receiver technology transfer to non-allied nations, limiting addressable market scope for American suppliers.
- Digital Receiver Latency Constraints:Wideband instantaneous frequency measurement architectures face fundamental processing delays that compromise threat reaction time against low-probability-of-intercept radars.
Strategic Opportunities
- Next Generation Air Dominance Unmanned Platforms:US Air Force collaborative combat aircraft programs require distributed, low-signature warning receivers that legacy suppliers have not yet qualified.
- EU Defence Industrial Readiness Benchmarks:European Union cross-border collaborative program eligibility conditions create procurement preference for sovereign production lines within member states.
- Machine Learning Threat Classification:Neural network pattern recognition converges with open-architecture receiver hardware to reduce operator cognitive load and false alarm rates.
Industry Challenges
- Radio Frequency Engineer Scarcity:Specialized expertise in microwave circuit design and electromagnetic compatibility testing concentrates at legacy defense contractors and national laboratories.
- MIL-STD-461G Certification Timelines:Electromagnetic interference qualification protocols extend development schedules by 18-24 months for new receiver variants.
- Legacy Platform Analog Integration:Cold War-era aircraft with federated avionics architectures require costly interface adapters to host modern digital warning receivers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Warning Receiver Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-Based, Airborne, Naval, Portable Technology: Digital, Analog, Hybrid, Software-Defined Application: Military, Homeland Security, Defense, Surveillance End User: Government, Defense Contractors, Private Security, Research Institutions |
| Companies Covered | Northrop Grumman, Saab AB, Lockheed Martin Corporation, Elbit Systems, Thales Group, Raytheon Technologies Corporation, Leonardo S.p.A., HENSOLDT, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Warning Receiver Market Evolving Landscape
Receiver architectures are migrating toward cognitive electronic warfare capabilities that autonomously characterize and counter emerging threats. This shift compresses the traditional threat library update cycle from years to operational hours.
Digital radio frequency memory technology is migrating from laboratory demonstration to operational deployment across fifth-generation fighter programs. The US Navy and Air Force are fielding these systems for coherent false target generation. This migration from analog delay-line techniques is enabling programmable deception waveforms that adapt to specific adversary radar modes in real time.
The European Union's developing defence industrial readiness benchmarks are conditioning cross-border collaborative program eligibility on supply chain transparency and technology sovereignty. Member states including France, Germany, and Italy are aligning national procurement with these standards. Airborne electronic warfare programs in these countries now require certified European production lines for critical receiver subsystems.
Defense agencies are consolidating electronic warfare suite procurement under single prime contractors rather than acquiring warning receivers as standalone items. The US Department of Defense and UK Ministry of Defence have shifted to this model for major platform upgrades. This concentration is most visible in F-35 and Eurofighter Typhoon programs, where subsystem suppliers must integrate through designated platform integrators.
Radar Warning Receiver Market Segmentation
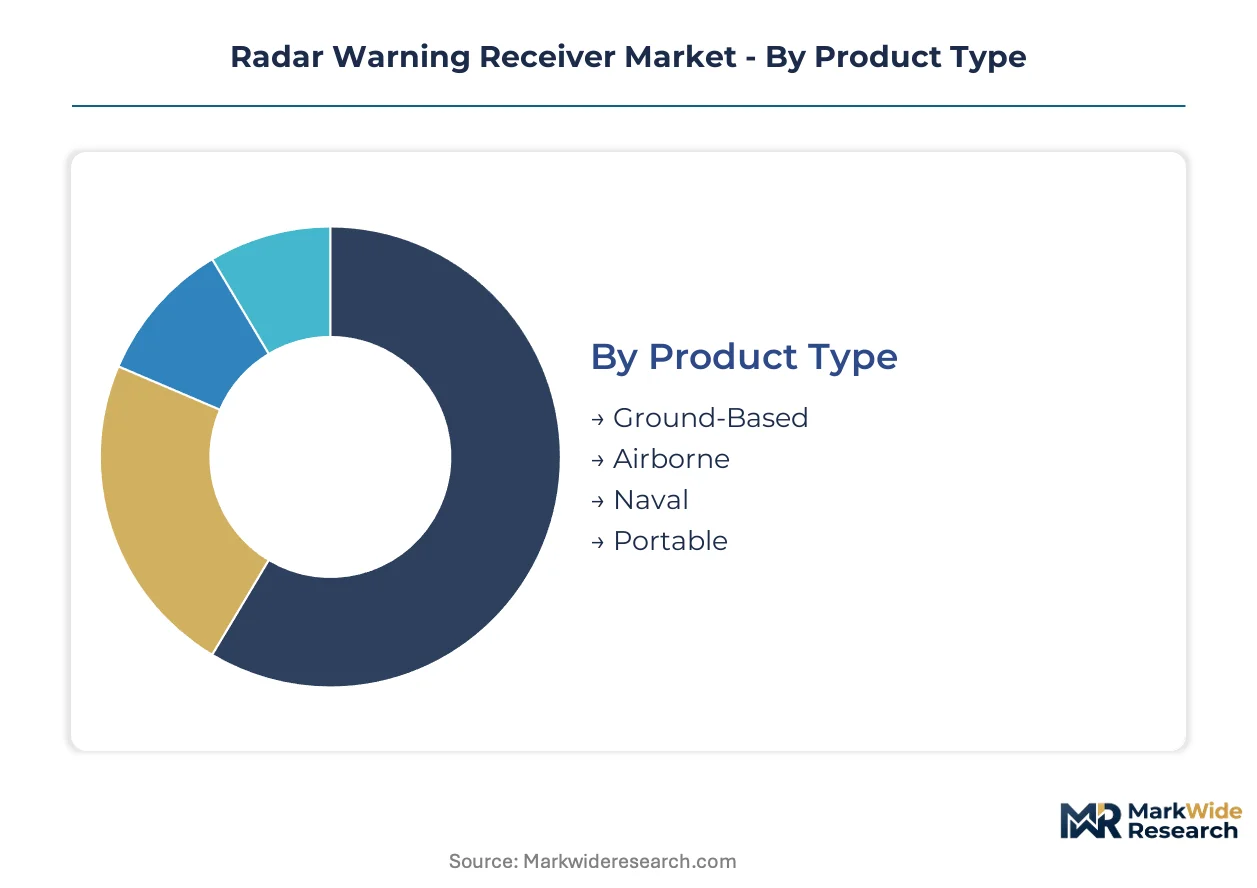
Segmentation in radar warning receiver procurement reveals divergent technical specifications and sustainment intensity across platform types. Military buyers prioritize receiver sensitivity and threat library interoperability over unit cost, creating aftermarket service pools that rival original equipment margins.
Product Type:
After-sales service intensity varies dramatically by installation permanence, with fixed ground stations demanding continuous calibration support while portable units require rapid field replacement logistics.
- Airborne:These receivers operate across 0.5 to 40 GHz bands with instantaneous frequency measurement architectures for fighter aircraft self-protection. Demand concentrates in United States F-35 and Next Generation Air Dominance programs where sensor fusion integration mandates qualified supplier relationships.
- Ground-Based:Fixed-site installations provide hemispherical coverage for air defense networks with depot-level overhaul cycles extending operational life. European NATO members sustain national security autonomy through sovereign production lines for these systems.
- Naval:Shipboard receivers withstand corrosive maritime environments while integrating with combat management systems.
- Portable:Man-packable units deliver dismounted threat warning for special operations forces with battery-powered constraints.
By volume, Airborne leads. By growth pace, Naval is gaining share fastest as surface fleet modernization accelerates.
Technology:
Cost tier stratification separates legacy analog architectures from premium software-defined platforms, with hybrid systems occupying a transitional middle band.
- Software-Defined:Programmable threat libraries enable rapid firmware updates without hardware replacement, compressing operational testing cycles. United States Department of Defense procurement favors these architectures for spectrum superiority mandates.
- Digital:Wideband digital radio frequency memory enables coherent false target generation against adversary fire control radars. Adoption concentrates in fifth-generation fighter programs where real-time waveform adaptation proves critical.
- Hybrid:Mixed-signal designs bridge legacy platform analog interfaces with modern processing backbones.
- Analog:Delay-line techniques persist in Cold War-era platform retrofits constrained by federated avionics architectures.
By deployment share, Digital leads. By expansion trajectory, Software-Defined climbs the fastest as militaries demand programmable threat response.
Application:
Volume concentration tracks defense budget allocation patterns, with military procurement dominating while homeland security represents an emerging adjacent market.
- Military:Combat aircraft, surface vessels, and ground vehicles require threat classification and azimuth data for countermeasure deployment. Procurement specifications emphasize MIL-STD-464C survivability against high-power microwave threats.
- Defense:National military establishments fund platform-integrated electronic warfare suites through single prime contractor consolidation models visible in F-35 and Eurofighter Typhoon programs.
- Homeland Security:Border surveillance and critical infrastructure protection drive demand for fixed-site warning networks with civil airspace coordination requirements.
- Surveillance:Intelligence collection platforms prioritize receiver sensitivity for passive detection of adversary emissions.
By program value, Military leads. By procurement momentum, Homeland Security shows steepest expansion as border monitoring investments multiply.
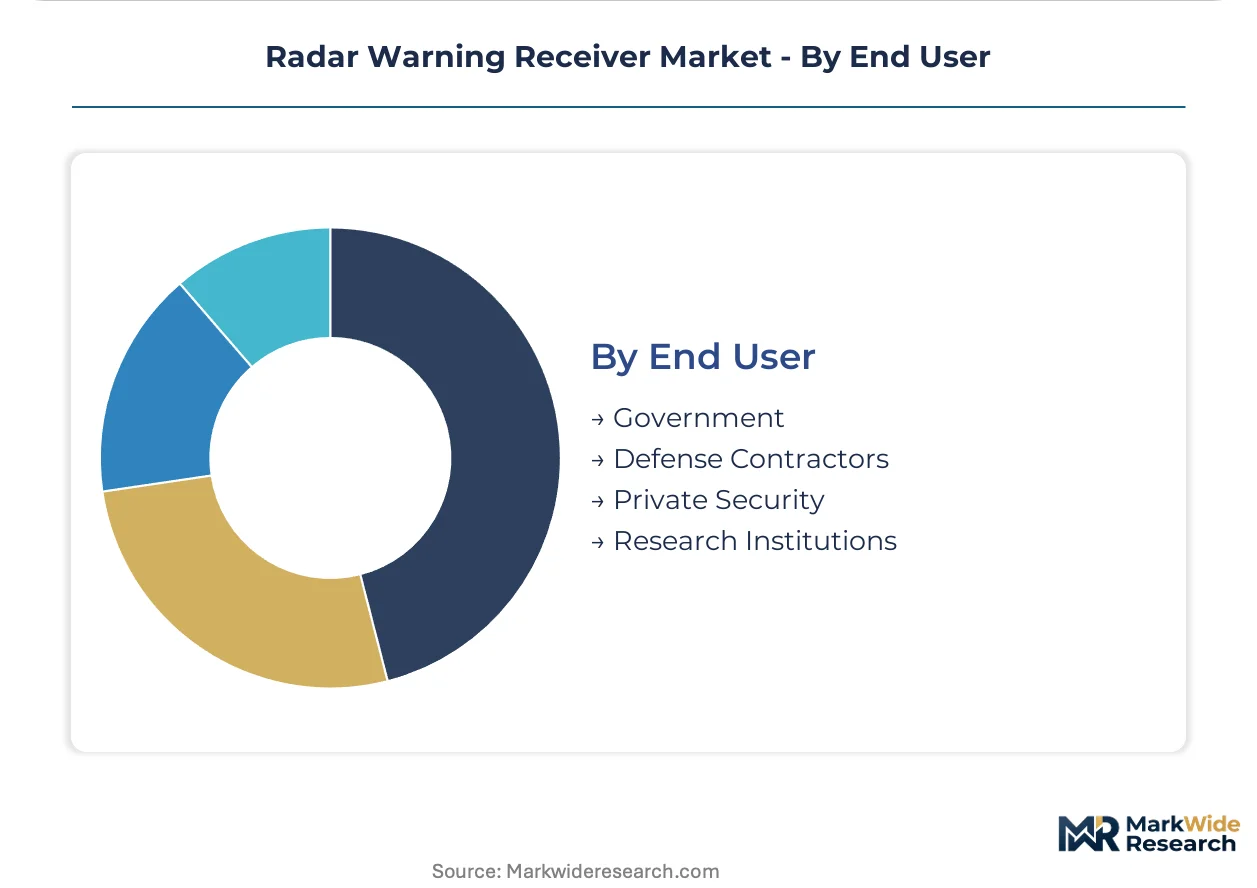
End User:
Customer type determines contracting structure, with government direct procurement favoring performance-based sustainment while defense contractors intermediate subsystem integration.
- Government:National defense agencies specify electromagnetic compatibility standards and control technology transfer through ITAR restrictions. United States Department of Defense mandates shape receiver design architectures and testing protocols.
- Defense Contractors:Platform integrators consolidate electronic warfare suite procurement, requiring subsystem suppliers to qualify through designated prime relationships.
- Private Security:Commercial operators purchase portable receivers for executive protection and high-value asset monitoring within regulatory constraints.
- Research Institutions:National laboratories concentrate specialized radio frequency engineering expertise for prototype development and threat library validation.
By contract volume, Government leads. By commercial flexibility, Defense Contractors are expanding most quickly as platform integration consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in NATO member states and major allied nations concentrate demand for radar warning receivers through fighter modernization programs and electronic warfare suite consolidation. National security autonomy mandates and spectrum superiority requirements shape supplier qualification across these buyer archetypes.
United States
The F-35 program and Next Generation Air Dominance initiatives sustain long-term receiver deployment through integrated electronic warfare architectures. MIL-STD-464C survivability mandates from the Department of Defense reshape design specifications and testing protocols. Defense industrial clusters in California and Texas anchor production of distributed aperture systems and software-defined receiver platforms.
United Kingdom
Eurofighter Typhoon electronic warfare upgrades and sovereign combat air program investments drive procurement volume for qualified subsystem suppliers. The Ministry of Defence shifted to single prime contractor consolidation models for major platform upgrades. BAE Systems facilities in Lancashire and Warton concentrate integration expertise for NATO STANAG-compliant receiver architectures.
France
Rafale fighter fleet modernization and FCAS program participation sustain demand for European-sourced warning receiver production. EU Defence Industrial Readiness Benchmarks condition cross-border collaborative program eligibility on supply chain transparency. Thales Group operations in Élancourt and Bordeaux anchor sovereign production lines for critical receiver subsystems.
Germany
Eurofighter electronic warfare retrofits and national combat air system development concentrate procurement in qualified European suppliers. NATO STANAG 4370 environmental testing standards align with developing EU defense industrial benchmarks. HENSOLDT facilities in Taufkirchen and Ulm specialize in high-frequency receiver front-ends for allied platform integration.
Israel
Indigenous fighter programs and export-oriented electronic warfare systems sustain specialized receiver development for compact platform integration. National security doctrine emphasizes autonomous threat library development and rapid firmware adaptation. Elbit Systems operations in Haifa and Beer-Sheva concentrate cognitive electronic warfare capabilities and machine learning threat classification.
Radar Warning Receiver Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions in radar warning receiver procurement. Prime contractors consolidate electronic warfare suite integration while subsystem suppliers qualify through designated platform relationships. Three archetypes dominate: aerospace conglomerates with sensor fusion integration capabilities, sovereign defense electronics specialists with national security mandates, and high-frequency component manufacturers with semiconductor foundry control. Competitive positioning depends on strategic partnerships with platform integrators and geographic expansion into qualified supplier networks.
Within the aerospace conglomerate tier, Northrop Grumman and Lockheed Martin exemplify channel-controlling positions through F-35 distributed aperture integration and next-generation combat aircraft programs. Saab AB and Thales Group represent the sovereign specialist archetype, anchoring European production autonomy through national security-aligned supply chains. Raytheon Technologies Corporation occupies a scale-driven position across US naval platform retrofits and allied export programs.
| Leading Market Players |
|---|
| Northrop Grumman |
| Saab AB |
| Lockheed Martin Corporation |
| Elbit Systems |
| Thales Group |
| Raytheon Technologies Corporation |
| Leonardo S.p.A. |
| HENSOLDT |
| BAE Systems |
| Others |
Value Network & Pricing Analysis
Undercapacity in gallium nitride component foundries across Taiwan and the United States compresses supplier pricing power while inflating long-term contract premiums for radar warning receiver manufacturers serving NATO procurement offices.
Pricing Analysis
Cost-plus contracts with producer price indexation dominate procurement between prime contractors and subsystem suppliers, insulating against raw material volatility in gallium arsenide substrates. Three-tier pricing structure across software-defined, digital, and analog architectures separates premium sensor-fusion-integrated units from legacy platform retrofits. Cost compression in analog receiver tiers intensifies because European defense ministries consolidate electronic warfare suite procurement under single primes. Government direct procurement exhibits lowest price sensitivity due to MIL-STD-464C survivability mandates, while private security buyers face the tightest budget constraints.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for radar warning receiver programs, particularly affecting rare earth magnet procurement for receiver front-ends. Manufacturing concentrates in the United States, Taiwan, and Germany, with specialized semiconductor foundries controlling high-frequency component output. The supply chain draws from gallium nitride wafers, microwave monolithic integrated circuits, and electromagnetic shielding materials. Single-source vulnerability persists in Taiwan-based gallium arsenide foundry capacity. Distribution runs through designated platform integrators rather than direct subsystem sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward consolidated prime contractors across NATO electronic warfare procurement, fragmenting the competitive field for standalone radar warning receiver suppliers.
For Market Incumbents: Entrench platform integrator relationships through F-35 and Eurofighter Typhoon qualification pathways, defending against gallium nitride transmitter proliferation that demands receiver sensitivity upgrades. Deepen backward integration into gallium arsenide foundry partnerships to secure component supply against Taiwan single-source exposure. MIL-STD-461G certification investment remains the critical barrier to entry. For New Entrants and Emerging Players: Build out machine learning threat classification capabilities for Next Generation Air Dominance unmanned platforms, where legacy suppliers lack qualified architectures. European Union Defence Industrial Readiness Benchmarks create procurement preference for sovereign production lines within member states. Target collaborative combat aircraft programs through open-architecture receiver hardware partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a defense-industrial-base consolidation play because spectrum superiority mandates sustain procurement volume regardless of budget cycles. Acquisition candidates include high-frequency component manufacturers with semiconductor foundry control and software-defined radio specialists with programmable threat library IP. Watch for gallium nitride transmitter adoption pace in adversary radar systems as the inflection signal for receiver retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Integration Partnership | Locks in multi-program revenue through F-35 and NGAD platform mandates. |
| Gallium Nitride Foundry Investment | Captures upstream component supply against Taiwan concentration risk. |
| Open Architecture Certification | Enables rapid firmware updates without hardware replacement cycles. |
| European Sovereign Production Line | Qualifies for EU Defence Industrial Readiness Benchmark procurement preference. |
| Machine Learning Threat Library Development | Reduces operator cognitive load in cognitive electronic warfare architectures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Department of Defense procurement databases, NATO STANAG documentation, and SEC 10-K filings from defense electronics suppliers. Primary interviews engaged platform integration engineers, electromagnetic compatibility test directors, military procurement officers, and radio frequency subsystem program managers. Bottom-up triangulation against top-down budget allocation analysis validates volume estimates across airborne, ground-based, naval, and portable receiver segments.
Forecast inputs include fighter modernization program schedules, gallium nitide transmitter proliferation curves, and software-defined architecture adoption rates across the projection horizon. Segmentation dimensions modeled encompass platform type, technology architecture, application domain, and end-user contracting structure. CAGRs derive from program-level procurement volume aggregation and platform lifecycle replacement cycle analysis. Spectrum allocation decisions by national regulators and directed energy threat evolution inform sensitivity scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign European specialists or gallium nitride component foundries would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Global Digital Battlefield Market
Defense and Military Systems and Equipment
Battle Management System (BMS) Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Global Military Laser Designator Market
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market