
 Military Helmet and Helmet Mounted Displays Market | 2026-2036
Military Helmet and Helmet Mounted Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Military Helmet and Helmet Mounted Displays Market Insights
Defense electronics engineering talent is rotating toward helmet-mounted display integration as legacy avionics programs mature and ground-force modernization gains budget priority. BAE Systems plc leverages its decades of electro-optical expertise to sustain competitive positioning in British and Australian helmet programs. Elbit Systems Ltd. anchors Middle Eastern and European demand through vertically integrated night vision and display manufacturing. L3Harris Technologies, Inc. dominates U.S. military helmet-mounted display procurement with broad-spectrum contracts spanning night vision, thermal fusion, and augmented reality subsystems.
Military helmets and helmet-mounted displays comprise protective headgear integrated with optical, sensor, and communication subsystems that project tactical data directly into the operator's field of view, typically employing ballistic composite shells rated against fragmentation and small-arms threats alongside micro-display engines operating at 800×600 to 1280×1024 resolution. These systems serve primarily to enhance situational awareness, reduce target engagement timelines, and enable network-centric warfare coordination for dismounted soldiers. Ballistic helmets and integrated systems occupy the largest product value pools given mandatory force-wide issuance requirements, while augmented reality technology represents the fastest-expanding segment as armies field next-generation soldier modernization kits. Military forces command the dominant end-user share due to scale of procurement, though law enforcement adoption of communication helmets is broadening as SWAT and counterterror units upgrade legacy equipment.
The U.S. Department of Defense mandates NIJ Level IIIA ballistic protection standards through the National Institute of Justice, while NATO STANAG 2920 defines fragmentation and blunt impact test protocols that shape transatlantic product development roadmaps. The EU AI Act and emerging European defence procurement coordination through the European Defence Agency are introducing new compliance layers for helmet-mounted displays with autonomous targeting assistance. Stakeholders must monitor how export control expansions under the U.S. International Traffic in Arms Regulations and evolving European strategic autonomy frameworks reshape supplier eligibility and technology transfer pathways for integrated helmet systems.
Market Dynamics
The integration of augmented reality overlays into ballistic helmet systems is compressing development cycles and forcing suppliers to merge optical, computing, and power management competencies that previously resided in separate industrial silos.
Growth Catalysts
- Enhanced Night Vision Goggle-Binocular Program:The U.S. Army's soldier modernization initiative mandates networked helmet-mounted displays across infantry brigades, creating standardized procurement volumes for fused thermal and image-intensified subsystems.
- NATO STANAG 2920 Harmonization:Transatlantic alignment on fragmentation and blunt impact test protocols reduces certification duplication costs for suppliers serving multiple allied defense ministries.
- Law Enforcement Counterterror Units:SWAT and specialized police response teams in Germany, France, and Australia are adopting military-derived communication helmets for urban operations, extending addressable demand beyond traditional defense channels.
Market Restraints
- Ballistic Composite Input Volatility:Ultra-high-molecular-weight polyethylene and aramid fiber prices fluctuate with aerospace and automotive demand, compressing helmet shell margins during raw material tightness.
- Export Control Concentration:U.S. International Traffic in Arms Regulations and EU dual-use technology frameworks restrict technology transfer pathways, fragmenting supplier eligibility for integrated helmet systems with autonomous targeting assistance.
- Power Density Limitations:Lithium-ion battery energy density constraints restrict continuous augmented reality operation to four-to-six-hour missions, forcing trade-offs between display brightness and mission duration.
Strategic Opportunities
- Underpenetrated Nordic Markets:Sweden, Norway, and Finland are accelerating soldier system modernization to meet NATO interoperability requirements, creating first-mover advantages for helmet-integrated radio and display suppliers.
- EU AI Act Compliance Services:Emerging European Defence Agency coordination on autonomous targeting assistance standards creates advisory and certification service revenue streams for engineering consultancies.
- Micro-LED and Waveguide Convergence:The pairing of emissive micro-display engines with diffractive optical waveguides enables daylight-readable symbology without external occlusion, opening fixed-wing and rotary aviation applications previously blocked by sunlight readability failures.
Industry Challenges
- Electro-Optical Systems Integration Talent:Defense electronics engineering capacity is migrating from legacy avionics programs to ground-force modernization, creating recruitment competition for professionals with combined optical design and embedded software skills.
- Multi-Domain Certification Timelines:Simultaneous compliance with NIJ Level IIIA ballistic standards, electromagnetic compatibility directives, and ITAR export classifications extends product qualification cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Helmet and Helmet Mounted Displays Market |
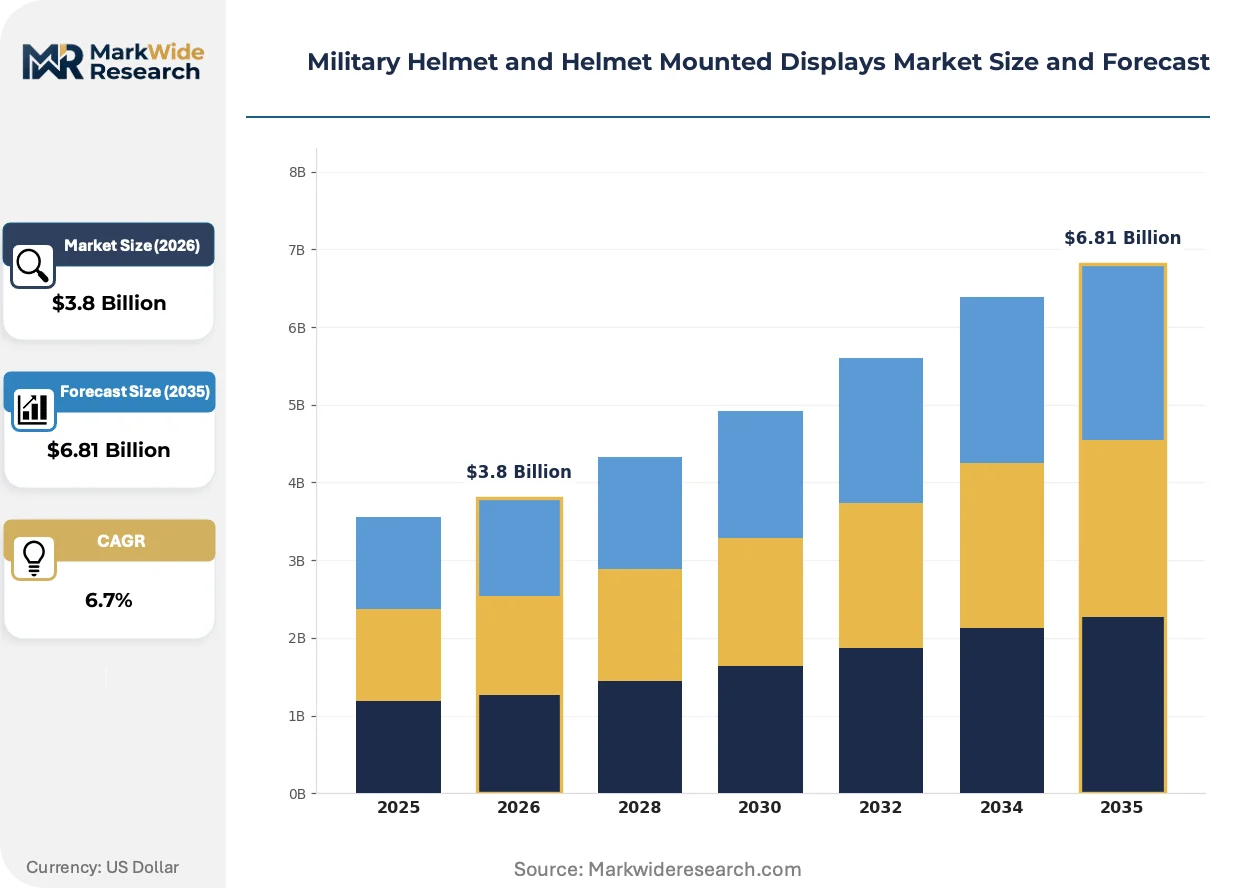
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Combat Helmets, Communication Helmets, Integrated Systems Technology: Augmented Reality, Night Vision, Thermal Imaging, Heads-Up Display End User: Military Forces, Law Enforcement, Security Agencies, Private Contractors Application: Surveillance, Navigation, Target Acquisition, Training |
| Companies Covered | RTX Corporation, BAE Systems plc, L3Harris Technologies, Inc., Thales Group, Elbit Systems Ltd., Honeywell International Inc., Leonardo S.p.A., Gentex Corporation, SAAB AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Helmet and Helmet Mounted Displays Market Trends and Innovations
Helmet-mounted display architectures are splitting into divergent technical paths as mission requirements harden around either lightweight situational awareness or heavy augmented reality computation, reshaping supplier specialization and procurement evaluation criteria.
Waveguide-based optical engines are bifurcating the helmet display market into two distinct performance tiers. Thin, see-through waveguides weighing under 100 grams serve dismounted infantry requiring peripheral vision preservation, while thicker, higher-index substrates support aviation applications demanding wide field-of-view symbology. Special operations forces across Australia and the United Kingdom are fielding the lightweight tier for counterinsurgency patrols, whereas attack helicopter crews in the United States prioritize the heavier configuration for threat detection. This technical schism is compressing vendor R&D budgets as engineering teams must maintain parallel optical design competencies rather than converging on a single dominant architecture.
The EU AI Act's risk classification framework for autonomous targeting assistance is reshaping product development roadmaps for helmet systems with machine-learning-enabled threat recognition. Manufacturers must now document algorithmic decision transparency and human oversight protocols before European Defence Agency-coordinated procurement processes. German and French integrators are responding by segregating AI-enabled features into modular software loads that can be disabled for export to jurisdictions with divergent regulatory interpretations, adding firmware complexity but preserving market access.
Defense ministries are consolidating soldier modernization procurement under single prime contractors rather than fragmenting helmet, display, and radio purchases across separate vendors. The United Kingdom's Morpheus program and Australia's Land 125 Phase 4 both mandate integrated system-of-systems delivery, displacing component-specialist business models. This concentration is most visible in NATO member states pursuing network-centric warfare coordination, where interoperability certification costs favor bundled procurement over best-of-breed assembly.
Military Helmet and Helmet Mounted Displays Market Segmentation
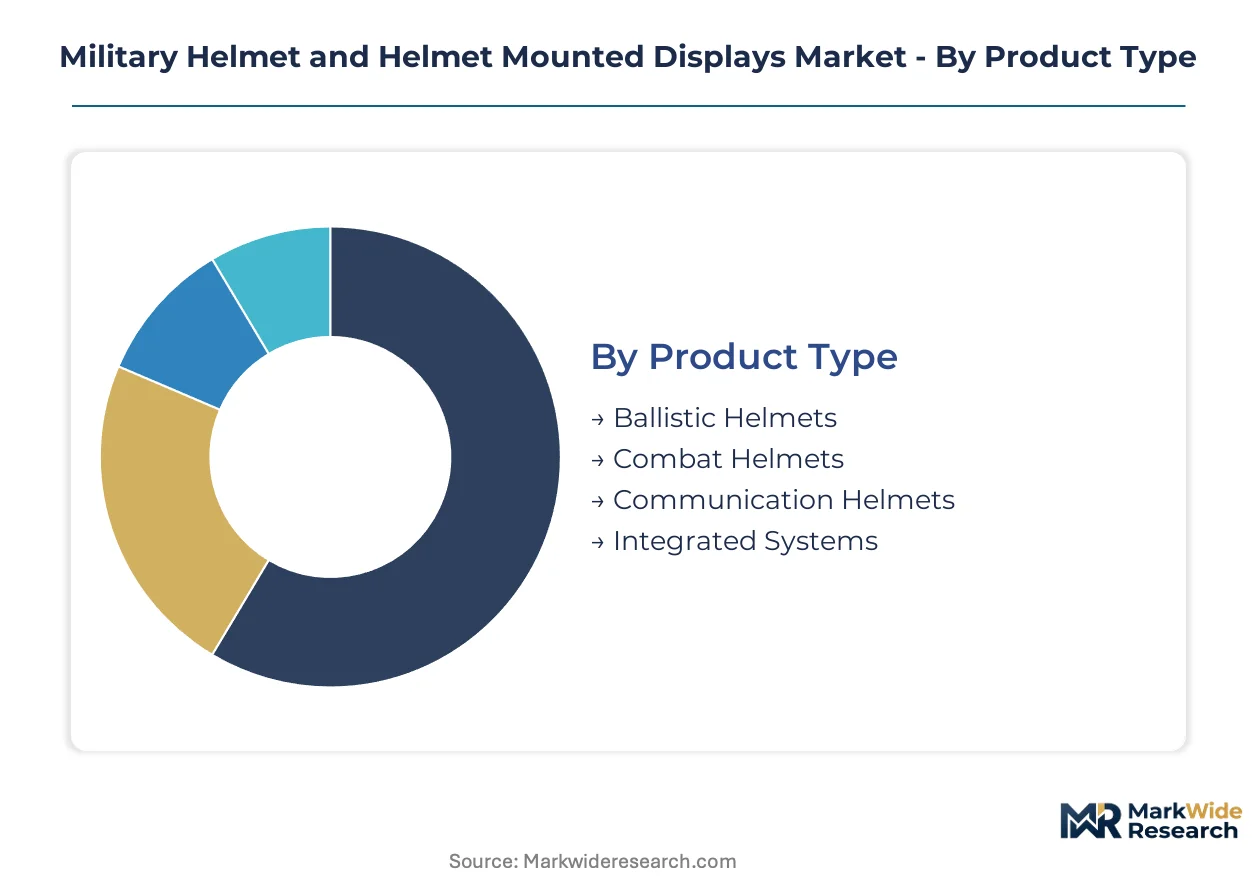
Military helmet procurement splits across protective gear mandates and electronics integration, with margin concentration shifting from shell fabrication toward optical subsystems and software-defined features. Understanding these segment boundaries clarifies where defense budgets allocate modernization dollars versus baseline replacement spending.
Product Type:
Integrated Systems capture the deepest margin pools as armies consolidate radio, display, and power management into single procurement vehicles, while Ballistic Helmets retain volume dominance through force-wide issuance requirements.
- Ballistic Helmets:Composite shells from ultra-high-molecular-weight polyethylene or aramid fibers rated against fragmentation and small-arms threats per NIJ Level IIIA and NATO STANAG 2920 protocols. U.S. Army procurement through Program Executive Office Soldier sustains standardized volumes for infantry brigades despite raw material price volatility.
- Integrated Systems:Helmet-mounted displays fused with communication modules, power distribution, and sensor interfaces in unified architectures. The United Kingdom's Morpheus program and Australia's Land 125 Phase 4 mandate this format, displacing component-specialist suppliers who cannot deliver system-of-systems integration.
- Combat Helmets:Enhanced protective designs with modular rail systems for accessory attachment.
- Communication Helmets:Audio integration for squad-level radio connectivity without full display capability.
Ballistic Helmets hold installed capacity. Integrated Systems is rotating up the share rankings.
Technology:
Volume concentration sits with mature image intensification, while development spending tilts toward augmented reality overlays that merge sensor feeds with network data.
- Night Vision:Image-intensified tubes amplifying ambient light for low-light operations, historically the dominant helmet-mounted display technology. The U.S. Army's Enhanced Night Vision Goggle-Binocular program refreshes this installed base with fused thermal overlay capability.
- Augmented Reality:Digital symbology projected onto transparent waveguides, enabling threat tagging, navigation waypoints, and networked unit positions in the operator's field of view. Special operations forces in Australia and the United Kingdom field lightweight variants for dismounted patrols where peripheral vision preservation matters.
- Thermal Imaging:Uncooled microbolometer arrays detecting infrared signatures for target discrimination in complete darkness.
- Heads-Up Display:Fixed symbology projection for aviation applications requiring weapon cueing and flight data.
Night Vision retains procurement volume leadership. Augmented Reality is climbing the fastest as modernization budgets prioritize situational awareness software.
End User:
Military procurement scales create tier-one supplier relationships, while law enforcement and security segments offer faster sales cycles with smaller contract values.
- Military Forces:National defense ministries issuing force-wide helmet systems through multi-year modernization programs. NATO member states expanding special operations capabilities drive integrated system demand with stringent interoperability certification requirements.
- Law Enforcement:SWAT and counterterror units in Germany, France, and Australia adopting military-derived communication helmets for urban operations.
- Security Agencies:Government protective services requiring ballistic protection with discrete communication capability.
- Private Contractors:Security firms operating in high-threat environments with procurement flexibility outside formal defense acquisition channels.
Military Forces anchor production planning. Law Enforcement is gaining share fastest as police modernization budgets expand.
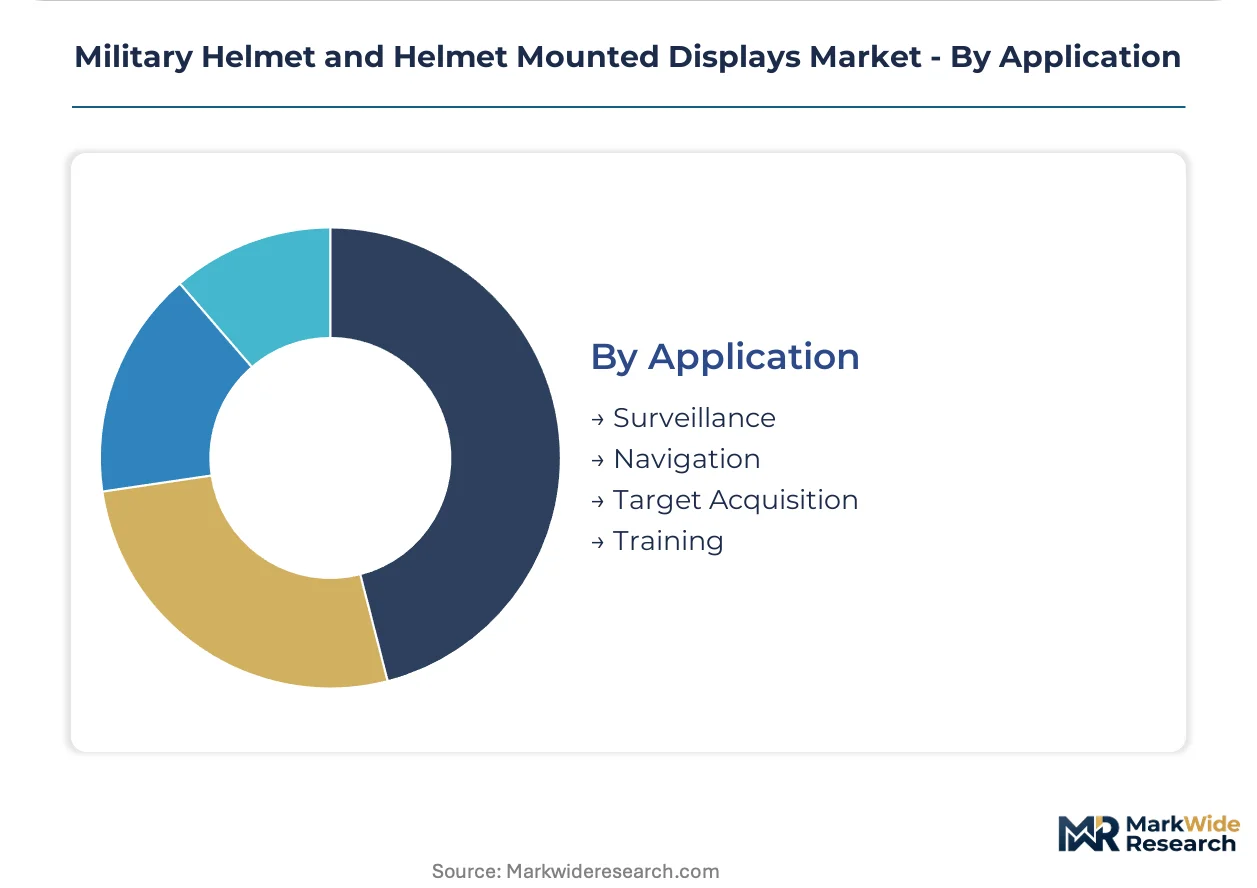
Application:
Navigation and surveillance dominate current fielding, while target acquisition applications face regulatory friction from emerging autonomous targeting standards.
- Surveillance:Persistent observation and perimeter monitoring using stabilized optical sensors mounted on helmet rails. Dismounted infantry in NATO border states prioritize this capability for territorial defense scenarios.
- Navigation:GPS-integrated wayfinding symbology reducing cognitive load during complex terrain movement. The EU AI Act's risk classification framework shapes development roadmaps when navigation cues approach autonomous route selection.
- Target Acquisition:Weapon cueing and threat identification with machine-learning assistance.
- Training:Simulation overlays for force-on-force exercise environments.
Surveillance holds doctrine priority. Navigation is expanding most quickly as networked battlefield coordination requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Defense anchors procurement volumes through Program Executive Office Soldier, with ITAR regulations shaping supplier eligibility across transatlantic technology transfer pathways.
United States
The Enhanced Night Vision Goggle-Binocular program drives integrated helmet-mounted display demand across infantry brigades. ITAR classifications restrict autonomous targeting assistance exports to allied defense ministries. Defense contractors cluster around Huntsville, Alabama and the Boston metropolitan area for electro-optical systems integration.
United Kingdom
The Morpheus program mandates system-of-systems delivery combining radio, display, and power management in unified architectures. Ministry of Defence procurement aligns with NATO STANAG 2920 protocols for fragmentation protection standards. Industrial activity concentrates in Bristol and the Home Counties for soldier modernization engineering.
Germany
Bundeswehr special operations expansion accelerates procurement of lightweight waveguide-based displays for dismounted patrols. The EU AI Act's risk classification framework shapes algorithmic transparency requirements for autonomous targeting features. Engineering consultancies in Munich and Stuttgart advise on compliance certification services.
Australia
Land 125 Phase 4 consolidates helmet, display, and communication purchases under single prime contractors rather than fragmented component sourcing. Defence export controls under the Defence Trade Controls Act govern technology transfer to regional partners. Canberra and Melbourne host system integration facilities for networked battlefield coordination.
Sweden
NATO interoperability requirements accelerate soldier system modernization following 2024 accession. The Swedish Defence Materiel Administration coordinates procurement alignment with transatlantic standardization protocols. Saab AB anchors electro-optical development in Linköping for Nordic market penetration.
Military Helmet and Helmet Mounted Displays Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in military helmet and helmet-mounted display supply. Tier-one primes capture system-of-systems contracts through backward integration into night vision, thermal fusion, and augmented reality subsystems. Specialist fabricators concentrate on ballistic shell production or discrete optical components. Competitive positioning hinges on multi-domain certification capabilities and ITAR-compliant technology transfer pathways.
Among U.S.-based defense conglomerates, L3Harris Technologies, Inc. and RTX Corporation exemplify the integrated prime archetype through electro-optical systems dominance. Elbit Systems Ltd. represents the vertically integrated specialist model with captive manufacturing across night vision and display engines. BAE Systems plc anchors British and Australian procurement through decades of helmet program execution. Gentex Corporation occupies a position in the protective equipment tier with ballistic shell specialization. Thales Group exemplifies European prime contracting for NATO-aligned soldier modernization.
| Leading Market Players |
|---|
| RTX Corporation |
| BAE Systems plc |
| L3Harris Technologies, Inc. |
| Thales Group |
| Elbit Systems Ltd. |
| Honeywell International Inc. |
| Leonardo S.p.A. |
| Gentex Corporation |
| SAAB AB |
| Others |
Pricing and Supply Chain Analysis
Polymer substitution from aramid to ultra-high-molecular-weight polyethylene in ballistic shell fabrication simultaneously relocates manufacturing toward South Korean and Chinese fiber production zones while compressing per-unit helmet costs for NATO procurement programs. This input transition redistributes margin capture from legacy European material suppliers toward integrated system primes with captive polymer sourcing agreements.
Pricing Analysis
Transatlantic price spreads of 15-25 percent separate U.S. ITAR-compliant helmet systems from comparable NATO STANAG-certified equipment sourced through European channels. Three-tier pricing structure across integrated systems, ballistic shells, and component subassemblies dominates procurement, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard ballistic helmets is intensifying because raw material volatility and force-wide issuance mandates squeeze fabricator margins. Military procurement officers exhibit lowest price sensitivity given mission-critical specifications, while law enforcement agencies demonstrate highest sensitivity due to constrained municipal budgets.
Supply Chain Analysis
Strait of Hormuz transit risk concentrates attention on alternative rare-earth magnet supply routes for helmet-mounted display actuators, with processing capacity anchored in China, Malaysia, and Australia. Micro-display engines draw from Taiwanese semiconductor foundries, Japanese optical glass, and German precision coating equipment. Single-source vulnerability in diffractive waveguide manufacturing creates procurement bottlenecks for augmented reality helmet programs. Distribution runs through defense prime contractor networks rather than open commercial channels, with Program Executive Office Soldier and European Defence Agency-coordinated procurement as dominant downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams from algorithmic transparency compliance consulting and field maintenance contracts are expanding faster than hardware shipments as European AI Act enforcement creates recurring certification obligations for helmet system operators.
For Market Incumbents: Consolidate backward integration into micro-display manufacturing to offset waveguide supplier concentration risk and capture margin pools shifting from ballistic shells toward optical subsystems. Lock in multi-year fiber supply agreements with South Korean polymer producers before aerospace demand recovery tightens ultra-high-molecular-weight polyethylene availability. Prioritize NIJ Level IIIA and NATO STANAG 2920 dual-certification investments to maintain eligibility for transatlantic procurement consolidation under Morpheus and Land 125 Phase 4 programs. For New Entrants and Emerging Players: Anchor in Nordic soldier system modernization as Sweden, Norway, and Finland accelerate NATO interoperability procurement with limited incumbent relationships. Target lightweight waveguide-based situational awareness tiers where special operations forces prioritize peripheral vision preservation over augmented reality computation. Pursue EU AI Act compliance service contracts as advisory revenue entry point before competing for integrated system hardware awards. For Investors and Strategic Acquirers: The market sits at a technology refresh phase that favors electro-optical integration specialists over pure-play ballistic fabricators. Long-term viability hinges on software-defined feature roadmaps and network-centric warfare certification relationships. Acquisition target archetype: mid-cap helmet-mounted display engineering firms with ITAR-compliant facilities and existing prime contractor subcontractor status. Signal to watch: European Defence Agency publication of autonomous targeting assistance procurement standards as inflection indicator for compliance service demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Micro-Display Manufacturing | Captures margin migrating from shell fabrication toward optical engines in integrated helmet systems. |
| EU AI Act Compliance Certification Services | Creates recurring revenue layer as European Defence Agency mandates algorithmic transparency documentation. |
| Nordic Market System-of-Systems Entry | Exploits Sweden's NATO accession-driven modernization with limited established supplier relationships. |
| Dual NIJ-STANAG Certification Investment | Preserves transatlantic procurement eligibility as U.S. and European programs consolidate vendor pools. |
| Lightweight Waveguide Product Line Expansion | Addresses special operations demand for peripheral vision preservation in dismounted patrol configurations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with program managers at Program Executive Office Soldier, procurement leads at European Defence Agency-coordinated ministries, electro-optical systems engineers at tier-one primes, and soldier modernization directors at NATO member defense ministries. Secondary validation drew from U.S. Department of Defense budget justification documents, EU AI Act implementation guidance, NATO STANAG 2920 technical specifications, and ITAR classification rulings. Bottom-up unit shipment estimates across ballistic helmet, integrated system, and component categories were triangulated against top-down defense budget allocation analysis.
Across the analysis window, volume and value outputs reflect modeling across product type segmentation, technology tier, end-user category, and application mission profile. CAGRs were derived from weighted regression of historical procurement cycles and announced modernization program timelines. Forecast inputs incorporated lithium-ion battery energy density improvement trajectories, micro-LED display yield curves, and raw material price elasticity assumptions for aramid and ultra-high-molecular-weight polyethylene fiber markets.
Material uncertainties — export control expansion under ITAR, EU strategic autonomy framework implementation, and rare-earth supply disruption scenarios — sit outside the modeled envelope. Forecasts reflect assumptions regarding NATO interoperability standardization continuity and defense budget prioritization for soldier modernization. Practitioners should keep alternative scenarios live as European AI Act enforcement intensity and U.S. administration trade policy orientation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
GCC Defense Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Search and Rescue Equipment Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market
Defense and Military Systems and Equipment
Global Military Laser Rangefinder Market
Defense and Military Systems and Equipment
United Kingdom Defense Market