
 Europe Defense Logistics Market | 2026-2036
Europe Defense Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Defense Logistics Market Insights
Platform lifecycle support revenue is fragmenting across third-party logistics providers and original equipment manufacturers. Rheinmetall AG leverages in-house maintenance capabilities to capture sustainment contracts for armored vehicle fleets. DHL Group competes through specialized military freight networks spanning European NATO corridors. Kuehne + Nagel International AG anchors critical spare parts distribution for naval and aerospace platforms.
Europe defense logistics encompasses the planning, execution, and control of materiel movement and sustainment for military operations, requiring adherence to NATO Standardization Agreements (STANAG) for interoperability across allied forces. The discipline integrates multimodal transport, secure warehousing, and real-time inventory tracking to maintain operational readiness under contested conditions. Transportation solutions within the service type dimension dominate contract value due to the complexity of moving heavy equipment across borders with diplomatic clearances. Automated systems within the technology dimension represent the fastest-expanding segment as militaries deploy autonomous warehousing and predictive maintenance algorithms. Supply chain consulting remains a mature, margin-diluted category where procurement consolidation pressures fee structures.
The EU Green Deal and F-Gas Regulation shape fuel and refrigerant standards for military transport assets, while CE marking requirements govern equipment interoperability across member states. ECHA chemical registration protocols affect materiel handling and hazardous cargo protocols in cross-border defense shipments. Stakeholders must monitor how PESCO-funded infrastructure projects redistribute logistics hub influence across Central and Eastern Europe.
Market Dynamics
NATO's integrated logistics networks are forcing cross-border military supply chain standardization across European allies, compressing procurement timelines while elevating interoperability requirements for materiel movement and sustainment systems.
Growth Catalysts
- PESCO Infrastructure Funding:The Permanent Structured Cooperation framework channels capital into Central and Eastern European logistics hubs, expanding depot capacity and multimodal transport corridors for expeditionary readiness.
- CE Marking Harmonization:Unified equipment certification across EU member states eliminates redundant testing protocols, accelerating cross-border defense procurement and spare parts mobility.
- Poland:Warsaw's defense spending surge drives demand for ammunition storage facilities, fuel distribution networks, and armored vehicle maintenance infrastructure modernization.
Market Restraints
- Specialized Labor Scarcity:Qualified military logistics engineers and hazardous materials handlers face acute shortages across Germany, France, and Poland, inflating wage premiums and contract fulfillment timelines.
- F-Gas Regulation Compliance:The EU's fluorinated gas phase-down mandates refrigerant retrofits for military cold-chain transport, imposing capital burdens on legacy fleet operators.
- Single-Source Dependencies:Critical aerospace spare parts concentrate with limited qualified suppliers in Southern France and Northern Italy, creating vulnerability to production disruptions.
Strategic Opportunities
- Romania:Underdeveloped Black Sea port infrastructure presents greenfield development potential for NATO maritime prepositioning and ammunition staging facilities.
- Autonomous Warehousing Convergence:Integration of robotic material handling with predictive maintenance algorithms enables 24/7 operations in contested electromagnetic environments.
- EU Green Deal Military Exemptions:Emerging carve-outs for defense-critical transport assets create regulatory space for alternative fuel pilot programs without civilian compliance penalties.
Industry Challenges
- NATO STANAG Certification Timelines:Standardization agreement testing for interoperability consumes 18-24 months for new logistics technologies, delaying field deployment against urgent operational requirements.
- Legacy System Integration:Cold War-era inventory management databases resist seamless API connectivity with modern real-time tracking platforms, fragmenting visibility across allied command structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Defense Logistics Market |
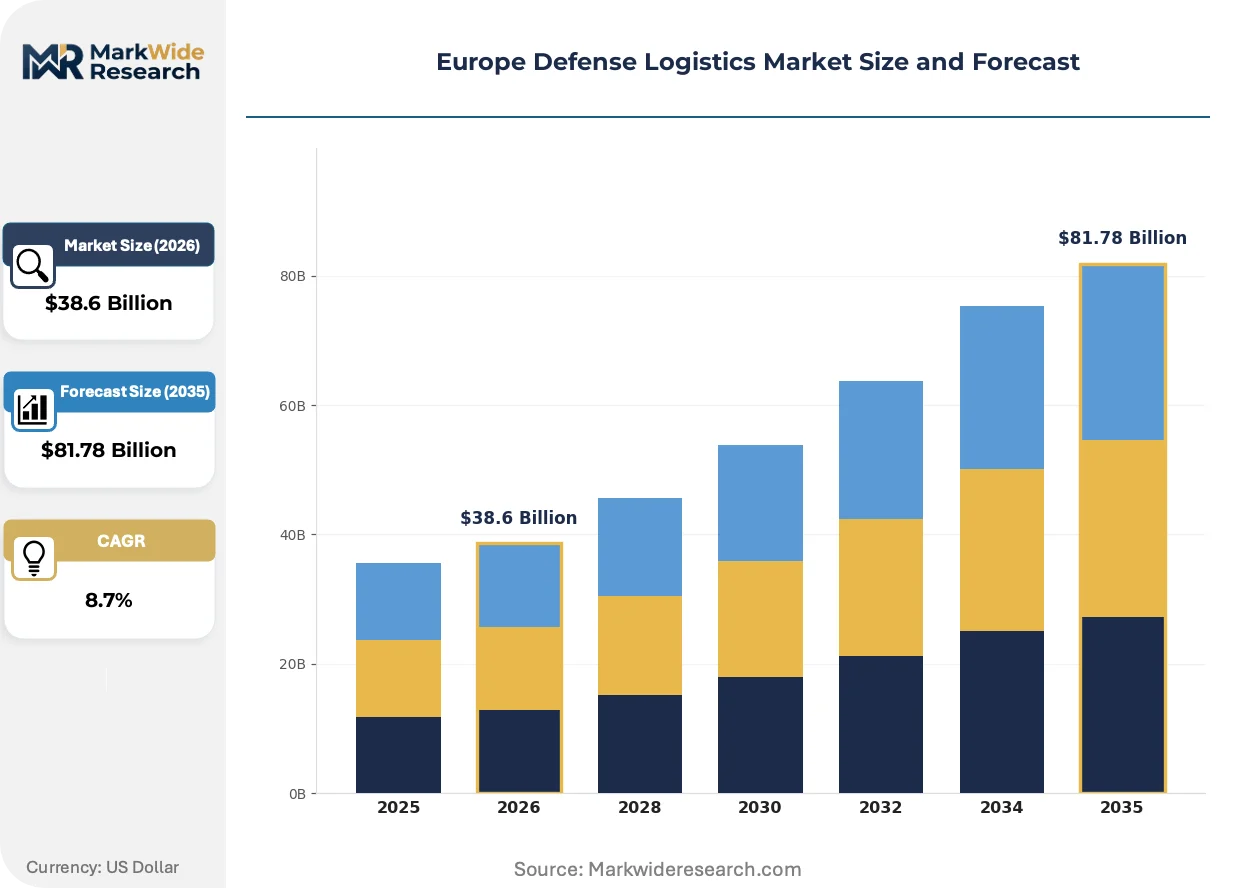
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
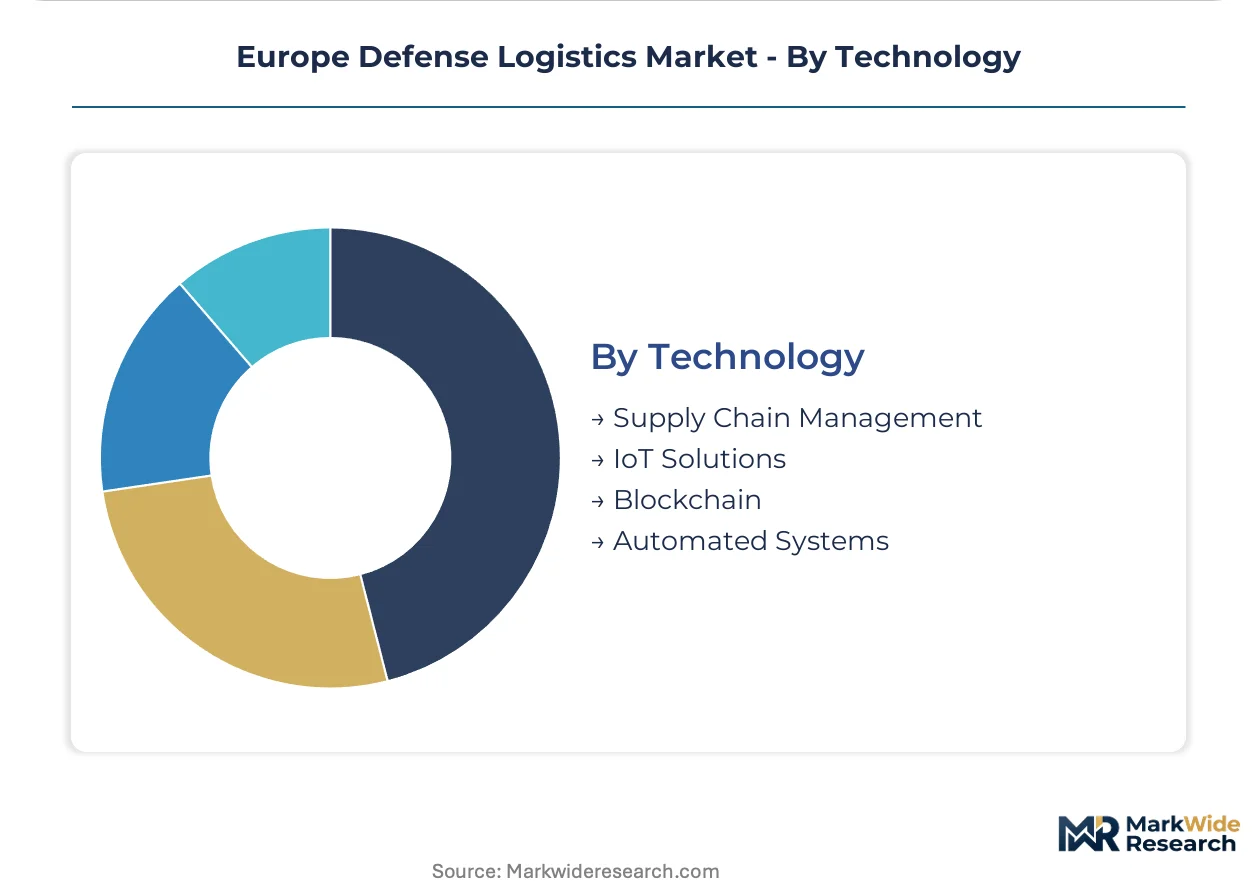
| Segmentation | Logistics Type: Transportation, Warehousing, Inventory Management, Distribution Service Type: Procurement Services, Maintenance Support, Transportation Solutions, Supply Chain Consulting End User: Military, Government Agencies, Contractors, Non-Governmental Organizations Technology: Supply Chain Management, IoT Solutions, Blockchain, Automated Systems |
| Companies Covered | Airbus Defence & Space, DHL Group, BAE Systems, CEVA Logistics, Kuehne + Nagel International AG, Rheinmetall AG, KBR Inc., Thales Group, Leonardo SpA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Defense Logistics Market Trends and Innovations
Digital twin technology and predictive analytics are compressing maintenance cycles while autonomous systems redefine warehouse operations under contested conditions. These shifts demand new capital allocation patterns across European defense ministries and their logistics contractors.
Blockchain-enabled supply chain verification is rendering obsolete paper-based customs documentation and manual diplomatic clearance processes for cross-border military freight. German and French expeditionary units pilot these systems for armored vehicle movements through NATO corridors. The technology is rendering obsolete traditional freight forwarding intermediaries who previously managed clearance complexity through established relationships.
The EU AI Act's risk classification framework imposes algorithmic transparency requirements on automated logistics decision systems deployed in EU member states. Military procurement offices must now document training data provenance and bias testing for predictive maintenance platforms. Naval aviation sustainment contracts in France and Italy face the steepest compliance adjustments given the complexity of their component failure prediction models.
Performance-based logistics contracts now dominate major platform sustainment awards, replacing time-and-materials arrangements with availability guarantees and outcome metrics. Original equipment manufacturers in Germany absorb inventory risk in exchange for per-flight-hour or per-kilometer pricing. This restructuring concentrates most visibly in armored vehicle fleet management agreements across Polish and Baltic defense ministries.
Europe Defense Logistics Market Segmentation
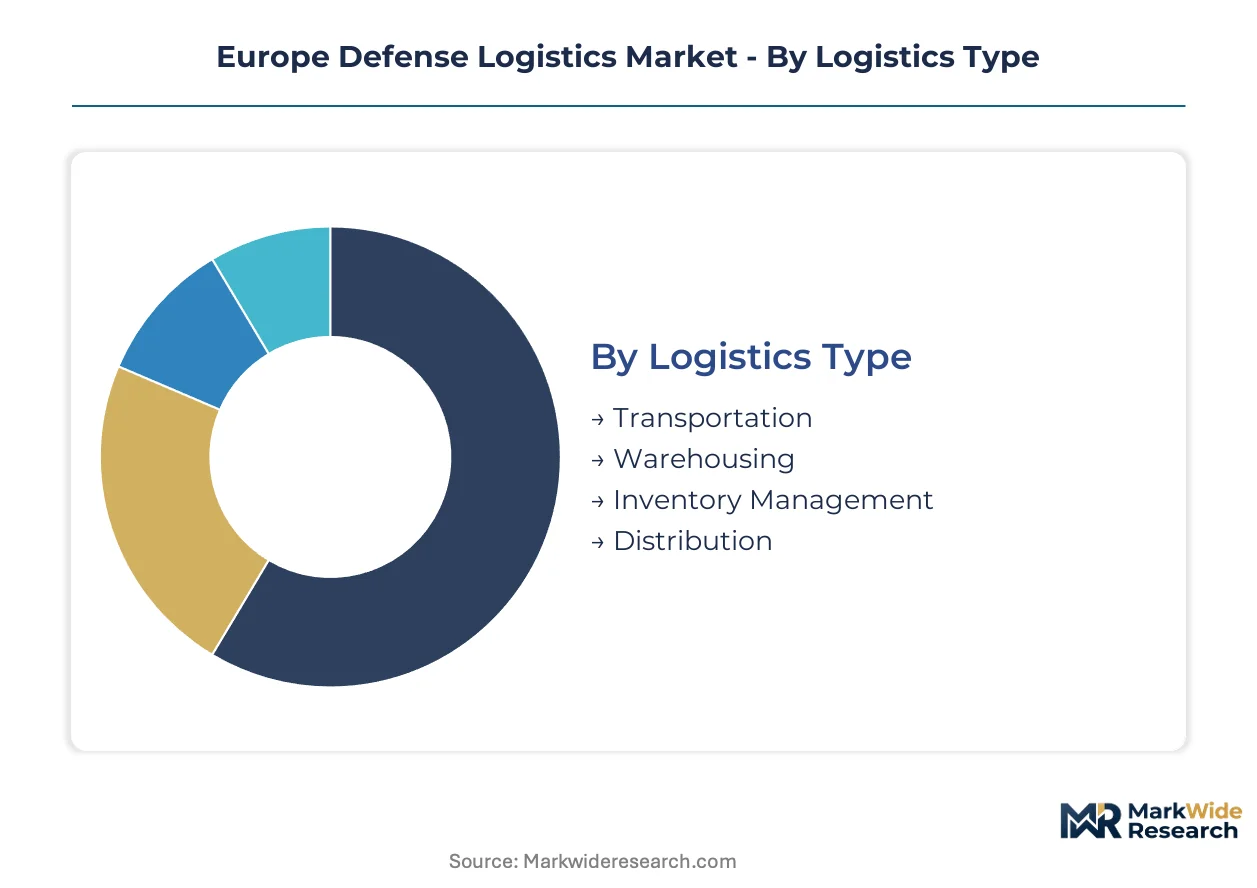
Segmentation in Europe defense logistics reveals how procurement patterns diverge across operational functions, service models, and technology readiness. NATO interoperability mandates and PESCO funding mechanisms reshape which segments capture capital allocation.
Logistics Type:
Cost tier differentiation separates high-complexity cross-border movements from localized depot operations. Capital intensity varies sharply across these operational layers.
- Transportation:Multimodal freight coordination for heavy armor and ammunition convoys demands diplomatic clearance protocols across NATO corridors. German and Polish ministries concentrate procurement here for expeditionary readiness.
- Warehousing:Secure storage facilities with blast-resistant construction and climate control for sensitive materiel. France and Central European allies drive demand through ammunition stockpile modernization programs.
- Inventory Management:Real-time tracking systems for spare parts and consumables.
- Distribution:Last-mile delivery networks to forward operating bases.
Transportation commands the established base. The steepest expansion runs through Warehousing.
Service Type:
Application focus determines contract structure — transactional procurement versus long-term platform sustainment partnerships.
- Transportation Solutions:Cross-border military freight services with NATO STANAG certification for interoperability. Demand concentrates in corridor logistics between Germany, Poland, and Baltic states.
- Maintenance Support:Lifecycle sustainment for armored vehicles, naval platforms, and aerospace systems. Polish defense spending surges are accelerating performance-based contracts with availability guarantees.
- Procurement Services:Strategic sourcing and vendor qualification for defense ministries.
- Supply Chain Consulting:Advisory on logistics network optimization and risk mitigation.
Maintenance Support commands the established base. Transportation Solutions are climbing the fastest.
End User:
Customer type dictates security classification, contract transparency requirements, and payment terms.
- Military:National armed forces requiring NATO-interoperable logistics with classified data handling. Germany, France, and Poland anchor procurement volume through defense budget expansion.
- Government Agencies:Civil defense and interior ministry units with dual-use equipment needs.
- Contractors:Private sector logistics providers serving under ministry oversight.
- Non-Governmental Organizations:Humanitarian and peacekeeping support operations with lighter security requirements.
Military commands the established base. Contractors are gaining share fastest as outsourcing deepens.
Technology:
Maturity gaps separate legacy inventory databases from emerging autonomous and distributed ledger systems.
- Automated Systems:Robotic warehousing and predictive maintenance algorithms enabling 24/7 operations in contested electromagnetic environments. French and German pilot programs validate autonomous materiel handling.
- Blockchain:Distributed ledger verification for customs documentation and diplomatic clearance acceleration. NATO corridor trials between Germany and Poland demonstrate paperless cross-border freight.
- Supply Chain Management:Integrated planning platforms for multi-echelon inventory optimization.
- IoT Solutions:Sensor networks for real-time asset tracking and condition monitoring.
Supply Chain Management commands the established base. Automated Systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense logistics consumption patterns diverge sharply across European states. Germany prioritizes expeditionary multimodal corridors for heavy armor deployment. France concentrates on naval and aerospace sustainment networks. Poland drives ammunition storage and armored vehicle infrastructure modernization.
Germany
Berlin's defense budget expansion funds NATO corridor logistics and heavy equipment transport networks. The KBA regulates military vehicle certification standards for cross-border interoperability. Bavaria hosts Rheinmetall's maintenance complexes serving Central European armored fleets.
France
Naval aviation sustainment and nuclear deterrent logistics dominate procurement allocation. The ANSM oversees hazardous materiel handling protocols for submarine and carrier supply chains. Toulouse and Marseille anchor aerospace and maritime logistics clusters respectively.
Poland
Warsaw's defense spending surge drives ammunition depot construction and fuel distribution network expansion. PESCO infrastructure funding accelerates Central European hub development. Poznań and Gdańsk concentrate new NATO prepositioning facilities and multimodal transport terminals.
United Kingdom
Post-Brexit logistics arrangements prioritize bilateral NATO agreements over EU frameworks. The Ministry of Defence maintains autonomous clearance protocols for expeditionary force deployment. BAE Systems anchors sustainment operations across Portsmouth and Barrow-in-Furness naval clusters.
Italy
Naval platform lifecycle support and Mediterranean corridor logistics shape procurement priorities. Leonardo SpA integrates maintenance capabilities for regional aerospace and maritime fleets. La Spezia and Taranto concentrate submarine and surface vessel sustainment infrastructure.
Europe Defense Logistics Market Competitive Landscape
Capability concentration sits with defense-integrated industrial groups; scale advantage sits with specialized logistics multinationals. The market structures around three tiers: original equipment manufacturers with captive sustainment arms, third-party military logistics providers, and platform-agnostic freight specialists. Strategic moves center on performance-based contracting restructuring and autonomous warehousing technology partnerships.
Among defense-integrated industrial groups, Rheinmetall AG and Leonardo SpA exemplify the OEM-sustainment convergence archetype. Within specialized military logistics, DHL Group and Kuehne + Nagel International AG occupy positions spanning NATO corridor freight and critical spare parts distribution. These named entities represent distinct competitive vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Airbus Defence & Space |
| DHL Group |
| BAE Systems |
| CEVA Logistics |
| Kuehne + Nagel International AG |
| Rheinmetall AG |
| KBR Inc. |
| Thales Group |
| Leonardo SpA |
| Others |
Pricing and Supply Chain Analysis
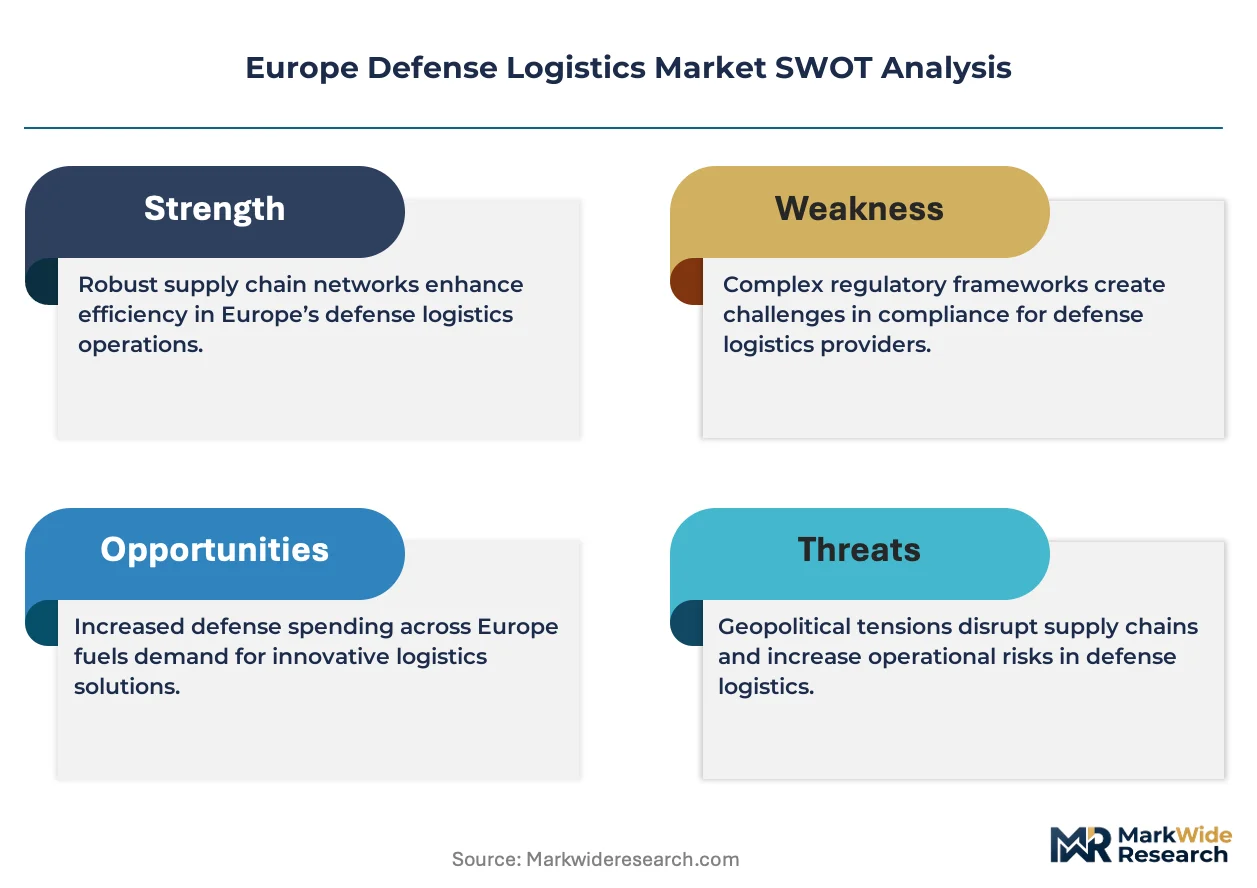
Depot undercapacity across Poland and the Baltic states drives supplier selection toward firms with guaranteed throughput commitments, compressing margins for speculative bidders while rewarding capital-heavy operators with pre-positioned infrastructure. NATO STANAG certification requirements add fixed compliance costs that smaller freight forwarders cannot amortize, concentrating pricing power with integrated logistics providers holding multi-year framework agreements.
Pricing Analysis
Long-term performance-based contracts dominate platform sustainment, replacing transactional spot arrangements with availability guarantees and per-kilometer pricing structures. Price differentiation hinges on NATO STANAG certification tier and after-sales service bundling, with fully certified providers commanding substantial premiums over corridor-only operators. Cost compression in ammunition transport reflects Poland's aggressive depot expansion and resulting capacity glut. Government procurement offices exhibit highest price sensitivity, while expeditionary force commands prioritize mission assurance over unit cost.
Supply Chain Analysis
Tariff exposure between EU member states and post-Brexit UK disrupts cross-border component flows for naval platform sustainment, forcing inventory pre-positioning at higher carrying cost. Supply concentration rests on Germany, France, and Poland for heavy armor maintenance infrastructure, with specialized aerospace spares drawing from Southern France and Northern Italy. Single-source vulnerability pervades precision navigation component supply. Distribution runs through NATO corridor networks with multimodal handoffs at Poznań, Gdańsk, and Rotterdam hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment via NATO STANAG certification creates formidable defensive moats, as 18-24 month approval timelines and specialized testing infrastructure requirements lock out speculative entrants.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into autonomous warehousing technology partnerships and securing exclusive maintenance rights for Polish armored vehicle fleets. The EU AI Act's algorithmic transparency mandates threaten predictive maintenance platform margins. Vertical integration into robotic material handling systems provides differentiation against third-party logistics challengers. For New Entrants and Emerging Players: Pursue underdeveloped Romanian Black Sea port infrastructure for NATO maritime prepositioning facilities, where greenfield development avoids entrenched competitor relationships. Romania presents the most penetrable geography given PESCO funding inflows and absence of established depot operators. A go-to-market angle anchored in EU Green Deal military exemption compliance for alternative fuel pilot programs bypasses incumbent fossil-fuel infrastructure advantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated systems segments as robotic warehousing and predictive maintenance platforms require substantial upfront deployment capital. Long-term viability favors acquisition targets with captive NATO certification capabilities and established ministry relationships. The signal to watch is PESCO infrastructure grant disbursement velocity, which indicates hub development priority and contract award timing.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contract Conversion | BAE Systems and Rheinmetall absorb inventory risk for Polish ministry availability guarantees. |
| Autonomous Warehousing Technology Partnership | French and German pilot programs validate robotic material handling in contested electromagnetic environments. |
| NATO Corridor Pre-Positioning Infrastructure | PESCO funding accelerates multimodal terminal development across Poznań and Gdańsk clusters. |
| Blockchain-Enabled Customs Verification | Paperless diplomatic clearance trials between Germany and Poland displace traditional freight intermediaries. |
| EU Green Deal Military Exemption Compliance | Alternative fuel pilot programs gain regulatory space without civilian F-Gas Regulation penalties. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NATO logistics framework agreements, EU defense procurement databases, and national ministry budget disclosures. Defense logistics directors, military procurement officers, and third-party military freight operators provided operational perspective. ECHA chemical handling protocols, CE marking harmonization directives, and PESCO infrastructure funding records furnished regulatory and capital flow validation. Bottom-up contract award analysis and top-down defense spending allocation triangulated market sizing.
Forecast inputs incorporate logistics type segmentation, service model differentiation, technology readiness tiers, and end-user procurement authority levels across the projection horizon. Modeled dimensions span transportation solutions, maintenance support arrangements, automated systems deployment, and military versus contractor outsourcing depth. CAGRs derive from expenditure trajectory analysis against platform lifecycle sustainment demand curves. NATO force posture adjustments and EU defence industrial strategy implementation pace serve as scenario-weighting variables.
Macroeconomic conditions sit as an overlay; deviation in defense budget appropriation cycles or PESCO funding disbursement rates would shift the trajectory. Forecasts reflect documented assumptions regarding interoperability mandate adherence and certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Mine Clearance System Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Military Software Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market