
 Military Actuators Market | 2026-2036
Military Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Military Actuators Market Intelligence
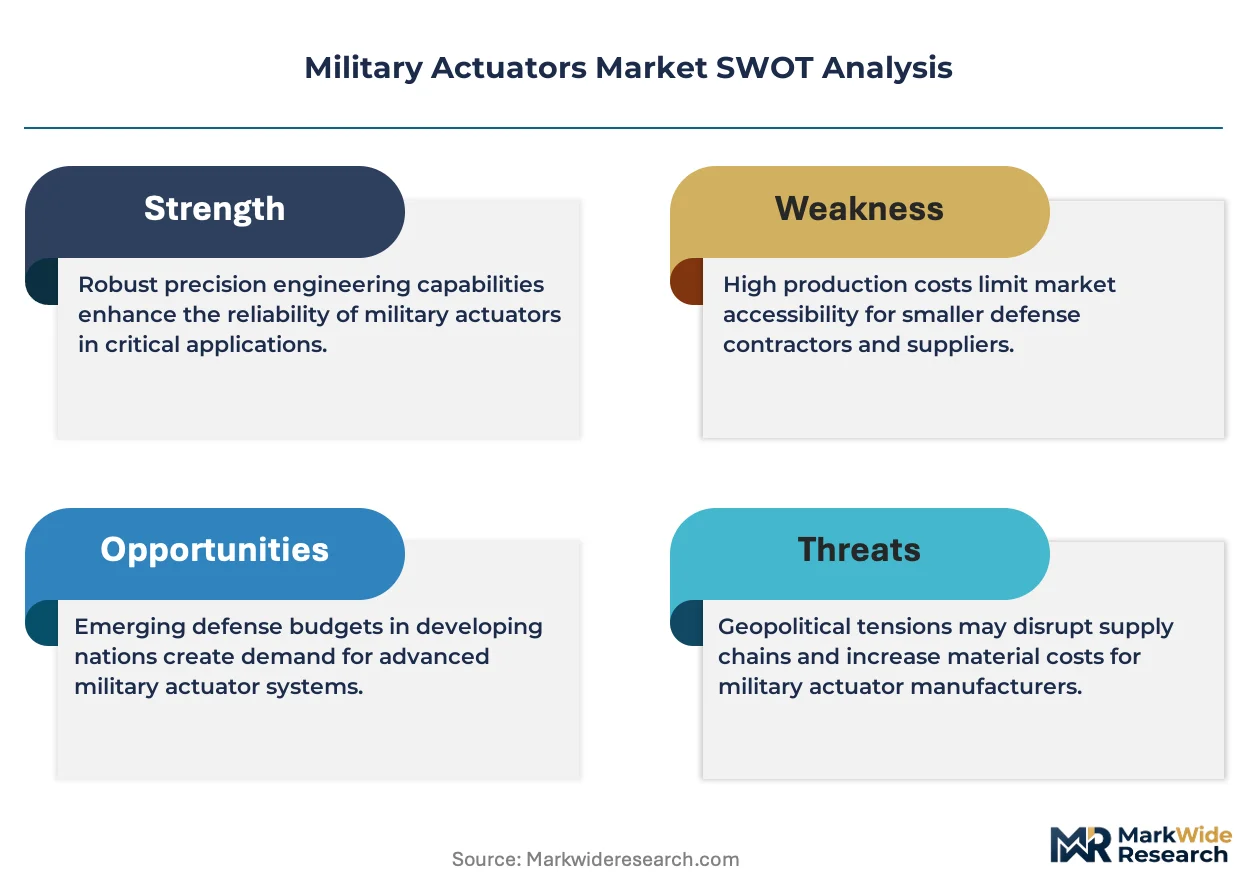
Electromechanical engineering talent scarcity is bifurcating the supplier landscape into tiered capability bands. Moog Inc. leverages deep heritage in precision motion control for missile guidance applications. Parker Hannifin Corporation anchors its position through integrated hydraulic-electromechanical portfolios. Curtiss-Wright Corporation specializes in hardened actuation for naval and aerospace platforms.
Military actuators are electromechanical, hydraulic, or pneumatic devices that convert energy into controlled mechanical motion, typically delivering force outputs from tens to thousands of pounds with positioning accuracy measured in micrometers for precision weapon aiming and flight control surfaces. Linear actuators dominate weapon systems integration where stroke length and load capacity determine platform compatibility, while smart actuators represent the fastest-expanding technology segment as embedded sensors and digital bus interfaces displace legacy analog control architectures. Hydraulic actuators retain entrenched positions in heavy-lift applications such as aircraft carrier launch systems and main battle gun elevation drives where peak power density exceeds electromechanical alternatives.
The US Department of Defense imposes Cybersecurity Maturity Model Certification on all subcontractors, forcing actuator suppliers to requalify their digital control interfaces and firmware supply chains. European defense procurement operates under EU Green Deal-aligned sustainability criteria that restrict hydraulic fluid chemistries and mandate end-of-life recyclability for electromechanical components. Stakeholders must weigh the capital requirements of smart actuator R&D against the contracting timelines of legacy platform refresh programs.
Market Dynamics
Defense procurement is bifurcating between legacy platform sustainment and next-generation unmanned system development, forcing actuator suppliers to maintain dual engineering pipelines under contracting military budgets. The Cybersecurity Maturity Model Certification is compressing supplier qualification timelines while elevating compliance costs.
Growth Catalysts
- Unmanned Aerial Vehicle Proliferation:The US Department of Defense's Replicator initiative mandates thousands of attritable autonomous systems, creating surge demand for miniaturized electromechanical actuators with embedded position feedback.
- Electrification Mandates:EU Green Deal sustainability criteria are restricting hydraulic fluid formulations in European defense procurement, accelerating electromechanical substitution in armored vehicle turret drives.
- Smart Actuator Architectures:Digital bus interfaces and embedded prognostic sensors are displacing analog control loops, enabling condition-based maintenance and reducing platform downtime.
Market Restraints
- Rare Earth Magnet Dependency:Permanent magnet motors in precision actuators rely on neodymium and dysprosium concentrated in Chinese processing facilities, exposing supply chains to export restriction risk.
- Extended Qualification Cycles:MIL-STD-810 environmental testing and DO-178C software certification for airborne systems stretch development timelines beyond commercial aerospace norms.
- Hydraulic Entrenchment:Aircraft carrier electromagnetic aircraft launch systems and main battle tank gun elevation drives retain hydraulic power density advantages that electromechanical alternatives have not matched.
Strategic Opportunities
- Indigenous Indian Production:India's PLI scheme for defense manufacturing offers capital subsidies for domestic actuator fabrication, targeting import substitution in Sukhoi upgrade programs.
- Additive Manufacturing Integration:Topology-optimized titanium actuator housings produced via electron beam melting are reducing weight fractions in missile fin control mechanisms.
- Model-Based Systems Engineering:Digital thread requirements in US DoD acquisition reform create openings for suppliers offering virtual qualification environments that compress physical test cycles.
Industry Challenges
- Electromechanical Talent Scarcity:Mechatronics engineers with both magnetic circuit design and embedded firmware expertise command premium compensation, constraining R&D team scaling.
- Legacy Integration Complexity:Smart actuators with 1553B or CAN bus interfaces must interoperate with analog-hydraulic control systems in platform mid-life upgrades, requiring protocol bridging architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Actuators Market |
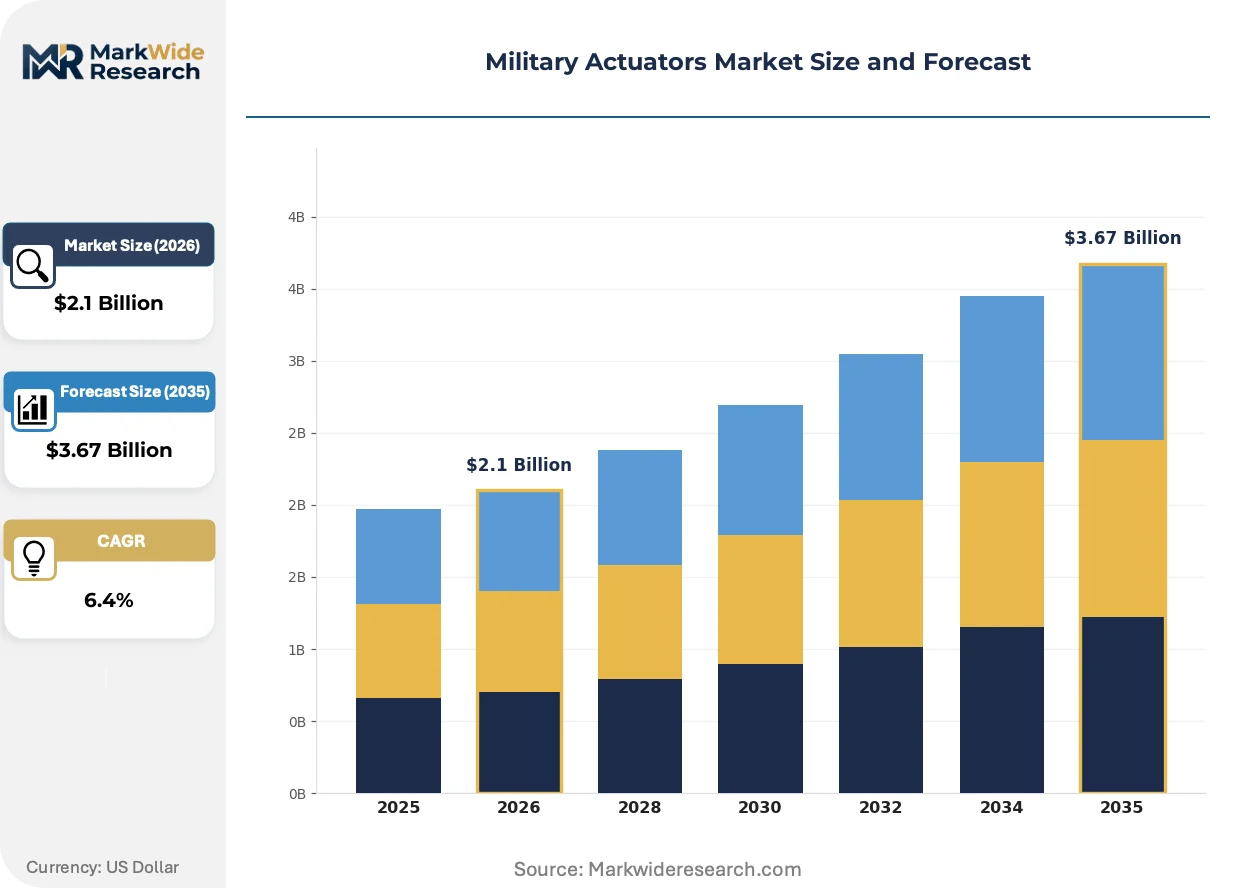
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Pneumatic Actuators, Hydraulic Actuators Application: Missile Guidance Systems, Weapon Systems, Robotics, Simulation Systems End User: Defense Contractors, Government Agencies, Military Forces, Research Institutions Technology: Electromechanical Systems, Hydraulic Systems, Pneumatic Systems, Smart Actuators |
| Companies Covered | Curtiss-Wright Corporation, Moog Inc., Parker Hannifin Corporation, Raytheon Technologies Corporation, Honeywell International Inc., Triumph Group, Nook Industries, Kyntronics, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Actuators Market Strategic Shifts & Innovations
Digitalization is penetrating actuation systems at the component level, transforming hardware suppliers into firmware-integrated solution providers. This shift demands new competencies in cybersecurity, predictive analytics, and model-based certification.
Integrated motor-drive actuators with field-oriented control algorithms are displacing traditional motor-gearbox-controller assemblies in precision weapon aiming applications. The US Army's Extended Range Cannon Artillery program is adopting these compact units for automated loading and elevation. This consolidation is compressing subsystem supplier counts while elevating electronics content in actuator bill-of-materials.
REACH restrictions on perfluorinated hydraulic fluids are forcing reformulation of legacy chemistries used in naval flight deck equipment. European defense contractors face compliance deadlines that coincide with platform refresh cycles, creating procurement friction. German and French naval programs are accelerating electromechanical alternatives to avoid fluid chemistry recertification costs.
Defense agencies are unbundling long-term sustainment contracts from initial platform acquisition, shifting actuator suppliers toward performance-based logistics arrangements. The UK Ministry of Defence's availability-based contracts for Typhoon fleets require suppliers to guarantee mean-time-between-failures rather than simply deliver spares. This transfer of operational risk is most advanced in UK and Australian fighter programs, where prime contractors now contract directly with actuator manufacturers for through-life support.
Military Actuators Market Segmentation
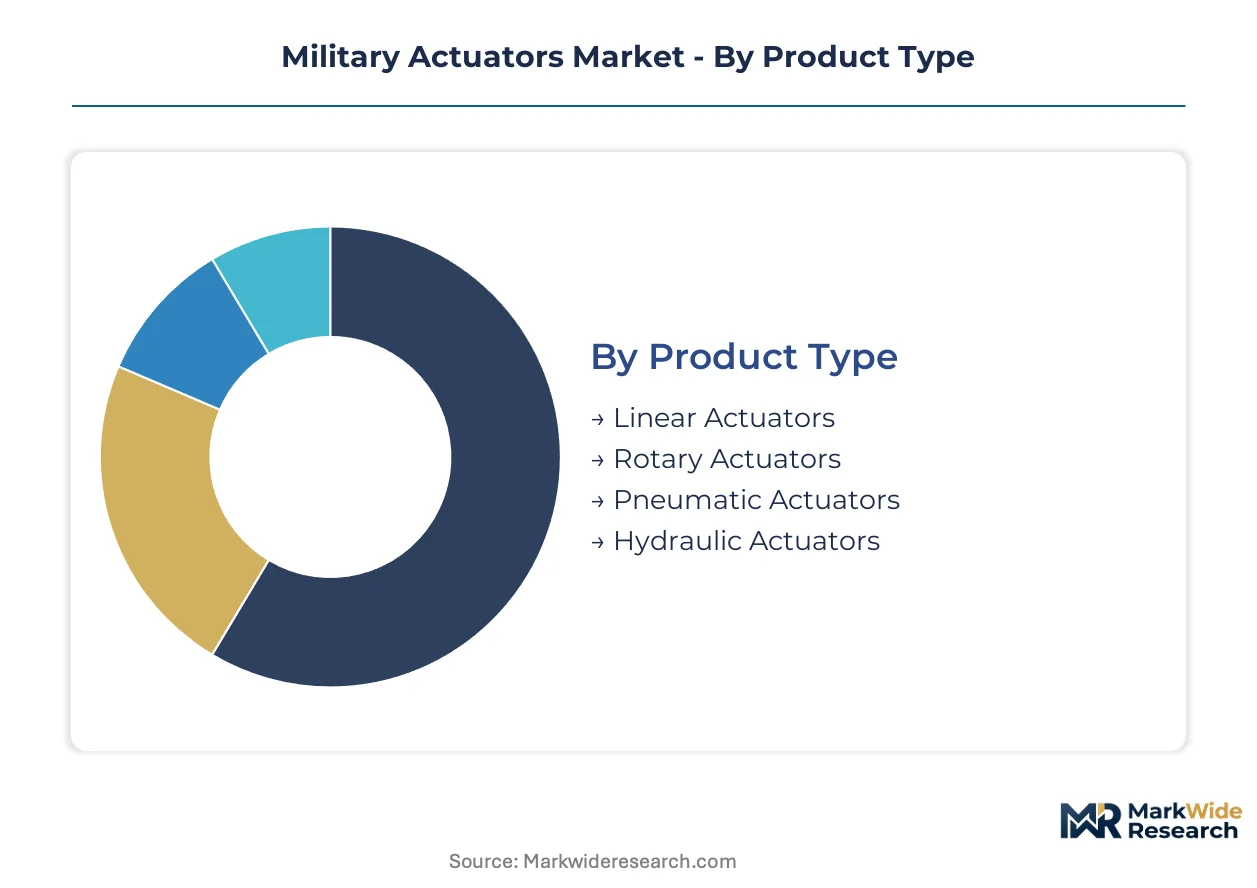
Military actuator procurement splits across incompatible technical standards and qualification regimes. Segment boundaries reflect divergent power density requirements, cybersecurity certification levels, and platform integration timelines.
Product Type:
Regulatory differentiation separates hydraulic systems governed by EPA spill containment rules from electromechanical alternatives subject to FCC electromagnetic interference standards.
- Linear Actuators:Convert rotational motion to precise linear displacement through ball screw or roller screw mechanisms, achieving positioning accuracy within micrometers for weapon aiming applications. The US Department of Defense's Replicator initiative concentrates demand in miniaturized electromechanical variants for attritable unmanned systems. Linear actuators handle the majority of throughput; smart electromechanical variants are the fastest mover on share.
- Rotary Actuators:Deliver torque output for turret rotation, radar positioning, and flight control surface actuation through direct-drive or geared architectures. European defense procurement under EU Green Deal restrictions is accelerating electromechanical substitution for hydraulic rotary units in armored vehicle applications.
- Pneumatic Actuators:Compressed gas systems for rapid-response applications requiring explosion-proof operation in munitions handling environments.
- Hydraulic Actuators:Retain entrenched positions in aircraft carrier electromagnetic launch systems and main battle tank gun elevation where peak power density exceeds electromechanical alternatives.
Linear configurations dominate weapon integration volumes; rotary units are climbing the fastest on technology refresh cycles.
Application:
Cost tier differentiation separates precision-guided munitions programs with extended development timelines from rapid-fielding initiatives for attritable systems.
- Missile Guidance Systems:Fin control mechanisms and thrust vectoring assemblies demand sub-millisecond response times with thermal stability across operational temperature extremes. The US Navy's Standard Missile and Army's Precision Strike Missile programs anchor demand for hardened electromechanical actuators with radiation-tolerant electronics.
- Weapon Systems:Turret drives, gun elevation mechanisms, and automated loading systems integrate multi-axis actuation with fire control computers. India's Sukhoi upgrade programs under PLI scheme subsidies are driving indigenous fabrication requirements for hydraulic-electric hybrid turret actuators.
- Robotics:Unmanned ground vehicle mobility platforms and manipulator arms require fault-tolerant actuator networks with distributed control architectures.
- Simulation Systems:High-fidelity motion platforms for pilot training replicate aircraft dynamics through synchronized multi-actuator arrays.
Weapon systems integration commands the largest program dollars; robotics applications are expanding most quickly on unmanned platform proliferation.
End User:
Customer type determines contracting mechanism, with defense primes managing subsystem integration versus direct military procurement for sustainment spares.
- Defense Contractors:Lockheed Martin, Raytheon, and Northrop Grumman specify actuator performance parameters for platform integration, driving qualification requirements through prime contractor supply chains. Cybersecurity Maturity Model Certification mandates are compressing supplier pools for digital control interfaces.
- Government Agencies:Defense Advanced Research Projects Agency and equivalent bodies fund advanced actuator technology demonstrators with accelerated procurement timelines outside standard acquisition regulations.
- Military Forces:Direct procurement of replacement actuators for depot-level maintenance, governed by military specification standards and performance-based logistics contracts.
- Research Institutions:National laboratories and university-affiliated research centers validate prototype actuators under extreme environmental conditions per MIL-STD-810 protocols.
Defense contractors channel the highest procurement volumes; government agencies are gaining share fastest on rapid acquisition reform initiatives.
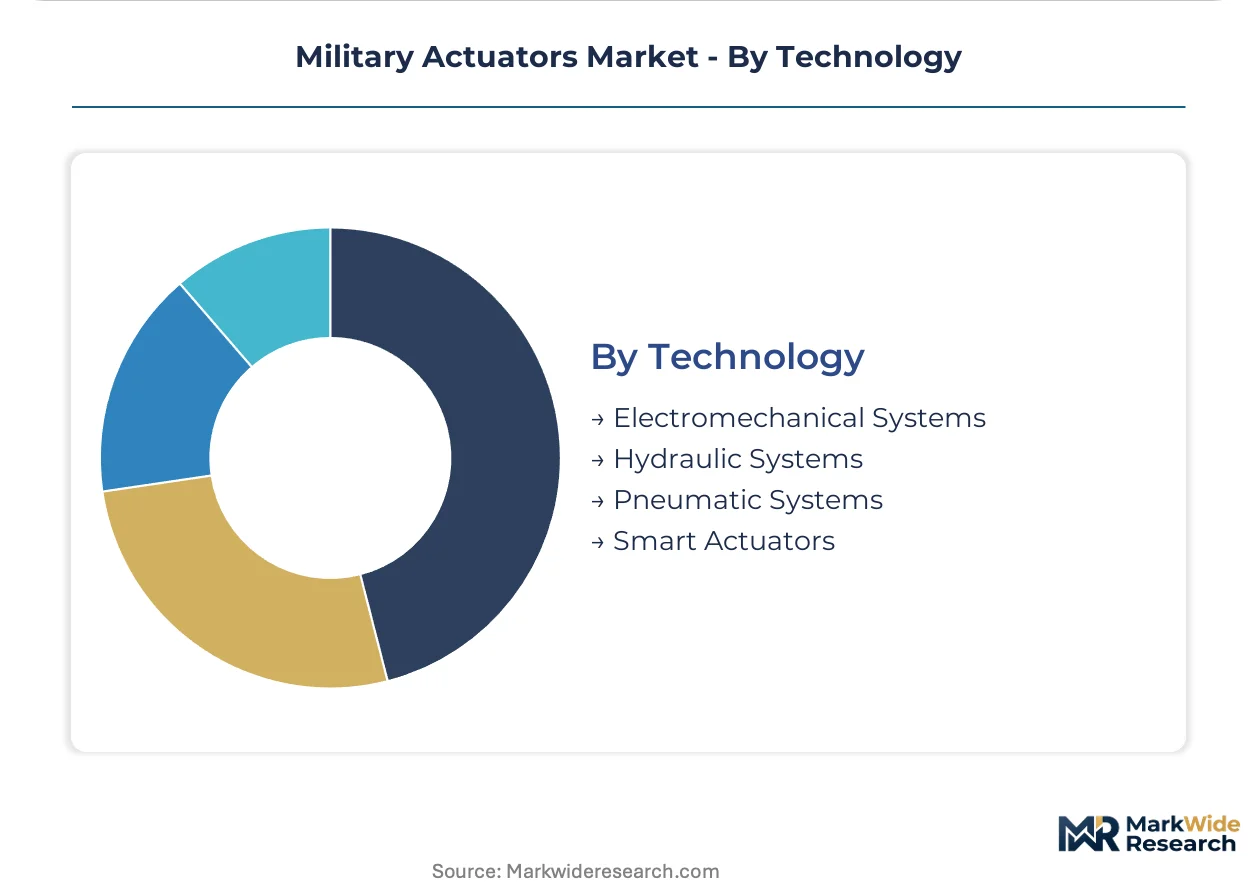
Technology:
Supply concentration in rare earth processing shapes technology trajectory, with permanent magnet motor dependencies influencing electromechanical system deployment risk assessments.
- Electromechanical Systems:Brushless DC motors with integrated position feedback displace legacy brushed architectures across precision applications. China's dominance in neodymium and dysprosium processing exposes supply chains to export restriction vulnerability.
- Hydraulic Systems:Fluid power actuation retains power density advantages in heavy-lift naval and armored applications. REACH restrictions on perfluorinated hydraulic fluids are forcing chemistry reformulation in European naval programs.
- Pneumatic Systems:Compressed air actuation for explosive atmosphere compatibility in munitions handling and fueling operations.
- Smart Actuators:Embedded sensors, digital bus interfaces, and prognostic algorithms enable condition-based maintenance and reduce platform downtime. Digital thread requirements in US DoD acquisition reform are accelerating adoption.
Electromechanical systems carry the largest installed base; smart actuators are gaining share fastest on predictive maintenance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply across geographies. The United States prioritizes attritable unmanned systems with embedded cybersecurity, while European states accelerate electromechanical substitution under environmental mandates. Asian defense industrial bases pursue indigenous fabrication through production-linked incentive schemes.
United States
The Department of Defense's Replicator initiative drives surge demand for miniaturized electromechanical actuators with embedded position feedback. Cybersecurity Maturity Model Certification mandates compress supplier qualification timelines while elevating compliance costs for digital control interfaces. Defense contractors in the aerospace corridor from Los Angeles to Seattle anchor precision motion control development for missile guidance applications.
Germany
Armored vehicle turret drives and naval flight deck equipment dominate procurement volumes as the Bundeswehr modernizes ground fleets. REACH restrictions on perfluorinated hydraulic fluids force chemistry reformulation in legacy naval programs, accelerating electromechanical alternatives. Industrial clusters in Baden-Württemberg specialize in hardened actuation systems for Leopard tank upgrade programs.
India
Sukhoi fighter upgrade programs and indigenous submarine construction drive import substitution requirements for hydraulic-electric hybrid actuators. The PLI scheme for defense manufacturing offers capital subsidies for domestic actuator fabrication targeting self-reliance in critical subsystems. Defense production units in Maharashtra and Tamil Nadu scale electromechanical assembly capacity for naval and aerospace platforms.
United Kingdom
Availability-based contracts for Typhoon fleets shift actuator suppliers toward performance-based logistics arrangements with guaranteed mean-time-between-failures. The Ministry of Defence's acquisition reform emphasizes through-life support contracting separate from initial platform procurement. Aerospace clusters in the Midlands and Southwest England concentrate smart actuator development for predictive maintenance integration.
Japan
Maritime Self-Defense Force destroyer programs and F-35 component supply sustain demand for precision electromechanical systems with radiation-hardened electronics. METI industrial policy supports dual-use technology development bridging commercial robotics and defense actuation. Manufacturing concentrations in the Nagoya aerospace corridor and Kanto region specialize in compact integrated motor-drive architectures.
Military Actuators Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in military actuator supply. Tier-one suppliers maintain dual capabilities across hydraulic and electromechanical portfolios, while mid-tier players concentrate on single-technology depth. Two strategic archetypes dominate: precision motion control specialists with heritage in aerospace guidance, and diversified industrial conglomerates with defense divisions. Competitive moves center on cybersecurity certification acquisition and additive manufacturing qualification for topology-optimized housings.
Among US-based integrated suppliers, Moog Inc., Curtiss-Wright Corporation, and Parker Hannifin Corporation occupy positions spanning the capability spectrum. Moog exemplifies the precision heritage archetype through its motion control specialization. Curtiss-Wright represents the hardened platform focus with naval and aerospace concentration. Parker Hannifin anchors the diversified industrial tier with portfolio breadth across fluid power and electromechanical domains.
| Leading Market Players |
|---|
| Curtiss-Wright Corporation |
| Moog Inc. |
| Parker Hannifin Corporation |
| Raytheon Technologies Corporation |
| Honeywell International Inc. |
| Triumph Group |
| Nook Industries |
| Kyntronics |
| Eaton Corporation |
| Others |
Cost & Logistics Intelligence
Cybersecurity Maturity Model Certification gates both supplier qualification and price differentiation in military actuator procurement. Compliance investment separates certified suppliers commanding performance-based premiums from uncertified competitors relegated to legacy analog contracts.
Pricing Analysis
Long-term offtake agreements dominate prime contractor relationships, with performance-based logistics contracts locking in through-life pricing for smart actuator fleets. Price differentiation rests on CMMC certification tier and embedded firmware complexity, with radiation-hardened variants for missile guidance commanding substantial premiums over standard industrial grades. Cost compression in attritable unmanned system tiers intensifies as the Replicator initiative scales volume procurement. Defense contractors exhibit lowest price sensitivity for precision weapon integration, while sustainment spares procurement shows acute cost consciousness under fixed military budgets.
Supply Chain Analysis
Extended lead times for rare earth magnet procurement stretch electromechanical actuator delivery schedules beyond eighteen months. Manufacturing concentrates in the United States, Germany, and Japan for precision motion control, with China dominating neodymium and dysprosium processing. Critical inputs include samarium-cobalt magnets, titanium powder for additive housings, and radiation-hardened semiconductors. Single-source vulnerability in Chinese rare earth refining exposes supply chains to export restriction risk. Distribution runs through defense prime contractor supply chains with direct military depot procurement for sustainment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military actuators sit in early-cycle expansion as unmanned platform proliferation outpaces legacy hydraulic replacement timelines. The Replicator initiative and smart actuator architecture shifts create durable adoption tailwinds.
For Market Incumbents: Shield qualification moats by accelerating CMMC Level 3 certification for firmware supply chains before competitor catch-up compresses compliance premiums. Consolidate backward integration into rare earth magnet sourcing through offtake agreements with Australian and North American mining ventures to neutralize Chinese supply weaponization risk.
For New Entrants and Emerging Players: Lead with additive manufacturing qualification for topology-optimized titanium actuator housings in missile fin control applications, where electron beam melting expertise remains scarce. Target Indian defense production units under PLI scheme subsidies as the most penetrable geography, offering technology transfer partnerships for Sukhoi upgrade actuator fabrication.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming defense divisions lacking CMMC certification infrastructure. Long-term viability hinges on smart actuator firmware integration capabilities across the projection horizon. Watch for inflection when attritable unmanned system procurement volumes exceed legacy platform sustainment spend in prime contractor revenue mix.
| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Certification Investment | Unlocks access to Replicator initiative contracts requiring embedded cybersecurity. |
| Additive Manufacturing Qualification | Enables topology-optimized titanium housings for missile fin control mechanisms. |
| Rare Earth Supply Agreement | Secures neodymium and dysprosium feedstock outside Chinese processing concentration. |
| Smart Actuator Firmware Development | Captures predictive maintenance value in UK availability-based contracting models. |
| Indian PLI Joint Venture | Accesses capital subsidies for indigenous Sukhoi upgrade actuator production. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with defense procurement officers, actuator engineering directors, prime contractor supply chain managers, and military depot maintenance chiefs; and secondary validation through DoD budget justification documents, SEC 10-K filings of listed suppliers, MIL-STD qualification registries, and EU defense procurement notices. Bottom-up platform integration estimates triangulated against top-down defense spending allocation models.
Across the modeling period, forecasts segmented by actuator technology, platform application, and end-user contracting mechanism projected volume and value outputs. CAGRs derived from historical procurement cycle analysis and unmanned system adoption curves. Industry-specific inputs included Replicator initiative unit targets, CMMC implementation timelines, and REACH hydraulic fluid restriction deadlines.
Forecasts assume regulatory continuity in CMMC, REACH, and PLI scheme regimes; material policy shifts would require re-modeling. Revision becomes warranted when rare earth export restrictions or defense budget sequestration cross operational thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Airborne Electronic Warfare Market
Defense and Military Systems and Equipment
Military Vetronics Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal (EOD) Equipment Market
Defense and Military Systems and Equipment
Military High Altitude Radio Jamming System Market
Defense and Military Systems and Equipment
Military Parachute Market
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Explosive Ordnance Disposal Market
Defense and Military Systems and Equipment
United States Defense Market
Defense and Military Systems and Equipment
Smart War Weapon Market
Defense and Military Systems and Equipment
Europe Defense Market
Defense and Military Systems and Equipment
Defense Tactical Computers Market