
 Sparkling Wine Market | 2026-2036
Sparkling Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Wine Market Intelligence
The EU Green Deal is broadening sustainability mandates across European vineyards, compelling producers to adopt lower-carbon viticulture practices and water-efficient cellar operations. Moët & Chandon leverages its historic Champagne estates to sustain heritage-driven premium pricing. Henkell & Co. Sektkellerei anchors German sparkling wine production through scale advantages in the Sekt category. E. & J. Gallo Winery competes in North American retail channels with diversified price-tier offerings.
Sparkling wine denotes effervescent wine containing dissolved carbon dioxide, achieved through secondary fermentation yielding pressures of three to six atmospheres, serving primarily as a celebratory beverage and gastronomic pairing agent across commercial and social settings. The Traditional Method segment commands premium margins due to extended lees-aging requirements and labor-intensive disgorgement processes. Brut and Extra Dry categories dominate volume, while Blanc de Blancs and Rosé attract disproportionate margin investment from producers seeking differentiation. The HoReCa channel concentrates value per hectoliter, though Online Retail extends reach to occasional drinkers in markets with underdeveloped specialist retail infrastructure.
France's INAO enforces Appellation d'Origine Contrôlée standards that restrict Champagne labeling to defined terroirs, while the EU's F-Gas Regulation pressures cellar refrigeration retrofits and the FDA governs import labeling for US-bound shipments. These frameworks elevate compliance costs for new entrants but reinforce scarcity value for established houses. Stakeholders must monitor evolving sustainability disclosure rules and carbon-border adjustment mechanisms that will reshape sourcing strategies and export competitiveness across key producing regions.
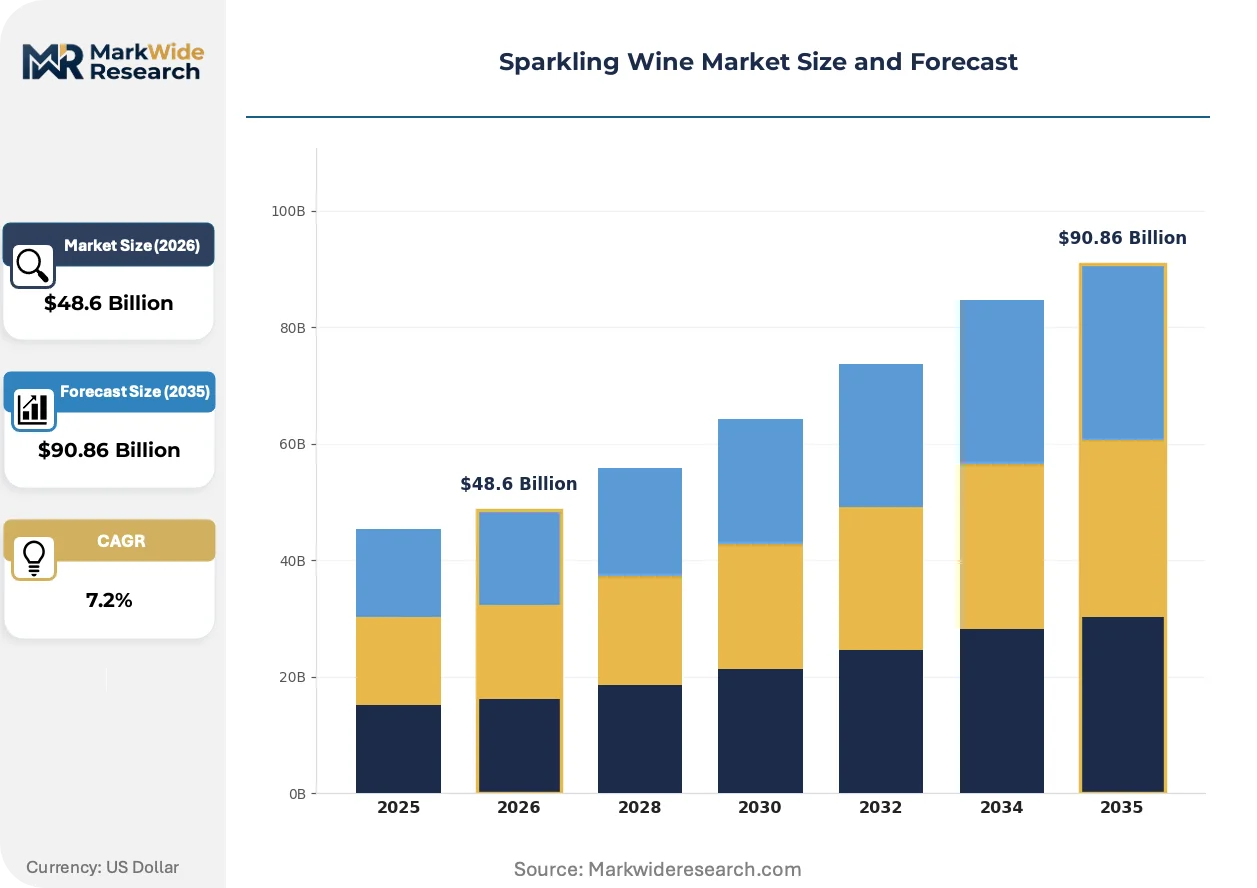
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanisms are forcing vineyard operators to retrofit cellar infrastructure and adopt regenerative viticulture, compressing margins for non-compliant producers while entrenching terroir-protected houses with legacy sustainability credentials.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-GWP refrigerants in temperature-controlled cellars are accelerating capital investment in energy-efficient disgorgement lines across French and Italian production zones.
- Premium hospitality recovery:Independent restaurants and hotel groups in the United States are rebuilding by-the-glass programs with higher-margin grower-Champagne selections.
- Secondary fermentation automation:Precision-controlled tank systems are reducing labor intensity in Traditional Method production, enabling mid-tier houses to compete on consistency.
Market Restraints
- Champagne AOC supply concentration:INAO-enforced terroir boundaries limit eligible vineyard hectares, constraining volume expansion for authentic Champagne labeling.
- Glass and cork input volatility:Energy-intensive bottle manufacturing faces natural gas price swings that transmit directly to packaging costs.
- Prosecco DOC volume competition:Tank-method Italian production at scale creates persistent price-floor pressure on entry-level sparkling wine categories.
Strategic Opportunities
- English sparkling wine terroirs:Sussex and Kent chalk subsoils are gaining PDO recognition as climate warming extends viable growing seasons in southern England.
- Direct-to-consumer subscription channels:Wineries are bypassing wholesale markups through curated club models targeting millennial occasional drinkers.
- EU CSRD disclosure mandates:Early compliance with sustainability reporting standards is creating marketing differentiation for listed wine groups.
Industry Challenges
- Master blender succession gaps:Decades-long apprenticeship requirements for dosage and lees-aging expertise face demographic compression as veteran cellar masters retire.
- Multi-jurisdiction label compliance:Divergent FDA allergen rules, EU ingredient disclosure, and emerging market language requirements multiply SKU complexity for export houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Wine Market |
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $90.86 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brut, Extra Dry, Dry, Demi-Sec, Rosé, Blanc de Blancs Production Method: Traditional Method, Charmat Method, Ancestral Method, Carbonation Method Distribution Channel: Supermarkets & Hypermarkets, Specialist Retailers, Online Retail, HoReCa, Duty-Free Shops Consumer Segment: Premium Consumers, Occasional Drinkers, Event Organizers, Hospitality Sector |
| Companies Covered | Laurent-Perrier, Freixenet, Moët & Chandon, Champagne Taittinger, Henkell & Co. Sektkellerei, E. & J. Gallo Winery, Veuve Clicquot Ponsardin, Grupo Codorníu Raventós, The Wine Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Wine Market Strategic Shifts & Innovations
Carbon-accounting transparency and precision viticulture are converging to reshape how sparkling wine houses demonstrate provenance and environmental accountability to trade buyers and consumers.
Precision canopy management sensors are unifying soil-moisture monitoring, foliar health assessment, and harvest-timing algorithms into single-platform decision tools. Champagne houses with significant estate holdings are deploying these systems across contiguous vineyard blocks. The technology is unifying agronomic and oenological data streams, compressing the feedback loop between field conditions and cellar intervention.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in commercial refrigeration, compelling cellar operators to install ammonia or CO2-based cooling systems before mandated deadlines. Retrofit capital requirements are falling disproportionately on smaller cooperatives lacking balance-sheet flexibility. Grower-producers in Champagne's Côte des Blancs are responding through shared-service chilling facilities to defray individual compliance burdens.
Restaurant buyers are consolidating supplier relationships around fewer, deeper partnerships with import agents who can guarantee vintage continuity and provenance documentation. Sommelier-led programs in New York and San Francisco are displacing fragmented distributor relationships with direct allocations from established négociants. This concentration is most visible in coastal US metropolitan markets where credential-driven beverage programs command premium pricing power.
Sparkling Wine Market Segmentation
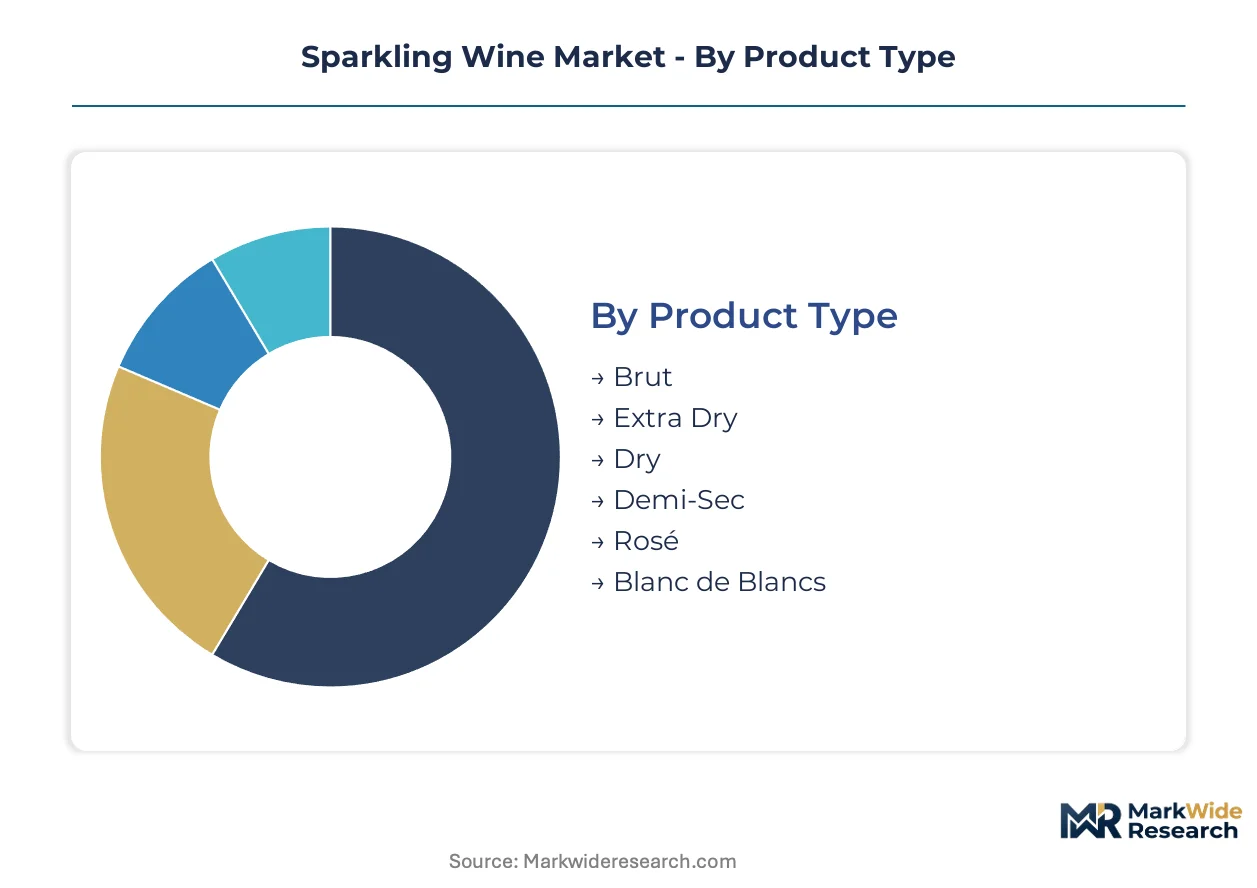
Sparkling wine segmentation reveals how production technique, sweetness level, and channel access shape purchasing behavior across celebratory and gastronomic occasions. Producers calibrate portfolio depth against channel-specific margin profiles and consumer occasion mapping.
Product Type:
Upgrade cycles in sparkling wine follow evolving palate sophistication, with consumers migrating toward drier styles and terroir-expressive formats as category familiarity deepens.
- Brut:The dominant dosage category contains less than 12 grams per liter residual sugar, aligning with contemporary preferences for drier palates. Restaurant programs in the United States concentrate Brut placements by-the-glass as entry points for new sparkling wine consumers.
- Extra Dry:Despite its name, this segment carries 12-17 grams per liter residual sugar, occupying a midpoint between austerity and perceptible sweetness. Italian Prosecco DOC production concentrates here, leveraging the style's approachability for casual home consumption occasions.
- Dry:Higher residual sugar levels suit dessert pairing applications and emerging market palates where sweetness signals quality.
- Demi-Sec:The sweetest standard category supports ceremonial toasting traditions in Eastern European and select Asian markets.
- Rosé:Pinot Noir-dominant blends or saignée production yield color and structural tension. French Champagne houses invest disproportionate margin resources here to differentiate seasonal and gifting portfolios.
- Blanc de Blancs:Chardonnay-exclusive cuvées from chalk terroirs command the most demanding production standards and extended lees aging. Collector demand concentrates in this segment for provenance-driven vertical programs.
Volume placements concentrate in Brut; the faster expansion belongs to Blanc de Blancs.
Production Method:
Cost structures diverge sharply across methods, with labor intensity and cellar aging duration determining which tiers can compete on price versus provenance narrative.
- Traditional Method:Secondary fermentation in bottle followed by disgorgement yields 3-6 atmospheres pressure and complex autolytic character. Champagne AOC mandates this technique, entrenching heritage houses with sunk capital in riddling equipment and cellar aging capacity.
- Charmat Method:Tank-based secondary fermentation reduces production cycle duration and labor requirements. Italian Prosecco DOC and Spanish Cava volume production anchors on this method, enabling price accessibility that Traditional Method houses cannot match.
- Ancestral Method:Single fermentation with early bottling preserves primary fruit aromatics and lower alcohol levels. Natural wine specialists in France's Loire Valley and Limoux AOCs are expanding this segment's commercial footprint.
- Carbonation Method:Direct CO2 injection offers the lowest production cost but limited complexity development. Private-label retail programs and entry-level price tiers depend on this technique for margin preservation.
Charmat Method dominates hectoliter output; Traditional Method retains the steepest value-per-liter trajectory.
Distribution Channel:
Channel selection determines margin capture versus volume velocity, with direct relationships increasingly displacing fragmented wholesale intermediaries in premium tiers.
- Supermarkets & Hypermarkets:High-velocity retail chains in Germany and the United Kingdom concentrate promotional pricing and seasonal gifting volume. Private-label and tank-method offerings dominate shelf positioning here.
- Specialist Retailers:Independent wine merchants and dedicated champagne boutiques curate grower-producer allocations and vintage depth. Staff expertise and provenance documentation justify premium pricing in this channel.
- Online Retail:Direct-to-consumer platforms extend reach to occasional drinkers in markets with underdeveloped specialist infrastructure. Subscription models and curated club offerings are consolidating repeat purchase behavior.
- HoReCa:Hotels, restaurants, and cafés command the highest value per hectoliter through by-the-glass pricing power. Sommelier-driven programs in coastal United States metropolitan markets are deepening supplier relationships with fewer import agents.
- Duty-Free Shops:Travel retail channels concentrate prestige cuvée allocations and limited editions for price-sensitive luxury positioning. Airport exclusivity supports margin structures unavailable in domestic markets.
Supermarkets & Hypermarkets anchor aggregate volume; HoReCa channels are climbing the fastest in value contribution.
Consumer Segment:
Occasion-based targeting separates ritual purchasers from exploratory drinkers, with hospitality sector procurement following distinct specification logic.
- Premium Consumers:Collector and connoisseur segments prioritize provenance documentation, vintage continuity, and house prestige. Direct allocation relationships with established négociants bypass wholesale markups for this cohort.
- Occasional Drinkers:Celebration-driven purchase patterns concentrate around holidays and personal milestones. Millennial demographics in English-speaking markets show receptivity to curated subscription formats that reduce decision friction.
- Event Organizers:Corporate hospitality and wedding planners demand consistent supply at scale with predictable pricing. Tank-method and carbonation offerings align with this segment's cost constraints.
- Hospitality Sector:Procurement teams specify by-the-glass cost targets and vintage breadth requirements. Consolidated supplier relationships with import agents who guarantee provenance documentation are displacing fragmented distributor networks.
Occasional Drinkers represent the broadest addressable base; Premium Consumers deliver the highest lifetime value per account.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Champagne's Reims-Épernay corridor anchors the world's most valuable sparkling wine production cluster, with terroir-protected estates commanding sustained price premiums across export markets.
France
Champagne AOC regulations enforced by INAO restrict vineyard expansion to 34,300 designated hectares, preserving scarcity value for heritage houses. The EU F-Gas Regulation mandates cellar refrigeration retrofits by 2030, compressing margins for smaller cooperatives. The Côte des Blancs sub-region concentrates Chardonnay plantings that supply prestige Blanc de Blancs cuvées.
Italy
Prosecco DOC volume from Veneto's Conegliano-Valdobbiadene corridor dominates global hectoliter output through tank-method efficiency. Italy's national agricultural regulator enforces geographic delimitation standards that distinguish DOCG-tier Superiore from broader DOC production. The Treviso province anchors consolidated bottling facilities serving export markets.
United States
California's Sonoma and Napa counties drive domestic premium sparkling wine production through estate-grown Pinot Noir and Chardonnay. The FDA governs allergen labeling requirements for imported and domestically produced bottles. New York City's hospitality sector concentrates by-the-glass pricing power for grower-Champagne allocations.
Germany
Sekt production in Hesse's Rheingau region leverages Riesling and Pinot varieties through both traditional and tank methods. Germany's federal environment agency implements EU Green Deal carbon-accounting standards across vineyard operations. The Wiesbaden-Mainz corridor hosts consolidated sparkling wine houses with scale advantages in private-label retail.
United Kingdom
Sussex and Kent chalk subsoils are gaining PDO recognition as climate warming extends viable growing seasons for traditional-method production. The UK's Wine Standards Board enforces emerging English sparkling wine labeling regulations. The South Downs cluster attracts investment from Champagne houses establishing satellite estates.
Sparkling Wine Market Key Industry Players
Premium-margin players sit above commodity-margin players across production-method tiers, with terroir-protected estates capturing value that tank-method producers cannot replicate. The market structures around heritage houses with sunk capital in riddling infrastructure, scale-driven national champions, and emerging estate producers with direct-to-consumer reach. Strategic moves concentrate on vineyard acquisitions securing AOC-eligible hectares, and shared-service chilling cooperatives defraying EU F-Gas compliance costs.
Within the heritage house tier, Moët & Chandon and Veuve Clicquot Ponsardin occupy positions sustained by historic Champagne estates and extended lees-aging capacity. Henkell & Co. Sektkellerei exemplifies the scale-driven archetype through consolidated German Sekt production. Laurent-Perrier represents mid-tier houses differentiating through Blanc de Blancs specialization and grower-producer relationships. These entities anchor competitive dynamics without exhaustive individual profiling.
| Leading Market Players |
|---|
| Laurent-Perrier |
| Freixenet |
| Moët & Chandon |
| Champagne Taittinger |
| Henkell & Co. Sektkellerei |
| E. & J. Gallo Winery |
| Veuve Clicquot Ponsardin |
| Grupo Codorníu Raventós |
| The Wine Group |
| Others |
Cost & Logistics Intelligence
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access by mandating cellar refrigeration retrofits that smaller cooperatives cannot absorb, entrenching heritage houses with legacy chilling infrastructure and carbon-accounting credentials that justify sustained price premiums across export markets.
Pricing Analysis
Value-based pricing anchored to terroir-protected designation of origin governs the sparkling wine market, with Champagne AOC labeling commanding sustained premiums over tank-method alternatives. Price differentiation rests on production method certification and extended lees-aging duration, while cost compression in entry-level tiers intensifies due to Prosecco DOC volume competition. Event organizers and hospitality procurement teams exhibit the highest price sensitivity, whereas collector segments prioritize provenance documentation over absolute cost.
Supply Chain Analysis
Direct allocation channels between grower-producers and specialist retailers handle premium buyer demand, bypassing fragmented wholesale intermediaries in coastal United States metropolitan markets. Supply concentrates in France, Italy, and Germany, with raw material dependencies spanning glass bottle manufacturing, natural cork supply, and specialized yeast cultures for secondary fermentation. Single-source vulnerability in Champagne AOC vineyard hectares constrains volume expansion for authentic labeling. Distribution runs through consolidated import agents who guarantee vintage continuity and provenance documentation for restaurant programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sparkling wine market functions as a cost-of-compliance story where the EU F-Gas Regulation creates a barrier-to-entry moat, compressing margins for non-compliant producers while entrenching heritage houses with legacy sustainability credentials and balance-sheet flexibility for mandated cellar retrofits.
For Market Incumbents: To counter Prosecco DOC volume competition at the entry-level price tier, deepen direct allocation relationships with sommelier-led restaurant programs in New York and San Francisco while securing shared-service chilling cooperatives in Champagne's Côte des Blancs to defray individual EU F-Gas compliance burdens.
For New Entrants and Emerging Players: The EU CSRD disclosure mandates in Europe open a window for early sustainability reporting compliance to differentiate against established houses lagging in carbon-accounting transparency, targeting English sparkling wine terroirs in Sussex and Kent where PDO recognition and climate warming extend viable growing seasons for traditional-method production.
For Investors and Strategic Acquirers: Master blender succession gaps in Champagne houses is the leading indicator that technical human capital scarcity will intensify acquisition premiums for mid-tier houses with documented apprenticeship pipelines and grower-producer relationships, positioning vertically integrated estate holdings with direct-to-consumer subscription reach as the optimal long-term viability archetype.
| Strategic Initiative | Industry Significance |
|---|---|
| Vineyard Acquisition in AOC-Eligible Hectares | Secures scarce terroir-protected supply capacity against INAO-enforced expansion limits. |
| Shared-Service Chilling Cooperative Formation | Defrays EU F-Gas retrofit costs for smaller Champagne cooperatives lacking balance-sheet depth. |
| Direct-to-Consumer Subscription Launch | Bypasses wholesale markups to capture millennial occasional drinker lifetime value. |
| Carbon-Accounting Transparency Program | Creates marketing differentiation under emerging EU CSRD disclosure mandates. |
| English Sparkling Wine Estate Establishment | Exploits Sussex and Kent PDO recognition as climate warming extends growing seasons. |
Research Approach
Multi-period observation of cellar infrastructure investment patterns, AOC vineyard hectare allocations, and hospitality channel pricing power anchored the trend analysis, supplemented by interviews with Champagne house cellar masters, Italian Prosecco DOC consortium representatives, United States restaurant beverage directors, German Sekt production managers, and English sparkling wine estate developers. Secondary validation drew from INAO regulatory filings, EU F-Gas implementation reports, FDA import labeling guidance, and trade customs data across France, Italy, and Germany. Bottom-up hectoliter volume modeling and top-down value aggregation enabled triangulation across production method tiers.
Segment-weighting across product type, production method, distribution channel, and consumer occasion dimensions shaped the analytical framework across the analysis window. CAGRs were derived from iterative reconciliation of supply-constrained Champagne AOC volume projections against tank-method expansion trajectories in Veneto and scale-driven Sekt output in Hesse. Forecast inputs incorporated climate warming impact assessments on English terrior viability and carbon-border adjustment mechanism implementation timelines.
Caveats apply where regulatory enforcement delays, glass and cork input volatility, or master blender succession disruptions could materially shift the outlook for premium-tier supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Malaysia Alcohol E-Commerce Market
Alcoholic Beverages
Spain Alcohol E-Commerce Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Tea Beer Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Organic Beer Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Spirit-Based RTD Mixes Market
Alcoholic Beverages
North America Mezcal Market
Alcoholic Beverages
Asia-Pacific Craft Beer Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Gin Market
Alcoholic Beverages
Asia-Pacific Alcoholic Beverage Market
Alcoholic Beverages
Cannabis Beverages Market
Alcoholic Beverages
Arak Market
Alcoholic Beverages
CBD Wine Market