
 Testosterone Booster Supplements Market | 2026-2036
Testosterone Booster Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Testosterone Booster Supplements Market Analytics
Platform licensing revenue from subscription-based supplement programs is reshaping how testosterone booster brands monetize customer relationships. Nugenix leverages its direct-response television heritage to sustain recurring revenue streams through auto-ship models. TestoPrime competes aggressively on price transparency, anchoring its position with fully disclosed ingredient dosages. Transparent Labs controls quality perception through third-party certification, extending its premium positioning across the athlete segment.
Testosterone booster supplements are oral or topical formulations containing botanical extracts, amino acid complexes, or mineral compounds designed to stimulate endogenous testosterone production or modulate androgen receptor sensitivity. These products typically specify standardized extract concentrations, such as fenugreek seed extract standardized to 50% saponins, to ensure batch-to-batch consistency in bioactive content. The primary commercial purpose is supporting lean muscle preservation, energy metabolism, and recovery metrics in aging males and resistance-trained populations. Pills dominate volume due to convenience and shelf stability, while powders capture margin pools through flavor customization and stack compatibility with protein and pre-workout regimens. The herbal ingredient source leads absolute dollar contribution, though bio-identical compounds attract premium pricing from consumers seeking pharmaceutical-grade parity.
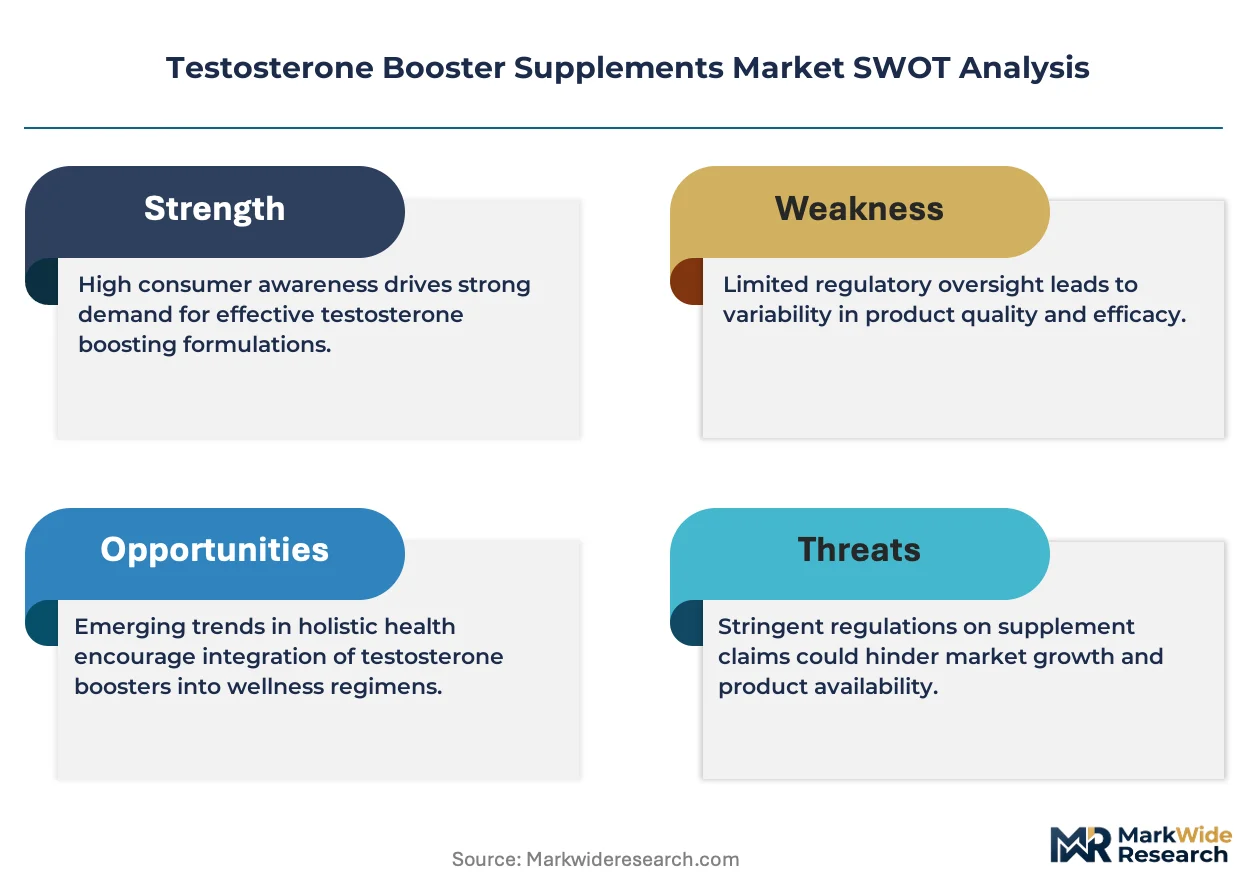
FDA oversight through DSHEA enforcement and cGMP compliance audits shapes manufacturing standards and adverse event reporting obligations for domestic producers. The FTC monitors advertising claims, restricting unsubstantiated efficacy assertions that could trigger warning letters or consent decrees. Stakeholders must monitor how regulatory scrutiny of influencer marketing and before-and-after testimonials reshapes customer acquisition economics across digital channels.
Market Dynamics
Direct-to-consumer subscription models are compressing traditional retail margins while forcing incumbent brands to rebuild their customer acquisition infrastructure around auto-ship retention mechanics rather than single-transaction velocity.
Growth Catalysts
- Fitness culture penetration:Resistance training adoption among men aged 35-55 in Brazil, Mexico, and Indonesia is creating first-time supplement users without established brand loyalties.
- DSHEA framework evolution:The FDA's draft guidance on New Dietary Ingredient notifications is clarifying compliance pathways for novel botanical extracts, reducing regulatory uncertainty for innovative formulations.
- Telehealth integration:Hormone optimization clinics in Texas, Florida, and Arizona are bundling testosterone support supplements with diagnostic panels, normalizing preventive male health expenditure.
Market Restraints
- Raw material concentration:Fenugreek seed extract supply concentrates in Rajasthan and Gujarat, exposing brands to monsoon-dependent harvest volatility and regional processing bottlenecks.
- Clinical substantiation costs:FTC enforcement against structure-function claims demands randomized controlled trial investment that mid-tier manufacturers cannot amortize across limited SKU lines.
- Pharmaceutical substitution:Compounded testosterone formulations prescribed through telehealth platforms capture aging male spend that botanical boosters previously accessed.
Strategic Opportunities
- Underpenetrated markets:Germany, France, and Spain exhibit low testosterone supplement penetration relative to protein powder consumption, suggesting latent demand activation potential through education-focused marketing.
- Regulatory tailwinds:India's FSSAI is streamlining health supplement registration through the Food Safety and Standards (Health Supplements, Nutraceuticals) Regulations, reducing time-to-market for compliant entrants.
- Channel innovation:Pharmacy-retail hybrid formats like Walgreens' specialized men's health sections in Chicago, Houston, and Phoenix are legitimizing supplement categories for skeptical first-time buyers.
Industry Challenges
- Formulation science talent scarcity:Phytochemistry expertise capable of standardizing complex botanical matrices commands premium compensation that bootstrapped brands struggle to match.
- Third-party certification timelines:NSF Certified for Sport and Informed Sport accreditation processes extend 14-18 months, delaying athlete-segment entry for new market entrants.
- Supply chain reconfiguration:Brands diversifying from single-source fenugreek processors to multi-origin supply must rebuild batch consistency protocols without disrupting existing customer experience.
Report Scope
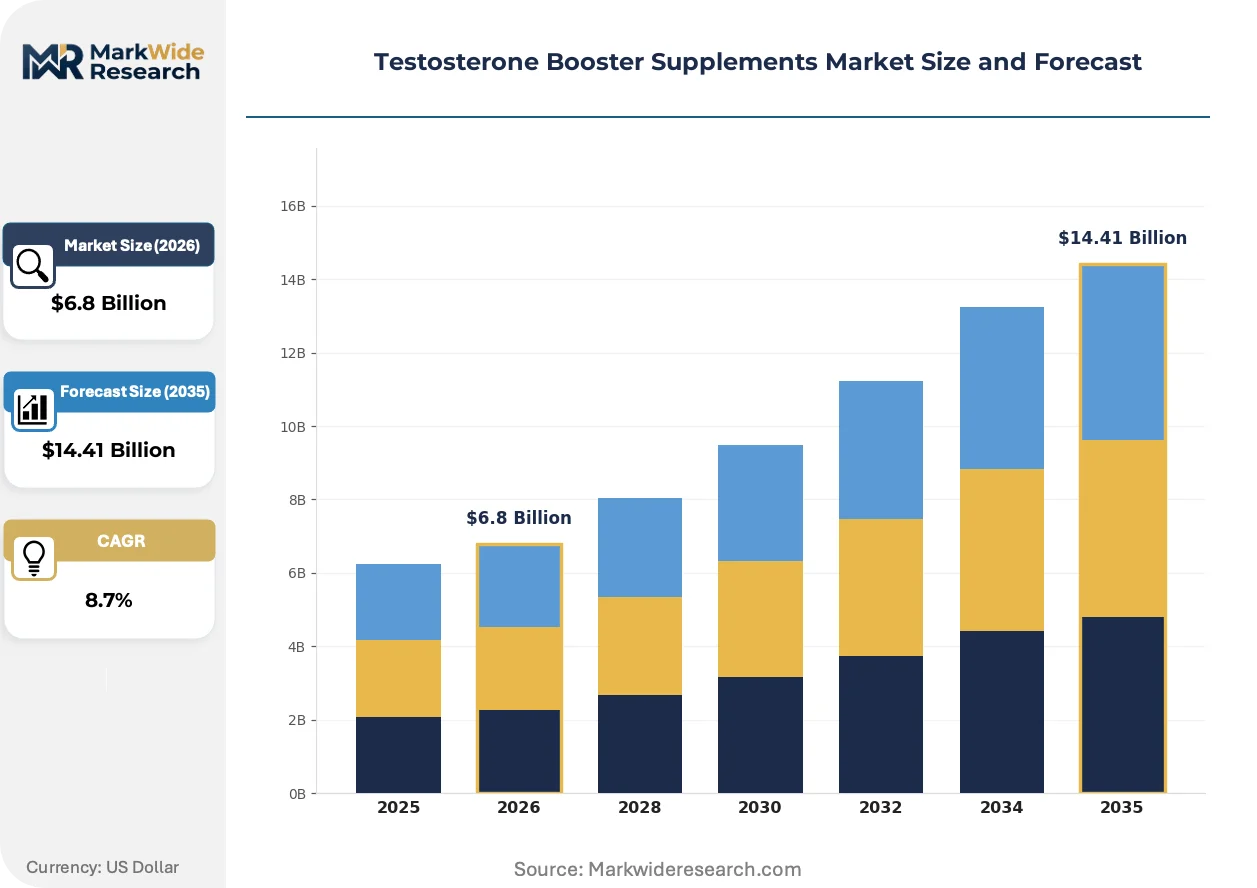
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testosterone Booster Supplements Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Powders, Liquids, Gels Ingredient Source: Herbal, Synthetic, Natural, Bio-identical Target Consumer: Athletes, Bodybuilders, Older Adults, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Testogen, Roman, Innerbody Labs, TestoFuel, Nugenix, TestoPrime, Transparent Labs, Nutricost, Testosil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testosterone Booster Supplements Market Evolving Landscape
Formulation science is pivoting toward bioavailability-enhanced delivery systems as consumers demand measurable physiological response rather than ingredient-list marketing. This shift rewards R&D investment over advertising spend.
Liposomal encapsulation technology for fat-soluble compounds like vitamin D3 and K2 is migrating from pharmaceutical applications into sports nutrition. Athlete-focused brands in California and Colorado are adopting these delivery mechanisms to differentiate absorption claims. The technology is compressing differentiation timelines for legacy tablet-based competitors who lack encapsulation partnerships.
EMA's evolving guidance on botanicals used in food supplements is tightening heavy metal and pesticide residue thresholds for fenugreek, ashwagandha, and tribulus terrestris imports. European contract manufacturers are consolidating supplier audits to preempt border rejection risk. Premium-positioned brands are responding by vertically integrating into controlled-environment agriculture for key botanical inputs.
Subscription bundling is displacing single-SKU purchases among resistance-trained populations. Digital-native brands are packaging testosterone support with sleep aids and omega-3s into personalized stacks. This pattern concentrates most visibly in the United States, where auto-ship infrastructure and credit-card-on-file consumer comfort enable predictable recurring revenue models that fund customer lifetime value optimization.
Testosterone Booster Supplements Market Segmentation
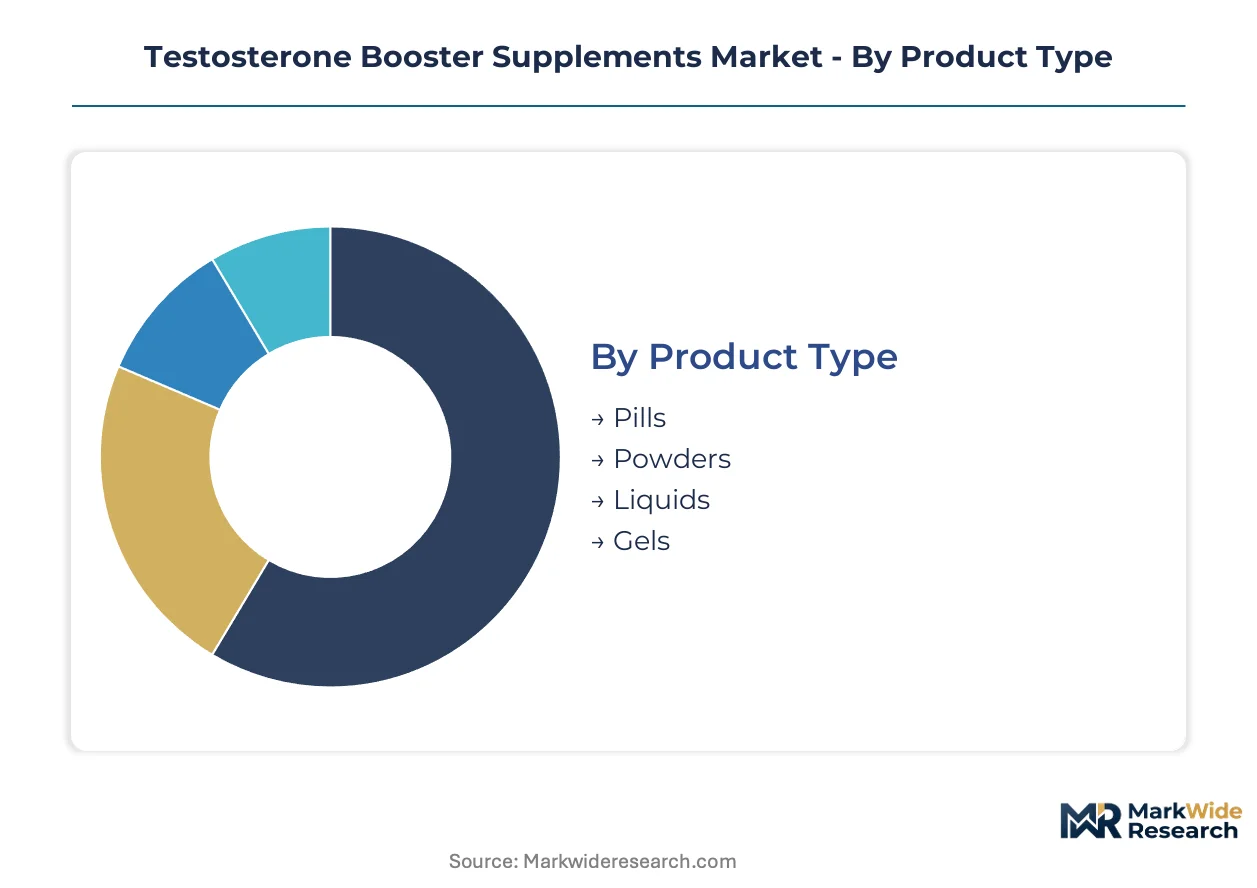
Segmentation in testosterone boosters reveals divergent purchase cycles across delivery formats and buyer psychographics. Repurchase intervals stretch from 30-day subscription renewals to seasonal bulk buying, shaping inventory planning and customer lifetime value calculations for brands competing on retention versus acquisition economics.
Product Type:
Pills turn inventory fastest through pharmacy and subscription channels, while powders and gels operate on slower replenishment cycles tied to usage volume and seasonal training intensity.
- Pills:Compressed tablets and capsules containing standardized botanical extracts dominate shelf-stable retail placement. Demand concentrates in the United States through CVS and Walgreens men's health sections, driven by convenience-seeking older adults who prioritize discrete consumption and travel portability. FDA cGMP compliance requirements for tablet dissolution rates favor established contract manufacturers with validated equipment.
- Powders:Flavored and unflavored bulk formulations enable stack integration with protein and pre-workout regimens. Concentrated demand appears in Texas and Florida gym-adjacent specialty retailers, where resistance-trained populations customize dosing protocols. The format captures margin pools through flavor R&D differentiation and larger average order values.
- Liquids:Sublingual drops and ready-to-drink shots emphasize rapid absorption claims for pre-workout timing. Bottled formats face higher shipping cost density that compresses direct-to-consumer unit economics.
- Gels:Transdermal formulations with liposomal or permeation-enhanced delivery target consumers skeptical of gastrointestinal bioavailability. Clinical positioning requirements limit mass-market penetration.
Pills anchor the volume base while powders gain share at the steepest rate.
Ingredient Source:
Cost structures stratify sharply between commodity botanical extracts and precision-manufactured bio-identical compounds, with regulatory validation burdens determining viable competitive sets.
- Herbal:Fenugreek, ashwagandha, and tribulus terrestris extracts standardized to specific saponin or withanolide concentrations constitute the volume foundation. EMA's tightening heavy metal thresholds for European imports are consolidating supplier qualification requirements around vertically integrated processors.
- Synthetic:Laboratory-derived compounds including D-aspartic acid and arachidonic acid analogs offer batch consistency advantages. Manufacturing concentrates in Chinese and Indian API facilities subject to FDA import alert monitoring.
- Natural:Non-standardized whole-food concentrates from oyster extract, beef liver, and egg yolk appeal to ancestral health positioning. Supply volatility from agricultural sourcing limits scale.
- Bio-identical:Compounds structurally matched to endogenous testosterone precursors command premium pricing from consumers seeking pharmaceutical-grade parity. DEA scheduling considerations constrain formulation flexibility in the United States.
Herbal formulations retain the largest revenue footprint though bio-identical segments expand most quickly among aging male demographics with preventive health expenditure capacity.
Target Consumer:
Training frequency and age-related hormonal awareness create distinct buyer personas with incompatible messaging requirements and channel preferences.
- Fitness Enthusiasts:Men aged 25-40 with consistent but non-competitive gym attendance represent the fastest-expanding segment. First-time supplement adoption in Brazil, Mexico, and Indonesia is concentrated here, with digital-native brands capturing trial through influencer partnerships and auto-ship incentives.
- Older Adults:Men aged 45-60 seeking energy and body composition maintenance drive pharmacy channel legitimacy. Bundling with diagnostic panels at Texas and Arizona hormone optimization clinics is normalizing preventive expenditure.
- Athletes:Competitive and semi-competitive populations demand NSF Certified for Sport or Informed Sport accreditation. Certification timelines of 14-18 months create barriers to entry for new market participants.
- Bodybuilders:High-volume consumers with sophisticated stacking protocols prioritize raw ingredient transparency and bulk pricing. Forum-driven brand reputation shapes purchase decisions more than advertising.
Fitness enthusiasts generate the steepest volume growth trajectory while older adults provide the most stable recurring revenue foundation.
Distribution Channel:
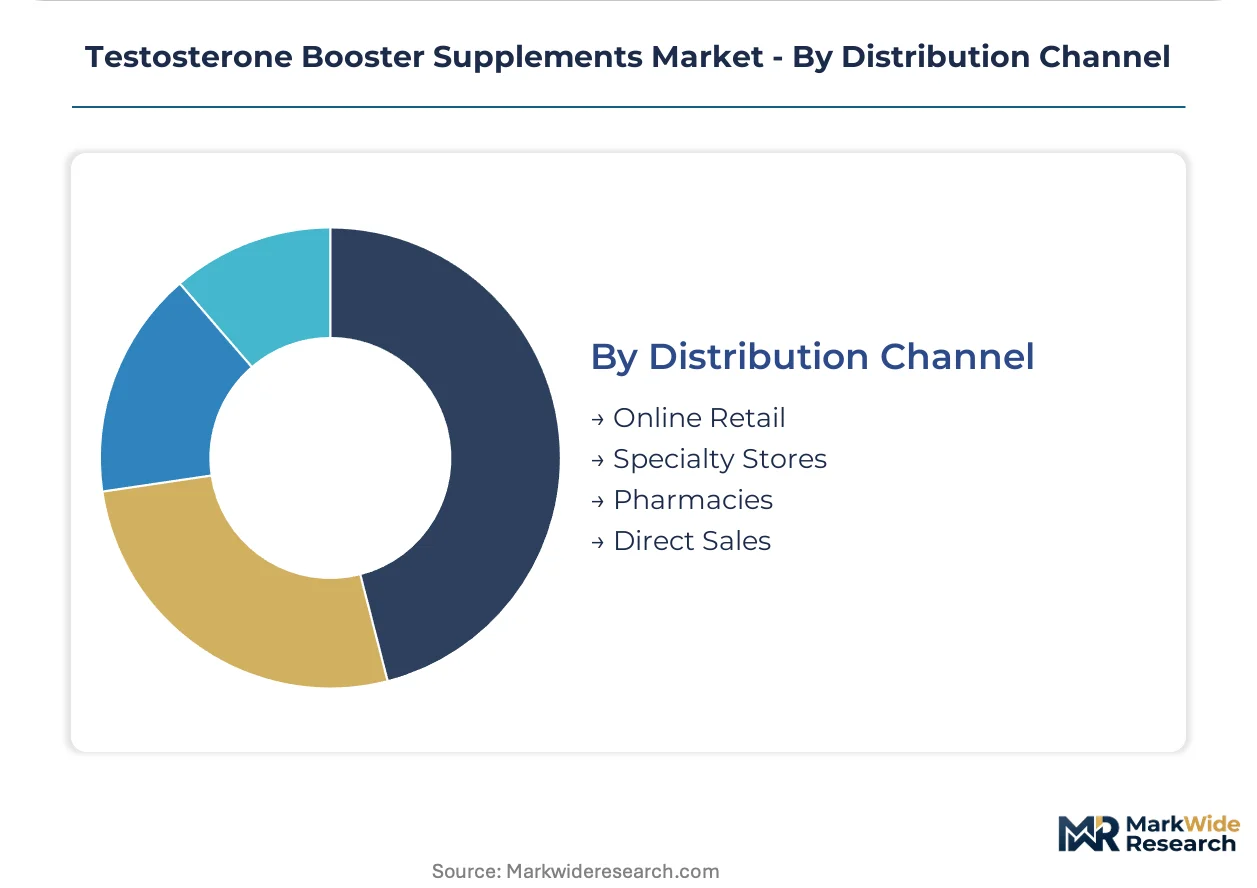
Channel selection determines margin structure, customer data ownership, and regulatory exposure intensity for testosterone booster brands.
- Online Retail:Amazon, brand-direct sites, and subscription platforms capture the majority of volume in the United States. FTC scrutiny of influencer testimonials and before-and-after imagery is reshaping customer acquisition compliance costs.
- Specialty Stores:GNC, Vitamin Shoppe, and independent sports nutrition retailers provide tactile trial and staff recommendation. Foot traffic dependency creates vulnerability to location-specific demographic shifts.
- Pharmacies:CVS, Walgreens, and Rite Aid placements legitimize the category for skeptical first-time buyers. Planogram competition with established pharmaceutical brands limits SKU breadth.
- Direct Sales:Telehealth-integrated hormone clinics and multi-level marketing networks enable personalized protocol bundling. Regulatory classification ambiguity creates compliance overhead.
Online retail commands the dominant volume position while pharmacy partnerships are gaining legitimacy share fastest among aging demographic entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fenugreek seed processing clusters in Rajasthan and Gujarat expose brands to monsoon-dependent harvest volatility, while regulatory divergence across major markets fragments compliance pathways for standardized botanical extracts.
United States
Telehealth-integrated hormone clinics in Texas, Florida, and Arizona bundle testosterone support supplements with diagnostic panels, normalizing preventive male health expenditure. The FDA's DSHEA enforcement and cGMP compliance audits shape manufacturing standards and adverse event reporting obligations for domestic producers. Direct-to-consumer subscription platforms concentrate in California and Colorado, where auto-ship infrastructure enables predictable recurring revenue models.
Germany
Low testosterone supplement penetration relative to protein powder consumption suggests latent demand activation potential through education-focused marketing. EMA's evolving guidance on botanicals tightens heavy metal and pesticide residue thresholds for fenugreek, ashwagandha, and tribulus terrestris imports. European contract manufacturers in Bavaria consolidate supplier audits to preempt border rejection risk.
Brazil
Resistance training adoption among men aged 35-55 creates first-time supplement users without established brand loyalties. ANVISA's evolving supplement registration framework clarifies import pathways for standardized botanical extracts. São Paulo's gym-adjacent specialty retailers concentrate demand for flavored bulk formulations enabling stack integration.
India
Fenugreek seed extract supply concentrates in Rajasthan and Gujarat, exposing brands to regional processing bottlenecks and harvest volatility. FSSAI streamlines health supplement registration through the Food Safety and Standards (Health Supplements, Nutraceuticals) Regulations, reducing time-to-market for compliant entrants. Maharashtra's contract manufacturing clusters attract brands diversifying from single-source processors.
United Kingdom
Pharmacy-retail hybrid formats legitimize supplement categories for skeptical first-time buyers seeking discrete consumption options. MHRA alignment with EMA botanical guidance shapes import compliance requirements for standardized extracts. London's direct-to-consumer brands leverage subscription bundling to displace single-SKU purchases among resistance-trained populations.
Testosterone Booster Supplements Market Competitive Landscape
Direct-response television heritage and digital-native subscription platforms split the market between incumbent auto-ship operators and challenger transparency brands. The competitive set stratifies across three archetypes: legacy infomercial brands with recurring revenue infrastructure, digitally native entrants competing on ingredient disclosure, and premium-positioned players leveraging third-party certification. M&A activity targets subscription platform capabilities, while portfolio diversification into adjacent sleep and recovery categories extends customer lifetime value.
Within the direct-response heritage tier, Nugenix exemplifies auto-ship retention mechanics built on television customer acquisition infrastructure. TestoPrime occupies a position anchored on price transparency and fully disclosed ingredient dosages. Transparent Labs sits within the premium certification segment, extending quality perception through third-party validation across the athlete segment. These three players collectively represent divergent strategic responses to FTC scrutiny of advertising claims and influencer marketing compliance costs.
| Leading Market Players |
|---|
| Testogen |
| Roman |
| Innerbody Labs |
| TestoFuel |
| Nugenix |
| TestoPrime |
| Transparent Labs |
| Nutricost |
| Testosil |
| Others |
Value Network & Pricing Analysis
Undercapacity in Rajasthan's fenugreek seed processing facilities during monsoon-disrupted harvest cycles forces brands to absorb spot-market premiums or reformulate around substitute botanicals, compressing margin flexibility across both premium and mass-market tiers.
Pricing Analysis
DSHEA dictates the pricing tier structure by imposing compliance cost burdens that stratify manufacturers by certification depth. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport products from cGMP-compliant tablets and unverified bulk powders. Cost compression in the economy tier is intensifying because telehealth-integrated hormone clinics capture aging male spend that botanical boosters previously accessed. Fitness enthusiasts in Brazil and Mexico exhibit highest price sensitivity, while older adults seeking pharmacy legitimacy show lowest elasticity.
Supply Chain Analysis
Fenugreek seed extract feedstock draws from Rajasthan and Gujarat in India, with secondary concentration in Chinese D-aspartic acid API facilities. Key inputs include standardized saponin concentrates, liposomal encapsulation compounds, and third-party certification services. Single-source vulnerability dominates as monsoon-dependent harvest volatility in western India exposes brands to regional processing bottlenecks. Distribution runs through direct-to-consumer subscription platforms, pharmacy-retail hybrid formats, and gym-adjacent specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription bundling economics are transforming testosterone boosters into platform-dependent recurring revenue businesses, with auto-ship infrastructure and diagnostic panel interoperability determining customer lifetime value capture.
For Market Incumbents: Harden subscription retention mechanics against telehealth-integrated hormone clinics that capture preventive male health expenditure through bundled diagnostic protocols. Prioritize NSF Certified for Sport or Informed Sport accreditation investment to defend athlete-segment positioning against challenger transparency brands. Build captive supply of fenugreek seed extract through backward integration into controlled-environment agriculture.
For New Entrants and Emerging Players: Germany's low testosterone supplement penetration relative to protein powder consumption offers education-focused marketing white space without entrenched brand loyalty. Target pharmacy-retail hybrid formats in European markets where EMA's tightening heavy metal thresholds have consolidated supplier qualification requirements around vertically integrated processors. Lead with fully disclosed ingredient dosages to differentiate from legacy infomercial brands.
For Investors and Strategic Acquirers: Capital is best deployed toward digital-native subscription platforms with demonstrated auto-ship retention metrics and cross-category bundling capabilities. Long-term viability hinges on telehealth interoperability and diagnostic panel integration rather than single-SKU transactional velocity. Watch for FDA draft guidance finalization on New Dietary Ingredient notifications as inflection indicator for formulation innovation runway.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Platform Integration | Auto-ship retention mechanics transform single-transaction economics into predictable recurring revenue streams. |
| Third-Party Certification Investment | NSF Certified for Sport accreditation unlocks athlete-segment entry with 14-18 month validation timelines. |
| Telehealth Partnership Development | Diagnostic panel bundling in Texas and Florida normalizes preventive male health expenditure. |
| Backward Integration into Botanical Supply | Controlled-environment agriculture secures fenugreek seed extract against monsoon-dependent harvest volatility. |
| Pharmacy-Retail Hybrid Expansion | Walgreens specialized men's health sections in Chicago and Houston legitimize supplements for skeptical first-time buyers. |
Research Methodology
The analysis maps pills, powders, liquids, and gels as delivery formats, each validated through contract manufacturing executives, sports nutrition retail buyers, hormone clinic operators, and regulatory affairs specialists. Primary interviews with formulation science directors and subscription platform operators combined with secondary validation against FDA warning letters, FTC consent decrees, EMA botanical guidance documents, and FSSAI registration databases. Bottom-up SKU-level demand modeling and top-down category spend estimates were triangulated.
Assumptions held fixed include DSHEA enforcement intensity, telehealth regulatory permissiveness, and fenugreek harvest yield coefficients; variables included subscription adoption rates and pharmacy channel expansion pace. Segmentation dimensions spanned product type, ingredient source, target consumer archetype, and distribution channel across the projection horizon. CAGRs derived from normalized historical growth patterns adjusted for fitness culture penetration curves and regulatory tailwinds.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth-integrated hormone clinics or pharmaceutical compounders would shift outcomes substantially. Cross-checking against protein powder category penetration benchmarks and preventive health expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
Medicinal Mushroom Supplement Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Ready-To-Use Therapeutic Food Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Organic Protein Powder Market