
 Melon Seed Market | 2026-2036
Melon Seed Market Size, Share, and Industry Trends Forecast 2026-2036
Melon Seed Market Analysis
The EU Green Deal is consolidating sustainability requirements across agricultural input supply chains, pushing European distributors toward certified seed sources. Sakata Seed Corp. leverages its Japan-based breeding infrastructure to supply heat-tolerant melon varieties to Mediterranean growers. East-West Seed anchors Southeast Asian market access through farmer-extension networks that emphasize open-pollinated lines. BASF SE differentiates via trait-stacked hybrids targeting reduced pesticide dependency in intensive greenhouse systems.
Melon seeds comprise the dried, germinable embryos of Cucumis melo and Citrullus lanatus species, typically processed to moisture levels below 8% to preserve viability across multi-year storage cycles. Commercial seed lots undergo germination testing, pathogen screening, and genetic purity verification before packaging for agricultural deployment. Watermelon seed lines command premium positioning in subtropical zones where F1 hybrid vigor justifies higher input costs against field productivity gains. Cantaloupe segments sustain volume leadership in North American and European fresh-market channels where netted-rind varieties dominate retail shelf space. Specialty stores and farmers' markets capture margin concentration through heritage and organic-certified cultivars that bypass commodity pricing dynamics.
China's MEE enforces stricter pesticide residue thresholds on seed coatings, while the USDA and EPA jointly regulate treated seed labeling and pollinator exposure protocols in US interstate commerce. The FAO International Treaty on Plant Genetic Resources shapes germplasm access terms that constrain proprietary breeding programs in developing markets. Stakeholders must monitor evolving phytosanitary barriers at import checkpoints and align variety portfolios with shifting heat-stress geographies before germplasm licensing windows narrow.
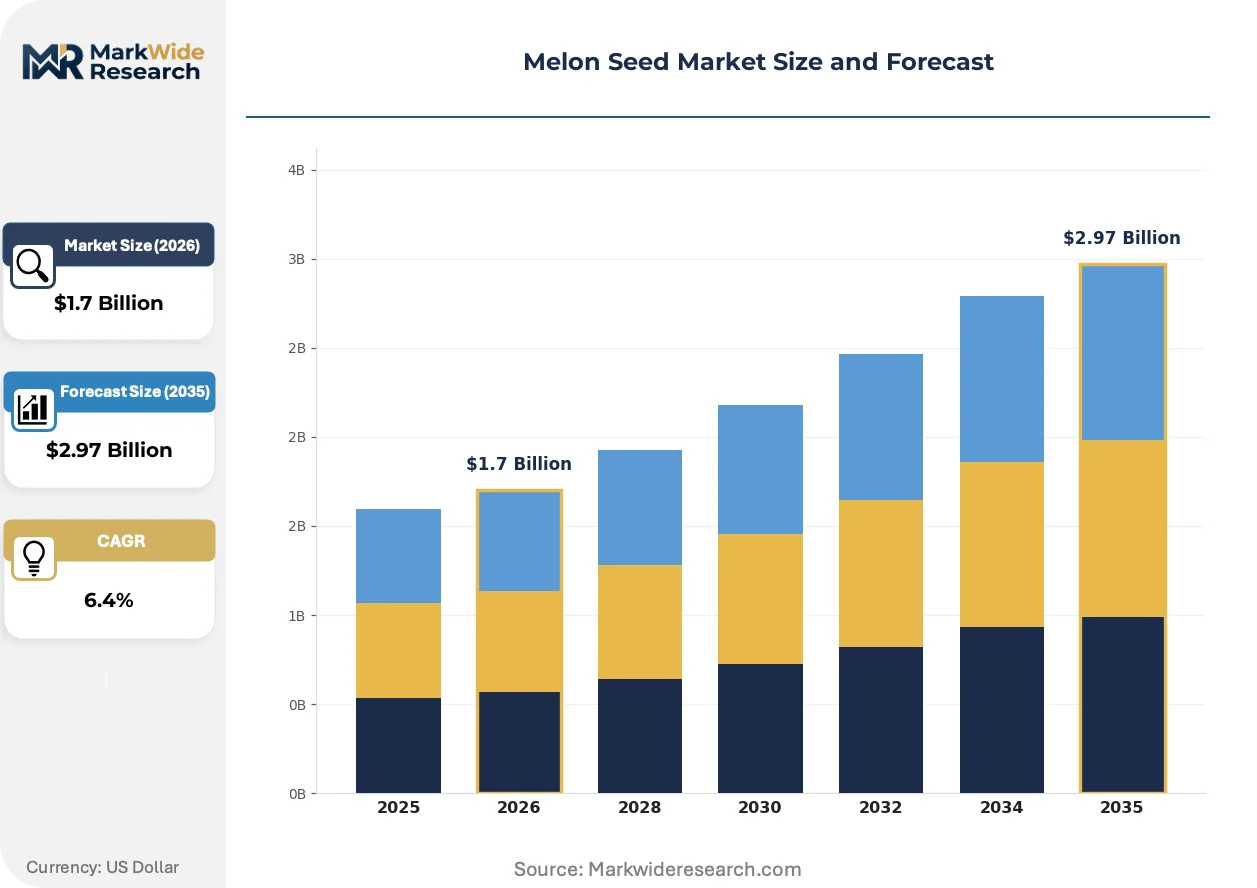
Market Dynamics
China's dual carbon goals are redirecting breeding investment toward drought-tolerant varieties while snack food manufacturers expand procurement of roasted and flavored melon seed products, creating dual pressure on germplasm development priorities.
Growth Catalysts
- EU Green Deal consolidation:Sustainability requirements across agricultural input supply chains push European distributors toward certified seed sources, tightening sourcing standards for Mediterranean growers.
- Heat-tolerant germplasm demand:Shifting heat-stress geographies in subtropical zones elevate demand for F1 hybrid vigor lines that justify higher input costs through field productivity gains.
- Xinjiang processing infrastructure:Large-scale melon cultivation clusters around regional seed production hubs, concentrating demand in China's western province with integrated processing capabilities.
Market Restraints
- Input cost volatility:Energy-intensive drying operations to reach below 8% moisture levels for multi-year storage face pressure from fluctuating natural gas and electricity tariffs.
- Supply concentration risk:Germplasm licensing windows narrow as the FAO International Treaty on Plant Genetic Resources constrains proprietary breeding programs in developing markets.
- Regulatory friction:China's MEE enforces stricter pesticide residue thresholds on seed coatings, requiring reformulation of established treatment protocols.
Strategic Opportunities
- Heritage cultivar channels:Specialty stores and farmers' markets capture margin concentration through organic-certified lines that bypass commodity pricing dynamics in North American fresh-market channels.
- Greenhouse system hybrids:Trait-stacked varieties targeting reduced pesticide dependency address intensive protected cultivation expansion in water-stressed regions.
- Farmer-extension network replication:Open-pollinated line distribution models proven in Southeast Asia offer transferable templates for smallholder penetration in Sub-Saharan Africa.
Industry Challenges
- Phytosanitary certification timelines:Evolving import checkpoint barriers delay seed lot releases after germination testing and pathogen screening, compressing planting-season windows.
- Genetic purity verification costs:Molecular marker-based testing for commercial seed lots requires capital-intensive laboratory infrastructure that mid-scale breeders struggle to amortize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Melon Seed Market |
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cantaloupe, Watermelon, Honeydew, Others Distribution Channel: Online Retail, Supermarkets, Farmers' Markets, Specialty Stores End User: Agricultural Producers, Home Gardeners, Food Processors, Retailers Packaging Type: Bulk, Retail Packs, Vacuum Sealed, Bags |
| Companies Covered | Sakata Seed Corp., East-West Seed, BASF SE, Takii & Co., Advanta Seeds, Bayer AG, Syngenta Crop Protection AG, Rijk Zwaan Zaadteelt en Zaadhandel B.V., Groupe Limagrain Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Melon Seed Market Emerging Trajectories
Breeding programs are converging with digital phenotyping and climate-adaptive selection protocols, compressing variety development cycles while regulatory frameworks tighten traceability requirements across seed value chains.
Hyperspectral imaging systems paired with machine learning classifiers are automating seed lot quality assessment, replacing manual germination counts and visual purity inspections. Large-scale processors in Xinjiang and California's Central Valley deploy these systems at intake points to sort by viability tiers. The technology is automating throughput bottlenecks that previously constrained seasonal procurement volumes.
The EU Green Deal's CSRD disclosure mandates now extend to agricultural input supply chains, requiring seed distributors to document carbon intensity across breeding, processing, and transport stages. Mediterranean growers face compliance deadlines that favor suppliers with verified lifecycle data. Netted-rind cantaloupe segments for European retail channels bear the heaviest documentation burden, accelerating supplier consolidation toward integrated breeding houses.
Roasted and flavored melon seed products are displacing raw commodity sales as snack manufacturers build direct procurement relationships with processors, bypassing traditional commodity exchanges. This channel compression concentrates margin capture with brands controlling flavor formulation and retail placement. The shift is most visible in China's urban convenience retail and North American natural food channels where heritage positioning commands shelf space premiums.
Melon Seed Market Segmentation
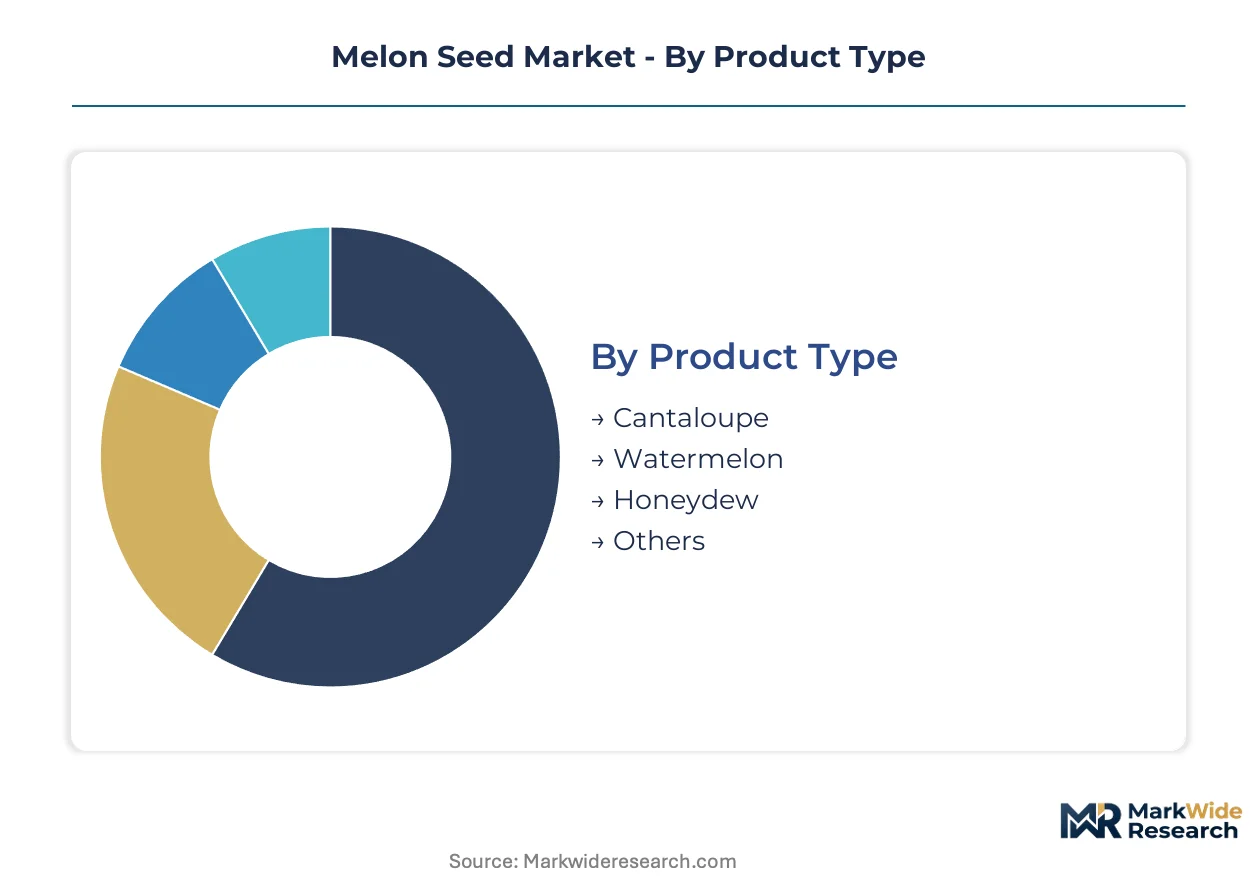
Melon seed segmentation reveals divergent margin structures across germplasm grades and channel formats. Breeders optimize variety portfolios differently for commodity field production versus protected cultivation systems.
Product Type:
Volume leadership sits with open-field commodity varieties, while premium capture concentrates in protected-cultivation hybrids with stacked disease resistance traits.
- Watermelon:F1 hybrid lines dominate subtropical zones where heat tolerance and synchronous fruit set justify elevated seed costs against yield gains. China's Xinjiang province anchors procurement volume for processing-grade seed stock. Demand concentrates among large-scale producers supplying snack manufacturers with roasted kernel feedstock.
- Cantaloupe:Netted-rind varieties command shelf space premiums in North American and European fresh-market channels. Netted-rind types face heaviest EU Green Deal documentation burden, accelerating supplier consolidation toward integrated breeding houses with verified lifecycle data.
- Honeydew:Smooth-rind cultivars serve processing channels for pre-cut fruit and juice concentrate.
- Others:Heritage landraces and specialty melons including Persian, Crenshaw, and Santa Claus types.
Mature deployment sits with Cantaloupe. Newer deployment is concentrated in Watermelon hybrid systems.
Distribution Channel:
Channel selection determines margin capture and traceability burden, with direct procurement relationships displacing traditional commodity exchange intermediaries.
- Supermarkets:Volume aggregation for standardized netted-rind cantaloupe and seedless watermelon varieties with consistent Brix specifications. EU CSRD disclosure mandates now extend to agricultural input supply chains, requiring distributors to document carbon intensity across breeding and transport stages.
- Specialty Stores:Heritage and organic-certified cultivars bypass commodity pricing through provenance storytelling and cultivar-specific labeling. North American natural food channels award shelf space premiums to varieties with drought-tolerant germplasm credentials.
- Online Retail:Direct-to-grower platforms for home gardener seed packets and small-lot agricultural procurement.
- Farmers' Markets:Local provenance verification and open-pollinated line distribution with minimal treatment documentation.
Volume throughput concentrates with Supermarkets. Margin expansion is climbing fastest in Specialty Stores.
End User:
User type dictates germplasm specification complexity, from pathogen-screened commercial lots to untreated heritage selections.
- Agricultural Producers:Commercial seed lots undergo germination testing, pathogen screening, and genetic purity verification before field deployment. Large-scale operations in California's Central Valley deploy hyperspectral imaging at intake points to sort by viability tiers, automating throughput bottlenecks.
- Food Processors:Snack manufacturers build direct procurement relationships with Xinjiang and Central Valley processors, bypassing commodity exchanges for roasted and flavored kernel supply. Channel compression concentrates margin capture with brands controlling flavor formulation.
- Home Gardeners:Small-lot retail packs with basic viability guarantees and heritage cultivar positioning.
- Retailers:Private-label seed programs with standardized treatment protocols and packaging formats.
Input standardization is deepest with Agricultural Producers. Procurement flexibility is expanding most quickly among Food Processors.
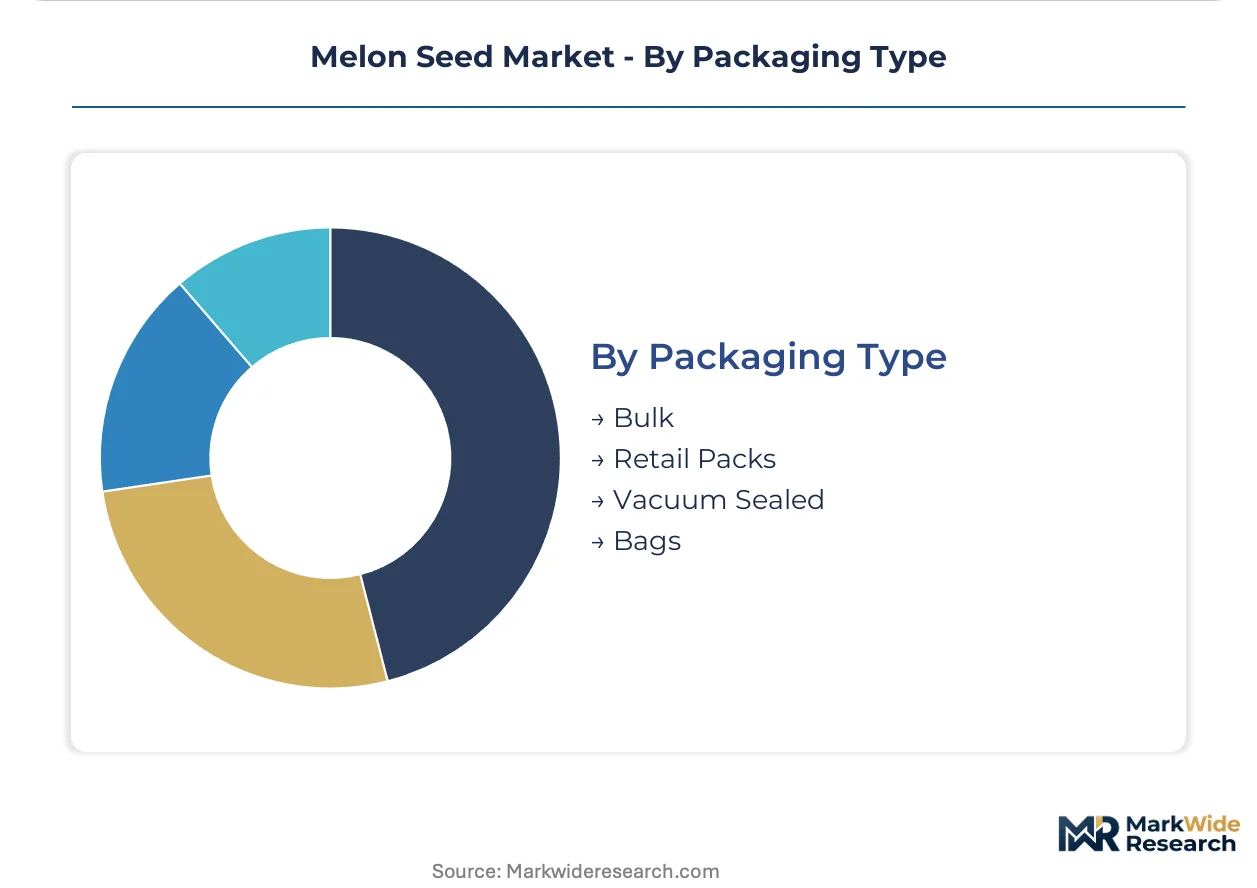
Packaging Type:
Packaging selection balances moisture control requirements against handling economics across storage durations.
- Vacuum Sealed:Multi-year viability preservation for germplasm banks and strategic reserve stockpiles, maintaining moisture levels below 8% through barrier film technologies. Energy-intensive drying operations face pressure from fluctuating natural gas tariffs.
- Bulk:Commodity-scale distribution to large agricultural producers with rapid turnover and minimal storage duration.
- Retail Packs:Branded consumer formats with cultivar imagery and basic planting instructions.
- Bags:Standard woven polypropylene for short-haul distribution to processing facilities.
Long-duration storage relies on Vacuum Sealed. Short-cycle turnover dominates Bulk deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Xinjiang's Turpan-Hami corridor anchors commercial seed production through integrated melon cultivation and processing infrastructure that supplies both agricultural and snack food channels.
China
Dual carbon goals redirect breeding investment toward drought-tolerant varieties while MEE enforces stricter pesticide residue thresholds on seed coatings. Large-scale processors in Xinjiang deploy hyperspectral imaging at intake points to sort viability tiers, automating throughput for snack manufacturer procurement.
United States
USDA and EPA jointly regulate treated seed labeling and pollinator exposure protocols across interstate commerce. California's Central Valley clusters germplasm development with hyperspectral deployment at commercial seed lot intake points, serving fresh-market cantaloupe channels.
Netherlands
EU Green Deal CSRD disclosure mandates extend to agricultural input supply chains, requiring carbon intensity documentation across breeding and transport stages. Wageningen-anchored breeding houses consolidate supplier relationships with Mediterranean growers facing compliance deadlines for netted-rind cantaloupe segments.
Japan
METI standards shape heat-tolerant germplasm development for subtropical zone deployment. Kanto-based breeding infrastructure supplies hybrid vigor lines to Southeast Asian extension networks, compressing variety development cycles through digital phenotyping protocols.
Thailand
Farmer-extension networks emphasize open-pollinated line distribution models proven across Southeast Asian smallholder penetration. Bangkok-centered seed distributors replicate East-West Seed's extension templates for Sub-Saharan Africa market development, bypassing commodity exchange intermediaries.
Melon Seed Market Vendor Landscape
Premium-margin players sit above commodity-margin players across germplasm certification and trait-stacking dimensions. The vendor base stratifies between integrated breeding houses with verified lifecycle data and regional distributors dependent on licensed germplasm. Three archetypes dominate: heat-tolerance specialists serving subtropical zones, heritage cultivar curators targeting specialty retail channels, and protected-cultivation hybrid developers for intensive greenhouse systems. Capacity expansion and strategic partnerships represent the dominant competitive moves, with breeding houses consolidating to meet EU documentation burdens.
Within the integrated breeding tier, Sakata Seed Corp., East-West Seed, and BASF SE exemplify divergent geographic and technological positioning. Sakata Seed Corp. anchors Japan-based heat-tolerant development for Mediterranean deployment. East-West Seed occupies the Southeast Asian extension-network archetype with open-pollinated line distribution. BASF SE sits within the trait-stacked hybrid segment targeting reduced pesticide dependency in protected cultivation systems.
| Leading Market Players |
|---|
| Sakata Seed Corp. |
| East-West Seed |
| BASF SE |
| Takii & Co. |
| Advanta Seeds |
| Bayer AG |
| Syngenta Crop Protection AG |
| Rijk Zwaan Zaadteelt en Zaadhandel B.V. |
| Groupe Limagrain Holding |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between F1 hybrid vigor lines and commodity open-pollinated varieties manifests in both pricing premiums and supply chain configuration complexity. EU Green Deal CSRD disclosure mandates impose documentation burdens that concentrate margin capture with integrated breeding houses possessing verified lifecycle data, while snack food manufacturers bypass commodity exchanges through direct procurement relationships with Xinjiang processors.
Pricing Analysis
Yield-per-hectare outcomes anchor value-based pricing for F1 hybrid watermelon lines in subtropical zones, where heat tolerance and synchronous fruit set justify elevated seed costs against field productivity gains. Three-tier pricing structure across premium, standard, and economy levels separates trait-stacked greenhouse hybrids from netted-rind cantaloupe varieties and bulk commodity field stock. Cost compression in energy-intensive drying operations is intensifying because fluctuating natural gas tariffs pressure processors maintaining below-8% moisture thresholds. Agricultural producers in California's Central Valley exhibit highest price sensitivity due to input cost volatility, while snack manufacturers controlling flavor formulation show lowest sensitivity given captive shelf placement economics.
Supply Chain Analysis
Phytosanitary certification gating delays seed lot releases after germination testing and pathogen screening, compressing planting-season windows and concentrating supply relationships with laboratories possessing molecular marker infrastructure. Production gravity centers on China's Xinjiang province, the United States, and the Netherlands, with germplasm development anchored in Japan and Thailand extension networks. Raw material dependencies include germplasm licensing from FAO treaty-constrained gene banks, energy inputs for vacuum-sealed packaging, and treated seed coating formulations facing MEE residue threshold reformulation. Single-source vulnerability runs through proprietary hybrid parent lines controlled by integrated breeding houses. Distribution runs through direct procurement channels displacing traditional commodity exchanges, with hyperspectral imaging deployment at intake points automating viability tier sorting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperspectral imaging and machine learning classifiers are displacing manual germination counts and visual purity inspections, compressing quality assessment timelines while regulatory traceability requirements tighten across seed value chains.
For Market Incumbents: Acquire hyperspectral imaging infrastructure and molecular marker laboratory capacity to defend against mid-scale breeders struggling to amortize genetic purity verification costs. Consolidate backward integration into Xinjiang processing facilities to secure roasted kernel feedstock relationships with snack manufacturers bypassing commodity exchanges. Prioritize EU Green Deal CSRD documentation capabilities to capture Mediterranean grower compliance deadlines for netted-rind cantaloupe segments. For New Entrants and Emerging Players: Capture heritage cultivar margin concentration in North American specialty stores and farmers' markets where organic-certified lines bypass commodity pricing dynamics through provenance storytelling. Penetrate Sub-Saharan Africa through farmer-extension network replication of East-West Seed's open-pollinated line distribution templates, bypassing commodity exchange intermediaries. Deploy direct-to-grower digital platforms for home gardener seed packets as lowest-capital entry vector. For Investors and Strategic Acquirers: Re-rating potential sits with integrated breeding houses possessing verified lifecycle data given EU CSRD disclosure mandate expansion across agricultural input supply chains. Long-term viability framing favors archetypes controlling trait-stacked hybrid development for protected cultivation systems in water-stressed regions. Watch for inflection upon FAO International Treaty germplasm licensing window narrowing that constrains proprietary breeding programs in developing markets.| Strategic Initiative | Industry Significance |
|---|---|
| Hyperspectral Imaging Deployment | Automates throughput bottlenecks at Xinjiang and Central Valley intake points for viability tier sorting. |
| CSRD Documentation Investment | Captures Mediterranean grower compliance deadlines for netted-rind cantaloupe supply consolidation. |
| Direct Procurement Relationships | Bypasses commodity exchanges for roasted kernel supply to snack manufacturers controlling flavor formulation. |
| Farmer-Extension Network Replication | Transfers East-West Seed's open-pollinated templates to Sub-Saharan Africa smallholder penetration. |
| Trait-Stacked Hybrid Development | Addresses reduced pesticide dependency in intensive greenhouse systems expanding across water-stressed regions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this melon seed market assessment, combined with primary interviews with breeding program directors, seed processing facility managers, agricultural extension officers, and snack food procurement leads. Secondary sources included FAO International Treaty germplasm access documentation, China MEE pesticide residue threshold enforcement records, USDA treated seed labeling regulations, and EU Green Deal CSRD disclosure mandate guidance. Bottom-up variety deployment modeling and top-down agricultural input market sizing were triangulated against hyperspectral imaging adoption rates and direct procurement channel growth indicators.
Data-stream reconciliation across germplasm licensing volumes, processing capacity utilization, and retail channel placement metrics informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled included melon type, distribution channel format, end-user specification complexity, and packaging moisture control technology. CAGRs were derived from trend extrapolation of breeder R&D allocation patterns and snack manufacturer procurement expansion trajectories. Climate-adaptive selection protocol adoption and digital phenotyping deployment timelines served as industry-specific forecast inputs.
The model holds under sustained EU regulatory disclosure expansion and stable germplasm licensing access terms; deviation in FAO treaty renegotiation outcomes or abrupt phytosanitary barrier escalation would shift variety development geographic concentration and procurement channel structure assumptions. Forecasts reflect documented breeding investment redirection toward drought-tolerant varieties under China's dual carbon goals and MEE coating reformulation requirements. A model refresh is warranted upon material change in hyperspectral imaging cost curves or CSRD mandate enforcement intensity across Mediterranean agricultural input supply chains.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Global Rice Seed Market
Seeds
Drought Tolerant Seeds Market
Seeds
Citrus Seeds Market
Seeds
Carrot Seed Oil Market
Seeds
South America Chia Seeds Market
Seeds
Seed Health Market
Seeds
Russia Seed Market
Seeds
North America Grain Seed Market
Seeds
Dragon Fruit Seeds Market
Seeds
Cannabis Seeds Market
Seeds
Canary Seeds Market
Seeds
Philippines Rice Seed Market
Seeds
Avena Sativa Market
Seeds
Bangladesh Seed Market
Seeds
Buckwheat Market
Seeds
Faba Beans Market