

Advanced Node Wafer Defect Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Node Wafer Defect Inspection Systems Market Insights
EUV photoresist chemistry is pivoting from chemically amplified resists to metal oxide resists as resolution requirements tighten below thirteen nanometers, altering defect contrast economics for inspection tool makers. KLA Corporation leverages its installed base of broadband plasma tools to sustain pricing power in logic foundry accounts. Applied Materials anchors its position through in-house production of electron beam columns, reducing dependency on external column suppliers. Lasertec competes aggressively in actinic mask inspection, where it occupies a near-monopoly position for EUV photomask qualification.
Advanced node wafer defect inspection systems are precision metrology platforms that detect, classify, and localize sub-ten-nanometer defects on semiconductor wafers using wavelengths from deep ultraviolet through soft X-ray, operating at throughputs exceeding one hundred wafers per hour for optical modes and single-digit wafers per hour for electron beam modes, with the primary purpose of preventing yield collapse in sub-seven-nanometer manufacturing flows. Electron beam inspection commands the highest average selling prices due to its resolution supremacy, though optical inspection retains volume leadership because throughput constraints limit e-beam deployment to critical layer sampling. Metrology-integrated systems are gaining fastest among product types as foundries seek to collapse separate measurement and inspection steps into unified process control loops.
The US Department of Commerce export controls on advanced semiconductor manufacturing equipment shape market access for inspection tools bound for certain Chinese fabs, while the EU Chips Act and Japan's METI subsidies redirect procurement toward domestic or allied-nation suppliers. FDA and ISO 14644 cleanroom standards indirectly govern tool design by mandating particulate limits that inspection systems must themselves not violate during operation. Stakeholders must monitor how actinic inspection technology maturity affects the competitive boundary between optical and electron beam modalities at each successive node transition.
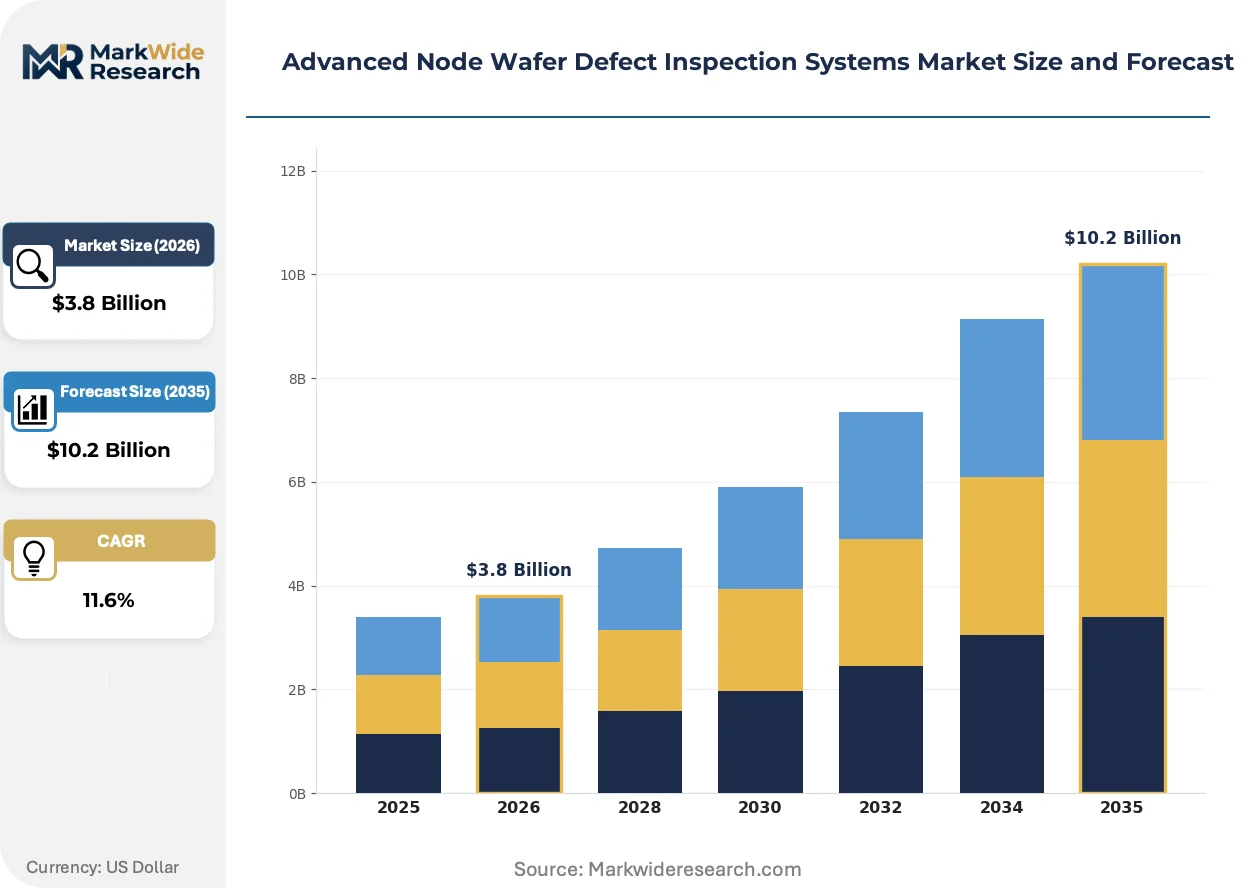
Market Dynamics
EUV node transitions below three nanometers are compressing defect tolerance windows to atomic-scale dimensions, forcing foundries to triple inspection sampling rates at critical lithography layers while tool vendors race to deliver higher-resolution platforms without sacrificing wafer throughput.
Growth Catalysts
- Japan's METI Semiconductor Subsidy Program:Domestic capital reallocation toward inspection equipment supply chains is accelerating local vendor qualification timelines for advanced node tools.
- Metal Oxide Resist Chemistry:The pivot from chemically amplified resists is creating new defect contrast signatures that demand upgraded inspection sensitivity across logic foundry process flows.
- Hsinchu Science Park Cluster:TSMC and allied foundries operate the densest concentration of sub-five-nanometer production, concentrating procurement volume for metrology-integrated systems.
Market Restraints
- E-beam Column Supply Concentration:Electron beam inspection systems depend on a limited supplier base for high-voltage column assemblies, creating single-source vulnerability for resolution-critical subcomponents.
- US Department of Commerce Export Controls:Licensing restrictions on advanced semiconductor manufacturing equipment are blocking market access for inspection tools bound for certain Chinese fabs.
- Throughput-Resolution Tradeoff:Electron beam inspection's single-digit wafers per hour throughput limits deployment to critical layer sampling, constraining addressable volume within high-volume manufacturing flows.
Strategic Opportunities
- South Korea's K-Semiconductor Belt:Government-directed investment in domestic equipment ecosystems is opening qualification pathways for non-incumbent inspection vendors.
- Metrology-Integration Convergence:The collapse of separate measurement and inspection steps into unified process control loops is creating demand for hybrid optical-electron beam platforms.
- Actinic Mask Inspection:EUV photomask qualification at wavelength-matched inspection nodes represents an underpenetrated segment where specialized optics command premium positioning.
Industry Challenges
- Cleanroom Particulate Compliance:FDA and ISO 14644 standards mandate operational particulate limits that inspection systems must not violate, complicating tool architecture for sub-ten-nanometer detection.
- Multi-Modal Integration Complexity:Foundries face execution risk when collapsing separate optical and electron beam inspection workflows into single-platform process control loops.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Node Wafer Defect Inspection Systems Market Trends and Innovations
Inspection modality boundaries are dissolving as resolution requirements outpace pure optical throughput and electron beam platforms struggle to scale economically. Vendors are converging on hybrid architectures that blend speed and precision.
Metal oxide photoresist formulations are absorbing the resolution burden previously carried by inspection system upgrades, enabling foundries to extend existing broadband plasma tool lifecycles at nodes where chemically amplified resists fail. Logic chip manufacturers in Taiwan and South Korea are adopting these materials at the three-nanometer node transition. This chemistry shift is absorbing capital that would otherwise flow to next-generation electron beam platforms, compressing the addressable market for ultra-high-resolution inspection at non-critical layers.
The EU Chips Act's domestic content requirements are redirecting procurement decisions toward allied-nation equipment suppliers, with compliance thresholds tightening through 2027. European foundry projects in Germany and France now prioritize inspection tool vendors with EU-based service infrastructure. Memory manufacturers operating within the bloc are responding by dual-qualifying domestic and Asian suppliers to hedge against supply disruption.
Foundry buyers are consolidating vendor relationships from multi-source optical-electron beam pairings to single-platform metrology-integrated contracts, collapsing separate procurement cycles. Equipment purchasing teams at leading logic manufacturers now specify unified process control loops rather than discrete inspection and measurement tools. This pattern is most visible in Taiwan's Hsinchu cluster, where TSMC and allied foundries have standardized on combined platforms for sub-five-nanometer layers.
Advanced Node Wafer Defect Inspection Systems Market Segmentation
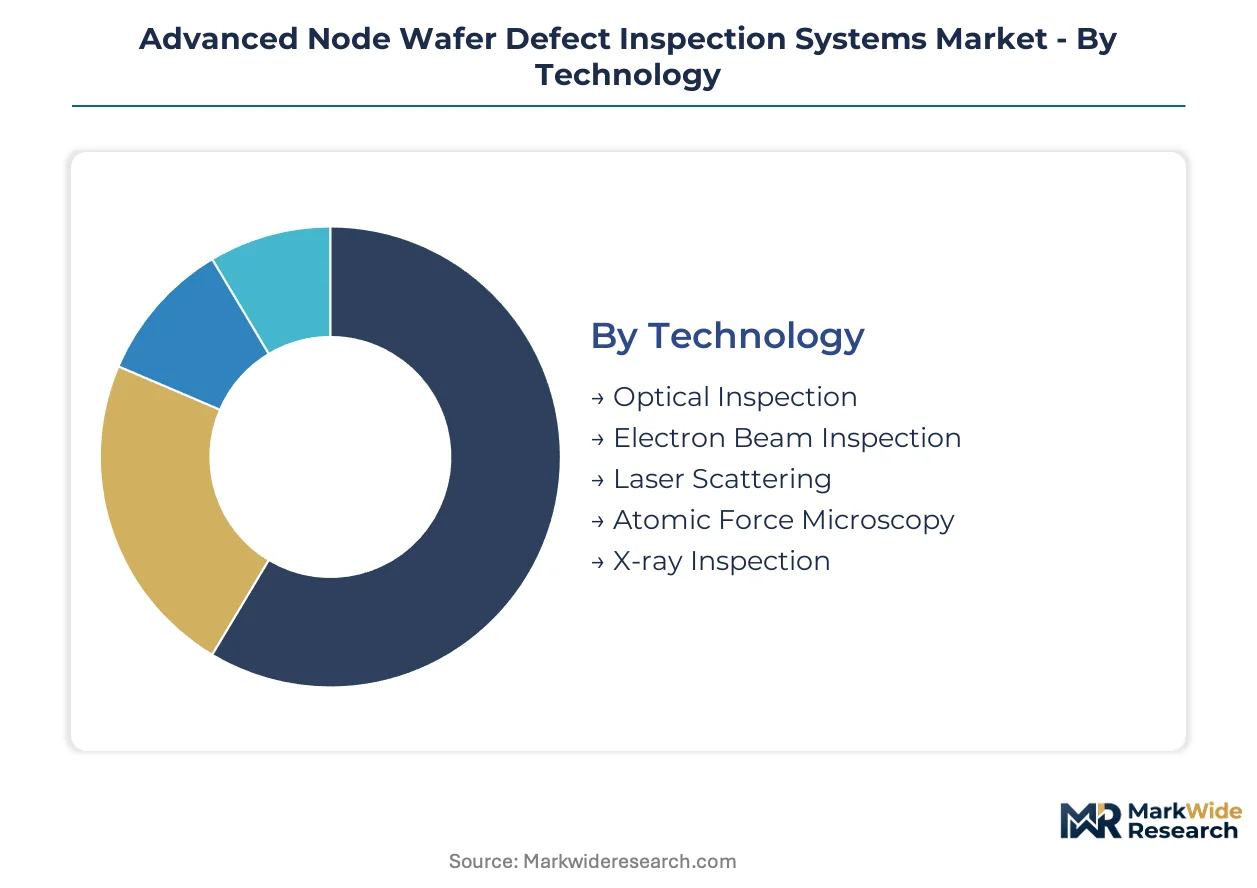
Technology-product-application-end user intersections determine procurement specifications for advanced node inspection systems. Foundries configure multi-modal tool suites differently across logic versus memory process flows. Understanding these segment boundaries clarifies where capital concentrates and where qualification barriers protect incumbent positions.
Technology:
Standardization dominates high-throughput optical platforms while electron beam systems demand extensive customization for each foundry's critical layer recipes.
- Optical Inspection:Broadband plasma and deep ultraviolet platforms scan wafers at speeds exceeding one hundred wafers per hour. TSMC's Hsinchu cluster deploys these systems across non-critical layers at three-nanometer nodes where metal oxide resists relax resolution requirements.
- Electron Beam Inspection:High-voltage column architectures achieve sub-nanometer resolution for critical layer sampling. Throughput constraints limit deployment to single-digit wafers per hour, restricting addressable volume to EUV lithography qualification steps at leading foundries.
- Laser Scattering:Non-actinic wavelength detection for macro-defect identification on bare silicon substrates.
- Atomic Force Microscopy:Three-dimensional surface profiling for research-phase process development at sub-five-nanometer nodes.
- X-ray Inspection:Soft X-ray transmission for buried defect detection in three-dimensional NAND stacks.
Most installed capacity flows through Optical Inspection. Expansion is steepest in Electron Beam Inspection.
Product Type:
Cost tier stratification separates capital-intensive inline systems from lower-margin offline and review platforms serving yield analysis laboratories.
- Inline Inspection Systems:Production-integrated tools operating within lithography-etch-clean sequences without breaking vacuum. South Korea's K-Semiconductor Belt foundries prioritize these platforms for real-time process control at Samsung's Pyeongtaek complex.
- Metrology-Integrated Systems:Unified platforms collapsing separate measurement and inspection steps into single process control loops. Taiwan's foundry buyers now specify these hybrid architectures as standard procurement for sub-five-nanometer layers.
- Offline Inspection Systems:Standalone tools for engineering analysis outside production flow constraints.
- Review Systems:Defect verification and classification stations feeding yield management databases.
- Mask Inspection Equipment:Actinic and non-actinic platforms for EUV photomask qualification.
Procurement volume concentrates in Inline Inspection Systems. Metrology-Integrated Systems are climbing the fastest as foundries consolidate vendor relationships.
Application:
Volume scale differentiates silicon wafer inspection serving high-volume logic foundries from specialized compound semiconductor applications.
- Silicon Wafer Inspection:Dominant application spanning front-end-of-line through back-end-of-line process steps for CMOS logic and memory devices.
- Photomask Defect Detection:Critical for EUV lithography yield assurance as mask complexity increases with each node shrink.
- Compound Semiconductor Inspection:Silicon carbide and gallium nitride wafer qualification for power electronics and RF applications.
- Thin Film Analysis:Metrology for atomic layer deposition and chemical vapor deposition process control.
- Packaging Defect Identification:Advanced packaging inspection for chiplets and three-dimensional integration schemes.
Silicon Wafer Inspection carries the largest installed base. Photomask Defect Detection is expanding most quickly as EUV adoption accelerates.
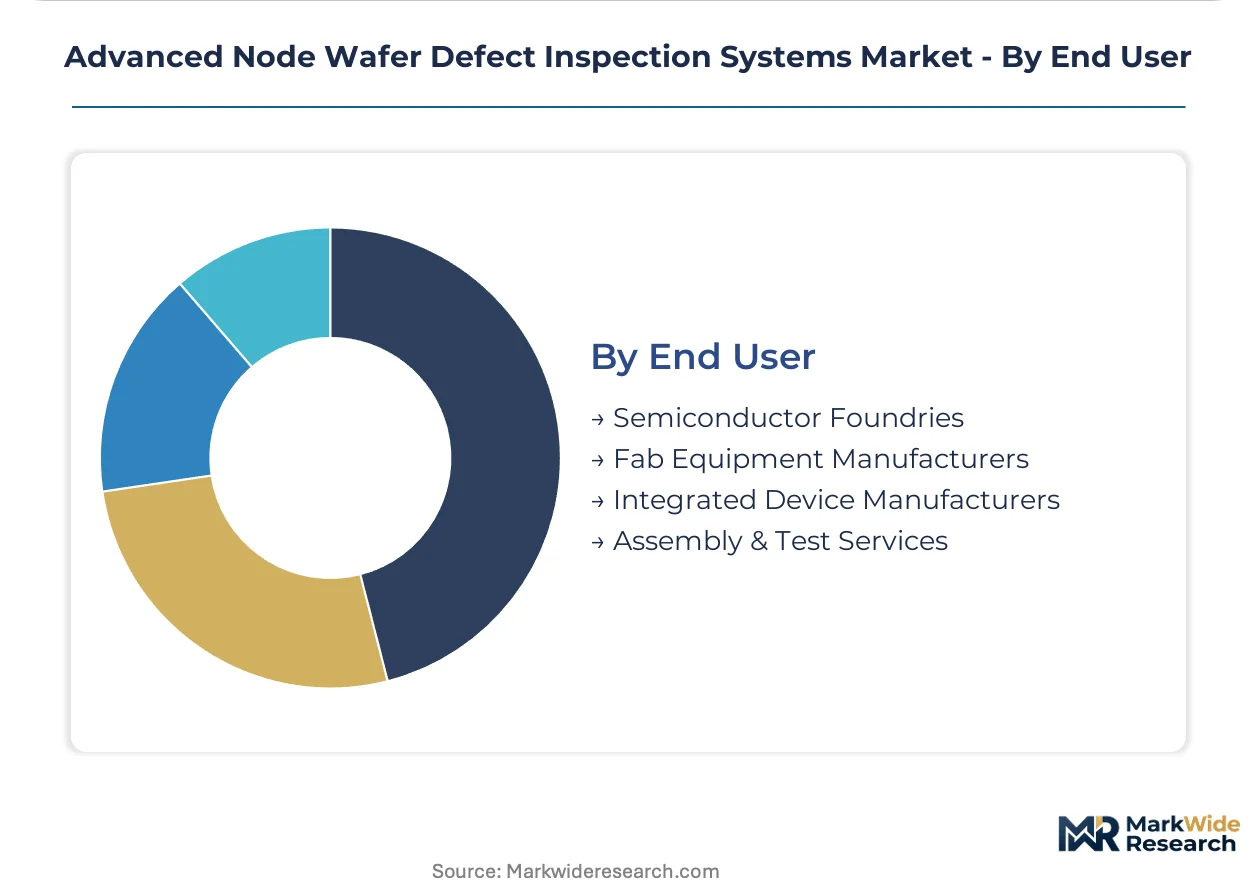
End User:
Customer type shapes pricing architecture and service intensity, with foundries demanding highest tool uptime guarantees.
- Semiconductor Foundries:Pure-play and integrated foundries operate the densest inspection tool concentrations. These buyers specify multi-year service contracts with guaranteed availability thresholds above ninety-five percent.
- Integrated Device Manufacturers:Vertically integrated memory and logic manufacturers with captive inspection operations.
- Fab Equipment Manufacturers:Tool vendors integrating inspection modules into larger process equipment platforms.
- Assembly & Test Services:Outsourced semiconductor assembly and test providers inspecting packaged devices.
Semiconductor Foundries absorb the majority of capital deployment. Fab Equipment Manufacturers are gaining share fastest through module integration strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park concentrates the densest procurement activity for sub-five-nanometer inspection systems, with TSMC and allied foundries driving metrology-integrated platform adoption. Government subsidy programs across Japan, South Korea, and the United States are redirecting capital toward domestic equipment supply chains.
United States
Silicon Valley fabs and Austin-area manufacturing complexes are expanding EUV lithography lines that require upgraded defect inspection sensitivity. The Department of Commerce export controls on advanced semiconductor equipment are restricting tool shipments to certain Chinese fabs while channeling domestic procurement toward allied-nation vendors. Intel's Oregon and Arizona operations anchor the highest concentration of sub-seven-nanometer pilot production outside Asia.
Japan
Tokyo Electron and Lasertec anchor a domestic equipment ecosystem that supplies actinic mask inspection systems for EUV photomask qualification. METI's semiconductor subsidy program is accelerating local vendor qualification timelines for advanced node tools. The Kyushu region's Kumamoto and Fukuoka prefectures host expanding foundry projects that are standardizing on domestically sourced inspection platforms.
South Korea
Samsung's Pyeongtaek complex and SK Hynix's Icheon operations are tripling inspection sampling rates at critical lithography layers below three nanometers. The K-Semiconductor Belt initiative is directing government investment toward domestic equipment ecosystems and opening qualification pathways for non-incumbent vendors. Seoul Capital Area foundries are consolidating vendor relationships from multi-source pairings to single-platform metrology-integrated contracts.
Taiwan
TSMC's Hsinchu Science Park cluster operates the world's densest concentration of sub-five-nanometer production, concentrating demand for optical and electron beam inspection systems. The National Development Council's advanced manufacturing subsidies are supporting local equipment supplier development alongside dominant Japanese and American vendors. Taichung's Central Taiwan Science Park is emerging as a secondary hub for three-nanometer ramp activities requiring expanded inspection tool deployment.
China
Yangtze Memory Technologies and SMIC are advancing domestic inspection tool development amid restricted access to American and Japanese equipment. MIIT's semiconductor self-sufficiency directives are channeling state capital toward local metrology platform vendors. The Shanghai and Beijing clusters host the most advanced indigenous foundry operations, though EUV lithography access constraints limit node progression below seven nanometers.
Advanced Node Wafer Defect Inspection Systems Market Competitive Landscape
Global majors compete with regional champions across technology modality and geographic account access, with concentrated positions in electron beam columns and actinic optics protecting premium pricing tiers. The vendor base stratifies into three functional archetypes: integrated platform suppliers controlling full technology stacks, specialized component providers dominating resolution-critical subsystems, and regional equipment integrators serving captive domestic demand. Consolidation pressures are intensifying as foundry buyers collapse separate procurement cycles into unified vendor relationships, while technology licensing and strategic partnerships emerge as dominant competitive moves for capability gaps.
Among the integrated platform tier, KLA Corporation and Applied Materials exemplify archetypes of scale-driven suppliers with installed base leverage, while Lasertec occupies a specialized position in wavelength-matched mask inspection that commands premium positioning. These three companies anchor distinct competitive vectors: KLA through broadband plasma tool penetration, Applied Materials through in-house electron beam column production, and Lasertec through near-monopoly positioning in actinic EUV photomask qualification.
| Leading Market Players |
|---|
| KLA Corporation |
| ASML Holding |
| Applied Materials |
| Hitachi High-Tech Corporation |
| Onto Innovation |
| Lasertec |
| SCREEN Semiconductor Solutions |
| Camtek |
| Nova |
| Others |
Pricing and Supply Chain Analysis
Japanese and American integrated platform suppliers anchor pricing discipline through captive electron beam column production and multi-year service contracts with foundry buyers. Their ownership structures—publicly traded equipment majors with deep installed bases—enable sustained premium positioning at sub-five-nanometer nodes where qualification barriers protect incumbent positions.
Pricing Analysis
Input-cost pass-through from high-voltage column assemblies and precision optics flows directly into equipment pricing, with electron beam systems commanding the highest average selling prices due to resolution supremacy. Price differentiation rests on throughput performance and metrology-integration depth, with optical platforms facing steeper cost compression as metal oxide resists extend existing tool lifecycles. Foundry buyers exhibit lowest price sensitivity for critical-layer electron beam sampling, while memory manufacturers drive harder negotiations for high-volume optical deployments.
Supply Chain Analysis
ISO 14644 cleanroom certification and SEMI equipment standards gate supplier entry, concentrating component sourcing across Japan, the United States, and Germany for electron beam columns and actinic optics. Raw material dependencies center on specialized optical glass, precision motion stages, and high-purity vacuum systems. Single-source vulnerability for column assemblies creates structural risk, while distribution runs through direct OEM sales teams with embedded field service engineers at major foundry clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced node wafer defect inspection systems market functions as a stable compounder, with EUV lithography node transitions below three nanometers driving persistent replacement demand regardless of semiconductor cycle volatility.
For Market Incumbents: To counter margin pressure from metal oxide resist chemistry extending optical tool lifecycles, KLA Corporation and Applied Materials should deepen in-house production of electron beam columns to reduce dependency on external suppliers, while accelerating metrology-integration roadmap execution to capture collapsing procurement cycles at Taiwan's Hsinchu cluster. For New Entrants and Emerging Players: Compound semiconductor foundries in the United States and Europe represent underserved buyer archetypes with less stringent qualification timelines than leading-edge logic manufacturers. These entrants should prioritize silicon carbide wafer inspection platforms for power electronics applications, leveraging South Korea's K-Semiconductor Belt qualification pathways as a beachhead for process credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among regional equipment integrators with captive domestic demand from China and Japan, where sovereign subsidy programs accelerate local vendor development. Long-term viability hinges on electron beam column technology access; the signal to watch is qualification momentum for non-incumbent column suppliers at Samsung or SK Hynix pilot lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electron Beam Columns | Applied Materials' in-house column production reduces supplier concentration risk for resolution-critical subcomponents. |
| Metrology-Integration Platform Convergence | Unified process control loops at TSMC collapse separate procurement cycles into single-vendor relationships. |
| Actinic Mask Inspection Specialization | Lasertec's wavelength-matched EUV photomask qualification commands premium positioning in near-monopoly segment. |
| Domestic Supply Chain Qualification | Japan's METI subsidies accelerate local vendor timelines for advanced node tools at Kyushu foundry projects. |
| Hybrid Optical-Electron Beam Architecture | Next-generation platforms blend throughput and precision as modality boundaries dissolve below three nanometers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fab equipment procurement managers, process control engineers at leading foundries, and electron beam column specialists with secondary validation against SEMI equipment market data, SEC filings from listed equipment vendors, and national subsidy program disclosures from Japan's METI and South Korea's trade ministry. Bottom-up wafer demand modeling and top-down capital expenditure triangulation anchored market sizing.
Segment-weighting across technology modality, product type, and end-user category shaped the analytical framework over the projection horizon, with electron beam and optical inspection splits derived from foundry sampling rate requirements at each node transition. Modeled dimensions included inspection throughput tier, metrology-integration depth, and regional fab concentration, with CAGRs derived from equipment replacement cycles tied to EUV lithography ramp schedules and sovereign subsidy program disbursement timelines.
Underlying measurement precision varies by segment; electron beam inspection carries tighter precision than optical platforms due to concentrated vendor base visibility. Forecasts reflect assumptions regarding EUV node transition pacing and subsidy program continuity, with model refresh warranted upon material change in export control licensing thresholds or metal oxide resist adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.