
 MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market | 2026-2036
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market Foresight
Clean-label specification upgrades across surfactant and preservative tiers is unwinding traditional procurement patterns in the MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market. BASF SE leverages its global R&D network to supply high-purity emulsifiers for halal-compliant skin care lines. Evonik Industries AG anchors specialty silicone alternatives production for the Gulf's humidity-adapted hair care segment. SABIC competes through backward integration into petrochemical feedstocks that feed regional surfactant manufacturing.
Cosmetics and personal care ingredients encompass functional raw materials—emulsifiers, preservatives, surfactants, and thickeners—formulated at specified active concentrations, HLB balances, and pH compatibilities to deliver stability, efficacy, and sensory performance in finished consumer products. These ingredients undergo cold-process or hot-process compounding, often requiring multi-phase homogenization to achieve droplet size distributions below 5 microns for premium skin care applications. Surfactants command the largest volume share given their ubiquity across cleansing formulations, while natural and organic ingredient sources capture expanding margin pools as Gulf consumers prioritize clean beauty claims. The professional user category sustains higher per-unit ingredient specifications than mass retail channels, driving differentiated pricing for salon-grade active complexes.
Saudi Arabia's SFDA, China's NMPA, and the UAE's MOHAP each enforce distinct cosmetic ingredient notification and safety assessment protocols that fragment compliance requirements across the MENA-G.C.C.-China corridor. REACH-aligned substance restrictions in Gulf Cooperation Council draft technical regulations are converging with China's updated cosmetic supervision regulation, elevating documentation burdens for cross-border suppliers. Stakeholders must monitor regulatory harmonization negotiations between Gulf standardization bodies and Chinese authorities to anticipate unified ingredient positive-list frameworks that would reshape market access requirements.
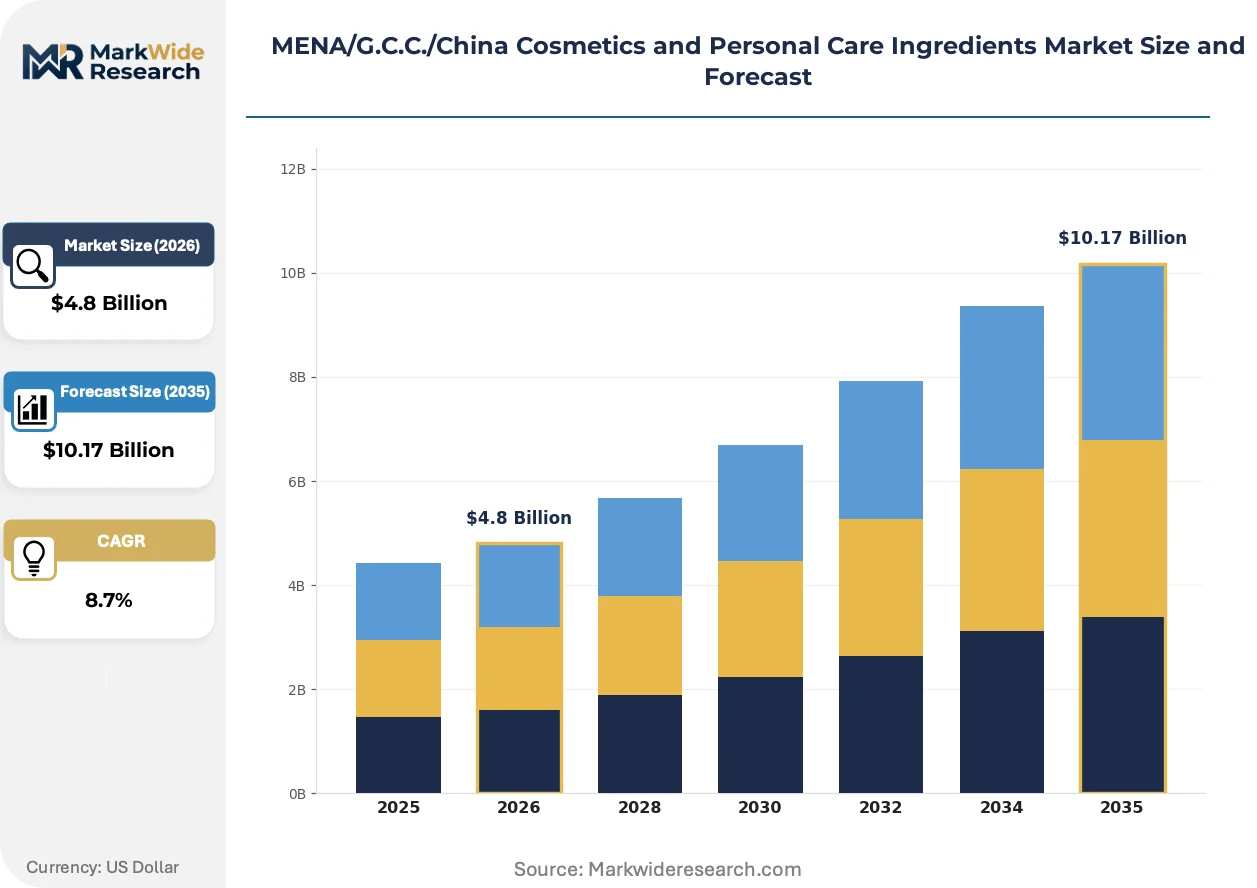
Market Dynamics
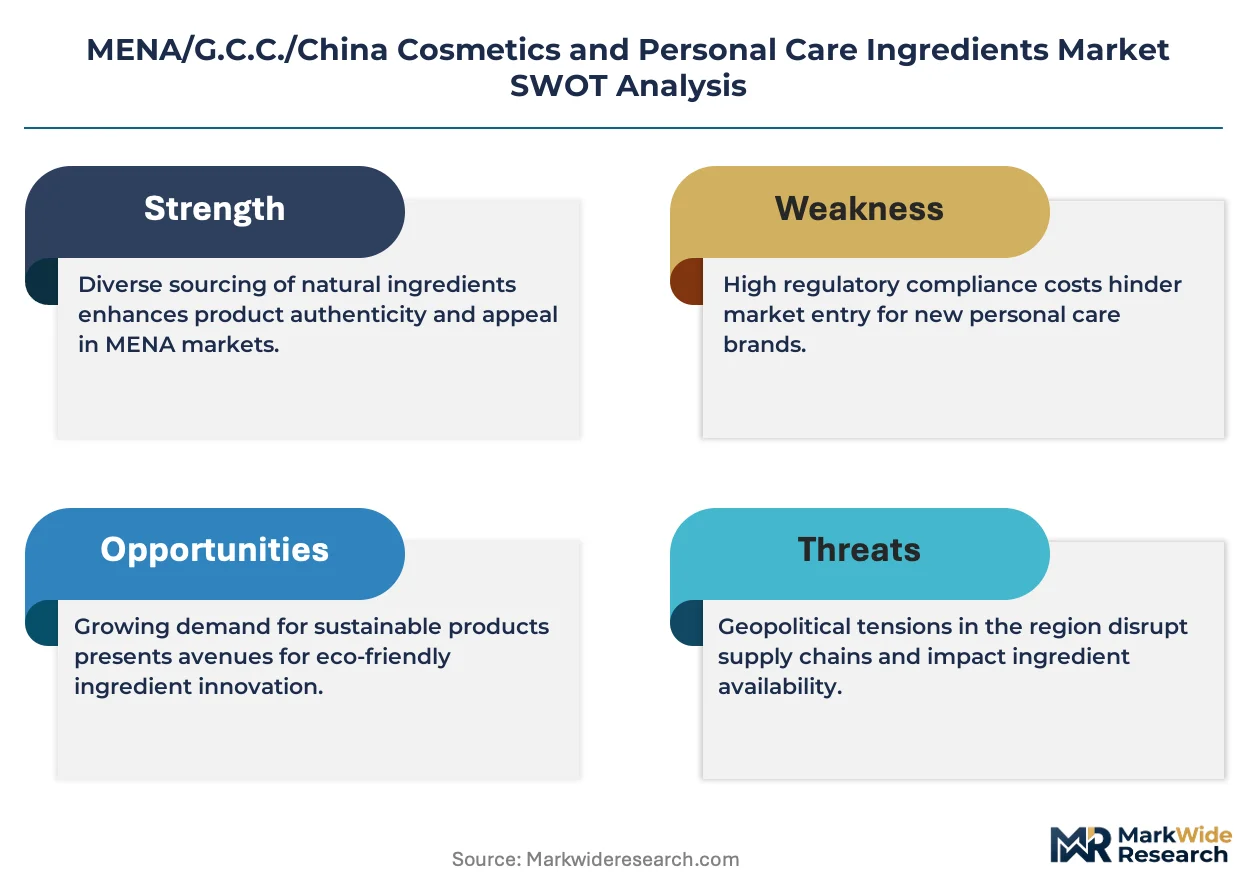
Clean-label specification upgrades across surfactant and preservative tiers are unwinding traditional procurement patterns in the MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market. China's NMPA tightened cosmetic ingredient registration rules, pushing multinationals toward pre-approved raw material libraries.
Growth Catalysts
- Halal certification mandates:Saudi Arabia's SFDA and the UAE's MOHAP enforce strict halal compliance for cosmetics, creating dedicated demand for alcohol-free emulsifiers and animal-derived-free actives.
- Petrochemical feedstock integration:SABIC's backward integration into regional surfactant manufacturing secures cost-competitive supply chains for Gulf-based formulators.
- Domestic manufacturing clusters:Riyadh-Jeddah corridor facilities now supply regional formulators, reducing import dependency and shortening lead times for specialty ingredients.
Market Restraints
- Regulatory fragmentation:Divergent notification protocols between Saudi Arabia's SFDA, China's NMPA, and the UAE's MOHAP elevate compliance costs and documentation burdens for cross-border suppliers.
- Petrochemical price volatility:Crude oil fluctuations directly impact surfactant and silicone derivative input costs, compressing margins for non-integrated manufacturers.
- Natural ingredient supply constraints:Limited cultivation of botanical actives within the Gulf region forces reliance on Asian and European botanical extract imports.
Strategic Opportunities
- Humidity-adapted formulations:The Gulf's extreme climate creates white space for silicone alternatives and anti-humectant systems in hair care applications.
- Professional salon channel expansion:Higher per-unit ingredient specifications in salon-grade products enable premium pricing for active complexes targeting Gulf beauty professionals.
- Regulatory harmonization negotiations:Convergence between Gulf standardization bodies and Chinese authorities on REACH-aligned substance restrictions may yield unified positive-list frameworks.
Industry Challenges
- Multi-jurisdictional compliance timelines:Navigating simultaneous SFDA, NMPA, and MOHAP safety assessment protocols stretches product launch schedules and strains regulatory affairs capacity.
- Cold-process formulation expertise gaps:Achieving sub-5-micron droplet size distributions for premium skin care requires specialized homogenization knowledge that remains scarce in regional manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Preservatives, Surfactants, Thickeners Application: Skin Care, Hair Care, Makeup, Fragrance Ingredient Source: Natural, Synthetic, Organic, Biodegradable User Category: Professional, Retail, Mass, Boutique |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, SABIC, Reza Chemical Industries, Ittihad International Chemicals Trading LLC, Dongming Jujin Chemical Co., Ltd., Artec Chemical Company Limited, Chemanol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market Shifts & Advancements
Active ingredient delivery systems are compressing formulation complexity while elevating efficacy thresholds across the MENA/G.C.C./China corridor. Three convergent developments are restructuring competitive positioning.
Encapsulation technology employing lipid nanoparticles and cyclodextrin complexes is miniaturizing active delivery architectures for retinoids and peptides. Premium skin care brands across the Gulf are adopting these systems to stabilize sensitive actives against heat degradation. This compression of formulation stability requirements is displacing conventional emulsion-based delivery in halal-certified product lines.
China's NMPA updated cosmetic supervision regulation now mandates extended safety documentation for novel ingredients, effectively creating a two-tier market of pre-approved legacy actives versus high-barrier new chemical entities. Multinationals are consolidating around established raw material libraries rather than pursuing novel ingredient registrations. Professional salon channels face the steepest reformulation burdens as they rely disproportionately on innovative active complexes.
Clean beauty certification is displacing conventional marketing claims as the primary purchase determinant among Gulf consumers. Mass retail channels are responding by demanding third-party verified natural and organic ingredient sourcing documentation from suppliers. This behavioral shift concentrates margin capture with formulators able to demonstrate supply chain transparency from Saudi Arabia's domestic manufacturing clusters through to finished goods.
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market Segmentation
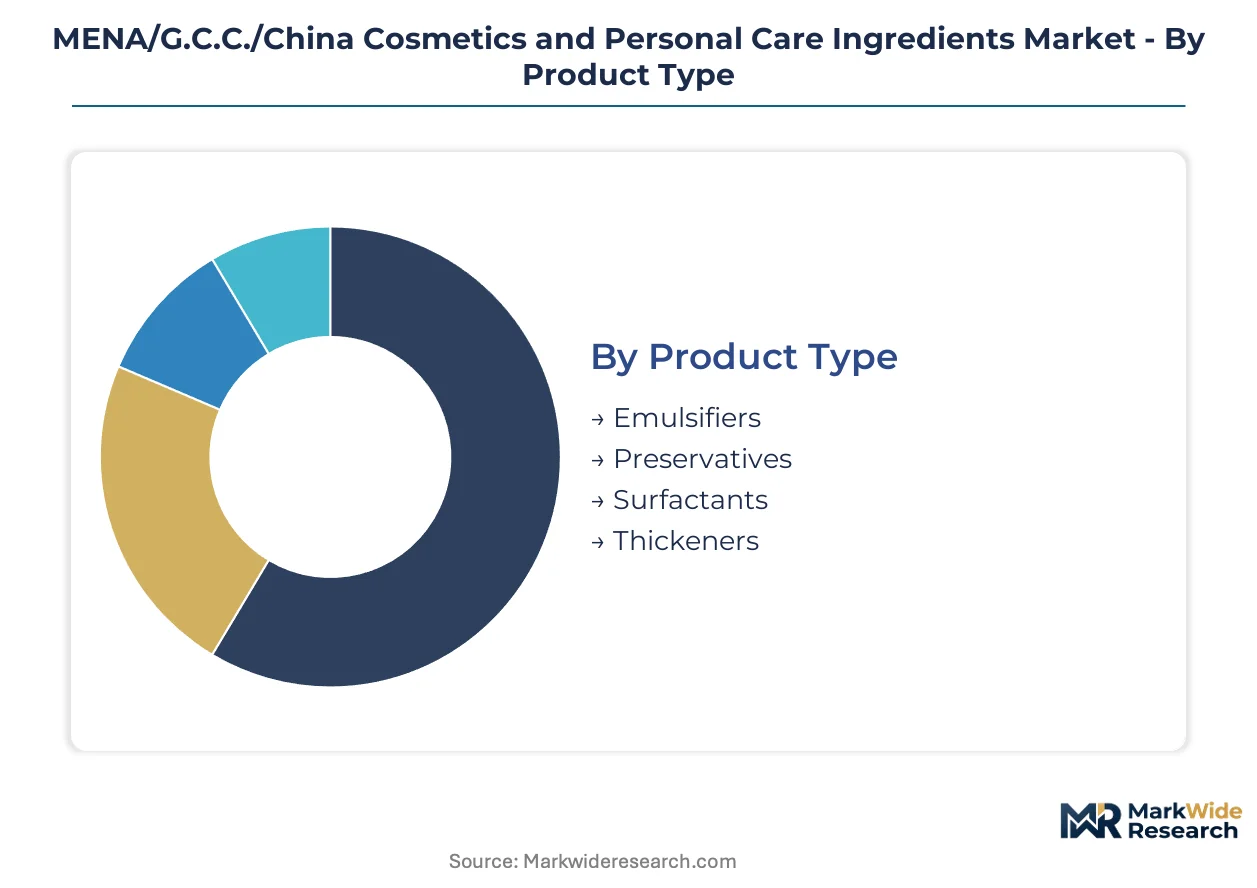
Ingredient specification tiers diverge sharply across the MENA-G.C.C.-China corridor, with domestic manufacturing clusters in Saudi Arabia's Riyadh-Jeddah corridor anchoring supply for regional formulators while export-oriented segments feed China's NMPA-registered channels. Procurement patterns fragment further between halal-certified professional lines and mass retail formulations.
Product Type:
Domestic production concentrates in surfactant and thickener categories where SABIC's petrochemical feedstock integration delivers cost-competitive supply, while emulsifier and preservative tiers remain import-dependent for high-purity specifications.
- Surfactants:Anionic, cationic, and non-ionic surface-active agents formulated at specified critical micelle concentrations for cleansing applications. Volume demand concentrates in Saudi Arabia's domestic manufacturing corridors where local formulators supply regional shampoo and body wash producers. SABIC's backward integration into regional feedstocks secures margin-competitive supply chains against Asian import alternatives.
- Emulsifiers:Lipophilic and hydrophilic balance-tuned agents enabling stable oil-water dispersions in skin care formulations. China's NMPA tightened registration rules push multinationals toward pre-approved emulsifier libraries, compressing novel ingredient adoption timelines. Halal-certified alcohol-free variants command premium positioning across Gulf professional channels.
- Preservatives:Antimicrobial and antioxidant systems maintaining formulation stability throughout product shelf life. Paraben alternatives and clean-label phenoxyethanol complexes gain specification share as Gulf consumers prioritize preservative-free marketing claims.
- Thickeners:Rheology modifiers including cellulose derivatives, carbomers, and natural gums adjusting product viscosity and sensory profile. Xanthan gum and hydroxyethylcellulose dominate regional sourcing from Asian suppliers.
Surfactants command the established base. The steepest expansion runs through emulsifiers.
Application:
Cost tier differentiation separates professional salon-grade specifications from mass retail formulations, with per-unit ingredient premiums reaching multiples in hair care and skin care active complexes.
- Skin Care:Functional actives, emollients, and delivery systems formulated for facial and body treatment applications. Humidity-adapted silicone alternatives from Evonik anchor the Gulf's premium positioning against heat degradation. China's NMPA registration burdens concentrate reformulation pressure on anti-aging peptide and retinoid complexes.
- Hair Care:Conditioning agents, silicones, and anti-humectant systems addressing the Gulf's extreme climate challenges. Salon-grade specifications sustain higher per-unit ingredient costs than mass retail channels.
- Makeup:Pigment dispersions, film formers, and texture modifiers enabling color cosmetic performance. Halal certification mandates from Saudi Arabia's SFDA and UAE's MOHAP restrict alcohol-based solvents and animal-derived colorants.
- Fragrance:Aromatic compounds, fixatives, and carrier systems delivering olfactory performance. Alcohol-free formulations dominate Gulf compliance requirements.
Skin Care anchors volume concentration. Hair Care is climbing the fastest.
Ingredient Source:
Supply concentration for natural and organic botanicals forces Gulf formulators toward Asian and European import dependency, while synthetic and biodegradable categories leverage regional petrochemical infrastructure.
- Natural:Botanical extracts, plant-derived oils, and mineral actives sourced from cultivated or wild-harvested raw materials. Limited Gulf cultivation capacity concentrates supply chain control with Asian extract suppliers.
- Synthetic:Petrochemical-derived functional ingredients including silicones, synthetic polymers, and processed surfactants. SABIC's regional feedstock integration secures captive supply advantages.
- Organic:Certified chemical-free cultivation meeting third-party organic standards. Third-party verification documentation demands concentrate margin capture with transparent supply chain operators.
- Biodegradable:Environmentally degradable surfactant and polymer systems aligning with clean beauty certification trends. Green chemistry process requirements elevate manufacturing complexity.
Synthetic ingredients retain volume leadership. Natural sourcing is gaining share fastest.
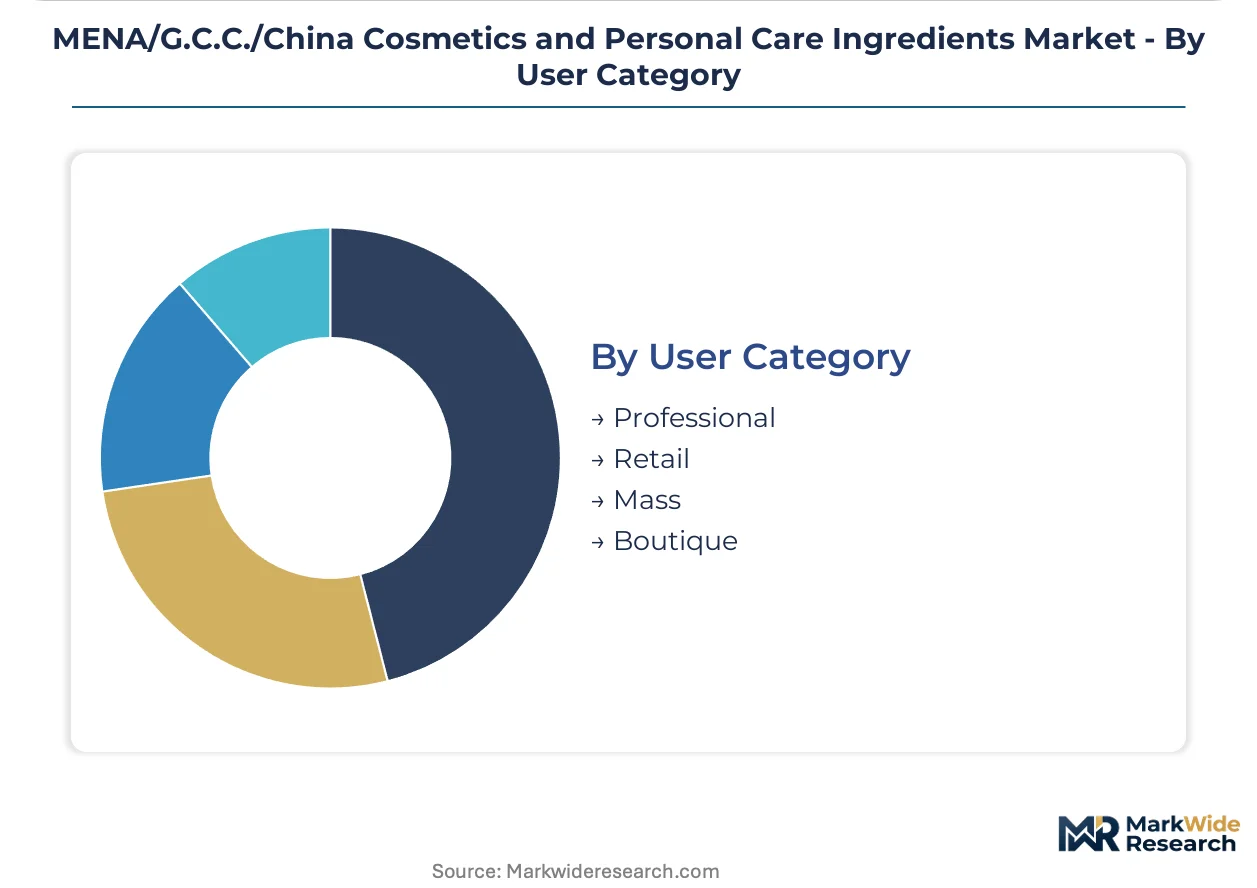
User Category:
Customer type fragmentation creates specification divergence between professional salon channels demanding sub-5-micron droplet homogenization and mass retail accepting broader performance tolerances.
- Professional:Salon-grade and clinic-dispensed formulations requiring elevated active concentrations and specialized delivery technologies. Cold-process formulation expertise gaps in regional manufacturing clusters constrain local supply.
- Retail:Department store and specialty channel products balancing performance claims with cost-optimized ingredient loading. Clean beauty certification documentation requirements intensify supplier qualification.
- Mass:Volume-scale consumer products prioritizing cost-competitive surfactant and preservative systems. Domestic manufacturing clusters in Saudi Arabia's Riyadh-Jeddah corridor shorten lead times for regional formulators.
- Boutique:Small-batch and artisanal formulations emphasizing novel ingredient stories and limited production runs. NMPA registration barriers in China limit boutique brand market access.
Mass channels dominate volume throughput. Professional specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feedstock-integrated manufacturing clusters anchor supply-side positioning across the MENA-G.C.C.-China corridor. Saudi Arabia's petrochemical infrastructure and China's NMPA-registered ingredient channels concentrate procurement gravity. Regulatory divergence between Gulf standardization bodies and Chinese authorities fragments compliance pathways.
Saudi Arabia
Halal-certified emulsifier specifications from Riyadh-Jeddah corridor facilities drive domestic manufacturing expansion. SFDA mandates on alcohol-free formulations restrict import sourcing flexibility. The King Abdullah Petroleum Studies and Research Center cluster near Riyadh anchors SABIC's backward-integrated surfactant production for regional formulators.
China
NMPA-registered active ingredient libraries concentrate procurement decisions among pre-approved raw material suppliers. The updated cosmetic supervision regulation compresses novel ingredient registration timelines for multinationals. Yangtze River Delta chemical parks near Shanghai host concentrated emulsifier and preservative manufacturing for domestic skin care brands.
United Arab Emirates
MOHAP halal compliance protocols for Dubai's professional salon channel elevate documentation requirements for European preservative imports. Jebel Ali free zone logistics infrastructure shortens lead times for specialty silicone alternatives. Dubai Science Park clusters formulation R&D facilities serving Gulf humidity-adapted hair care applications.
South Korea
MFDS-aligned cosmetic ingredient safety assessments enable Korean active complex suppliers to bridge NMPA and Gulf regulatory requirements. Seoul Capital Area biotech clusters specialize in peptide encapsulation technologies for premium anti-aging applications. Incheon port infrastructure supports bulk surfactant re-export to Saudi manufacturing corridors.
Germany
REACH-compliant preservative alternatives from BASF's Ludwigshafen complex supply Gulf clean-label formulation upgrades. ECHA substance restriction harmonization efforts with Gulf standardization bodies reduce documentation duplication for cross-border suppliers. The Rhine-Neckar metropolitan region anchors high-purity emulsifier production for halal-certified professional channels.
MENA/G.C.C./China Cosmetics and Personal Care Ingredients Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the MENA-G.C.C.-China corridor. German and Korean specialists anchor premium-tier encapsulation and delivery system innovation, while Saudi petrochemical-integrated producers capture surfactant volume economics. Three archetypes dominate: feedstock-integrated regional champions, multinational specialty chemical licensors, and Asian contract manufacturers serving NMPA-registered channels. Consolidation pressures favor backward integration moves and pre-approved raw material library expansion over novel ingredient R&D.
Within the feedstock-integrated tier, SABIC exemplifies regional champion positioning through captive petrochemical supply. BASF SE and Evonik Industries AG occupy multinational specialty archetype roles, with the former representing German high-purity emulsifier leadership and the latter anchoring silicone alternative technology for Gulf climate applications. Dongming Jujin Chemical Co., Ltd. sits within the Asian contract manufacturing vector serving China's NMPA-registered ingredient procurement.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| SABIC |
| Reza Chemical Industries |
| Ittihad International Chemicals Trading LLC |
| Dongming Jujin Chemical Co., Ltd. |
| Artec Chemical Company Limited |
| Chemanol |
| Others |
Supply & Pricing Matrix
SABIC's petrochemical scale economies in Saudi Arabia establish regional price floors for surfactant feedstocks while compressing margins for non-integrated Asian competitors. China's NMPA registration burdens concentrate procurement power among pre-approved raw material libraries, amplifying supplier pricing leverage over formulators lacking backward integration.
Pricing Analysis
NMPA ingredient registration rules dictate the pricing tier structure across the MENA-G.C.C.-China corridor, separating pre-approved legacy actives from high-barrier novel chemical entities. Three-tier pricing structure across premium halal-certified, standard NMPA-registered, and economy domestic-synthetic levels reflects certification grade and volume scale differentials. Cost compression in standard-tier emulsifiers is intensifying because Gulf formulators are consolidating procurement around Saudi manufacturing clusters. Mass retail channels exhibit highest price sensitivity, while professional salon specifications sustain premium tolerance for sub-5-micron delivery systems.
Supply Chain Analysis
Saudi Arabia and China anchor regional surfactant and emulsifier production respectively, with Germany supplying REACH-compliant preservative alternatives. Feedstock dependencies draw from crude oil derivatives, botanical extracts from Asian suppliers, and specialized silicone precursors. Single-source vulnerability concentrates in NMPA-registered active ingredient libraries where multinationals face reformulation bottlenecks. Distribution runs through Jebel Ali free zone logistics hubs and Yangtze River Delta chemical parks to regional formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward feedstock-integrated domestic manufacturers as Saudi formulators consolidate procurement around Riyadh-Jeddah corridor facilities, fragmenting import-dependent supplier margins.
For Market Incumbents: Consolidate backward integration into petrochemical feedstocks to defend against SABIC's captive supply advantages, while expanding pre-approved raw material libraries to offset NMPA registration compression on novel ingredient timelines. Prioritize halal certification investment as SFDA and MOHAP mandates harden compliance barriers for non-certified imports. For New Entrants and Emerging Players: Anchor in humidity-adapted silicone alternatives for Gulf hair care applications, where Evonik's technology leadership leaves white space for regional specialists. Target professional salon channels with cold-process formulation expertise, leveraging the scarcity of sub-5-micron homogenization capability in Saudi manufacturing clusters. Pursue direct technical service partnerships with Dubai Science Park R&D facilities to bypass established distributor networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among feedstock-integrated regional champions with captive surfactant supply and long-term offtake agreements with Gulf formulators. Over the medium-term horizon, acquisition focus should center on Saudi manufacturing cluster operators with SFDA pre-qualification and backward integration depth. Monitor NMPA-Gulf regulatory harmonization negotiations as the critical inflection signal for cross-border margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | SABIC's captive supply model secures margin-competitive surfactant production against Asian imports. |
| Halal Certification Program Expansion | SFDA and MOHAP compliance investments unlock professional channel pricing premiums in Gulf markets. |
| Pre-approved Raw Material Library Buildout | NMPA-registered ingredient portfolios compress novel registration timelines for multinational formulators. |
| Cold-Process Formulation Capability Investment | Sub-5-micron homogenization expertise addresses scarcity gaps in Saudi manufacturing clusters. |
| Regulatory Harmonization Partnership | Gulf-Chinese authority convergence on REACH-aligned standards would reshape cross-border compliance costs. |
Research Methodology
The analysis maps surfactant, emulsifier, preservative, and thickener sub-sectors, each validated through procurement leads at Gulf formulators, regulatory affairs directors navigating SFDA-NMPA-MOHAP protocols, and technical R&D heads at specialty chemical suppliers. Primary interview intelligence triangulates against customs and trade data, chemical industry association reports, SEC 10-K filings, and national regulator substance restriction disclosures. Bottom-up segment sizing and top-down market reconciliation ensure cross-validation consistency.
Forecast outputs were validated against external capacity utilization benchmarks and feedstock price trajectory assumptions across the projection horizon. Segmentation dimensions modeled include ingredient functional class, halal certification status, application end-use, professional versus mass retail channel, and domestic manufacturing versus import sourcing. CAGRs derive from demand elasticity analysis tied to Gulf consumer clean beauty preference shifts and Chinese cosmetic brand domestic market expansion. Industry-specific inputs incorporate petrochemical feedstock cost curves and NMPA registration queue dynamics.
Material uncertainties — regulatory harmonization delays, crude oil volatility impacts on surfactant economics, and botanical supply disruptions from Asian extract sources — sit outside the modeled envelope. Forecasts reflect assumptions about sustained Gulf manufacturing cluster investment and stable NMPA enforcement intensity. Recalibration cycles align with material shifts in SFDA halal mandate scope and Chinese cosmetic supervision regulation implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Functional Cosmetic Ingredients Market
Cosmetic Chemicals
Jojoba Oil Derivatives Market
Cosmetic Chemicals
Lip Powder Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
Cosmetics Contract Manufacturing Market
Cosmetic Chemicals
Xerosis Market
Cosmetic Chemicals
Australia Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
Germany Dead Sea Mud Cosmetics Market
Cosmetic Chemicals
European Fragrances Microencapsulation Market
Cosmetic Chemicals
Arbutin for Cosmetics Market
Cosmetic Chemicals
Canada Eyeshadow Stick and Blush Stick Market
Cosmetic Chemicals
Chemicals for Cosmetics and Toiletries Market
Cosmetic Chemicals
Personal Care Chemicals Market