
 Minoxidil Market | 2026-2036
Minoxidil Market Size, Share, and Industry Trends Forecast 2026-2036
Minoxidil Market Analysis
Asset-light licensing arrangements for generic manufacturing is rewriting competitive entry barriers across the minoxidil supply chain. Dr. Reddy's Laboratories leverages its integrated active pharmaceutical ingredient capabilities to control cost structures from synthesis to finished dose. Sun Pharmaceutical Industries Ltd anchors its position through dense pharmacy distribution across emerging markets. Johnson & Johnson sustains brand equity in the premium foam segment through sustained clinical marketing investment.
Minoxidil is a piperidinopyrimidine derivative vasodilator, typically formulated at 2% to 5% concentrations in propylene glycol or alcohol-based vehicles for topical absorption, functioning primarily as a potassium channel opener that prolongs the anagen phase of hair follicle cycling. The topical solution category dominates unit volumes due to decades of physician familiarity and lower per-treatment cost, while the foam segment captures disproportionate margin pools through reduced irritation profiles and premium positioning. Distribution through online retail channels is expanding fastest as telehealth prescriptions and direct-to-consumer platforms bypass traditional pharmacy gatekeepers.
The FDA regulates minoxidil as an over-the-counter monograph ingredient in the United States, capping concentrations and mandating specific labeling around cardiovascular warnings, while India's CDSCO oversees manufacturing standards for export-oriented generic production. The EMA's MDR framework in Europe imposes stricter post-market surveillance on combination devices incorporating topical applicators. Stakeholders must monitor how regulatory divergence on concentration limits and digital prescription pathways reshapes competitive access across priority markets.
Market Dynamics
Generic pharmaceutical licensing is compressing manufacturing margins while dermatology clinics expand direct dispensing protocols, creating a bifurcated supply structure between institutional and retail channels.
Growth Catalysts
- Telehealth prescription pathways:Digital health platforms in the United States bypass traditional pharmacy gatekeepers, accelerating patient access to topical therapies through direct-to-consumer fulfillment models.
- CDSCO export manufacturing standards:India's streamlined regulatory framework for active pharmaceutical ingredient production enables domestic manufacturers to scale generic output for international markets.
- Foam formulation technology:Reduced propylene glycol content in next-generation vehicles addresses dermatological irritation concerns, expanding addressable patient populations with sensitive scalp conditions.
Market Restraints
- FDA concentration ceiling uncertainty:Pending over-the-counter monograph revisions create formulation planning paralysis for manufacturers considering 5% plus product development.
- Active pharmaceutical ingredient supply concentration:Synthesis capabilities for minoxidil base material cluster among Indian and Chinese chemical manufacturers, exposing finished dose producers to single-source risk.
- Topical absorption rate limitations:Transepidermal penetration barriers cap clinical efficacy regardless of concentration increases, constraining therapeutic outcome differentiation.
Strategic Opportunities
- Combination device regulatory pathways:EMA's MDR framework for topical applicators with integrated dosing mechanisms creates premium positioning opportunities in European markets.
- Preventive application segments:Younger demographic cohorts in South Korea and Japan are adopting minoxidil prior to visible hair loss, expanding the addressable window for intervention.
- Veterinary dermatology crossover:Canine alopecia treatment protocols are adapting human topical vasodilator formulations, opening companion animal pharmaceutical channels.
Industry Challenges
- Formulation stability expertise:Alcohol-based vehicle degradation kinetics require specialized analytical chemistry capabilities that contract manufacturers struggle to staff.
- Multi-jurisdiction labeling compliance:Divergent cardiovascular warning requirements across FDA, EMA, and Health Canada/PMRA regimes force SKU fragmentation and inventory complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minoxidil Market |
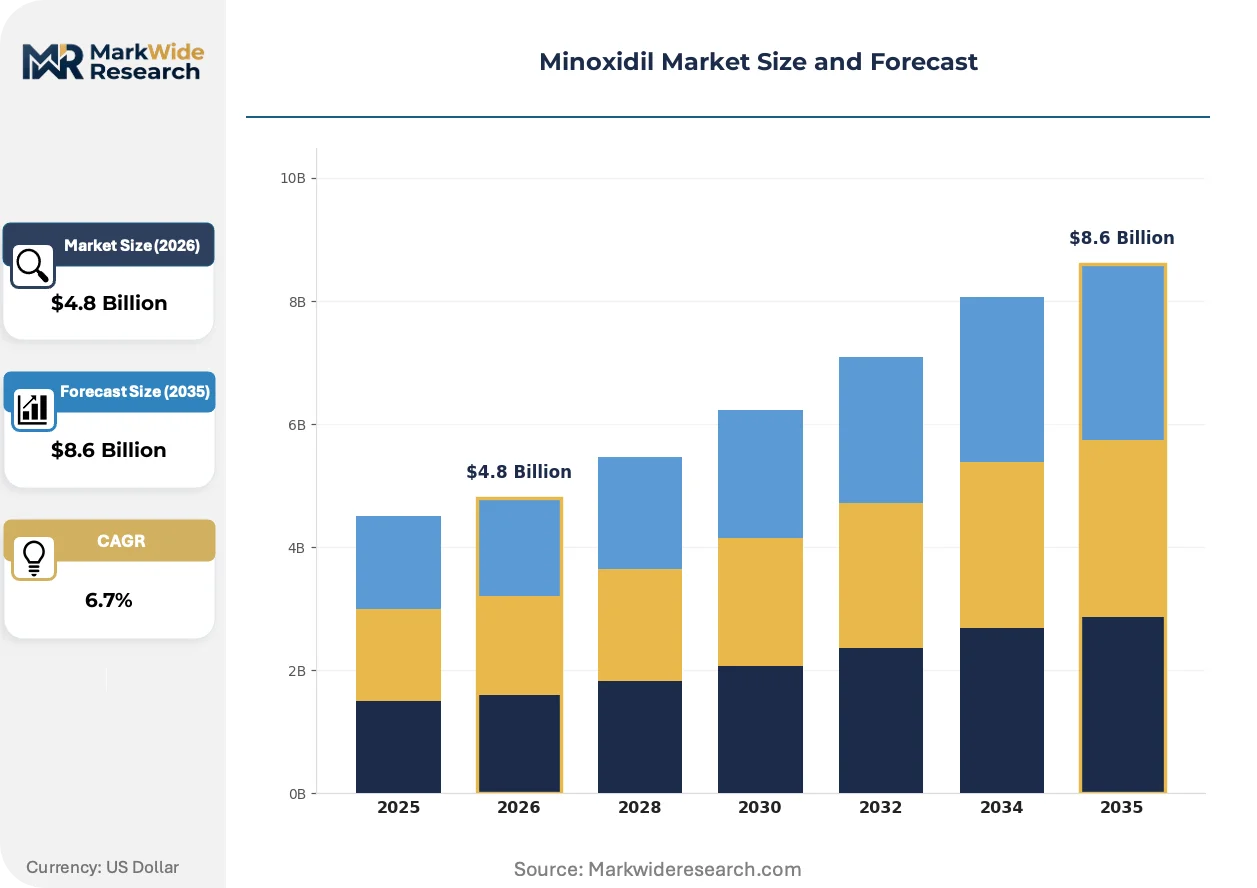
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Solution, Foam, Spray, Tablets Distribution Channel: Online Retail, Pharmacies, Supermarkets, Clinics End User: Men, Women, Dermatologists, General Practitioners Application: Alopecia Areata, Androgenetic Alopecia, Hair Growth, Scalp Treatment |
| Companies Covered | Dr. Reddy's Laboratories, Sun Pharmaceutical Industries Ltd, Johnson & Johnson, Mylan N.V., Himalaya Drug Company, Pfizer Inc, Bausch Health Companies Inc, Sandoz International GmbH, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minoxidil Market Emerging Trajectories
Formulation science and distribution architecture are the primary axes of competitive differentiation, with vehicle chemistry and channel access determining margin capture more than active ingredient sourcing.
Microencapsulation delivery systems are rendering obsolete conventional propylene glycol vehicles by enabling sustained-release kinetics that improve follicular retention time. Specialty compounding pharmacies in Germany and Switzerland are piloting these lipid-shell formulations for resistant patient cases. The technology is rendering obsolete the historical trade-off between efficacy and tolerability that has constrained 5% solution adoption.
EMA's Medical Device Regulation implementation is reclassifying combination products incorporating precision dosing applicators as Class IIa devices, triggering enhanced post-market surveillance obligations. Manufacturers with existing pharmaceutical-only compliance infrastructure face capital outlays for quality management system upgrades. Foam-based presentations with integrated metered pumps in France and Italy are experiencing the steepest regulatory adaptation costs.
Subscription-based replenishment models are capturing patient lifetime value through automated delivery schedules tied to treatment protocol adherence. Direct-to-consumer platforms in the United States and United Kingdom are disintermediating retail pharmacy margins, though clinic-dispensed channels retain higher per-unit economics. Dermatology practices in Brazil and Mexico are responding by launching proprietary private-label lines to recover volume lost to digital competitors.
Minoxidil Market Segmentation
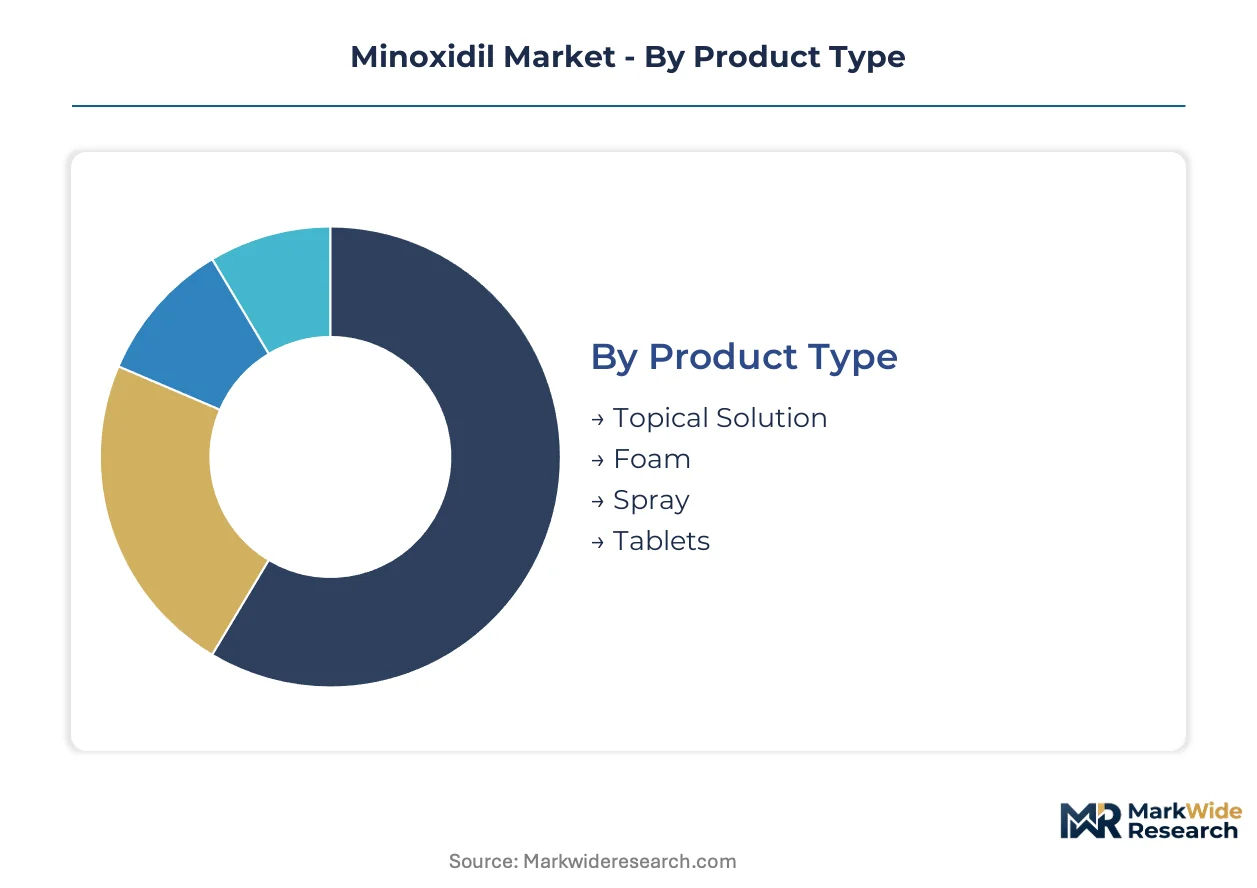
Segmentation in the minoxidil market determines both formulation investment priorities and channel access strategies. Product vehicle chemistry and distribution pathway selection directly influence patient adherence rates and margin capture for manufacturers.
Product Type:
After-sales service intensity varies sharply across vehicle formats, with foam formulations requiring specialized handling guidance and stability monitoring that solution variants do not demand.
- Foam:Propylene glycol-free aqueous vehicles reduce scalp irritation and extend treatment persistence among sensitive patients. Demand concentrates in the United States where Johnson & Johnson's clinical marketing has established premium positioning, though Indian generic manufacturers are narrowing the cost gap through process innovation. The format commands higher per-unit economics despite manufacturing complexity.
- Topical Solution:Alcohol-based 2% and 5% concentrations in propylene glycol vehicles dominate prescription volumes due to decades of physician familiarity and lower per-treatment cost. Indian pharmaceutical exporters and Chinese API suppliers anchor global production, with CDSCO-compliant manufacturing scaling for Latin American and Southeast Asian markets where price sensitivity shapes procurement decisions.
- Spray:Metered-dose aerosol presentations target convenience-oriented patients in South Korea and Japan's preventive application segments, though regulatory complexity around propellant chemistry limits manufacturer entry.
- Tablets:Oral minoxidil for refractory hypertension and off-label hair loss protocols operates through distinct clinical channels with cardiovascular monitoring requirements that topical formats avoid.
Topical Solution holds the largest share; momentum sits with Foam.
Distribution Channel:
Margin capture follows channel architecture, with direct-to-consumer platforms extracting retail pharmacy spreads while clinic dispensing preserves higher per-unit economics through professional consultation bundling.
- Online Retail:Telehealth-integrated platforms in the United States and United Kingdom bypass traditional pharmacy gatekeepers through automated prescription verification and subscription replenishment models. FDA's OTC monograph framework enables direct fulfillment without brick-and-mortar intermediation.
- Pharmacies:Dense retail networks across India, Brazil, and Mexico remain the volume anchor for generic manufacturers, with Sun Pharmaceutical's distribution infrastructure exemplifying channel control strategies.
- Supermarkets:Mass-market placement in North American and European big-box retailers concentrates in 2% concentration SKUs with simplified labeling to minimize regulatory compliance burden.
- Clinics:Dermatology practices in Germany, France, and Italy are expanding direct dispensing protocols for foam formulations, capturing patient lifetime value through treatment protocol adherence programs.
Pharmacies anchor volume throughput; Online Retail climbs the fastest.
End User:
Prescription authority and treatment initiation patterns split the addressable population between self-directed consumers and clinically supervised protocols.
- Men:Androgenetic alopecia prevalence drives the majority of topical solution consumption, with 5% concentration formulations standardizing as first-line intervention across North American and European markets.
- Women:Lower concentration requirements and pregnancy labeling restrictions create distinct formulation SKUs, with foam vehicles gaining preference due to reduced systemic absorption concerns and cosmetic compatibility.
- Dermatologists:Specialist prescribing concentrates in combination therapy protocols and resistant cases, particularly in South Korea's aesthetic medicine clusters and Japan's preventive application segments.
- General Practitioners:Primary care gatekeeping in National Health Service jurisdictions and emerging markets funnels patients toward standardized 2% solution initiations before specialist referral.
Men represent the largest addressable population; Women show the steepest expansion trajectory.
Application:
Therapeutic indication determines concentration selection, treatment duration, and reimbursement pathway access across regulated markets.
- Androgenetic Alopecia:Pattern hair loss in both sexes constitutes the commercial core, with 5% topical solution and foam variants capturing chronic treatment adherence through visible efficacy timelines.
- Hair Growth:Cosmetic positioning for non-pathological thinning expands the addressable window in Asian markets, particularly among younger demographic cohorts in Seoul and Tokyo adopting preventive protocols.
- Alopecia Areata:Autoimmune-mediated patchy hair loss requires combination immunomodulatory approaches where minoxidil serves adjunctive rather than primary therapeutic role.
- Scalp Treatment:Seborrheic dermatitis and post-surgical hair transplant maintenance applications utilize lower concentration formulations with vehicle modifications for tolerability in compromised skin barriers.
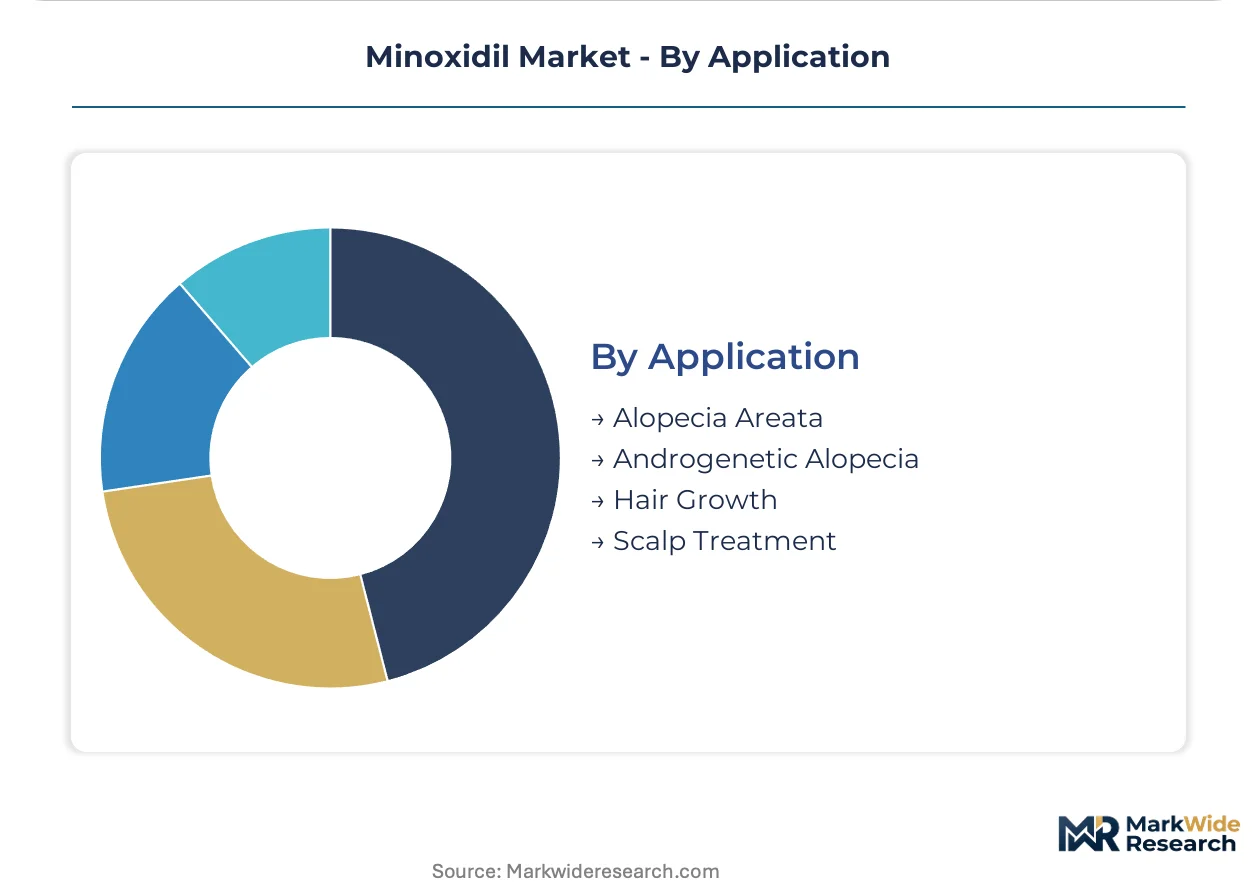
Androgenetic Alopecia dominates commercial value; Hair Growth gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium foam formulations in the United States command unit economics that generic solution exports from India cannot replicate, creating a persistent pricing-power asymmetry across the Atlantic and Indian Ocean basins.
United States
Telehealth-integrated prescription platforms and direct-to-consumer subscription models accelerate patient access while bypassing traditional pharmacy intermediaries. FDA's OTC monograph framework caps concentration limits but enables streamlined market entry for compliant formulations. Clinical marketing investment concentrates in New Jersey and California corridors where dermatology practice networks anchor brand equity.
India
Domestic pharmaceutical manufacturers scale active pharmaceutical ingredient synthesis for export markets across Latin America and Southeast Asia. CDSCO's streamlined manufacturing standards reduce regulatory friction for export-oriented production. Hyderabad and Mumbai clusters house integrated operations controlling cost structures from chemical synthesis through finished dose packaging.
Germany
Specialty compounding pharmacies pilot microencapsulation delivery systems for resistant patient cases requiring sustained-release kinetics. EMA's MDR framework imposes enhanced post-market surveillance on combination devices with precision dosing applicators. Berlin and Munich dermatology practices expand direct dispensing protocols to recover patient volume lost to digital competitors.
South Korea
Younger demographic cohorts adopt preventive minoxidil applications prior to visible hair loss, expanding the addressable intervention window. MFDS regulates cosmetic-positioned hair growth formulations with distinct labeling requirements from therapeutic indications. Seoul's aesthetic medicine clusters drive protocol innovation for combination therapy approaches.
Brazil
Dense retail pharmacy networks anchor generic solution volumes while dermatology clinics launch proprietary private-label lines. ANVISA's regulatory pathway for topical vasodilators shapes import licensing for Indian-manufactured finished doses. São Paulo and Rio de Janeiro distribution hubs coordinate Latin American market access.
Minoxidil Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where formulation chemistry and active pharmaceutical ingredient synthesis determine margin capture. The vendor base stratifies between brand-holding multinationals with clinical marketing infrastructure and generic manufacturers competing on cost-engineered supply chains. Three archetypes dominate: integrated API-to-dose producers, brand-equity defenders, and contract manufacturing specialists. Capacity expansion in Indian chemical synthesis clusters and strategic partnerships for foam vehicle technology represent the dominant competitive moves.
Within the integrated API-to-dose tier, Dr. Reddy's Laboratories and Sun Pharmaceutical Industries Ltd occupy positions exemplifying backward control over cost structures from chemical synthesis through finished packaging. Johnson & Johnson sits within the brand-equity defender archetype, anchoring premium positioning through sustained clinical marketing investment. These three entities represent the competitive spectrum from commodity-scale generic production to differentiated foam formulation marketing.
| Leading Market Players |
|---|
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries Ltd |
| Johnson & Johnson |
| Mylan N.V. |
| Himalaya Drug Company |
| Pfizer Inc |
| Bausch Health Companies Inc |
| Sandoz International GmbH |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Indian active pharmaceutical ingredient synthesis clusters is compressing spot pricing for minoxidil base material while simultaneously eroding manufacturing margins for finished dose producers dependent on external sourcing. This utilization dynamic rewards integrated producers with captive synthesis capabilities and punishes formulation-only competitors exposed to input cost volatility.
Pricing Analysis
The customization-premium spread separates subscription-based foam formulations from commodity topical solutions, with the former capturing recurring revenue through automated replenishment models. Pricing stratifies across premium, standard, and economy tiers defined by vehicle chemistry, propylene glycol content, and after-sales consultation bundling. Cost compression in the solution segment is intensifying because Indian generic exporters are scaling CDSCO-compliant manufacturing for Latin American and Southeast Asian procurement tenders. Price sensitivity concentrates among pharmacy channel buyers in emerging markets, while clinic-dispensed foam commands inelastic demand through professional recommendation authority.
Supply Chain Analysis
Tariff exposure between India and Brazil dominates supply chain risk planning for export-oriented generic manufacturers navigating ANVISA import licensing requirements. Active pharmaceutical ingredient synthesis clusters in Hyderabad and Mumbai feed finished dose production across Latin America and Southeast Asia, with propylene glycol and alcohol-based vehicle chemicals drawing from petrochemical suppliers in the Gulf Coast and Rotterdam hubs. Single-source vulnerability concentrates in Chinese intermediate chemical suppliers for piperidinopyrimidine derivative precursors. Distribution runs through dense pharmacy networks in São Paulo and Mumbai, with direct-to-consumer platforms in the United States and United Kingdom disintermediating traditional wholesale spreads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment services and treatment protocol adherence programs are expanding faster than hardware sales, transforming the minoxidil market into a service-attach opportunity where patient lifetime value exceeds per-unit margin capture.
For Market Incumbents: Harden formulation stability expertise through specialized analytical chemistry capabilities that contract manufacturers struggle to staff, defending against quality failures that trigger FDA warning letters. Anchor channel control through exclusive clinic dispensing partnerships in Germany and France, where EMA's MDR framework creates compliance barriers for digital competitors lacking device quality management systems. For New Entrants and Emerging Players: Pursue preventive application segments among younger demographic cohorts in Seoul and Tokyo, where cosmetic-positioned hair growth protocols remain underpenetrated by established therapeutic marketers. Target veterinary dermatology crossover opportunities in companion animal pharmaceutical channels, leveraging existing topical vasodilator formulation templates with modified vehicle chemistry for canine alopecia protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across foam vehicle technology licensing, enabling asset-light market entry through outsourced manufacturing partnerships rather than captive capacity buildout. Over the projection horizon, acquisition candidates with integrated API-to-dose capabilities and CDSCO export manufacturing certifications offer superior margin resilience. The signal to watch is FDA over-the-counter monograph revision timing, which would trigger formulation repositioning investments and reshape competitive access economics.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Delivery Development | Lipid-shell sustained-release kinetics improve follicular retention time for resistant cases in German compounding pharmacies. |
| EMA MDR Compliance Investment | Class IIa device reclassification for combination applicators triggers quality management system upgrades in France and Italy. |
| Subscription Replenishment Platform Launch | Automated delivery schedules tied to treatment protocols capture patient lifetime value through direct-to-consumer channels. |
| CDSCO Export Manufacturing Scale-Up | Hyderabad and Mumbai clusters control cost structures from chemical synthesis through finished dose packaging for Latin America. |
| Telehealth Prescription Integration | Digital health platforms bypass traditional pharmacy gatekeepers through automated verification in United States markets. |
Methodological Framework
Operator-level perspectives from dermatology practice managers, pharmaceutical regulatory affairs leads, active pharmaceutical ingredient procurement directors, and direct-to-consumer platform executives anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA OTC monograph filings, CDSCO manufacturing standard disclosures, EMA MDR implementation guidance, and customs trade data for minoxidil base material flows. Bottom-up patient population modeling and top-down pharmaceutical market sizing converged across the analysis window.
Scenario-bracketing framed the analytical approach, with segmentation dimensions spanning vehicle chemistry, distribution channel architecture, and regional regulatory clusters. Modeled variables included concentration tier adoption curves, foam versus solution format migration rates, and clinic versus digital channel share shifts. CAGRs derived from treatment persistence assumptions and preventive application segment expansion in Asian markets, cross-referenced against API production capacity utilization signals from Indian chemical synthesis clusters.
Sensitivities concentrate around FDA concentration ceiling revisions, CDSCO export manufacturing standard modifications, and EMA post-market surveillance enforcement intensity for combination devices. Forecasts reflect assumptions around telehealth prescription pathway durability and subscription replenishment model retention rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Chemicals
Fractionated Shea Butter in Cosmetics and Personal Care Market
Cosmetic Chemicals
South America Cosmeceuticals Market
Cosmetic Chemicals
Cosmetic Grade Warming Agents Market
Cosmetic Chemicals
Global Cosmetics OEM/ODM Market
Cosmetic Chemicals
ASEAN Cosmetic Chemicals Market
Cosmetic Chemicals
Cosmetic Ingredients Polymers Market
Cosmetic Chemicals
Premium Tattoo Ink Market
Cosmetic Chemicals
PRP and PRF in Cosmetics Market
Cosmetic Chemicals
UV Nail Gel Polish Market
Cosmetic Chemicals
Cosmetic UV Absorbers Market
Cosmetic Chemicals
Makeup Emulsion Market
Cosmetic Chemicals
Cosmetic Grade CI 77491 Market
Cosmetic Chemicals
Cosmetic Based Preservatives Market
Cosmetic Chemicals
US Minoxidil Market
Cosmetic Chemicals
Global Argireline Market
Cosmetic Chemicals
Xerosis Market