
 Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market | 2026-2036
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market Insights
Specialty chemical distribution is narrowing as consolidated buyers in pharmaceutical and semiconductor sectors demand direct technical service relationships. Ecolab leverages its global institutional footprint to embed formulation scientists at client sites. Henkel anchors European supply through captive production of neutral and alkaline detergents for cleanroom environments. Zep competes aggressively on private-label programs for contract manufacturing organizations seeking certified low-residue documentation.
Low-residue glass and stainless-steel maintenance chemicals comprise formulated surfactant blends, chelating agents, and volatile solvents engineered to leave less than 10 micrograms per square centimeter of detectable residue after evaporation. These formulations serve critical cleaning validation protocols in industries where surface contamination compromises product integrity or optical clarity. Alkaline detergents dominate volume due to their efficacy against organic soils in pharmaceutical bioreactors and food processing tanks. Solvent cleaners represent the fastest-expanding category as semiconductor fabricators adopt non-flammable hydrofluoroether bases for wafer-handling equipment. Neutral cleaners command premium positioning in laboratory settings where pH-sensitive substrates require residue-free finishing without etching.
The U.S. FDA enforces residue limits through Current Good Manufacturing Practice guidelines that mandate documented cleaning validation for pharmaceutical contact surfaces. REACH registration requirements in Europe compel suppliers to disclose full substance compositions, favoring established formulators with toxicology dossiers over import entrants. EPA Safer Choice and OSHA permissible exposure limits further constrain volatile organic compound content in industrial maintenance products. Stakeholders must monitor evolving dual regulatory pressure from pharmaceutical regulators and chemical safety agencies to anticipate which formulation platforms will retain market access.
Market Dynamics
Pharmaceutical manufacturers are consolidating supplier relationships around embedded technical service capabilities, compressing the viable vendor base to formulators capable of co-locating validation scientists at production sites.
Growth Catalysts
- REACH registration dossiers:Full substance disclosure mandates in Europe favor established European formulators with pre-existing toxicology portfolios, creating regulatory moats against import competition.
- Semiconductor wafer-handling equipment:Non-flammable hydrofluoroether solvent bases are displacing legacy flammable chemistries in cleanroom maintenance protocols across fabrication facilities.
- Munich-Stuttgart precision manufacturing corridor:Certified low-residue protocols for stainless-steel equipment maintenance concentrate demand in Southern Germany's medical device and automotive supply clusters.
Market Restraints
- Fluorinated solvent feedstock volatility:Hydrofluoroether precursor supply concentrates among Japanese and Chinese specialty chemical producers, exposing formulators to input cost swings.
- EPA Safer Choice VOC thresholds:Permissible exposure limit compression constrains volatile organic compound content in industrial maintenance formulations, forcing costly reformulation cycles.
- Aqueous alkaline detergent substitution ceiling:Water-based cleaners face performance limits against silicone and fluoropolymer residues in semiconductor applications, preserving solvent dependency.
Strategic Opportunities
- India's CDMO expansion:Contract manufacturing organizations in Hyderabad and Bengaluru seek certified low-residue documentation for FDA-inspected export facilities, opening technical service relationships.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions accelerate demand for low-global-warming-potential hydrofluoroether alternatives in precision cleaning applications.
- Direct technical service embedding:Pharmaceutical buyers are bypassing distributors for on-site formulation scientists who validate cleaning protocols against product-specific residue limits.
Industry Challenges
- Analytical chemist scarcity:Surface validation protocols requiring ion chromatography and TOC analysis face talent gaps in secondary pharmaceutical manufacturing regions.
- Cleaning validation protocol harmonization:Divergent FDA, EMA, and PMDA residue limit methodologies force redundant documentation for multi-regional facilities.
- Legacy equipment compatibility:Older stainless-steel tanks and glass-lined reactors in European pharmaceutical plants resist low-residue formulation transitions due to elastomer seal degradation risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market |
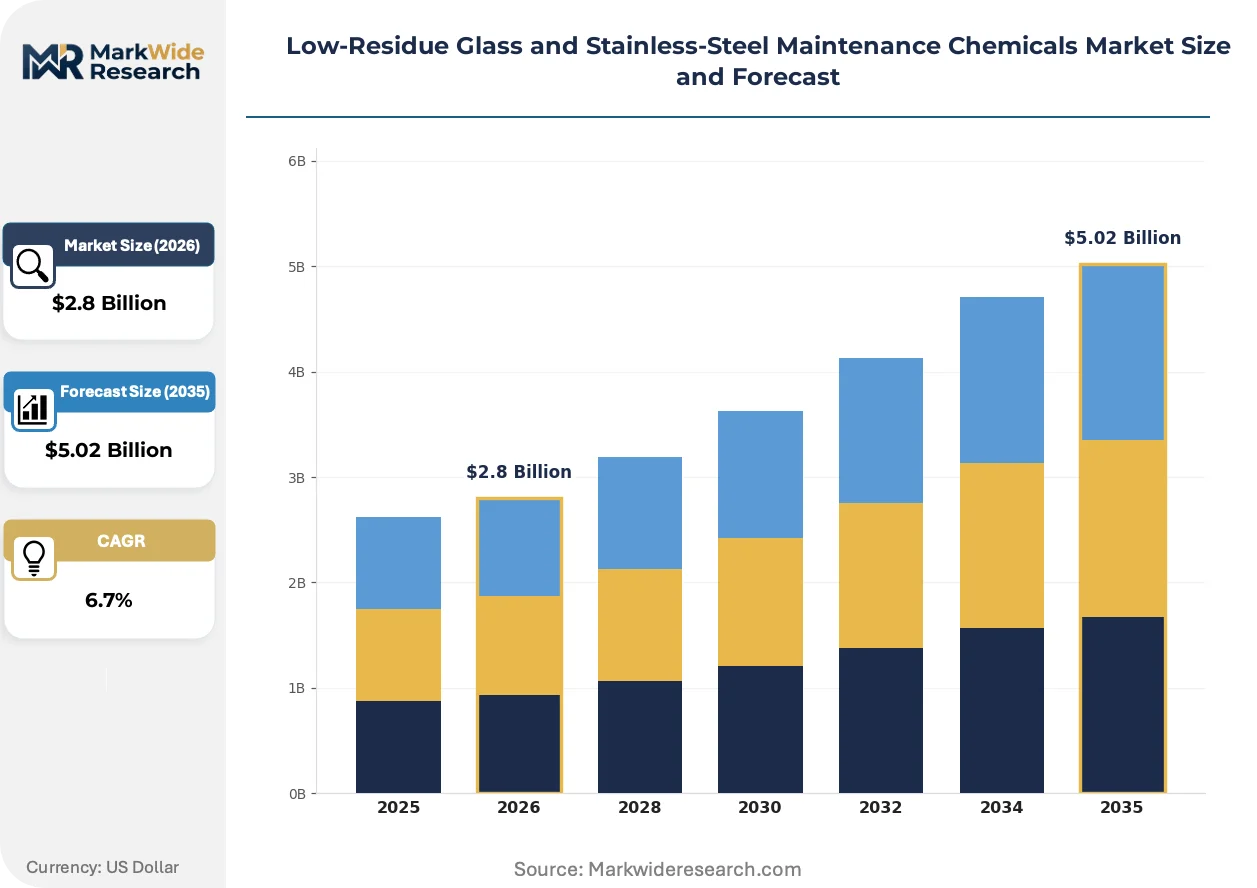
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Detergents, Acid Cleaners, Solvent Cleaners, Neutral Cleaners, Sanitizers Application: Pharmaceutical Production, Food Processing, Electronic Manufacturing, Laboratory Cleaning, Automotive Painting End User: Contract Manufacturing Organizations, Food & Beverage Producers, Semiconductor Fabricators, Research Institutions Packaging Type: Drums, Totes, Bottles, Aerosol Cans, Sachets |
| Companies Covered | Ecolab, 3M, Zep, Reckitt Benckiser Group, Henkel, The Clorox Company, Procter & Gamble, S.C. Johnson & Son, SC Johnson Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market Trends and Innovations
Formulation chemistry is bifurcating between ultra-low-residue solvent systems for semiconductor cleanrooms and aqueous alkaline concentrates for pharmaceutical bioreactor maintenance, with regulatory pressure accelerating both tracks simultaneously.
Hydrofluoroether solvent bases are collapsing the flammable solvent segment in semiconductor wafer-handling equipment maintenance. Taiwan Semiconductor Manufacturing and Samsung Foundry have adopted non-flammable HFE-7100 and HFE-7200 formulations for chamber cleaning, eliminating nitrogen-purged storage requirements. This chemistry is collapsing capital barriers to solvent-based precision cleaning while compressing insurance and facility infrastructure costs for new fabrication entrants.
REACH Article 33 disclosure obligations are forcing full substance transparency across European supply chains. Formulators must now register complete chelating agent and surfactant compositions with ECHA, raising compliance costs that disadvantage smaller import competitors. Pharmaceutical contract manufacturers in Ireland and the Netherlands are responding by qualifying only REACH-registered suppliers for validated cleaning protocols.
Certification-driven procurement is consolidating buyer relationships around documented residue performance. Large pharmaceutical manufacturers in North Carolina and New Jersey now require third-party surface validation reports before qualifying new chemical suppliers. This behavioral shift is most visible in parenteral drug facilities, where FDA inspection history has made documented <10 microgram per square centimeter residue guarantees a non-negotiable gate for vendor inclusion.
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market Segmentation
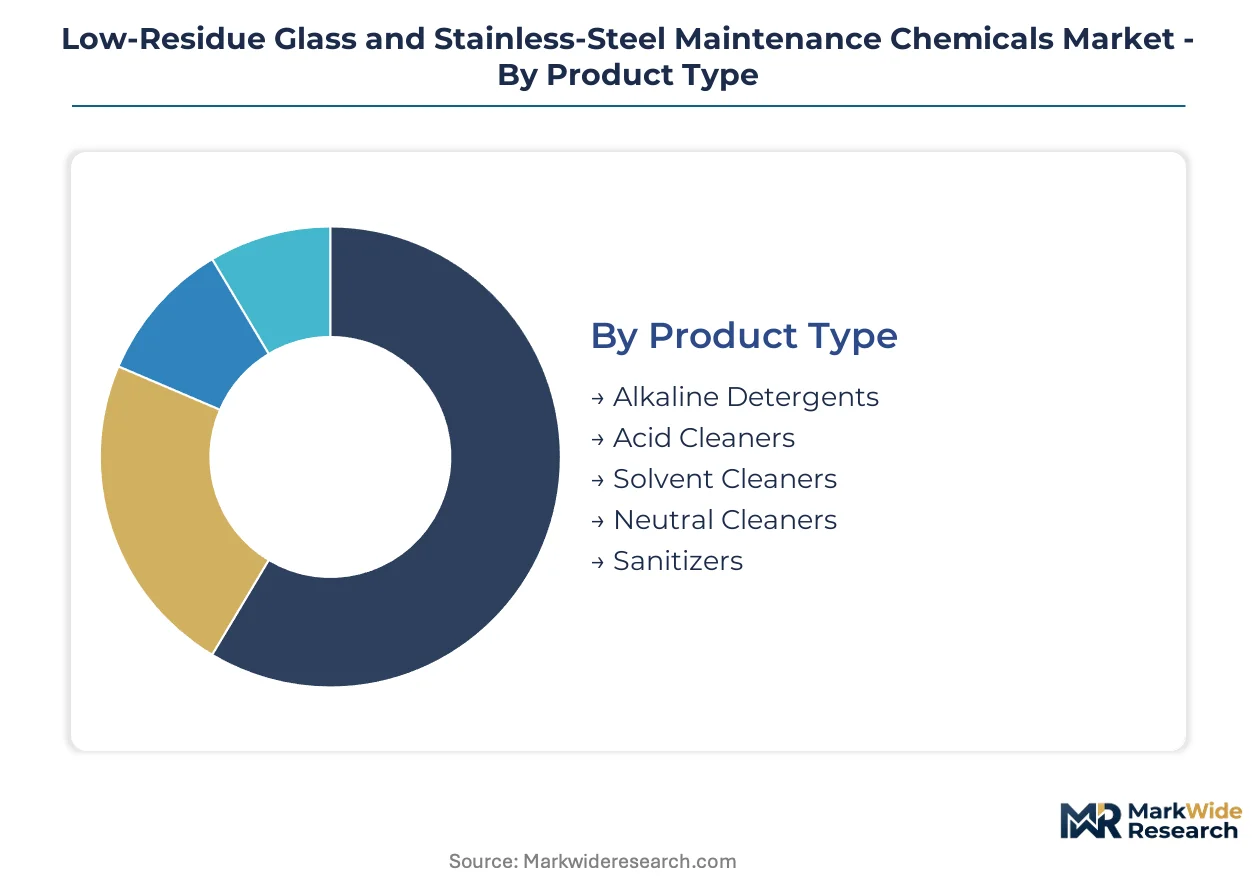
Low-residue maintenance chemicals serve distinct operational rhythms across product categories, with solvent cleaners turning over fastest in semiconductor cleanrooms while alkaline detergents anchor longer replacement cycles in pharmaceutical bioreactors. Understanding these velocity differentials enables suppliers to calibrate inventory, technical service deployment, and pricing structures to the actual consumption patterns of each segment.
Product Type:
Cycle times vary dramatically across chemistries, with solvent cleaners evaporating rapidly in precision applications and alkaline concentrates persisting through extended cleaning campaigns in heavy-soil environments.
- Alkaline Detergents:Formulated surfactant blends with pH 10-13, chelating agents, and builders engineered to hydrolyze organic soils on stainless-steel pharmaceutical equipment. Demand concentrates in North Carolina and New Jersey parenteral drug facilities where FDA inspection history mandates documented residue validation for every cleaning protocol.
- Solvent Cleaners:Hydrofluoroether and modified alcohol bases delivering sub-10 microgram per square centimeter residue profiles through controlled evaporation. Semiconductor fabricators in Taiwan and South Korea are displacing legacy flammable isopropyl alcohol with non-flammable HFE-7100 formulations, collapsing nitrogen-purged storage infrastructure requirements.
- Acid Cleaners:Mineral acid or organic acid formulations targeting inorganic scale and oxide deposits on glass-lined reactors.
- Neutral Cleaners:pH-neutral surfactant systems for laboratory optical components and pH-sensitive substrates.
- Sanitizers:Residue-free biocidal formulations for terminal disinfection of validated surfaces.
Alkaline detergents dominate installed base. Solvent cleaners are where expansion concentrates.
Application:
Cost tier stratification separates high-frequency precision cleaning in semiconductor fabrication from commodity-volume tank cleaning in food processing, with pharmaceutical production commanding premium positioning through validation documentation requirements.
- Pharmaceutical Production:Bioreactor cleaning, tank CIP systems, and equipment surface validation protocols requiring ion chromatography and TOC analytical documentation. Southern Germany's Munich-Stuttgart precision manufacturing corridor concentrates demand for certified low-residue stainless-steel maintenance, with medical device and automotive supply clusters requiring ECHA-registered formulation disclosure.
- Electronic Manufacturing:Wafer-handling equipment, photolithography tools, and cleanroom chamber maintenance demanding sub-part-per-billion contamination control. Taiwan Semiconductor Manufacturing and Samsung Foundry have adopted HFE-7200 solvent systems, eliminating flammable storage capital barriers for new fabrication entrants.
- Food Processing:Tank cleaning, conveyor sanitation, and processing equipment maintenance with USDA and FDA food contact surface compliance.
- Laboratory Cleaning:Glassware washers, analytical instrument exteriors, and optical component maintenance in research settings.
- Automotive Painting:Paint booth glass and stainless-steel spray equipment cleaning with appearance-critical residue requirements.
Pharmaceutical production commands margin premium. Electronic manufacturing is climbing the fastest.
End User:
Customer type determines procurement sophistication, with semiconductor fabricators demanding embedded formulation scientists and contract manufacturing organizations seeking certified documentation for FDA-inspected export facilities.
- Contract Manufacturing Organizations:Hyderabad and Bengaluru CDMOs expanding technical service relationships for validated cleaning protocols in FDA-inspected export facilities.
- Semiconductor Fabricators:Cleanroom maintenance protocols with non-flammable solvent requirements and nitrogen-purged storage elimination.
- Food & Beverage Producers:Volume-driven alkaline detergent consumption with USDA compliance documentation.
- Research Institutions:Neutral cleaner demand for pH-sensitive optical and glass substrate maintenance.
Semiconductor fabricators drive specification intensity. Contract manufacturing organizations are where geographic expansion concentrates.
Packaging Type:
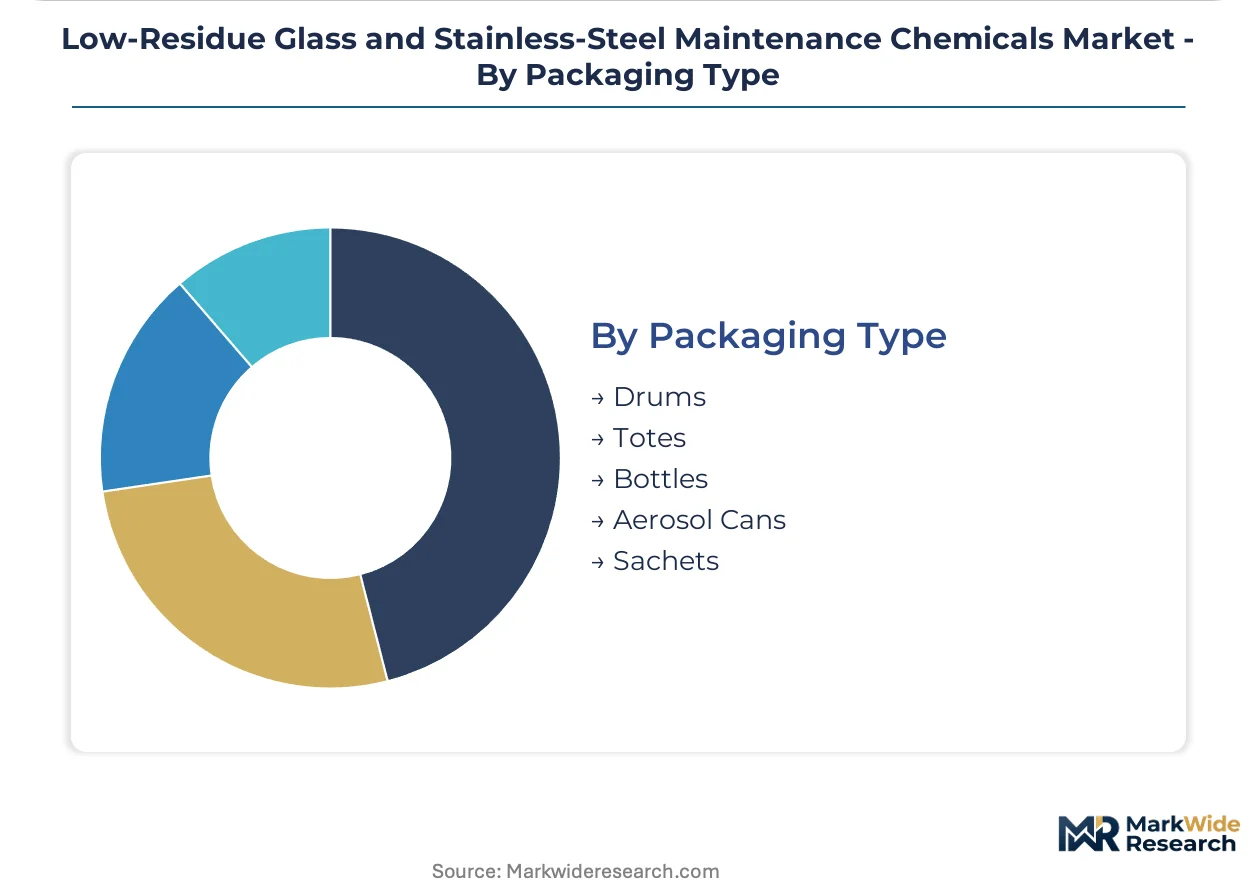
Volume scale and application criticality dictate packaging selection, with drums and totes serving high-throughput pharmaceutical CIP systems and aerosol cans addressing precision spot-cleaning in semiconductor tool maintenance.
- Drums:55-gallon and 15-gallon steel and poly containers for centralized CIP system feeding in pharmaceutical and food processing plants.
- Totes:Intermediate bulk containers for high-volume alkaline detergent distribution to multi-tank manufacturing facilities.
- Bottles:Laboratory-scale dispensing for research institutions and pilot plant operations.
- Aerosol Cans:Precision solvent application for semiconductor wafer-handling equipment spot maintenance.
- Sachets:Single-use pre-measured concentrates for validated cleaning protocol standardization.
Drums and totes dominate volume throughput. Aerosol cans are where packaging innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites the Netherlands' distribution dominance for REACH-registered formulations serving European pharmaceutical clusters.
United States
FDA inspection intensity in North Carolina and New Jersey parenteral drug facilities drives demand for documented residue validation protocols. EPA Safer Choice VOC thresholds constrain formulation chemistry, forcing reformulation cycles among industrial maintenance suppliers. The Research Triangle Park pharmaceutical corridor concentrates technical service relationships for bioreactor cleaning validation.
Germany
ECHA registration dossiers favor established European formulators with pre-existing toxicology portfolios against import competition. The EU F-Gas Regulation phase-down accelerates demand for low-global-warming-potential hydrofluoroether alternatives in precision cleaning. Munich-Stuttgart precision manufacturing clusters require certified low-residue protocols for medical device and automotive supply chain stainless-steel equipment.
Taiwan
Semiconductor fabricators adopt non-flammable hydrofluoroether solvent bases for wafer-handling equipment maintenance, displacing legacy flammable chemistries. Taiwan Semiconductor Manufacturing's cleanroom protocols eliminate nitrogen-purged storage requirements, collapsing capital barriers for new fabrication entrants. The Hsinchu Science Park concentration drives specification intensity for sub-part-per-billion contamination control.
South Korea
Samsung Foundry's adoption of HFE-7200 formulations mirrors Taiwan's flammable solvent displacement trajectory. MFDS pharmaceutical manufacturing standards align with FDA and EMA residue limit methodologies, creating harmonized validation documentation requirements. The Giheung and Hwaseong semiconductor complexes anchor solvent cleaner demand for photolithography tool maintenance.
India
Contract manufacturing organizations in Hyderabad and Bengaluru seek certified low-residue documentation for FDA-inspected export facilities. CDSCO's evolving Good Manufacturing Practice standards for active pharmaceutical ingredient production push adoption of validated cleaning protocols. The Genome Valley biotech cluster concentrates technical service relationship expansion for specialty chemical suppliers.
Low-Residue Glass and Stainless-Steel Maintenance Chemicals Market Competitive Landscape
On the supply side, the industry is consolidating around embedded technical service capabilities, compressing the viable vendor base to formulators capable of co-locating validation scientists at production sites. Three strategic archetypes dominate: global institutional suppliers with captive formulation science deployment, regional specialists with REACH-registered toxicology dossiers, and private-label competitors serving contract manufacturing documentation requirements. Competitive moves concentrate on direct technical service embedding and geographic expansion into FDA-inspected export manufacturing corridors.
Among global institutional suppliers, Ecolab exemplifies the embedded scientist archetype through site-based formulation validation, while Henkel occupies a position anchoring European supply through captive production capabilities. Zep represents the private-label tier competing on certified documentation programs for contract manufacturing organizations. These three players illustrate the market's bifurcation between technical service-intensive pharmaceutical relationships and documentation-focused CDMO supply.
| Leading Market Players |
|---|
| Ecolab |
| 3M |
| Zep |
| Reckitt Benckiser Group |
| Henkel |
| The Clorox Company |
| Procter & Gamble |
| S.C. Johnson & Son |
| SC Johnson Professional |
| Others |
Pricing and Supply Chain Analysis
The Port of Rotterdam's chemical handling infrastructure channels REACH-registered formulations across European pharmaceutical clusters, with freight cost dynamics amplifying price differentiation between bulk alkaline detergent contracts and precision solvent spot purchases. Supply concentration among Japanese and Chinese hydrofluoroether precursor producers feeds input cost volatility into semiconductor-grade solvent pricing, while drum-and-tote volume discounts compress margins for commodity alkaline concentrates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified low-residue formulations with full ECHA disclosure from private-label alternatives and commodity surfactant blends. Price differentiation hinges on REACH registration completeness and embedded technical service intensity, with pharmaceutical buyers absorbing premium positioning for on-site validation scientists. Cost compression in standard-grade alkaline detergents is intensifying because contract manufacturing organizations in India negotiate volume guarantees against certified documentation. Food and beverage producers exhibit highest price sensitivity, while semiconductor fabricators prioritize non-flammable solvent performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration among Hyderabad and Bengaluru CDMOs anchors demand growth for REACH-registered formulation imports, with Samsung Foundry and Taiwan Semiconductor Manufacturing driving solvent cleaner specification intensity. Supply draws from Germany for alkaline detergent production, Japan and China for hydrofluoroether precursors, and the Netherlands for distribution hub consolidation. Raw material dependencies center on fluorinated solvent feedstocks, chelating agent surfactants, and stainless-steel-compatible corrosion inhibitors. Single-source vulnerability in Japanese hydrofluoroether precursor supply exposes formulators to input cost swings. Distribution runs through direct technical service relationships for pharmaceutical accounts and distributor networks for commodity volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation phase-down constitutes a regulatory inflection accelerating chemistry transitions, positioning low-global-warming-potential hydrofluoroether alternatives as the dominant growth vector across precision cleaning applications.
For Market Incumbents: Entrench embedded formulation scientist capabilities at pharmaceutical production sites to defend against regional specialists with REACH-registered toxicology dossiers. Deepen backward integration into hydrofluoroether precursor supply through long-term offtake agreements with Japanese and Chinese specialty chemical producers. Prioritize certification investment for CDMO documentation programs in India's Genome Valley cluster. For New Entrants and Emerging Players: Establish a beachhead in India's contract manufacturing organization segment by offering certified low-residue documentation packages for FDA-inspected export facilities. Target the aqueous alkaline detergent substitution ceiling in semiconductor applications where water-based cleaners face performance limits against silicone residues. Pursue private-label partnerships with European distributors seeking REACH-registered alternatives to established formulators. For Investors and Strategic Acquirers: Regional specialists with captive REACH toxicology portfolios and embedded technical service relationships in Southern Germany's precision manufacturing corridor represent the most defensible acquisition archetype. Long-term viability hinges on regulatory moat sustainability against import competition and chemistry transition execution. Monitor CDSCO Good Manufacturing Practice enforcement intensity as the inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Feedstocks | Long-term offtake agreements with Japanese and Chinese precursor producers secure input cost stability. |
| REACH Registration Dossier Expansion | Full substance disclosure with ECHA creates regulatory moats against import competitors in European pharmaceutical clusters. |
| Embedded Technical Service Deployment | On-site formulation scientists at pharmaceutical production sites compress viable vendor bases to co-location capable suppliers. |
| CDMO Documentation Program Development | Certified low-residue protocols for FDA-inspected export facilities in India open geographic expansion corridors. |
| Hydrofluoroether Formulation Transition | Non-flammable HFE-7100 and HFE-7200 bases displace legacy flammable chemistries in semiconductor cleanrooms. |
Research Methodology
A spread of perspectives from plant managers at pharmaceutical production facilities, procurement leads at semiconductor fabricators, distribution channel partners, and technical R&D directors converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from ECHA registration databases, FDA Current Good Manufacturing Practice guidance documents, customs and trade flow data, and SEC filings from disclosed specialty chemical suppliers. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product chemistry type, end-use industry vertical, packaging format, and regional production hub. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment incorporated semiconductor fabrication capacity expansion schedules and pharmaceutical manufacturing inspection intensity as industry-specific forecast inputs.
Sensitivities concentrate around hydrofluoroether precursor supply disruptions, REACH registration timeline accelerations, and FDA inspection protocol harmonization across multi-regional facilities. Forecasts reflect assumptions about regulatory enforcement continuity and chemistry transition adoption curves. Quarterly review of CDSCO GMP enforcement bulletins, EU F-Gas Regulation phase-down milestones, and Taiwan semiconductor fabrication utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Pipeline Chemical Cleaners Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Cleaning Nozzles Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Bleaching Chemicals Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Dust Suppressant Market