
 Korea Industrial and Institutional Cleaning Chemicals Market | 2026-2036
Korea Industrial and Institutional Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Korea Industrial and Institutional Cleaning Chemicals Market Analytics
South Korea is reconfiguring its chemical manufacturing footprint with new capacity additions in Yeosu and Ulsan industrial complexes. BASF SE leverages its integrated surfactant operations to supply Korean institutional buyers with phosphate-free formulations. Kook Je Industry anchors domestic production through specialized degreaser lines for food processing plants. Croda International Plc competes on bio-based feedstock technology imported into Korean manufacturing plants.
Korea industrial and institutional cleaning chemicals comprise formulated surfactant blends, solvents, and antimicrobial agents engineered for sanitation in commercial and manufacturing environments, typically manufactured through batch sulfonation or enzymatic processing to achieve specific pH stability and foam control parameters. These formulations serve to remove contaminants, neutralize pathogens, and maintain operational hygiene across non-residential facilities where regulatory compliance mandates documented cleaning protocols. Disinfectant demand leads product type revenue as Korean healthcare facilities enforce stricter terminal cleaning standards post-pandemic. Bio-based grades represent the fastest-expanding segment as institutional buyers in Seoul and Busan prioritize MFDS-registered formulations with reduced aquatic toxicity profiles. Industrial grade formulations remain the mature volume base, though margin pools increasingly shift toward concentrated delivery systems that reduce logistics costs for remote manufacturing plants.
MFDS registration requirements govern antimicrobial claims and substance safety documentation for cleaning chemicals distributed to Korean hospitals and food processors. K-REACH compliance obligations force reformulation of legacy degreasers containing restricted solvents, redirecting R&D spending toward compliant alternatives. ISO 14001 environmental management certification shapes procurement criteria for manufacturing plant end users evaluating supplier qualification. Stakeholders must monitor pending amendments to Korea's chemical control act that could expand notification requirements for surface cleaner ingredients used in education facilities.
Market Dynamics
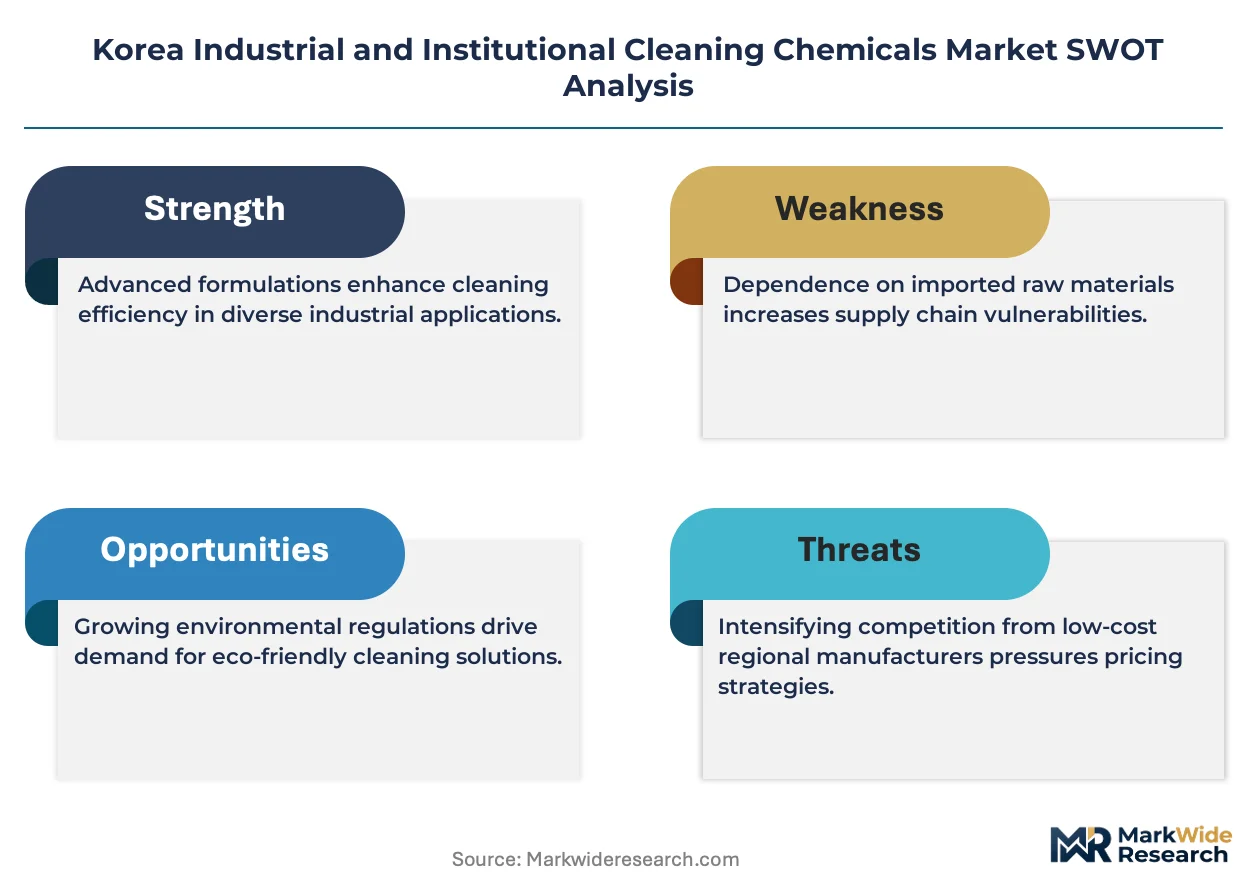
K-REACH substance registration deadlines are forcing Korean formulators to rebuild product portfolios around compliant chemistries, compressing development cycles and redirecting R&D budgets toward bio-based surfactant platforms.
Growth Catalysts
- Terminal cleaning mandates:Korean healthcare facilities enforce stricter disinfection protocols post-pandemic, expanding procurement of MFDS-registered antimicrobial formulations for hospital-grade sanitation.
- Yeosu industrial complex expansion:New sulfonation capacity additions in South Korea's petrochemical corridor reduce import dependency for key surfactant intermediates serving institutional buyers.
- Enzymatic processing adoption:Food processing plants in Busan and Incheon convert to cold-water compatible cleaning systems that cut energy consumption while maintaining degreasing efficacy.
Market Restraints
- Palm kernel oil volatility:Bio-based surfactant feedstock costs swing with Southeast Asian agricultural output, squeezing margin stability for domestic formulators.
- Yeosu-Ulsan production concentration:Over half of Korean surfactant manufacturing clusters within two coastal industrial zones, creating geographic vulnerability to port disruptions or regional environmental enforcement.
- K-REACH compliance friction:Legacy solvent-based degreasers face phase-out timelines that outpace substitute development, stranding inventory for metal fabrication end users.
Strategic Opportunities
- Daegu-Gyeongbuk manufacturing belt:Underpenetrated textile and electronics cleaning demand in Korea's southeastern industrial corridor offers first-mover positioning for concentrated delivery system suppliers.
- ISO 14001 procurement criteria:Manufacturing plant buyers increasingly mandate environmental management certification, creating competitive differentiation for qualified Korean chemical suppliers.
- Smart dispensing convergence:IoT-enabled dilution control systems paired with concentrated chemistry reduce per-site chemical consumption while locking in long-term supply contracts.
Industry Challenges
- Green chemistry talent scarcity:Korean universities produce insufficient formulation scientists trained in bio-based surfactant design, forcing employers to recruit from overseas competitors.
- MFDS registration timeline compression:Antimicrobial claim approvals stretch 18-24 months, delaying product launches and freezing working capital in pre-revenue inventory.
- Legacy system integration:Food processors struggle to retrofit enzymatic cleaning protocols into existing CIP infrastructure without extended production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Korea Industrial and Institutional Cleaning Chemicals Market |
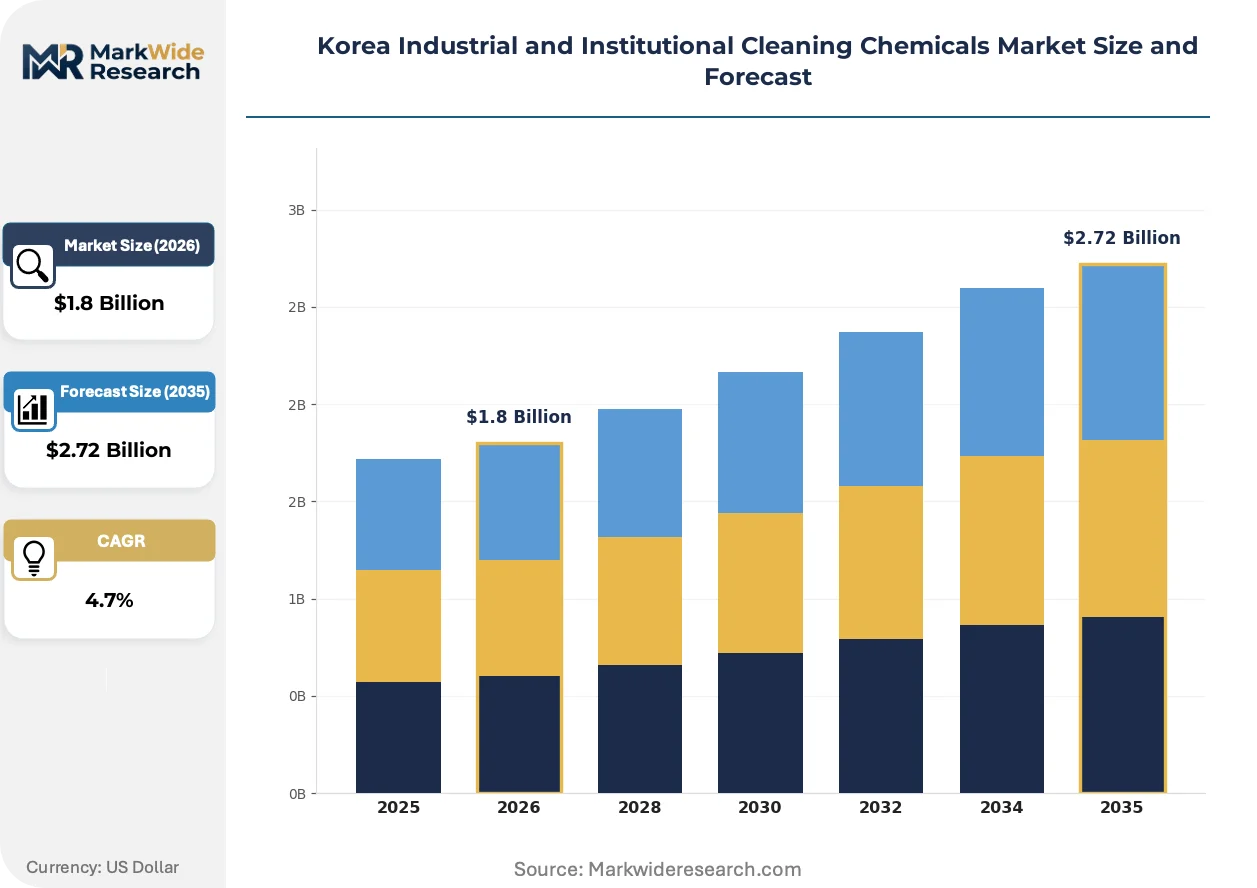
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Disinfectants, Degreasers, Surface Cleaners Application: Food Processing, Healthcare Facilities, Hospitality, Education End User: Manufacturing Plants, Hospitals, Restaurants, Schools Grade: Industrial Grade, Bio-Based, Phosphate-Free, Concentrated |
| Companies Covered | The Clorox Company, Croda International Plc, 3M, Huntsman International LLC, Eastman Chemical Corporation, BASF SE, Reckitt Benckiser Group Plc, Kook Je Industry, Procter & Gamble, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Korea Industrial and Institutional Cleaning Chemicals Market Evolving Landscape
Formulation chemistry and delivery mechanisms are converging around sustainability metrics and operational efficiency, reshaping how Korean institutional buyers evaluate supplier partnerships.
Phosphate-free surfactant technology is collapsing the traditional performance gap between petrochemical and bio-based alternatives. Seoul metropolitan hospitals now specify these formulations in tender documents, pressuring suppliers to eliminate legacy builders. The shift compresses pricing premiums for sustainable chemistry and accelerates volume migration away from phosphorus-containing products.
MFDS is tightening antimicrobial efficacy documentation requirements for surface disinfectants distributed to Korean healthcare and education facilities. Manufacturers must submit expanded toxicological data and environmental fate studies, extending registration timelines. Hospital procurement departments respond by consolidating supplier bases toward established registrants with proven compliance track records.
Buyer concentration among Korean hospital networks and integrated food processing conglomerates is consolidating purchasing authority into centralized procurement functions. Regional distributors lose shelf space as direct manufacturer relationships and volume-based contracting replace fragmented supply arrangements. This concentration is most visible in the Seoul-Incheon corridor where hospital group purchasing organizations now dominate disinfectant sourcing decisions.
Korea Industrial and Institutional Cleaning Chemicals Market Segmentation
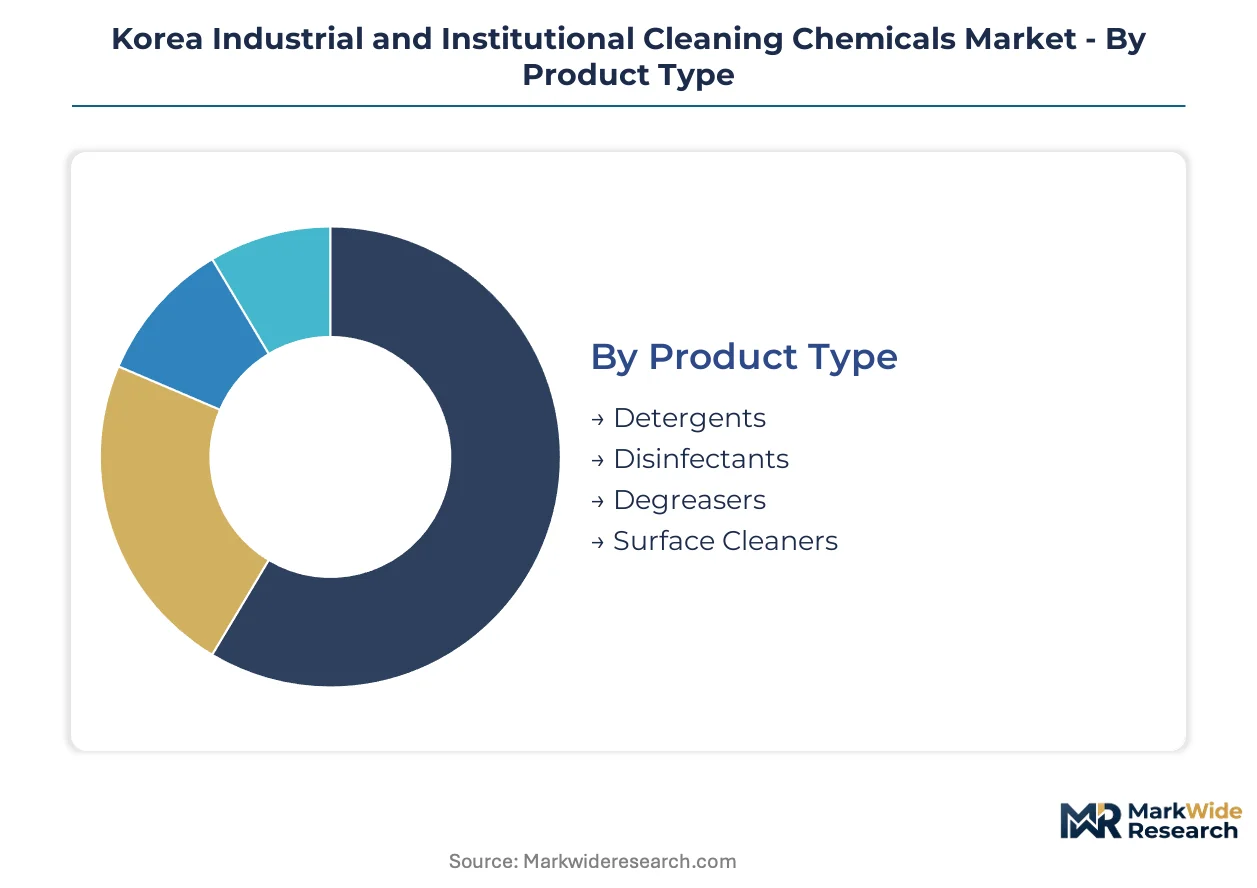
Segmentation in Korea's industrial and institutional cleaning chemicals market reveals how procurement authority concentrates among healthcare networks and food conglomerates. Formulators must align technical specifications with MFDS registration tiers and K-REACH compliance obligations to win supply contracts.
Product Type:
After-sales service intensity varies sharply across product categories, with disinfectants requiring MFDS re-registration support and technical training while detergents demand routine formulation troubleshooting.
- Disinfectants:Quaternary ammonium compound and chlorine-based formulations engineered for hospital-grade pathogen neutralization. Korean healthcare facilities in Seoul enforce terminal cleaning protocols that specify these chemistries, driving volume through group purchasing organizations with strict documentation requirements.
- Detergents:Surfactant blends optimized for pH stability and foam control across hard surface applications. Food processing plants in Busan and Incheon specify cold-water compatible enzymatic variants that reduce energy consumption while maintaining soil removal efficacy.
- Degreasers:Solvent-based and alkaline formulations targeting hydrocarbon removal in metal fabrication and automotive manufacturing.
- Surface Cleaners:General-purpose formulations for routine maintenance in commercial and institutional environments.
Disinfectants hold the largest share; momentum sits with bio-based detergent variants.
Application:
Cost tier differentiation separates premium MFDS-registered formulations for healthcare from commodity-grade products serving education and hospitality.
- Healthcare Facilities:Terminal cleaning and infection control applications demanding validated antimicrobial efficacy data. Korean hospital networks in the Seoul metropolitan corridor centralize procurement of disinfectants with proven compliance track records, extending registration timelines but locking in supplier relationships.
- Food Processing:Sanitation protocols for CIP systems and open plant cleaning with enzymatic cold-water compatibility. Plants in Busan convert from hot-caustic cycles to reduce energy costs while meeting HACCP documentation standards.
- Hospitality:Guest room and food service sanitation with emphasis on fragrance profiles and rapid surface turnover.
- Education:Routine disinfection of classrooms and common areas with lower regulatory burden than healthcare applications.
Healthcare facilities command premium pricing; education applications expand most quickly as MFDS extends registration requirements to school environments.
End User:
Customer type determines contract structure, with manufacturing plants negotiating multi-year supply agreements while restaurants purchase through distributor networks.
- Manufacturing Plants:Integrated chemical management programs spanning degreasers, detergents, and specialty solvents. Yeosu and Ulsan petrochemical complexes drive concentrated delivery system adoption to reduce drum handling and storage footprint.
- Hospitals:Centralized procurement functions with mandatory MFDS registration and documented cleaning protocols. Seoul-Incheon hospital group purchasing organizations dominate disinfectant sourcing decisions, squeezing regional distributors.
- Restaurants:Fragmented demand through food service distributors with price-sensitive procurement patterns.
- Schools:Municipal and private institutional buyers responding to pending amendments in Korea's chemical control act.
Hospitals hold the largest share; manufacturing plants show the steepest expansion trajectory for concentrated chemistry systems.
Grade:
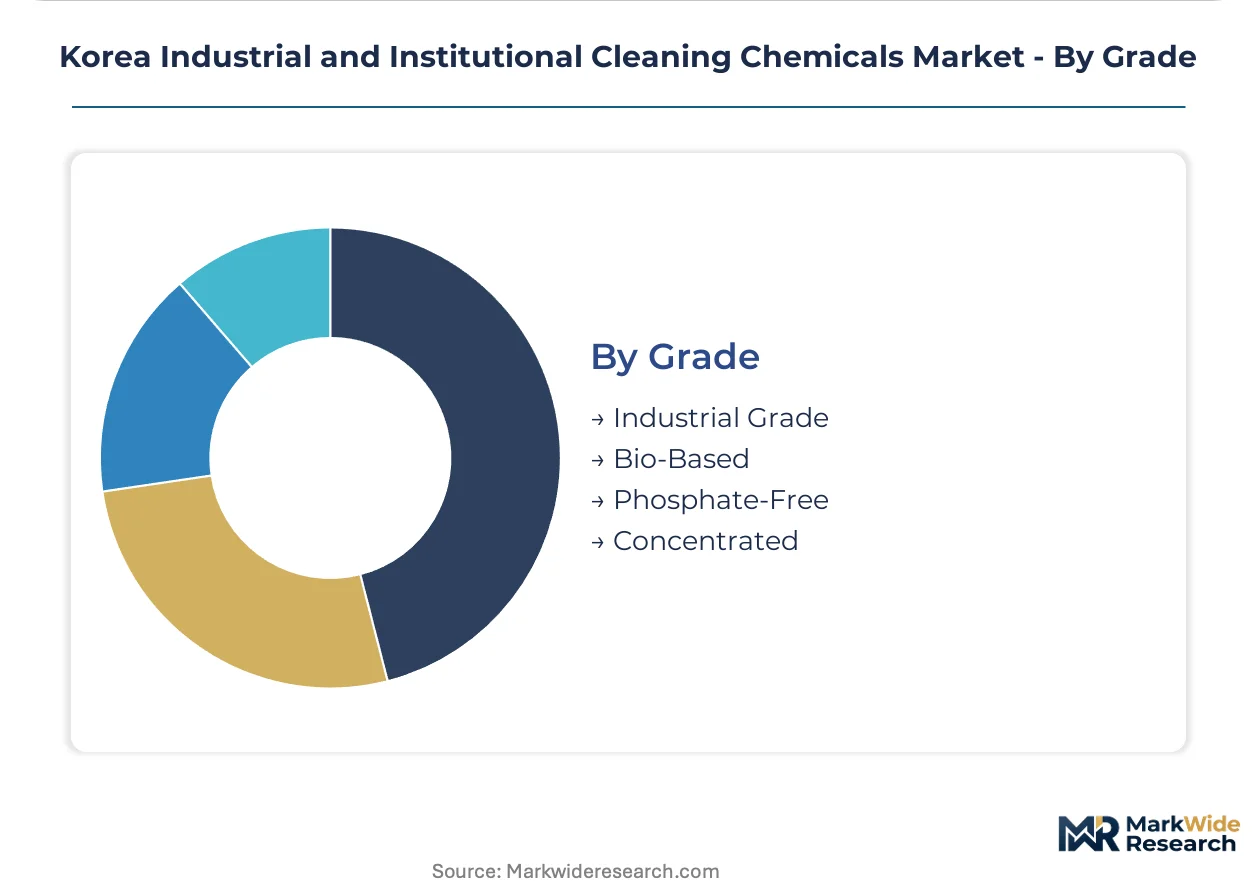
Volume concentration favors industrial grade formulations while margin pools migrate toward certified sustainable alternatives.
- Industrial Grade:Petrochemical-derived surfactants and solvents serving established manufacturing applications. These formulations remain the mature volume base though K-REACH compliance deadlines force portfolio rebuilding around restricted substance replacements.
- Bio-Based:Plant-derived surfactants with reduced aquatic toxicity profiles and MFDS-registered environmental fate data. Institutional buyers in Seoul and Busan prioritize these formulations as phosphate-free technology collapses performance gaps with conventional alternatives.
- Phosphate-Free:Builder-free formulations specified in Seoul metropolitan hospital tender documents.
- Concentrated:High-active chemistry designed for on-site dilution and IoT-enabled dispensing systems.
Industrial grade holds the largest share; bio-based grades gain share fastest as procurement criteria harden around sustainability metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yeosu and Ulsan industrial complexes concentrate over half of Korean surfactant manufacturing capacity, creating geographic vulnerability alongside economies of scale. This coastal clustering shapes procurement patterns for institutional buyers across the peninsula.
Seoul Capital Area
Hospital group purchasing organizations in Seoul and Incheon centralize disinfectant procurement, enforcing MFDS registration requirements and documented terminal cleaning protocols. The metropolitan corridor commands premium pricing for antimicrobial formulations. Healthcare network consolidation squeezes regional distributors from tender processes.
Busan-Ulsan
Food processing plants in Busan convert to enzymatic cold-water cleaning systems, cutting energy costs while maintaining HACCP documentation standards. Ulsan petrochemical complexes drive concentrated delivery system adoption to reduce drum handling logistics. K-REACH compliance deadlines force portfolio rebuilding among local formulators.
Daegu-Gyeongbuk
Textile and electronics manufacturers in Korea's southeastern industrial belt generate underpenetrated demand for specialized cleaning chemistries. ISO 14001 certification increasingly shapes supplier qualification for manufacturing plant buyers. First-mover positioning opportunities exist for concentrated delivery system suppliers targeting this corridor.
Daejeon-Sejong
Government research institutes in Daejeon anchor green chemistry R&D initiatives, though talent scarcity limits commercial translation. Bio-based surfactant development programs receive public funding support. Sejong administrative city procurement patterns influence national standards for institutional cleaning product specifications.
Gwangju-Honam
Agricultural processing and smaller-scale manufacturing in the southwestern region purchase through fragmented distributor networks rather than direct manufacturer relationships. Price-sensitive procurement patterns dominate institutional buyer behavior. Remote location logistics costs favor concentrated chemistry formulations that reduce transport frequency.
Korea Industrial and Institutional Cleaning Chemicals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying surfactant intermediates and antimicrobial actives. The Korean market exhibits tiered concentration with multinational chemical conglomerates holding hospital and food processing accounts while domestic formulators serve regional manufacturing plants. Three archetypes dominate: integrated petrochemical suppliers with captive surfactant production, specialized institutional formulators with MFDS registration expertise, and regional distributors losing share to direct manufacturer relationships. Competitive dynamics center on K-REACH compliance acceleration and smart dispensing system partnerships that lock in long-term supply contracts.
Among the named participants, BASF SE and Croda International Plc represent integrated multinational platforms with established Korean supply relationships, while Kook Je Industry anchors domestic production capabilities. These three exemplify divergent strategic positioning: the multinationals leverage global R&D scale and phosphate-free formulation portfolios, whereas the domestic specialist occupies regional manufacturing plant accounts with customized degreaser lines. The competitive terrain rewards MFDS registration track records and K-REACH compliance infrastructure over pure price positioning.
| Leading Market Players |
|---|
| The Clorox Company |
| Croda International Plc |
| 3M |
| Huntsman International LLC |
| Eastman Chemical Corporation |
| BASF SE |
| Reckitt Benckiser Group Plc |
| Kook Je Industry |
| Procter & Gamble |
| Others |
Value Network & Pricing Analysis
Yeosu and Ulsan industrial complexes concentrate over half of Korean surfactant manufacturing capacity, anchoring pricing power for domestic formulators while exposing buyers to regional supply disruptions. This coastal clustering compresses logistics costs for Seoul-Incheon hospital networks but amplifies vulnerability to port congestion or environmental enforcement actions.
Pricing Analysis
K-REACH dictates the pricing tier structure across the Korean market, separating MFDS-registered disinfectants for healthcare networks from commodity-grade surface cleaners serving education facilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, volume scale, and after-sales service bundling. Cost compression in bio-based grades is intensifying because palm kernel oil feedstock volatility squeezes margin stability. Restaurants and smaller manufacturing plants in Gwangju-Honam exhibit highest price sensitivity, while Seoul hospital group purchasing organizations prioritize compliance track records over unit cost.
Supply Chain Analysis
Domestic sulfonation capacity at Yeosu and Ulsan petrochemical complexes holds the majority of Korean surfactant production, with residual dependence on Southeast Asian palm kernel oil and German specialty chemical imports. Raw material sourcing draws from Indonesian and Malaysian agricultural output, German enzymatic processing technology, and Chinese packaging components. Single-source vulnerability concentrates in palm-derived feedstocks subject to El Niño-driven harvest volatility. Distribution runs through direct manufacturer relationships with hospital group purchasing organizations and food processing conglomerates, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic cold-water cleaning systems threaten incumbent solvent-based degreaser portfolios, forcing established suppliers to defend substitution risk through compliance acceleration and performance parity investments.
For Market Incumbents: Insulate core hospital and food processing accounts by accelerating K-REACH-compliant bio-surfactant R&D and securing ISO 14001 certification ahead of procurement mandate expansion. Backward integration into Yeosu sulfonation capacity reduces import exposure while locking in supply security for concentrated delivery system growth. Channel control through IoT-enabled dispensing partnerships creates switching costs that defend against enzymatic cleaning substitutes. For New Entrants and Emerging Players: Build out specialized presence in the underpenetrated Daegu-Gyeongbuk textile and electronics cleaning corridor, where ISO 14001 procurement criteria increasingly shape supplier qualification. First-mover positioning for concentrated chemistry systems serving remote manufacturing plants offers lowest competitive density. Direct sales engagement with municipal school procurement functions in Sejong exploits pending chemical control act amendments. For Investors and Strategic Acquirers: Carve-out targets emerge from domestic petrochemical conglomerates seeking to divest non-core institutional cleaning chemical divisions amid portfolio restructuring around green chemistry mandates. Long-term viability hinges on K-REACH compliance infrastructure and MFDS registration track records that compound competitive moats. Watch for consolidation signals among regional distributors losing share to direct manufacturer relationships as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfonation Capacity | Captive supply of key surfactant intermediates at Yeosu reduces palm kernel oil cost pass-through exposure. |
| MFDS Registration Acceleration | Antimicrobial claim approvals for healthcare disinfectants lock in multi-year supply contracts with Seoul hospital networks. |
| IoT-Enabled Dispensing Partnership | Smart dilution control systems paired with concentrated chemistry reduce per-site consumption while embedding supplier relationships. |
| Green Manufacturing Transition | Bio-based surfactant platforms satisfy tightening MFDS environmental fate documentation and Seoul tender specifications. |
| Joint Venture with Enzyme Technology Provider | Cold-water compatible cleaning systems cut energy costs for Busan food processors while meeting HACCP standards. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at Yeosu and Ulsan manufacturing complexes, procurement leads at Seoul hospital group purchasing organizations, distribution channel partners in Busan, and technical R&D directors specializing in bio-surfactant formulation, then refined against customs and trade data, Korea Petrochemical Industry Association reports, MFDS registration filings, and SEC disclosures from multinational chemical suppliers. Bottom-up volume estimates from individual facility consumption patterns were triangulated with top-down sector spending analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including grade tier (industrial, bio-based, phosphate-free, concentrated), end-use industry (healthcare, food processing, hospitality, education, manufacturing), packaging format, and regional production hub. CAGRs were derived from installed capacity trajectories, regulatory compliance timelines, and substitution elasticity estimates for enzymatic versus solvent-based cleaning systems.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese surfactant suppliers or accelerated enzymatic technology adoption by Korean food processors would shift outcomes beyond modeled ranges. Quarterly review of MFDS registration approval timelines, palm kernel oil futures, and K-REACH amendment progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Micellar Cleansing Water Market
Cleaning Chemicals
Descaler Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Mosquito Repellent Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Dry Electrostatic Wipes Market