
 Chemical Analyzer Market | 2026-2036
Chemical Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Analyzer Market Analysis
Recurring software and predictive maintenance subscriptions is broadening revenue capture beyond instrument sales for vendors serving life-science clients. Danaher Corporation leverages its diagnostic platform installed base to sustain high-margin service attach rates across clinical laboratories. Thermo Fisher Scientific anchors its position through R&D intensity in mass spectrometry workflows, while HORIBA Ltd. competes on optical sensor specialization for environmental monitoring applications.
Chemical analyzers are precision instruments that quantify elemental composition, molecular structure, or concentration through spectroscopic, chromatographic, or electrochemical methods, typically achieving detection limits in parts-per-billion for regulatory-compliant assays. Their primary commercial purpose is to ensure product safety, environmental compliance, and manufacturing quality across regulated industries. Chromatography systems command the largest installed base among product types, though mass spectrometry captures premium pricing for proteomics and metabolomics applications. Microfluidics technology is gaining fastest adoption where pharmaceutical companies miniaturize assay volumes to reduce reagent costs and accelerate throughput.
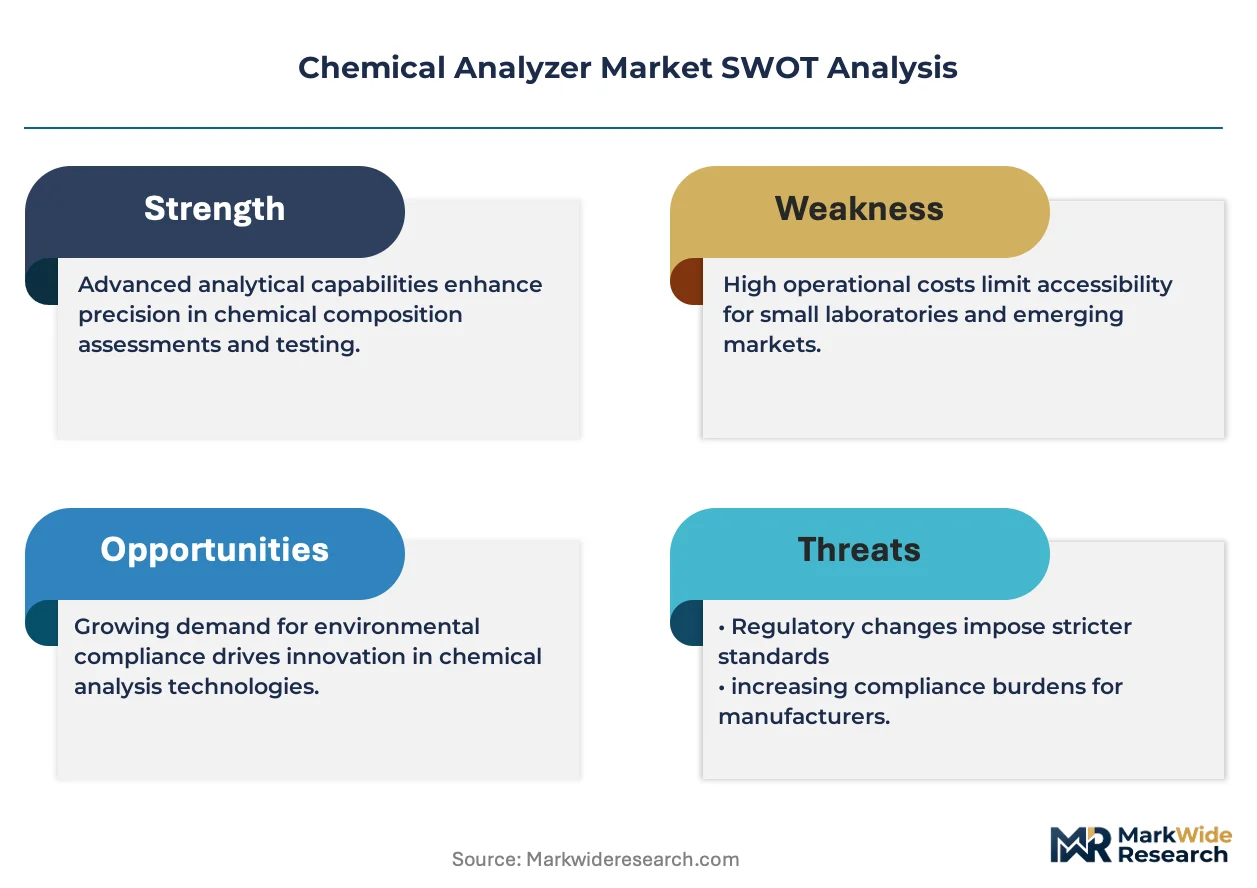
EPA methods and FDA guidance documents shape instrument specifications for environmental and pharmaceutical end users in the United States, while REACH compliance in Europe drives demand for trace-level detection capabilities in industrial laboratories. ISO 17025 accreditation requirements force quality control facilities to upgrade calibration protocols and data integrity systems. Stakeholders must monitor how AI-enabled spectral interpretation reshapes technician skill requirements and service delivery models.
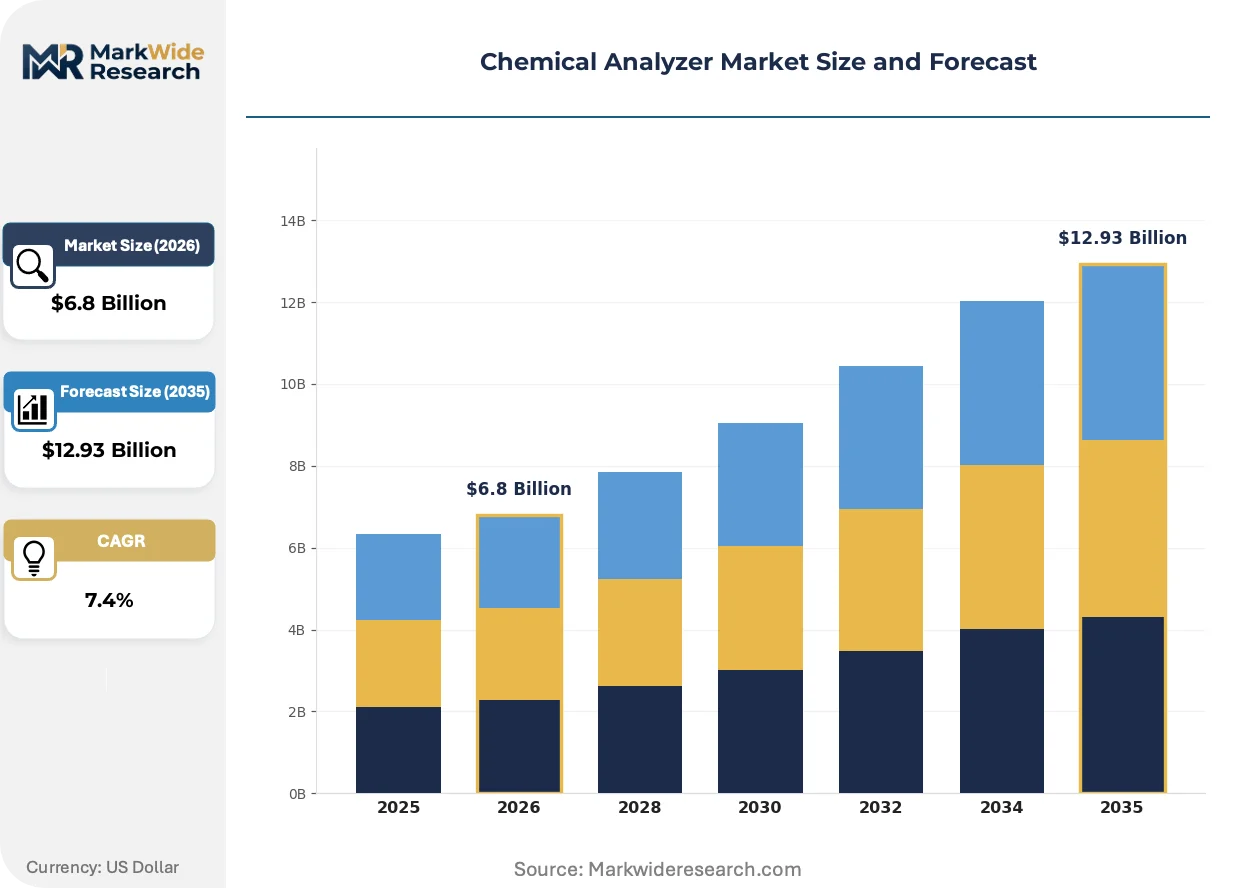
Market Dynamics
AI-enabled spectral interpretation is compressing technician training cycles while forcing recalibration of service delivery economics across analytical instrumentation vendors. This capability shift redistributes value from hardware margins toward software-enabled workflow automation.
Growth Catalysts
- FDA validation requirements:Pharmaceutical manufacturers in the United States expand chromatography and mass spectrometry fleets to meet drug purity mandates for biologics stability testing.
- REACH compliance:European industrial laboratories upgrade to trace-level detection systems for substance registration and restricted chemical monitoring.
- Microfluidics miniaturization:Assay volume reduction cuts reagent costs and accelerates throughput for high-throughput screening workflows.
Market Restraints
- Helium supply volatility:Gas chromatography operations face input cost pressure from concentrated noble gas sourcing in Qatar and Algeria.
- Detector component concentration:Specialized optical sensors and ion sources rely on limited qualified suppliers in Germany and Japan.
- ISO 17025 accreditation timelines:Quality control facilities endure 12-18 month certification cycles that delay instrument commissioning.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO compliance requirements and PLI scheme incentives drive greenfield analytical laboratory buildouts.
- AI-spectral convergence:Machine learning interpretation layers integrate with existing mass spectrometry hardware to automate compound identification.
- Environmental monitoring expansion:EPA method updates for PFAS detection mandate new instrument acquisitions at water utilities and industrial discharge sites.
Industry Challenges
- Mass spectrometry technician scarcity:Specialized training programs for ion source maintenance and method development lag instrument deployment rates.
- Legacy data system migration:21 CFR Part 11 compliance requirements force replacement of paper-based batch records and non-validated electronic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Analyzer Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomic Absorption, Mass Spectrometry, Chromatography, Spectrophotometry Application: Environmental Testing, Pharmaceutical Analysis, Food & Beverage Safety, Clinical Diagnostics End User: Laboratories, Research Institutions, Pharmaceutical Companies, Quality Control Facilities Technology: Optical Sensors, Thermal Sensors, Microfluidics, Automation Solutions |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., HORIBA Ltd., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Sysmex Corporation, QuidelOrtho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Analyzer Market Emerging Trajectories
Spectroscopic and chromatographic platforms are absorbing computational layers that automate interpretation and compress analytical cycles. This convergence redistributes competitive advantage from detection sensitivity toward workflow integration depth.
Machine learning algorithms for spectral deconvolution are integrating into chromatography data systems to flag anomalies and suggest compound identification without manual library searching. Pharmaceutical quality control laboratories in the United States adopt these modules fastest, driven by batch release timeline pressure. The technology is integrating method development and validation steps that previously required separate specialist interventions.
EPA method revisions for per- and polyfluoroalkyl substance quantification are mandating tandem mass spectrometry capabilities at municipal water testing facilities. Industrial laboratories must demonstrate sub-parts-per-trillion detection limits to meet discharge monitoring requirements. Environmental compliance service providers in California and Michigan are responding by consolidating instrument fleets around triple-quadrupole platforms.
Service contract unbundling is separating preventive maintenance, software updates, and technical support into discrete purchasing decisions. Biopharma procurement teams in Massachusetts and North Carolina now benchmark response-time guarantees independently from calibration service pricing. This shift is most visible among CDMOs managing multi-site instrument fleets under centralized vendor management programs.
Chemical Analyzer Market Segmentation
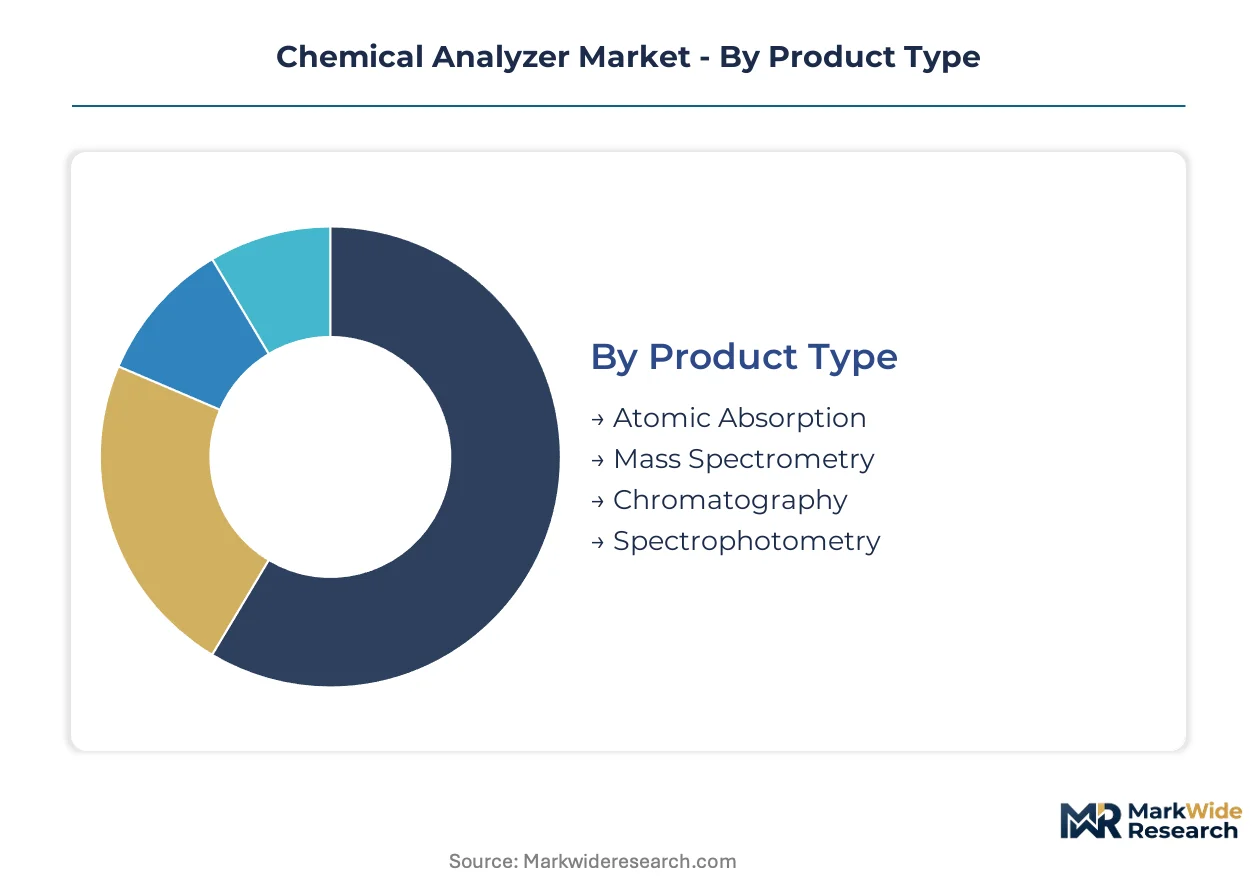
Chemical analyzer procurement patterns diverge sharply across product architectures and end-use environments. Capital deployment priorities shift based on detection sensitivity requirements, regulatory stringency, and throughput scaling needs.
Product Type:
Capital intensity peaks with mass spectrometry platforms requiring vacuum systems and precision ion optics, while chromatography systems spread fixed costs across higher unit volumes.
- Mass Spectrometry:Triple-quadrupole and time-of-flight architectures achieve parts-per-trillion detection limits for proteomics and metabolomics workflows. Pharmaceutical manufacturers in Massachusetts and North Carolina deploy these systems for biologics characterization under FDA validation protocols.
- Chromatography:Gas and liquid chromatography systems command the largest installed base through modular configurations that scale from benchtop quality control to preparative purification. Environmental laboratories in California upgrade HPLC fleets to meet EPA method revisions for PFAS quantification.
- Spectrophotometry:UV-Vis and infrared platforms serve routine concentration assays with lower barrier-to-entry pricing.
- Atomic Absorption:Flame and graphite furnace configurations specialize in heavy metal trace analysis for water utilities and industrial discharge monitoring.
Most installed capacity flows through Chromatography. Expansion is steepest in Mass Spectrometry.
Application:
Application mix tracks regulatory enforcement intensity, with environmental and pharmaceutical testing commanding premium instrument specifications.
- Pharmaceutical Analysis:Stability testing and impurity profiling require validated chromatography workflows with 21 CFR Part 11 compliant data systems. CDMOs in India expand analytical capacity to serve export markets under CDSCO and FDA dual compliance.
- Environmental Testing:Water utilities and industrial discharge sites adopt tandem mass spectrometry for per- and polyfluoroalkyl substance monitoring. EPA method updates in Michigan and California drive replacement of legacy single-quadrupole systems.
- Clinical Diagnostics:Hospital laboratories integrate automated immunoassay platforms with centralized laboratory information systems.
- Food & Beverage Safety:Pesticide residue and contaminant screening employs rapid chromatography methods for high-throughput batch release.
Pharmaceutical Analysis captures the highest average selling prices. Environmental Testing is expanding most quickly.
End User:
Procurement sophistication varies by organizational scale, with pharmaceutical companies negotiating enterprise service agreements and quality control facilities prioritizing ISO 17025 accreditation support.
- Pharmaceutical Companies:Biologics manufacturers in the United States deploy integrated mass spectrometry workflows from early development through commercial release. Method transfer between R&D and quality control sites demands vendor-managed calibration protocols.
- Quality Control Facilities:Third-party testing laboratories in Germany and Japan concentrate demand for multi-technique platforms serving industrial clients under REACH and JIS standards.
- Laboratories:Academic and government research centers access grant-funded instrumentation with emphasis on publication-grade sensitivity specifications.
- Research Institutions:National laboratories and university consortia drive adoption of emerging technologies including microfluidics and AI-enabled spectral interpretation.
Pharmaceutical Companies deploy the most capital per site. Quality Control Facilities are gaining share fastest.
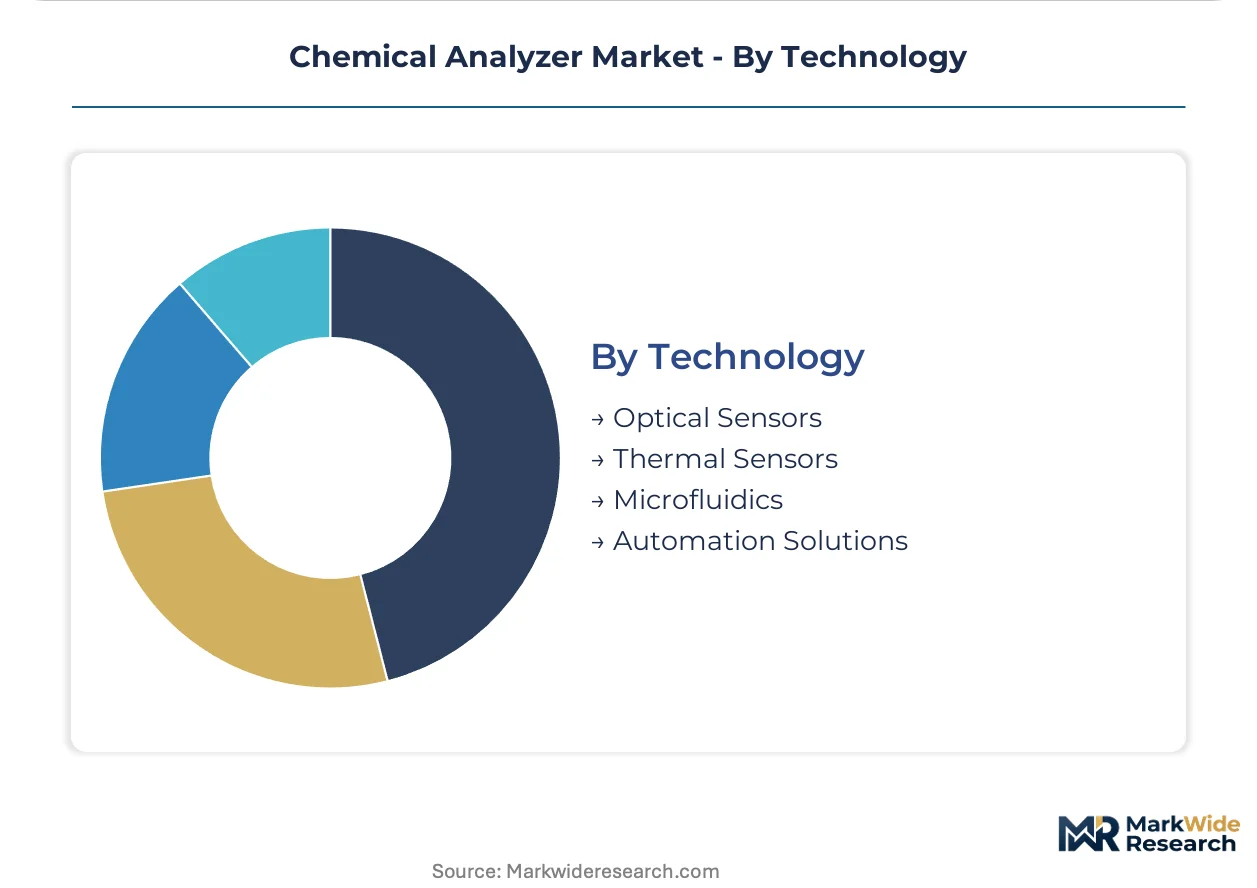
Technology:
Technology adoption curves reflect trade-offs between detection performance and operational complexity, with automation solutions reducing technician dependency.
- Microfluidics:Lab-on-chip architectures miniaturize assay volumes to nanoliter scales, cutting reagent costs for high-throughput screening. Pharmaceutical companies in Switzerland and the United Kingdom integrate these platforms into automated compound libraries.
- Automation Solutions:Robotic sample handling and cloud-connected data systems compress turnaround times for 24/7 operations. CDMOs in North Carolina deploy these modules to manage multi-site instrument fleets under centralized vendor management programs.
- Optical Sensors:Specialized photodiode arrays and CCD detectors enable rapid spectral acquisition for process analytical technology applications.
- Thermal Sensors:Differential scanning calorimetry and thermogravimetric analysis support materials characterization for polymer and pharmaceutical formulation development.
Optical Sensors dominate current deployment. Microfluidics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys more mass spectrometry capacity for biologics validation than any other single market, while Germany's industrial laboratory density creates comparable instrument demand through REACH enforcement and automotive supply chain testing.
United States
FDA validation protocols for drug purity and stability testing drive pharmaceutical manufacturers in Massachusetts and North Carolina to expand chromatography and mass spectrometry fleets. EPA method revisions for PFAS detection mandate tandem mass spectrometry acquisitions at municipal water utilities in California and Michigan. The Boston-Cambridge biotech corridor anchors the highest concentration of biologics analytical capacity.
Germany
Industrial laboratories serving automotive and chemical supply chains upgrade trace-level detection systems to meet REACH substance registration requirements. ECHA compliance deadlines accelerate replacement cycles for legacy single-quadrupole platforms in the Rhine-Ruhr industrial region. Bavaria's pharmaceutical manufacturing belt concentrates demand for 21 CFR Part 11 compliant data systems.
China
NMPA regulatory harmonization with ICH standards drives domestic pharmaceutical manufacturers to adopt international-grade analytical instrumentation. The country's national pharmaceutical regulator enforces data integrity requirements that mirror FDA guidance. Yangtze River Delta biopharma clusters in Shanghai and Suzhou deploy automated chromatography workflows for export market compliance.
India
CDSCO compliance requirements and PLI scheme incentives accelerate greenfield analytical laboratory buildouts for contract manufacturing organizations. The national pharmaceutical regulator mandates stability testing protocols that align with FDA and EMA standards. Hyderabad and Ahmedabad pharmaceutical manufacturing hubs concentrate demand for multi-technique platforms serving dual compliance markets.
Japan
PMDA quality guidelines for biologics and biosimilars sustain premium instrument specifications across pharmaceutical quality control facilities. METI industrial standards programs support adoption of process analytical technology in chemical manufacturing. The Kansai region's pharmaceutical and fine chemical clusters maintain dense concentrations of mass spectrometry service providers.
Chemical Analyzer Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated life-science conglomerates commanding premium pricing in pharmaceutical applications while regional equipment fabricators compete on service responsiveness in environmental monitoring. The vendor base concentrates around three strategic archetypes: diversified conglomerates with diagnostic platform installed bases, pure-play analytical instrumentation specialists, and emerging Asia-Pacific manufacturers with cost-optimized chromatography configurations. Competitive moves center on predictive maintenance subscription unbundling and AI-enabled spectral interpretation software layers that attach to existing hardware fleets.
Among diversified conglomerates, Danaher Corporation and Thermo Fisher Scientific occupy positions that exemplify the service-attach-rate model, while HORIBA Ltd. represents the specialization archetype in optical sensor technologies for environmental applications. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. sits within the Asia-Pacific cost-optimization tier alongside other regional manufacturers expanding into international compliance markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| HORIBA Ltd. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Sysmex Corporation |
| QuidelOrtho Corporation |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical manufacturers in Massachusetts and North Carolina negotiate enterprise service agreements that anchor pricing around predictive maintenance subscriptions rather than capital equipment transactions. This buyer concentration forces vendors to unbundle software updates, calibration services, and technical support into discrete purchasing decisions that compress hardware margins while expanding recurring revenue streams.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for chromatography systems as domestic manufacturers introduce cost-optimized configurations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated platforms with 21 CFR Part 11 compliance from entry-level systems serving academic laboratories. Pricing pressure stems from helium supply volatility and concentrated detector component sourcing in Germany and Japan. Contract manufacturing organizations exhibit highest price sensitivity due to multi-site fleet standardization mandates, while biologics innovators in the Boston-Cambridge corridor prioritize detection sensitivity over acquisition cost.
Supply Chain Analysis
Refurbishment flows for ion sources and vacuum systems create secondary supply channels that extend instrument lifecycles and delay new unit purchases. Manufacturing concentrates in Germany, Japan, and the United States for precision ion optics and optical sensor arrays. Specialized photodiode arrays and CCD detectors draw from limited qualified supplier bases concentrated in Bavaria and the Kansai region. Single-source vulnerability for helium sourcing in Qatar and Algeria disrupts gas chromatography operations. Distribution runs through authorized service providers and direct vendor relationships with pharmaceutical quality control facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chemical Analyzer Market functions as a stable compounder sustained by regulatory validation requirements that mandate periodic instrument replacement regardless of economic cycles.
For Market Incumbents: Deepen predictive maintenance subscription penetration to capture high-margin service attach rates across clinical and pharmaceutical installed bases. Expand backward integration into specialized detector component production to reduce exposure to German and Japanese supplier concentration. Counter emerging Asia-Pacific cost-optimized entrants by emphasizing FDA and EPA method validation support that domestic manufacturers cannot replicate. For New Entrants and Emerging Players: Enter via environmental monitoring applications in India and Southeast Asia where CDSCO compliance buildouts and greenfield laboratory construction outpace established vendor service capacity. Target water utilities facing EPA method revisions for PFAS detection that mandate tandem mass spectrometry acquisitions without legacy vendor relationships. Lead with AI-enabled spectral interpretation software layers that integrate with existing hardware fleets rather than competing on instrument sensitivity specifications. For Investors and Strategic Acquirers: Life-science conglomerates with diagnostic platform installed bases are the most active acquirer in this space, seeking predictive maintenance revenue streams and regulatory compliance expertise. Acquisition targets should display dense service contract backlogs and established FDA validation protocol libraries rather than pure hardware manufacturing scale. Monitor EPA method update announcements and REACH compliance deadline accelerations as inflection indicators for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Spectral Interpretation Integration | Machine learning layers automate compound identification for pharmaceutical quality control laboratories under FDA batch release pressure. |
| Microfluidics Platform Development | Lab-on-chip architectures reduce reagent costs for high-throughput screening workflows in Swiss and UK pharmaceutical compound libraries. |
| Predictive Maintenance Subscription Unbundling | Service contract separation enables CDMO procurement teams in Massachusetts and North Carolina to benchmark response-time guarantees independently. |
| Helium Recovery System Investment | Closed-loop noble gas recycling mitigates supply volatility from concentrated Qatar and Algeria sourcing for gas chromatography operations. |
| CDSCO Dual Compliance Certification | Indian pharmaceutical manufacturing hubs in Hyderabad and Ahmedabad demand multi-technique platforms serving export and domestic markets simultaneously. |
Methodological Framework
Bottom-up pharmaceutical and environmental laboratory modeling reconciled against top-down analytical instrumentation production tracking forms the analytical core of this study. Primary interviews with quality control facility managers, regulatory affairs specialists at CDMOs, EPA compliance officers, and aftermarket service directors combined with secondary validation from FDA guidance documents, ECHA substance registration databases, EPA method revisions, and SEC filings from diversified life-science conglomerates. Triangulation between demand-side procurement patterns and supply-side manufacturing capacity ensures segment-level accuracy.
Historical instrument deployment trendlines across mass spectrometry, chromatography, and spectrophotometry platforms establish baseline penetration rates that inform projection modeling. Segmentation dimensions include product architecture, application environment, end-user scale, and technology adoption curve, with regulatory compliance intensity serving as an industry-specific weighting factor. CAGRs derive from replacement cycle analysis, greenfield laboratory buildout tracking, and method update enforcement timelines rather than extrapolated growth rates.
Inputs from EPA method revision schedules and ECHA compliance deadline announcements were available through the study window; gaps in real-time helium supply contract pricing and proprietary AI-spectral algorithm performance metrics introduce uncertainty bands around service revenue projections. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and supply chain concentration persistence. Practitioners should monitor EPA PFAS method finalization dates, REACH substance restriction expansions, and NMPA-ICH harmonization progress for early signals of replacement cycle acceleration or delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
Durability Testing Systems Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Chromatography Data Systems Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Gold Tester Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Membrane Osmometer Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Sand Testing Equipments Market