
 Battery Analyzer Market | 2026-2036
Battery Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Analyzer Market Outlook
Equipment leasing and pay-per-test service models is rewriting competitive access for mid-sized battery test labs. Keysight Technologies leverages its RF measurement heritage to dominate high-frequency impedance applications. B&K Precision Corporation anchors its position through calibrated instrument families priced for educational and maintenance markets. Chroma ATE Inc. competes on manufacturing scale, supplying automated test lines to Asian cell producers.
A battery analyzer measures electrochemical performance through voltage, current, resistance, and impedance characterization, typically operating across ranges from microvolts to kilovolts with microampere resolution for diagnostic accuracy. The instrument serves primary industrial purposes in quality assurance, predictive maintenance, and research validation for energy storage systems. Portable analyzers occupy the largest revenue pool among product types due to field service requirements in automotive and telecom backup power. Impedance spectroscopy commands premium positioning within technology segments, as the technique enables non-destructive state-of-health estimation that conductance methods cannot replicate. Automotive testing applications generate the fastest volume expansion, driven by warranty liability concerns among EV manufacturers.
The EU Green Deal battery passport framework and REACH substance restrictions are reshaping analyzer specifications, mandating traceable test documentation across European cell supply chains. China's GB standards and MIIT circular economy regulations enforce comparable documentation for domestic battery producers. The US EPA hazardous waste rules and OSHA electrical safety standards govern analyzer deployment in North American recycling facilities. Stakeholders must monitor which regulatory jurisdiction's test protocol gains adoption in cross-border supply contracts.
Market Dynamics
EU battery passport mandates under the EU Green Deal are compressing test documentation cycles and forcing analyzer vendors to embed traceability software directly into hardware platforms.
Growth Catalysts
- EU Green Deal battery passport framework:Mandates under REACH and the EU Green Deal require cell-level test documentation across European supply chains, pulling analyzer procurement into gigafactory qualification workflows.
- Impedance spectroscopy adoption:Non-destructive state-of-health estimation that conductance methods cannot replicate is displacing legacy diagnostic protocols in automotive warranty programs.
- China's manufacturing belt concentration:Cell producers in Jiangsu and Guangdong provinces require inline testing equipment, concentrating demand for automated analyzer lines in East Asian production corridors.
Market Restraints
- Precision component supply concentration:High-resolution ADCs and precision current sensors concentrate in Taiwanese and South Korean foundries, exposing analyzer OEMs to single-source fragility.
- Calibration gas and reference cell cost volatility:Lithium cobalt oxide reference cells and certified electrolyte standards face price instability tied to cobalt extraction disruptions in the DRC.
- Technical limitation in solid-state interfaces:Existing impedance spectroscopy protocols struggle with ceramic electrolyte characterization, constraining analyzer utility for next-generation solid-state battery R&D.
Strategic Opportunities
- India's PLI scheme for ACC battery manufacturing:Production-linked incentives for advanced chemistry cell plants in Gujarat and Tamil Nadu create virgin demand for analyzer deployment in emerging South Asian gigafactories.
- Equipment leasing and pay-per-test service models:Mid-sized battery test labs in Germany and South Korea are accessing high-end impedance analyzers through subscription structures rather than capital purchase.
- AI-driven predictive maintenance convergence:Machine learning algorithms trained on analyzer output streams are enabling predictive cell replacement in telecom backup power installations.
Industry Challenges
- Electrochemical modeling expertise scarcity:Analyzer vendors struggle to recruit engineers capable of translating raw impedance spectra into actionable state-of-health algorithms for EV fleet operators.
- Multi-jurisdiction certification timelines:Simultaneous CE marking, UL listing, and China Compulsory Certification requirements extend product launch cycles by 8-14 months for portable analyzer platforms.
- Legacy BMS integration complexity:Analyzer data streams must interface with proprietary battery management system architectures from incumbent automotive Tier 1s, requiring costly protocol adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Analyzer Market |
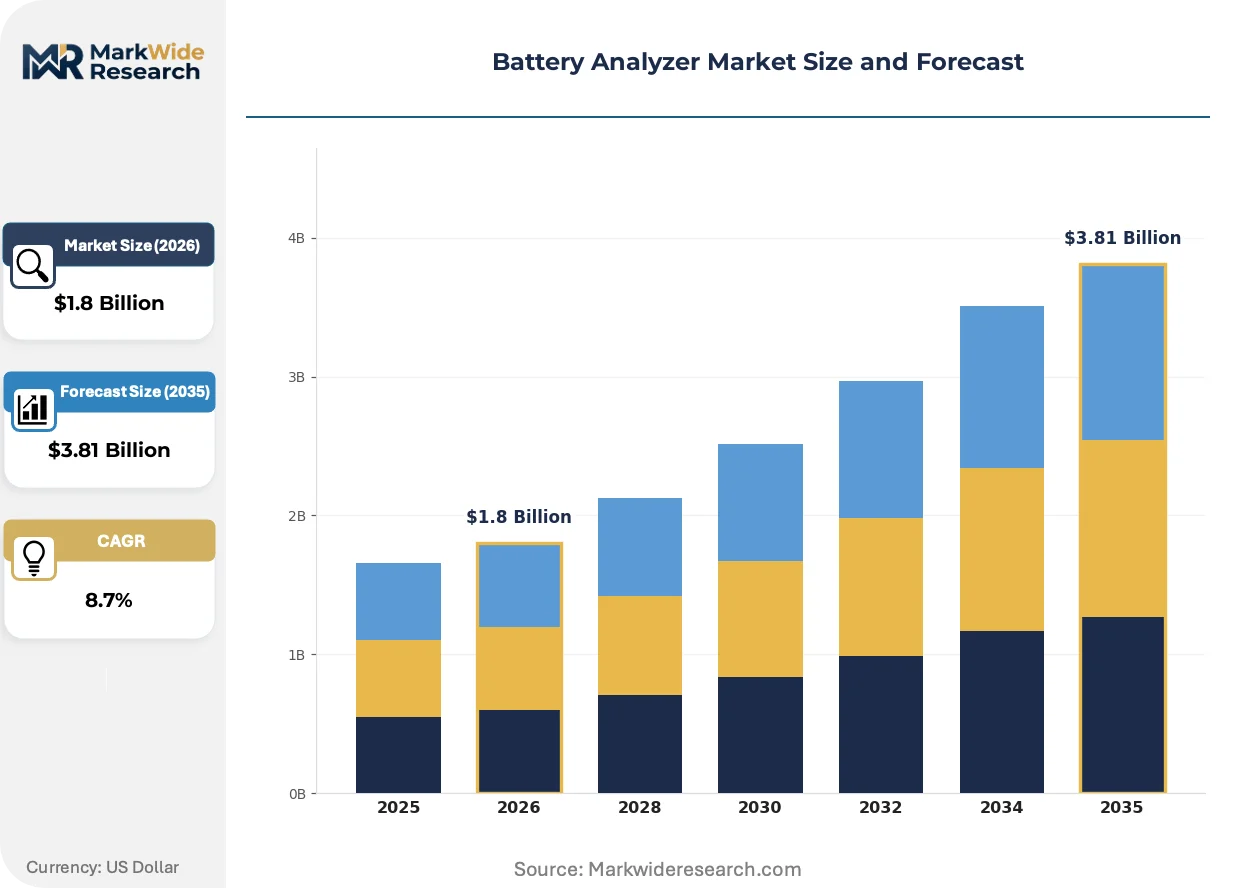
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Stationary Analyzers, Digital Analyzers, Advanced Analyzers Technology: Conductance Testing, Impedance Spectroscopy, Thermal Imaging, Performance Analysis Application: Automotive Testing, Industrial Applications, Renewable Energy Systems, Consumer Electronics End User: Manufacturers, Maintenance Providers, Research Institutions, Resellers |
| Companies Covered | Keysight Technologies, B&K Precision Corporation, AMETEK Inc., ACE Instruments, Hioki E.E. Corporation, Fluke Corporation, Chroma ATE Inc., Teledyne FLIR LLC, Cadex Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Analyzer Market Strategic Shifts
Analyzer architectures are bifurcating between high-frequency laboratory instruments and ruggedized field units, with software-defined measurement cores enabling hardware consolidation across both branches.
Wideband electrochemical impedance spectroscopy (EIS) platforms operating from millihertz to megahertz are rendering obsolete narrowband conductance-based analyzers in automotive warranty validation. BMW and Hyundai Motor Group have mandated EIS-capable equipment for supplier qualification. The technique's ability to isolate electrode degradation mechanisms without cell disassembly is compressing root-cause analysis timelines from weeks to hours.
REACH substance restrictions and the EU Green Deal battery passport framework are mandating traceable test documentation across European cell supply chains. Analyzer vendors must now embed cryptographic data signing and blockchain-ready export formats to satisfy ECHA audit requirements. German EV fleet operators and Dutch recycling facilities represent the most advanced compliance adopters, with equipment specifications increasingly written around documentation integrity rather than raw measurement precision.
Telecom infrastructure operators in Southeast Asia are unbundling after-sales calibration and recertification from initial equipment purchase, treating analyzer maintenance as an operational expense rather than capital burden. Field service providers in Indonesia and Vietnam now compete on technician response time to cell tower sites, with analyzer uptime guarantees becoming contract differentiators. This service-model rotation is compressing vendor margins on hardware while expanding recurring revenue pools for calibration specialists.
Battery Analyzer Market Segmentation
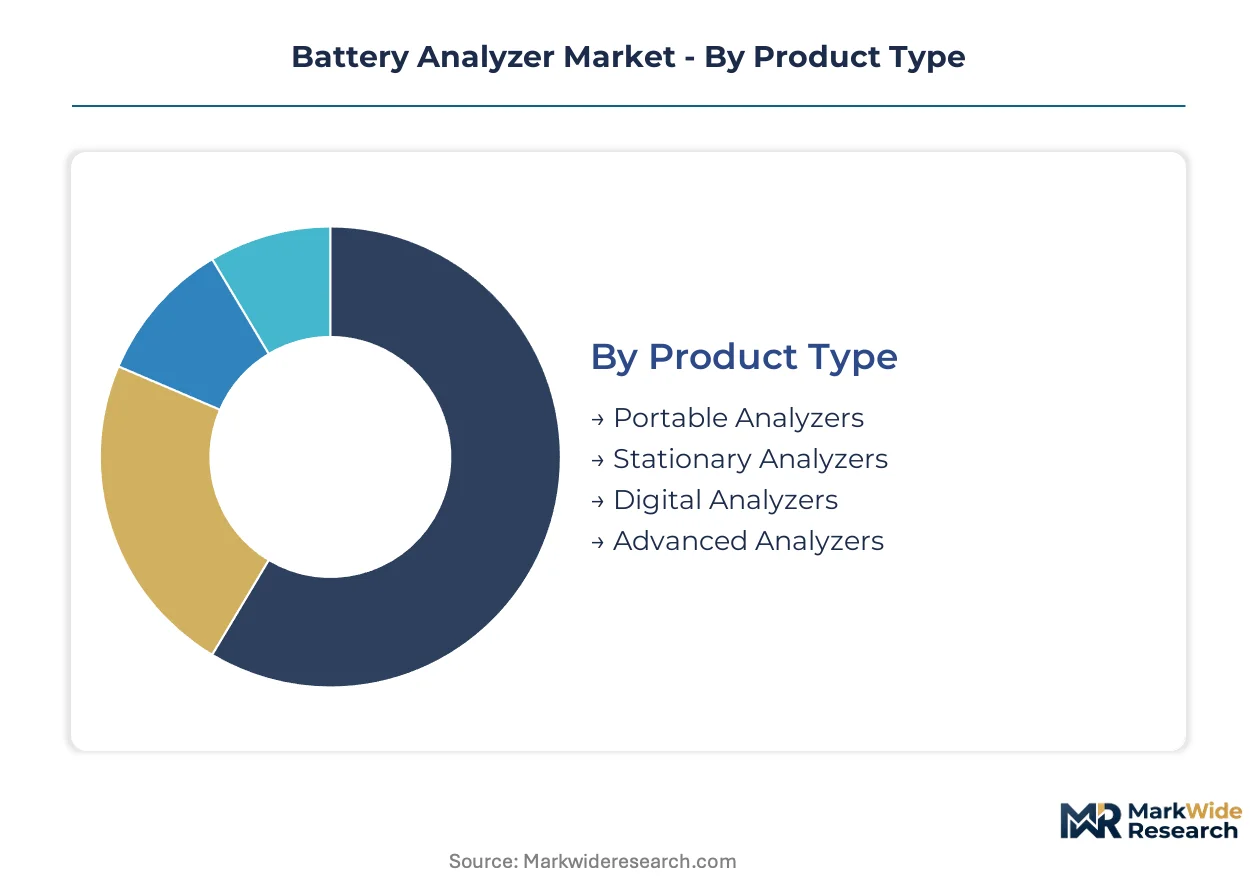
Segmentation in the battery analyzer market reflects divergent performance requirements across field service, laboratory validation, and production-line environments. Equipment specifications vary sharply between portable units for telecom technicians and high-precision laboratory platforms for cell qualification workflows.
Product Type:
Cost tier stratification separates capital-intensive stationary installations from accessible portable units for service technicians.
- Portable Analyzers:Handheld units with microampere resolution and Bluetooth data export dominate field service deployments. EV fleet operators in Germany and telecom maintenance crews across Southeast Asia account for concentrated procurement volumes, driven by warranty documentation mandates under EU battery passport rules.
- Stationary Analyzers:Rack-mounted systems with kilovolt-range capability serve gigafactory quality assurance lines. Chinese cell producers in Jiangsu and Guangdong provinces anchor demand, where inline testing equipment integrates directly with production conveyors for 100% cell inspection.
- Digital Analyzers:Software-defined measurement cores consolidate multiple test protocols into single hardware platforms.
- Advanced Analyzers:Multi-technique instruments combining impedance spectroscopy with thermal characterization target R&D laboratories.
Portable analyzers command the established base. The steepest expansion runs through stationary analyzers.
Technology:
Application maturity divides legacy conductance methods from emerging non-destructive diagnostic protocols.
- Impedance Spectroscopy:Wideband EIS platforms operating millihertz-to-megahertz isolate electrode degradation without cell disassembly. BMW and Hyundai Motor Group have mandated EIS-capable equipment for supplier qualification, compressing root-cause analysis timelines from weeks to hours in automotive warranty programs.
- Conductance Testing:Legacy DC resistance measurement remains entrenched in forklift battery maintenance and telecom backup power servicing. The technique's hardware simplicity sustains adoption among price-sensitive maintenance providers in Indonesia and Vietnam.
- Thermal Imaging:Infrared-based hotspot detection complements electrical characterization for safety-critical applications.
- Performance Analysis:Integrated cycling and rate capability testing targets research validation workflows.
Conductance testing commands the established base. The steepest expansion runs through impedance spectroscopy.
Application:
End-use volume concentration centers on automotive qualification workflows and industrial asset management.
- Automotive Testing:Cell-level validation for EV powertrains drives premium equipment procurement. Warranty liability concerns among European and Korean manufacturers pull high-frequency impedance analyzers into supplier audit protocols, with test documentation now required for EU battery passport compliance.
- Industrial Applications:Forklift fleets, uninterruptible power supplies, and material handling equipment sustain recurring demand for conductance-based field testers. Maintenance contractors compete on analyzer uptime guarantees as operational expense models displace capital purchase.
- Renewable Energy Systems:Grid-scale battery installations require periodic state-of-health verification for insurance and financing purposes.
- Consumer Electronics:Smartphone and laptop battery recycling facilities deploy basic capacity testers for sorting workflows.
Industrial applications command the established base. The steepest expansion runs through automotive testing.
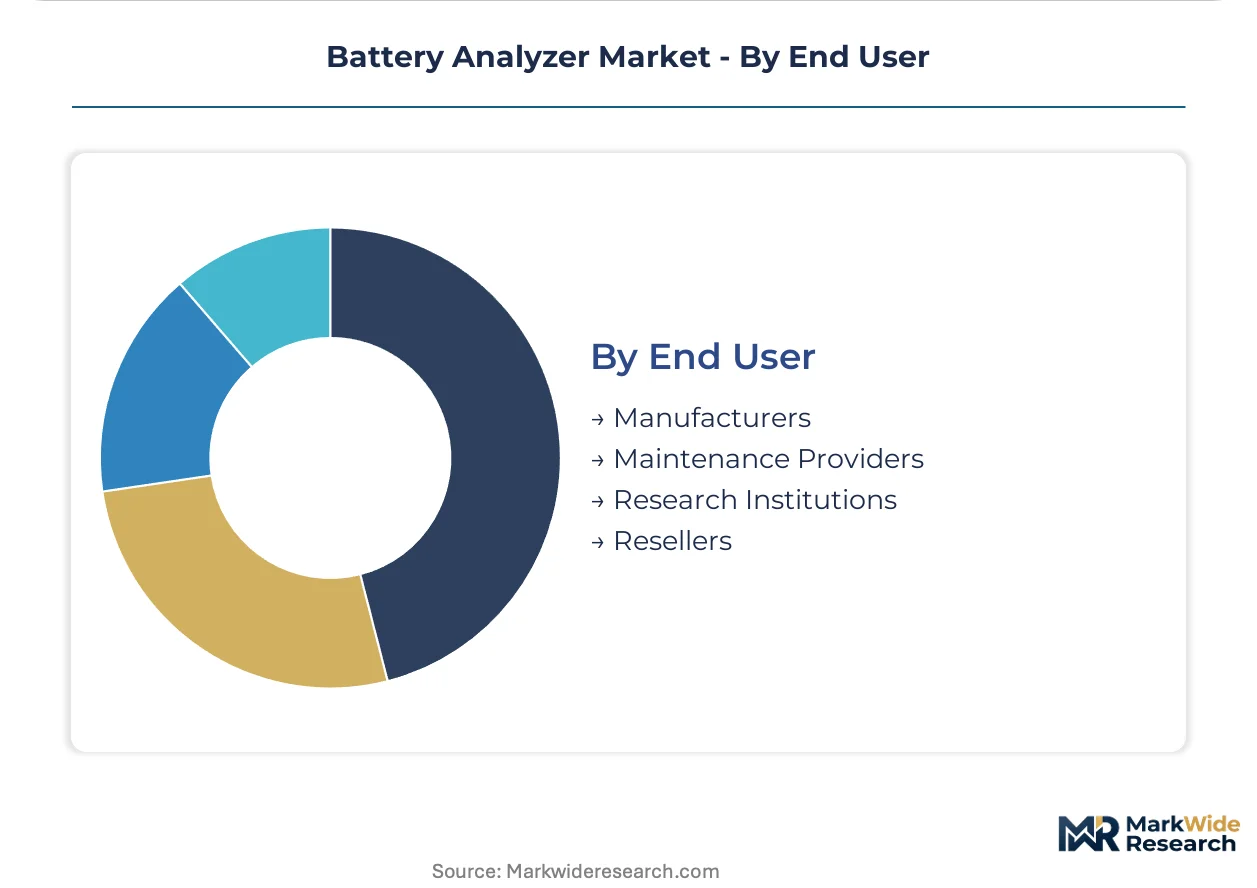
End User:
Customer type determines procurement modality, from capital-intensive manufacturing lines to subscription-based service access.
- Manufacturers:Cell producers and automotive OEMs purchase automated test lines as capital equipment. Chinese gigafactories in the manufacturing belt represent the densest concentration, where inline analyzer deployment correlates with production capacity expansion.
- Maintenance Providers:Independent service technicians and field operations teams access equipment through leasing and pay-per-test subscriptions. German and South Korean test labs have pioneered this model for high-end impedance analyzers previously beyond mid-tier capital budgets.
- Research Institutions:Universities and national laboratories procure multi-technique platforms for electrochemical mechanism studies.
- Resellers:Distributors and system integrators bundle analyzers with calibration and training services.
Manufacturers command the established base. The steepest expansion runs through maintenance providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal battery passport mandates and India's PLI scheme for advanced chemistry cells are redrawing procurement maps for analyzer vendors. National regulations now determine equipment specification requirements more than raw demand volume.
Germany
EV fleet operators in Bavaria and North Rhine-Westphalia are expanding analyzer procurement as KBA enforcement of EU battery passport traceability tightens. ECHA documentation requirements under REACH now mandate cryptographic data signing capabilities in equipment specifications. Stuttgart's automotive supplier cluster has mandated EIS-capable analyzers for cell qualification workflows.
China
Cell producers in Jiangsu and Guangdong provinces anchor demand for inline testing equipment as MIIT circular economy regulations enforce domestic battery documentation standards. GB standards compliance now requires traceable test records across production lines. Shenzhen and Suzhou manufacturing corridors concentrate automated analyzer deployment at gigafactory scale.
United States
Recycling facilities in Michigan and Ohio deploy analyzers under EPA hazardous waste rules governing battery processing operations. OSHA electrical safety standards shape equipment specifications for North American deployment. Detroit's automotive R&D cluster drives premium instrument procurement for solid-state battery development programs.
India
Production-linked incentives for ACC battery plants in Gujarat and Tamil Nadu create virgin demand for analyzer deployment in emerging gigafactories. BIS certification requirements for test equipment are formalizing as domestic cell production scales. The Delhi-Mumbai industrial corridor is attracting analyzer vendors establishing calibration service networks.
South Korea
Battery test labs in Seoul and Gyeonggi Province pioneered subscription-based access to high-end impedance analyzers previously beyond mid-tier capital budgets. MFDS-equivalent documentation standards for cell exports to Europe are pulling traceability software into hardware platforms. Busan's port logistics cluster is developing analyzer recertification hubs for regional equipment leasing networks.
Battery Analyzer Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three strategic archetypes: precision instrument heritage houses, manufacturing-scale automation suppliers, and field-service-oriented portability specialists. Consolidation pressure runs highest in laboratory-grade segments where impedance spectroscopy capabilities command premium positioning. Competitive moves center on strategic partnerships with automotive OEMs and geographic expansion through calibration service networks.
Among precision measurement heritage houses, Keysight Technologies and Hioki E.E. Corporation exemplify the high-frequency impedance application tier. B&K Precision Corporation anchors the educational and maintenance market archetype through calibrated instrument families. Chroma ATE Inc. represents the manufacturing-scale automation supplier category serving Asian cell production corridors. These three archetypes collectively define competitive positioning without any single vendor commanding cross-segment dominance.
| Leading Market Players |
|---|
| Keysight Technologies |
| B&K Precision Corporation |
| AMETEK Inc. |
| ACE Instruments |
| Hioki E.E. Corporation |
| Fluke Corporation |
| Chroma ATE Inc. |
| Teledyne FLIR LLC |
| Cadex Electronics Inc. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese inline testing equipment manufacturing is compressing margins for stationary analyzer OEMs while simultaneously expanding procurement leverage for cell producers in Jiangsu and Guangdong. This utilization imbalance feeds directly into pricing posture: suppliers with captive component production defend position through bundled service contracts, while pure-play hardware vendors absorb margin erosion to maintain gigafactory relationships.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with CE-marked and UL-listed analyzers commanding substantial premiums over uncertified alternatives for European and North American buyers. The dominant structure stratifies across three tiers: capital purchase for manufacturing-scale deployments, equipment leasing for mid-tier test labs, and pay-per-test subscriptions for field service providers. Price erosion runs through portable analyzer segments as Chinese manufacturers expand calibrated instrument families into educational and maintenance markets. Maintenance providers in Southeast Asia exhibit highest price sensitivity, while German EV fleet operators under KBA enforcement show lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Export control regimes limiting high-resolution ADC and precision current sensor flows from Taiwanese and South Korean foundries are constraining analyzer OEM sourcing flexibility. Component supply concentrates in Taiwan, South Korea, and Japan for high-frequency impedance measurement cores, while electrochemical reference cells and certified electrolyte standards draw from Chinese processing facilities and DRC cobalt extraction. Single-source vulnerability in precision sensor foundries exposes vendors to allocation risk during semiconductor demand cycles. Distribution runs through direct sales for gigafactory deployments, regional distributors for portable field units, and specialized calibration service networks for recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-tier test lab access models, as EU battery passport mandates and India's PLI scheme simultaneously expand compliance-driven demand while splintering procurement authority across emerging cell production corridors.
For Market Incumbents: Pre-empt displacement by impedance spectroscopy specialists through embedded traceability software integration and cryptographic data signing capabilities. Consolidate position via backward integration into precision sensor production or captive calibration service networks in South Korea and Germany. Defend against Asian manufacturing-scale automation suppliers by locking automotive OEM qualification protocols.
For New Entrants and Emerging Players: Establish a beachhead in India's emerging ACC gigafactory corridor before BIS certification requirements formalize, targeting analyzer deployment for Gujarat and Tamil Nadu production lines. White-space concentrates in AI-driven predictive maintenance convergence for telecom backup power installations across Southeast Asia. Go-to-market leverage: subscription-based equipment access for mid-tier maintenance providers previously excluded from high-end impedance analyzer procurement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because battery passport mandates and circular economy documentation requirements are embedding analyzers irreversibly into cell supply chains. Target acquisition archetype: precision measurement heritage houses with impedance spectroscopy IP and established automotive OEM relationships. Signal to watch: which jurisdiction's test protocol gains adoption in cross-border supply contracts between European and Asian cell producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Traceability Software Integration | Cryptographic data signing capabilities satisfy ECHA audit requirements under EU Green Deal mandates. |
| Calibration Service Network Expansion | Busan and Delhi-Mumbai hubs anchor regional equipment leasing and recertification operations. |
| Backward Integration into Precision Sensors | In-house ADC production mitigates single-source fragility from Taiwanese foundry concentration. |
| AI-Driven Predictive Maintenance Platform | Machine learning algorithms trained on analyzer output enable telecom cell replacement forecasting. |
| Geographic Manufacturing Footprint in India | Gujarat and Tamil Nadu deployment captures PLI scheme-driven virgin demand from ACC plants. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrochemical test engineers at cell producers, calibration service technicians, automotive OEM qualification managers, and impedance spectroscopy R&D directors. Secondary validation drew from MIIT circular economy regulation filings, ECHA REACH documentation standards, EPA hazardous waste processing rules, and SEC disclosures from precision instrument manufacturers. Bottom-up demand modeling from gigafactory deployment schedules and top-down market sizing from equipment import data were triangulated for cross-verification.
Calibration against historical analyzer procurement cycles and capacity expansion announcements from Jiangsu and Guangdong cell producers anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type stratification, technology protocol maturity, automotive versus industrial application intensity, and end-user procurement modality. CAGRs were derived from equipment shipment trajectories and production-linked incentive implementation timelines. Industry-specific inputs incorporated EU battery passport enforcement schedules and solid-state battery R&D program funding flows.
Sensitivities concentrate around solid-state battery commercialization timelines and cobalt supply disruption severity from DRC extraction operations. Forecasts reflect documented assumptions regarding regulatory adoption rates and automotive OEM qualification protocol standardization. Material shifts in ceramic electrolyte characterization capability or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
NIR and Raman Spectroscopy Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Vector Network Analyzer Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Global Mercury Analyzer Market
Analytical Instruments
Microfluidics Market