
 Global Particle Counters Market | 2026-2036
Global Particle Counters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Particle Counters Market Foresight
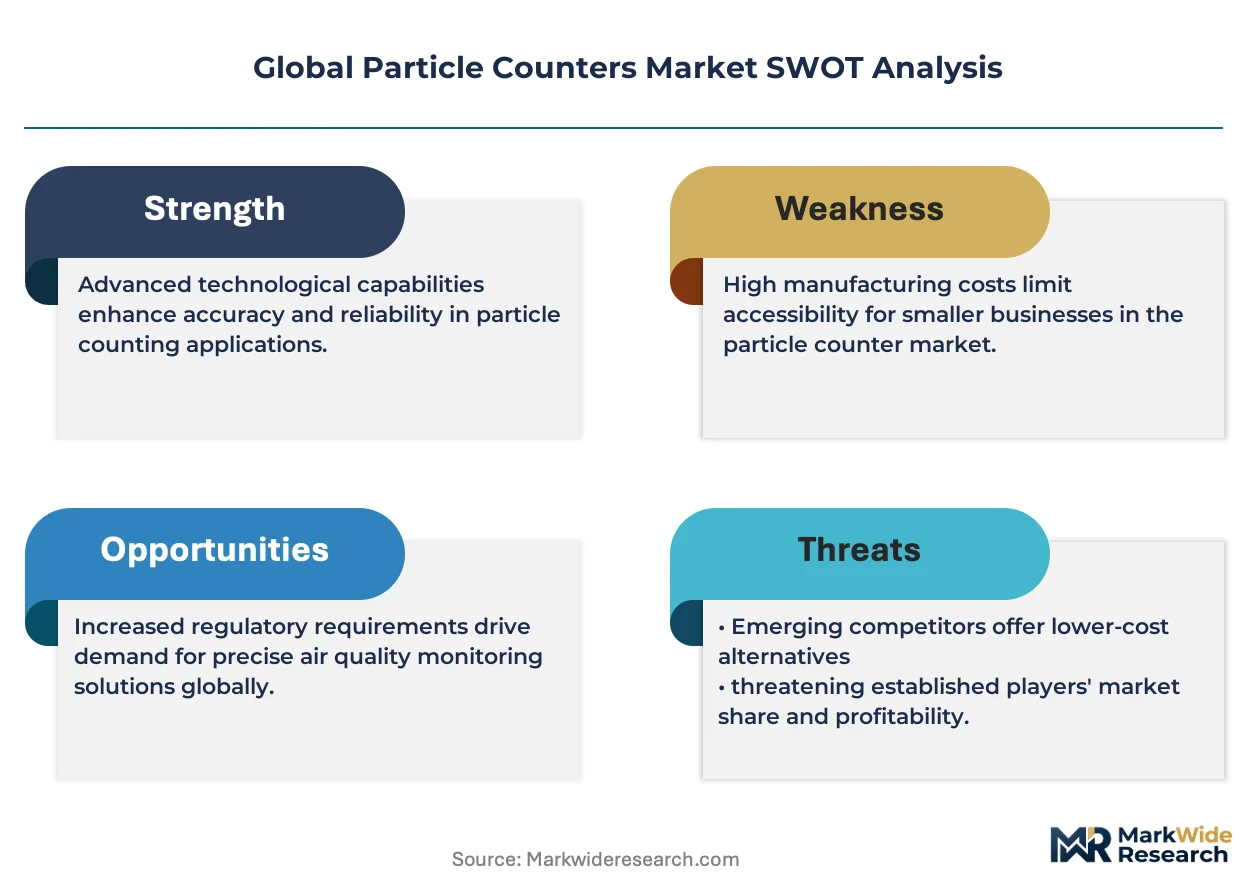
Buyer concentration among semiconductor manufacturers is restructuring procurement patterns across the particle counters landscape. TSI Inc. leverages its optical sensor expertise to anchor North American supply relationships. Lighthouse Worldwide Solutions competes through channel control in Asian cleanroom markets. Beckman Coulter sustains brand strength in pharmaceutical validation segments.
Particle counters are instruments that detect and quantify airborne particulate matter using light scattering, optical, or electrical sensing technologies, typically resolving particles from 0.1 to 10.0 micrometers to certify air quality in controlled environments. Their primary purpose is to validate ISO cleanroom classifications and ensure contamination limits in sterile manufacturing. Portable units lead in field service flexibility while online monitoring systems capture the fastest-growing margin pool through continuous validation contracts. Handheld devices serve mature spot-check applications in food processing plants where mobility outweighs precision requirements.
FDA sterility guidelines and EU MDR framework mandate continuous environmental monitoring in aseptic processing, directly expanding installed bases for fixed and online systems. Japan's PMDA and South Korea's MFDS enforce harmonized cleanroom standards that drive cross-border equipment certification demands. China's NMPA accelerates domestic substitution programs for pharmaceutical quality instruments. Stakeholders must monitor regulatory divergence between FDA's Annex 1 alignment and emerging Asian bioequivalence protocols.
Market Dynamics
Cleanroom verification intensity in semiconductor fabrication is compressing particle counter replacement cycles as Taiwan and South Korea fabs tighten sub-micron contamination protocols ahead of EU MDR sterility deadlines.
Growth Catalysts
- EU MDR Annex 1 alignment:FDA sterility guidelines now mandate continuous environmental monitoring in aseptic processing, expanding installed bases for fixed and online systems across pharmaceutical manufacturing.
- Semiconductor yield sensitivity:Sub-7nm node production in Hsinchu and Pyeongtaek clusters demands real-time particle detection at 0.1-micron resolution, pulling portable and handheld units into field service rotations.
- Optical sensor miniaturization:Solid-state laser diodes and CMOS detector arrays are shrinking unit footprints while maintaining ISO 14644-1 certification accuracy, enabling ceiling-mount distributed sensor networks.
Market Restraints
- High-purity sensor supply concentration:Photomultiplier tubes and specialized optical filters concentrate in Japanese and German component suppliers, exposing lead times to single-source vulnerabilities.
- Calibration infrastructure scarcity:NIST-traceable calibration facilities cluster in North America and Western Europe, forcing Asian end-users to absorb shipping costs and extended downtime for certification maintenance.
- Optical interferometry substitution:Condensation particle counters and scanning mobility particle sizers capture ultrafine detection applications below 0.1 microns, eroding traditional light-scattering instrument relevance in nanomaterial research.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO enforcement of Schedule M compliance and PLI scheme incentives for active pharmaceutical ingredient production create first-time installed base opportunities in Hyderabad and Ahmedabad clusters.
- Cell and gene therapy cleanrooms:ATMP manufacturing suites require ISO 5-7 continuous monitoring with 21 CFR Part 11 data integrity, opening validation service contracts for integrated environmental monitoring systems.
- Cloud-native monitoring platforms:Edge-computing particle counters with MQTT protocol connectivity bypass traditional SCADA integration, allowing direct SaaS subscription models that displace capital-heavy hardware procurement.
Industry Challenges
- Metrology technician scarcity:ISO 14644-3 cleanroom testing certification programs lag demand in Southeast Asian electronics hubs, constraining commissioning and re-qualification throughput.
- Legacy building management system integration:BACnet and Modbus protocol fragmentation across pharmaceutical facilities complicates unified environmental monitoring dashboard deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Particle Counters Market |
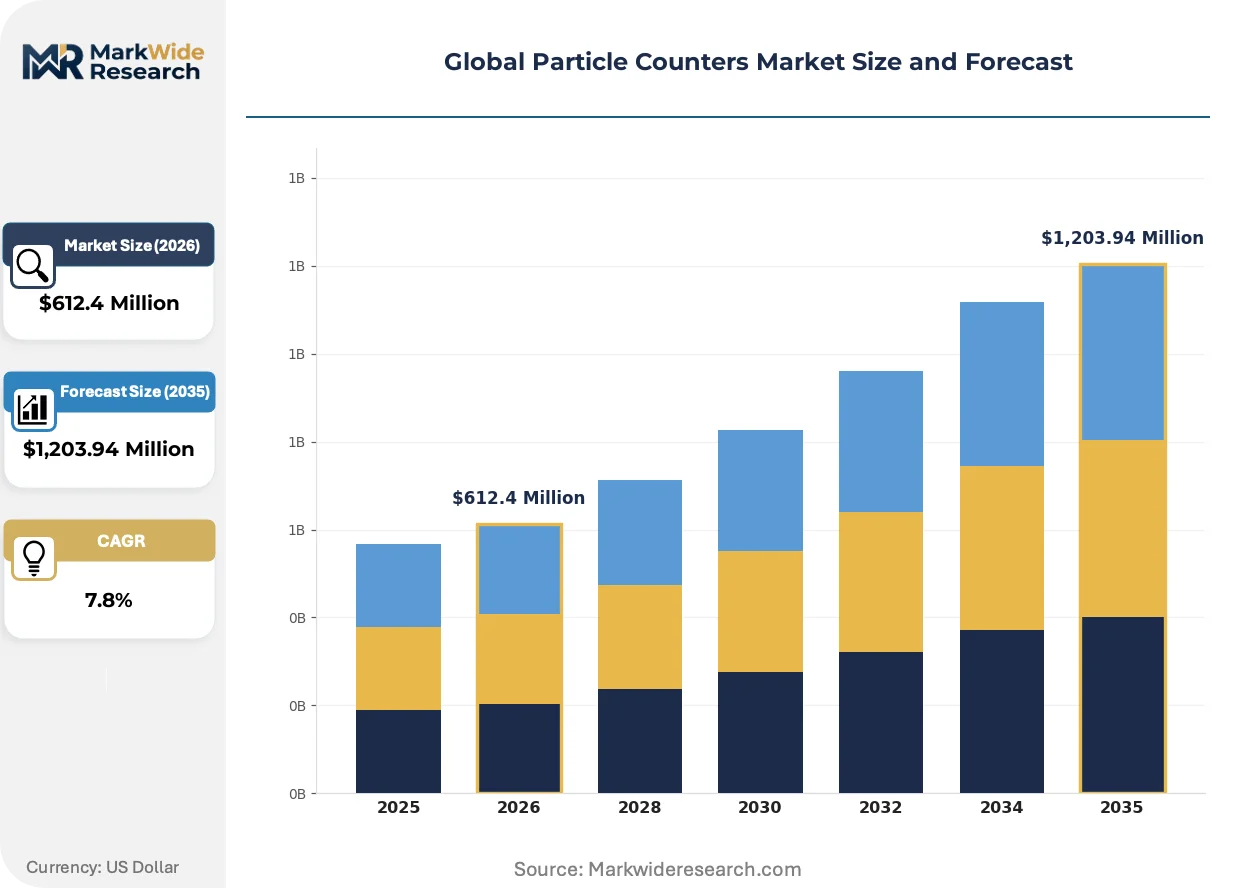
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Handheld, Online Monitoring Technology: Light Scattering, Magnetic Detection, Optical, Acoustic, Electrical Sensing Application: Pharmaceutical Manufacturing, Electronics Assembly, Aerospace Component Testing, Cleanroom Monitoring, Food & Beverage Quality End User: Biotech Firms, Semiconductor Manufacturers, Aircraft OEMs, Food Processing Plants |
| Companies Covered | Particle Measuring Systems, TSI Inc., Lighthouse Worldwide Solutions, RION Co., Ltd., Beckman Coulter, Spectris Plc, Danaher Corporation, Climet Instruments Company, Met One Instruments, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Particle Counters Market Shifts & Advancements
Real-time contamination intelligence is displacing periodic manual sampling as semiconductor and pharmaceutical buyers prioritize yield protection over capital equipment minimization.
Laser-induced breakdown spectroscopy is converging with traditional light-scattering architectures to enable simultaneous particle counting and elemental composition analysis. Battery manufacturers in South Korea and Japan are piloting these hybrid instruments for lithium-ion dry room monitoring. The technology is converging with existing optical platforms to create premium-tier instruments that command service contract attachment rates above standard portable units.
China's NMPA is accelerating domestic substitution mandates for pharmaceutical quality instruments through revised Good Manufacturing Practice annexes. Foreign manufacturers must now establish local calibration centers and Mandarin-language technical support to maintain hospital and vaccine facility access. Domestic suppliers in Suzhou and Beijing are capturing mid-tier accounts through accelerated regulatory approval timelines.
Service unbundling is fragmenting traditional capital-plus-maintenance contracts into discrete validation, calibration, and software subscription components. Pharmaceutical quality assurance departments in Germany and Switzerland are sourcing these elements from specialized third-party metrology providers rather than original equipment manufacturers. This behavior concentrates in facilities with existing in-house cleanroom certification capabilities that no longer require turnkey vendor support.
Global Particle Counters Market Segmentation
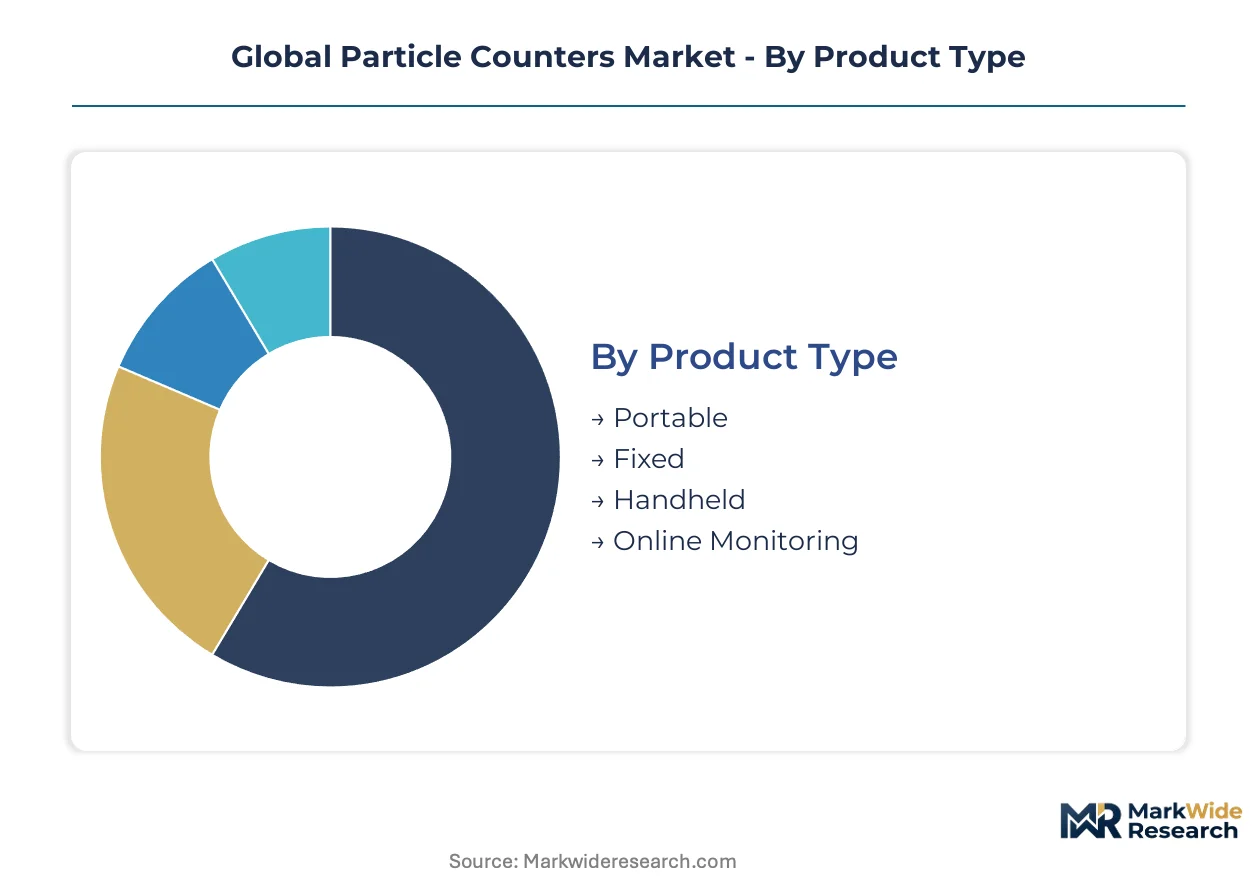
Particle counter procurement diverges sharply between integrated facility-wide systems and standalone verification tools. Semiconductor fabs in Taiwan and pharmaceutical suites in Germany source different form factors based on contamination risk tolerance and regulatory audit frequency.
Product Type:
Integration depth separates portable field units from ceiling-mounted distributed networks in cleanroom architectures.
- Portable:Battery-operated units with 0.3-10.0 micron detection ranges rotate through semiconductor fabs in Hsinchu for spot qualification between production campaigns. South Korean battery manufacturers deploy these for dry room certification where mobility outweighs continuous monitoring requirements.
- Fixed:Permanently installed sensors with Ethernet backbones anchor pharmaceutical filling lines in Basel and Singapore under FDA Annex 1 continuous monitoring mandates. These systems command premium service contracts through 21 CFR Part 11 data integrity validation.
- Handheld:Compact devices serve food processing plants in Chicago and Rotterdam where ISO 8 spot checks satisfy HACCP documentation without capital-intensive infrastructure.
- Online Monitoring:Edge-computing nodes with MQTT protocol connectivity bypass traditional SCADA layers, enabling SaaS subscription models that displace hardware-heavy procurement in mid-tier Indian pharmaceutical clusters.
Portable units lead volumes today; online monitoring is gaining share fastest.
Technology:
Detection physics determines resolution thresholds and maintenance complexity across semiconductor and pharmaceutical use cases.
- Light Scattering:Laser diode architectures with CMOS detector arrays dominate ISO 14644-1 certification applications. Japanese photomultiplier tube suppliers constrain component availability for sub-0.1 micron resolution instruments.
- Optical:Solid-state platforms with distributed sensor networks shrink unit footprints while maintaining classification accuracy. Swiss pharmaceutical manufacturers favor these for ATMP cleanroom suites requiring redundant validation paths.
- Magnetic Detection:Ferrous particle specificity serves aerospace hydraulic fluid testing in Toulouse and Wichita where metallic contamination threatens actuator performance.
- Acoustic:Particle sizing through ultrasonic attenuation captures liquid-borne applications in bioreactor sampling where optical methods face interference from media opacity.
- Electrical Sensing:Coulter principle instruments quantify conductive fluid contamination in battery electrolyte quality control for South Korean cell manufacturers.
Light scattering dominates current installed base; optical platforms are expanding most quickly through miniaturization gains.
Application:
Regulatory stringency tiers separate life science validation from industrial quality assurance budgets.
- Pharmaceutical Manufacturing:Aseptic filling lines under EU MDR Annex 1 mandate continuous environmental monitoring with alarm thresholds tied to batch release protocols. German and Swiss facilities drive replacement cycles for legacy portable units with integrated building management systems.
- Cleanroom Monitoring:ISO classification verification spans semiconductor fabrication in Pyeongtaek and gene therapy suites in Boston. NIST-traceable calibration requirements concentrate service revenue in North American and Western European metrology providers.
- Electronics Assembly:Surface mount operations in Shenzhen and Penang deploy handheld units for pre-shift qualification where particle loads fluctuate with seasonal humidity.
- Aerospace Component Testing:Fuel system cleanliness per AS4059 standards drives demand in Toulouse and Seattle for magnetic detection instruments with particle morphology reporting.
- Food & Beverage Quality:HACCP compliance in dairy and beverage plants favors economical spot-check protocols over continuous monitoring infrastructure.
Pharmaceutical manufacturing commands the highest unit margins; cleanroom monitoring shows the steepest expansion trajectory through semiconductor capacity additions.
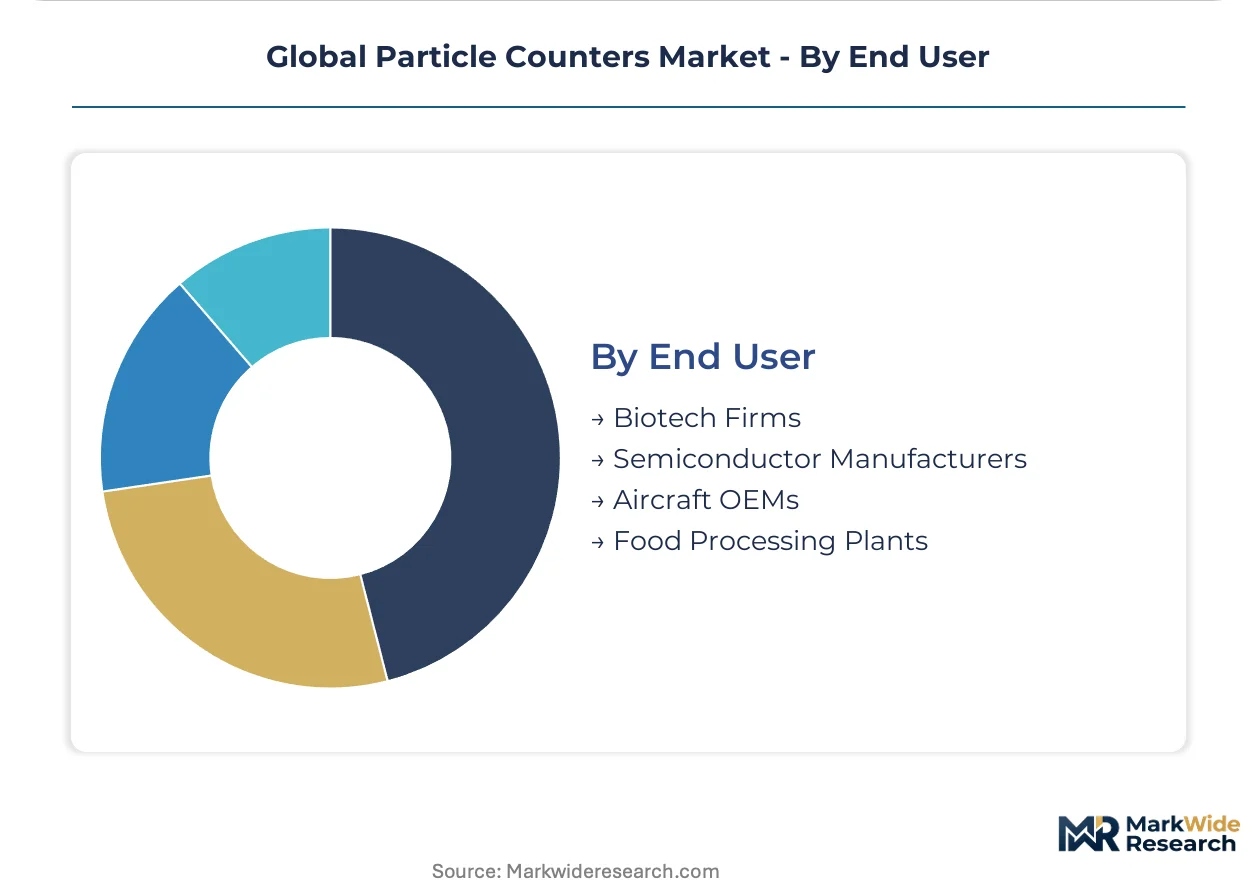
End User:
Buyer sophistication and in-house metrology capability determine service contract attachment rates and replacement frequency.
- Semiconductor Manufacturers:Sub-7nm node production in Taiwan and South Korea compresses replacement cycles as yield sensitivity tightens contamination protocols. These buyers demand 0.1-micron resolution with real-time data integration into manufacturing execution systems.
- Biotech Firms:Cell and gene therapy manufacturers in Boston and Basel require ISO 5-7 continuous monitoring with audit-ready documentation trails. ATMP facility construction is pulling integrated environmental monitoring system demand.
- Aircraft OEMs:Hydraulic and fuel system testing in Wichita and Hamburg sources specialized magnetic detection for metallic particle quantification per SAE cleanliness standards.
- Food Processing Plants:Mature spot-check applications in Chicago and São Paulo prioritize capital minimization over precision, sustaining handheld device demand with extended replacement horizons.
Semiconductor manufacturers anchor volume demand; biotech firms are climbing the fastest through ATMP facility construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and the United States operate on divergent particle counter procurement rhythms, with Beijing prioritizing domestic substitution while American fabs emphasize yield protection through premium instrumentation.
United States
FDA sterility guidelines and Annex 1 alignment mandate continuous environmental monitoring across aseptic processing facilities. Boston and Research Triangle Park biotech clusters drive demand for ISO 5-7 validation systems with 21 CFR Part 11 data integrity. Semiconductor fabs in Arizona and Texas compress replacement cycles for sub-7nm contamination protocols.
Germany
EU MDR enforcement tightens cleanroom verification requirements for pharmaceutical manufacturers in Basel-adjacent Baden-Württemberg and Bavarian vaccine facilities. EMA harmonization with FDA Annex 1 standards accelerates fixed system installations. Stuttgart and Munich industrial zones anchor metrology service contract concentration.
China
NMPA domestic substitution mandates reshape procurement for pharmaceutical quality instruments through revised GMP annexes. Suzhou and Beijing suppliers capture mid-tier accounts with accelerated regulatory timelines. Yangtze River Delta semiconductor fabs expand 0.1-micron resolution deployments for advanced node production.
South Korea
MFDS cleanroom standards enforcement drives cross-border equipment certification demands for Seoul Capital Area biopharma suites. Pyeongtaek and Busan-Ulsan battery dry rooms pilot hybrid detection instruments for lithium-ion contamination control. Domestic fabs tighten sub-micron protocols ahead of EU MDR sterility deadlines.
India
CDSCO Schedule M compliance enforcement and PLI scheme incentives for active pharmaceutical ingredient production create first-time installed base opportunities. Hyderabad and Ahmedabad pharmaceutical clusters source portable units for field qualification. NIST-traceable calibration infrastructure scarcity forces extended downtime absorption for certification maintenance.
Global Particle Counters Market Competitive Landscape
North American producers anchor the premium instrumentation tier; East Asian specialists hold channel control in cleanroom-dense electronics hubs. Market structure concentrates around three strategic archetypes: optical sensor technology owners, distributed network integrators, and validation service bundlers. Capacity expansion and strategic partnerships dominate competitive moves as fabs demand localized calibration infrastructure.
Within the technology-owner tier, TSI Inc. and Beckman Coulter exemplify instrument manufacturers leveraging sensing expertise to anchor supply relationships. Lighthouse Worldwide Solutions occupies a position representing channel-focused specialists competing through geographic proximity to Asian cleanroom markets. These three entities collectively illustrate how procurement patterns restructure around buyer concentration among semiconductor and pharmaceutical end-users.
| Leading Market Players |
|---|
| Particle Measuring Systems |
| TSI Inc. |
| Lighthouse Worldwide Solutions |
| RION Co., Ltd. |
| Beckman Coulter |
| Spectris Plc |
| Danaher Corporation |
| Climet Instruments Company |
| Met One Instruments, Inc. |
| Others |
Supply & Pricing Matrix
Semiconductor manufacturers in Taiwan and South Korea demanding 0.1-micron resolution certification are compressing supplier lead times and forcing component localization investments that reshape cost structures across tiers.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for mid-tier portable units as domestic suppliers capture pharmaceutical accounts with accelerated regulatory timelines. Three-tier pricing structure across premium, standard, and economy levels separates 21 CFR Part 11-validated fixed systems from basic handheld spot-check devices. Cost compression in the standard tier is intensifying because NMPA domestic substitution mandates erode foreign brand premiums. Food processing plants in Brazil and Mexico exhibit highest price sensitivity, while ATMP cleanroom builders in Basel and Boston absorb premium positioning for continuous monitoring architectures.
Supply Chain Analysis
ISO 17025 calibration accreditation requirements gate market access and tether component sourcing to NIST-traceable metrology infrastructure concentrated in the United States, Germany, and Japan. Photomultiplier tubes from Hamamatsu suppliers, specialized optical filters from German coating houses, and solid-state laser diodes from Japanese foundries constitute critical input dependencies. Single-source vulnerability in photodetector supply exposes lead times to disruption from semiconductor equipment allocation priorities. Distribution runs through authorized metrology service partners in cleanroom-dense clusters rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on optical sensor miniaturization reducing bill-of-materials costs while ATMP facility construction pulls premium-tier system demand.
For Market Incumbents: Lock in calibration infrastructure ownership in Asian electronics hubs before NMPA domestic substitution mandates harden. Establish captive service centers in Hsinchu and Pyeongtaek to compress commissioning cycles for semiconductor fabs. Deepen backward integration into CMOS detector arrays to offset Japanese photomultiplier tube supply concentration. For New Entrants and Emerging Players: EU MDR Annex 1 alignment in Germany opens a window for cloud-native monitoring platforms with SaaS pricing that undercuts capital-heavy incumbents. Target mid-tier Indian pharmaceutical clusters in Hyderabad where CDSCO Schedule M enforcement creates first-time installed base demand without legacy SCADA integration burdens. Lead with MQTT protocol connectivity and Mandarin-language technical support to bypass traditional building management system fragmentation. For Investors and Strategic Acquirers: Asymmetric upside sits with distributed sensor network integrators possessing edge-computing firmware capabilities and regional calibration accreditation. The five-to-ten year viability window favors acquisition targets with pharmaceutical validation service contracts rather than pure hardware manufacturers. Watch for inflection when semiconductor fabs in Arizona and Texas announce sub-7nm node production timelines requiring real-time contamination intelligence.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Localization | NIST-traceable centers in Taiwan and South Korea reduce Asian fab downtime from certification maintenance. |
| Cloud-Native Platform Development | MQTT protocol connectivity enables SaaS subscription models displacing capital-heavy hardware procurement in Indian pharmaceutical clusters. |
| Optical Sensor Miniaturization | CMOS detector arrays shrink unit footprints while maintaining ISO 14644-1 accuracy for ceiling-mount distributed networks. |
| Regulatory Certification Fast-Tracking | Accelerated NMPA approval timelines allow domestic Chinese suppliers to capture mid-tier hospital and vaccine facility accounts. |
| Service Contract Unbundling | Discrete validation and software subscription components concentrate revenue with specialized third-party metrology providers in Germany and Switzerland. |
Research Methodology
Multiple input streams — cleanroom certification body filings, semiconductor fab capital expenditure disclosures, and pharmaceutical regulatory enforcement records — were reconciled against primary interviews with metrology service heads, pharmaceutical quality assurance directors, and semiconductor facility engineers. Secondary validation drew from FDA 483 inspection observations, EMA GMP deficiency reports, MFDS medical device registration databases, and ISO 14644-1 certification audit logs. Bottom-up unit demand estimates across portable, fixed, handheld, and online monitoring form factors were triangulated with top-down market value reconstruction.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling particle counter demand by product type, detection technology, application vertical, and end-user sophistication tier. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory mandate timing. Forecast inputs incorporated semiconductor node transition schedules and ATMP facility construction pipelines without year-specific anchoring.
Revisions become necessary when NMPA domestic substitution mandates accelerate beyond current implementation trajectories or when photomultiplier tube supply concentration triggers allocation restrictions from Japanese component suppliers. A model refresh is warranted upon material change in FDA-EU MDR regulatory harmonization timelines affecting continuous monitoring mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Spectrum and Signal Analyzers Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Spectrophotometers Market
Analytical Instruments
Dissolved Gas Analyzer Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Global IR Spectroscopy Market