
 Global Theater Linen Market | 2026-2036
Global Theater Linen Market Size, Share, and Industry Trends Forecast 2026-2036
Global Theater Linen Market Foresight
Multi-source outsourcing is recalibrating how hospital systems procure theater linen across North America and Western Europe. ImageFIRST Healthcare Laundry Specialists leverages its dedicated healthcare infrastructure to sustain infection-control compliance across large integrated delivery networks. Medline Industries anchors its position through direct-to-facility distribution that competes with traditional rental models. Aramark Corporation differentiates via comprehensive facility management contracts that embed linen services within broader operating-room support packages.
Theater linen encompasses reusable and disposable textile products engineered for surgical environments, typically constructed from cotton-polyester blends or advanced microfiber substrates meeting AAMI PB70 liquid-barrier standards, designed to maintain sterile fields and manage fluid control during operative procedures. Surgical drapes and gowns occupy the largest volume share within product-type segmentation, while microfiber and blended-fabric materials are gaining fastest due to superior durability and lower per-use lifecycle costs. Hospitals dominate end-user demand, though surgical centers represent the most rapidly expanding channel as outpatient procedure volumes shift away from inpatient settings.
FDA enforcement of AAMI PB70 barrier classifications and EPA oversight of industrial laundry effluent directly shape product specifications and service-provider compliance burdens for theater linen sold or processed in the United States. The EU Medical Device Regulation and REACH chemical restrictions impose parallel conformity requirements on European market participants, elevating testing and documentation costs. Stakeholders must monitor evolving reusable-textile sterilization validation protocols and assess whether regional regulatory divergence will fragment supply chains or consolidate procurement toward multi-continent service platforms.
Market Dynamics
Hospital consolidation across the United States is compressing vendor relationships into centralized procurement frameworks that favor multi-service contracts over standalone linen rental agreements.
Growth Catalysts
- AAMI PB70 Barrier Mandates:FDA enforcement of liquid-barrier classifications for surgical drapes and gowns is forcing replacement cycles for non-compliant inventory across US acute-care facilities.
- Outpatient Migration:Ambulatory surgical centers in Germany and France are expanding procedure volumes beyond traditional hospital settings, generating parallel demand streams for specialized theater linen.
- Microfiber Substrate Advances:Blended-fabric materials with superior durability and lower per-use lifecycle costs are displacing cotton-polyester standards in high-throughput operating rooms.
Market Restraints
- Cotton Price Volatility:Raw cotton futures fluctuation directly compresses margins for reusable textile processors dependent on natural fiber inputs.
- EU REACH Compliance Burden:Chemical restriction documentation requirements elevate testing costs for European theater linen manufacturers seeking CE marking under MDR.
- Single-Use Substitution Pressure:Disposable surgical packs from integrated medical device suppliers threaten reusable linen rental models in cost-sensitive procurement environments.
Strategic Opportunities
- Indian ASC Expansion:Private surgical center chains in Mumbai and Delhi represent underpenetrated demand for outsourced linen management services.
- EPA Effluent Incentives:Industrial laundry operators investing in water-recovery systems qualify for environmental compliance credits in California and Texas regulatory jurisdictions.
- RFID-Enabled Inventory Tracking:Convergence of radio-frequency identification with cloud-based asset management is opening subscription-based linen monitoring services for mid-sized hospital networks.
Industry Challenges
- Sterilization Validation Expertise Gap:Reusable textile processors face acute shortages of technicians qualified to execute AAMI ST65 steam-sterilization validation protocols.
- Legacy ERP Integration Friction:Hospital supply chain systems require costly middleware development to connect with third-party linen service billing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Theater Linen Market |
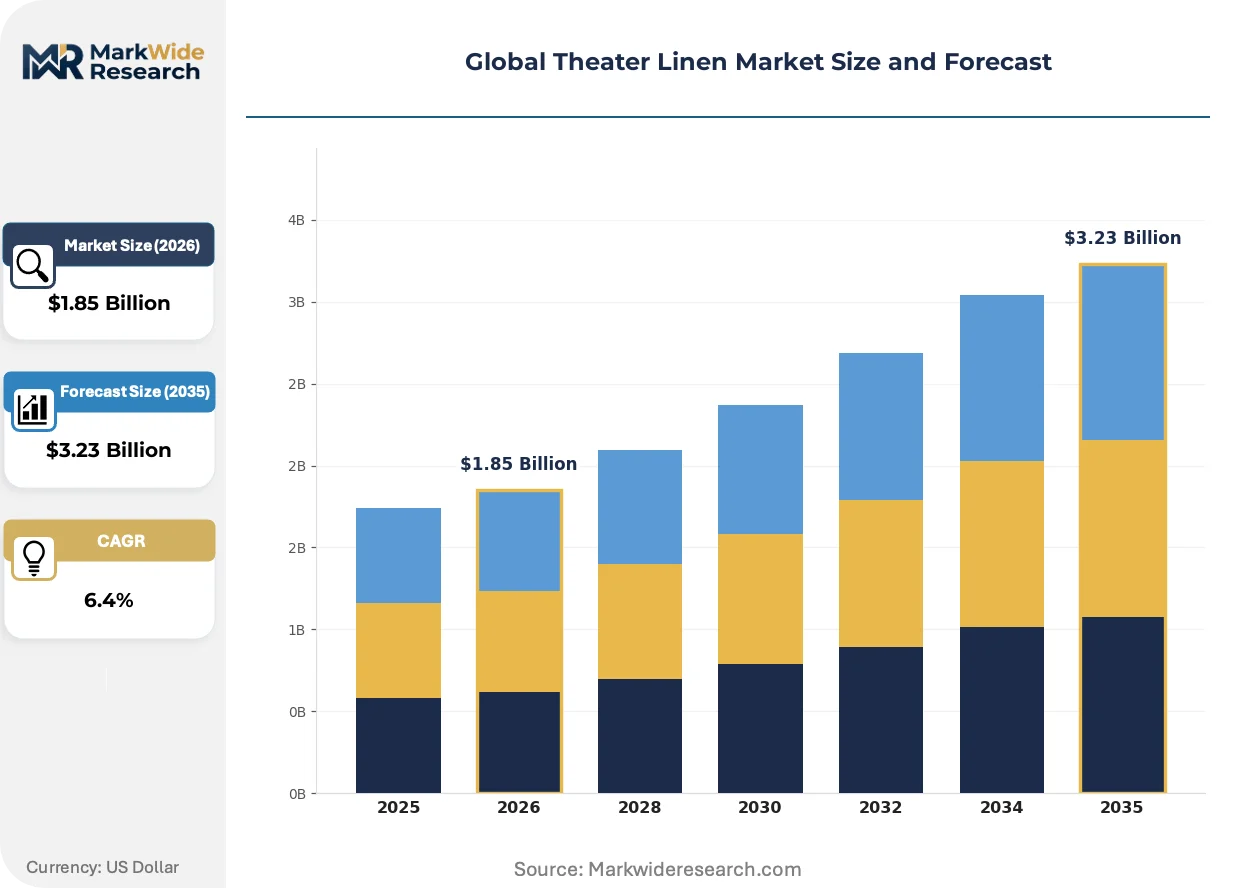
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drapes, Towels, Sheets, Gowns, Curtains, Tablecloths Material: Cotton, Polyester, Blended Fabrics, Silk, Microfiber, Linen End User: Hospitals, Surgical Centers, Diagnostic Clinics, Research Labs Application: Preoperative, Intraoperative, Postoperative, Anesthesia Procedures, Sterile Draping, Patient Care |
| Companies Covered | ImageFIRST Healthcare Laundry Specialists, Medline Industries, Angelica Corporation, Aramark Corporation, Alsco, AmeriPride Services, Crothall Healthcare, Unitex Textile Rental Services, Synergy Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Theater Linen Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while reshaping how surgical textiles are specified, validated, and procured across institutional buyers.
Antimicrobial-finished microfiber substrates is unifying fluid management and infection-control functions into single-layer surgical drapes, eliminating separate reinforcement zones. Integrated delivery networks in Texas and Ohio are piloting these consolidated designs to reduce gown-change frequency during lengthy orthopedic procedures. The technology is unifying previously segmented product categories into standardized SKUs that simplify centralized procurement.
EU Medical Device Regulation implementation timelines are forcing European theater linen manufacturers to revalidate entire product portfolios under new conformity assessment procedures. Industrial laundries serving French and German hospital systems must now maintain technical documentation previously required only of device manufacturers. Surgical gown suppliers in Italy and Spain are responding by consolidating testing partnerships with notified bodies to accelerate CE certificate renewals.
Subscription-based linen utilization models are displacing per-piece rental billing across US ambulatory surgery centers. Flat-rate monthly fees covering unlimited gown and drape exchanges appeal to cash-flow-sensitive outpatient facilities in Florida and Arizona. This shift is most visible in ophthalmology and endoscopy suites where procedure volume predictability supports fixed-cost service structures.
Global Theater Linen Market Segmentation
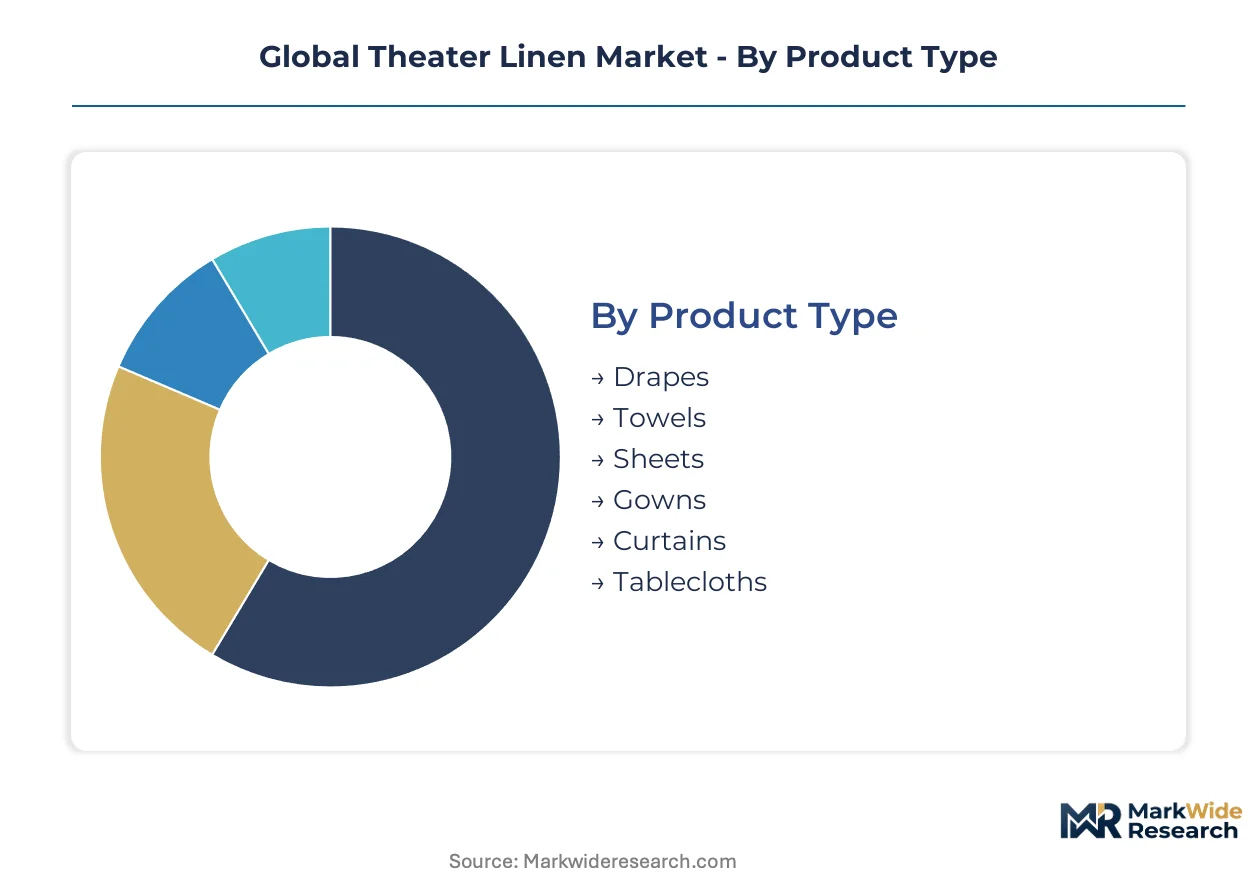
Theater linen procurement patterns fragment sharply across product categories and institutional settings, with supply concentration in reusable surgical textiles creating procurement leverage points distinct from disposable alternatives. Material specifications and end-use environments dictate validation protocols, pricing structures, and service-provider selection criteria that resist standardization.
Product Type:
Supply concentration in surgical drapes and gowns dominates manufacturing capacity allocation, with specialized processors maintaining dedicated barrier-testing infrastructure for AAMI PB70 compliance.
- Drapes:Multi-layer barrier fabrics with reinforced zones for fluid control anchor procurement volumes in US hospital systems consolidating around standardized sterile field configurations. Demand concentrates in orthopedic and cardiovascular suites where procedure length intensifies fluid exposure risks.
- Gowns:AAMI Level 3 and Level 4 surgical gowns with sealed seams and knit cuffs absorb the majority of infection-control compliance spending across integrated delivery networks. Texas and Ohio health systems are piloting antimicrobial-finished microfiber variants to reduce change frequency during lengthy procedures.
- Towels:Absorbent cotton-polyester blends for general operative field management.
- Sheets:Flat and fitted designs for patient positioning and transport.
- Curtains:Privacy and contamination barriers for perioperative zones.
- Tablecloths:Protective covers for equipment and instrument staging surfaces.
Drapes absorb the bulk of installed capacity; gowns are expanding most quickly.
Material:
Cost tier differentiation separates commodity natural fibers from engineered synthetics requiring capital-intensive substrate development and sterilization validation.
- Microfiber:Advanced synthetic substrates with superior durability and lower per-use lifecycle costs are displacing cotton-polyester standards in high-throughput German and French operating rooms. Private surgical center chains in Mumbai and Delhi represent underpenetrated demand for these materials.
- Blended Fabrics:Cotton-polyester combinations balancing absorbency and durability maintain volume leadership in cost-sensitive procurement environments. US ambulatory surgery centers in Florida and Arizona favor these materials for subscription-based flat-rate service structures.
- Cotton:Natural fiber base material subject to raw futures price volatility.
- Polyester:Synthetic foundation for moisture-wicking and quick-dry properties.
- Silk:Premium natural fiber for specialized ophthalmic and microsurgical applications.
- Linen:Traditional woven material with limited contemporary surgical adoption.
Blended fabrics retain the greatest installed base; microfiber is climbing the fastest.
End User:
Customer type determines service model viability, with centralized procurement frameworks in consolidated hospital systems contrasting against cash-flow-sensitive outpatient facilities.
- Hospitals:Acute-care facilities with centralized sterile processing departments drive standardized theater linen portfolios across multi-hospital networks. US hospital consolidation is compressing vendor relationships into multi-service contracts favoring outsourced linen management.
- Surgical Centers:Ambulatory facilities specializing in outpatient procedures represent the steepest expansion trajectory as volumes shift away from inpatient settings. German and French ASCs are expanding outsourced linen management programs alongside procedure volume growth.
- Diagnostic Clinics:Imaging and interventional facilities with limited sterile processing infrastructure.
- Research Labs:Preclinical and clinical trial settings with specialized contamination control requirements.
Hospitals command the greatest procurement volume; surgical centers are gaining share fastest.
Application:
Procedure phase dictates barrier performance requirements and replacement frequency, with intraoperative applications demanding the most stringent validation protocols.
- Intraoperative:Sterile field maintenance during active surgical procedures requires AAMI PB70 Level 3-4 barrier performance with documented steam-sterilization validation under ST65 protocols. FDA enforcement is forcing replacement cycles for non-compliant inventory across US acute-care facilities.
- Sterile Draping:Field isolation and fluid containment functions are unifying into single-layer designs eliminating separate reinforcement zones. Integrated delivery networks are consolidating previously segmented product categories into standardized SKUs.
- Preoperative:Patient preparation and positioning prior to incision.
- Postoperative:Recovery and wound management following procedure completion.
- Anesthesia Procedures:Sedation administration and airway management support.
- Patient Care:General comfort and hygiene in perioperative settings.
Intraoperative applications dominate capacity utilization; sterile draping is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cotton futures volatility in Texas and Louisiana directly shapes North American theater linen economics, while polyester feedstock concentration in Zhejiang and Jiangsu provinces anchors Asian supply chains for synthetic surgical textiles.
United States
Hospital consolidation across Texas and Ohio compresses vendor relationships into centralized procurement frameworks favoring multi-service contracts. FDA enforcement of AAMI PB70 barrier classifications forces replacement cycles for non-compliant surgical drape inventory. Dallas-Fort Worth health systems pilot antimicrobial-finished microfiber gowns to reduce change frequency during lengthy orthopedic procedures.
Germany
Ambulatory surgical centers in Bavaria and North Rhine-Westphalia expand outsourced linen management programs alongside outpatient procedure volume growth. EU Medical Device Regulation implementation forces revalidation of entire surgical textile portfolios under new conformity assessment procedures. Industrial laundries serving Stuttgart hospital clusters consolidate testing partnerships with notified bodies to accelerate CE certificate renewals.
France
Private surgical center chains in Île-de-France generate parallel demand streams for specialized theater linen as volumes shift from traditional hospital settings. REACH chemical restriction documentation requirements elevate testing costs for manufacturers seeking CE marking. Lyon-based textile processors maintain technical documentation previously required only of device manufacturers under tightened MDR oversight.
India
Private surgical center chains in Mumbai and Delhi represent underpenetrated demand for outsourced linen management services. CDSCO alignment with international barrier-performance standards elevates product specifications for imported surgical textiles. Bangalore hospital networks expand centralized sterile processing departments driving standardized theater linen portfolio procurement.
China
Microfiber substrate manufacturing clusters in Zhejiang and Jiangsu provinces supply advanced synthetic materials displacing cotton-polyester standards. NMPA medical device registration requirements shape sterilization validation protocols for reusable surgical textiles. Shanghai integrated delivery networks pilot RFID-enabled inventory tracking systems for cloud-based linen asset management.
Global Theater Linen Market Competitive Landscape
Global majors compete with regional champions across service-model dimensions, with dedicated healthcare laundry specialists, diversified facility management conglomerates, and direct-distribution medical suppliers occupying distinct competitive positions. Market structure tilts toward consolidation at the top tier while mid-scale regional operators retain share through specialized infection-control compliance expertise. Three archetypes dominate: vertically integrated rental-service platforms, direct-manufacturing distributors, and embedded facility-management contractors. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players seeking geographic density to amortize sterilization validation infrastructure costs.
Within the healthcare-specialist tier, ImageFIRST Healthcare Laundry Specialists and Angelica Corporation exemplify dedicated infrastructure models focused exclusively on infection-control compliance across integrated delivery networks. Medline Industries occupies a position as a direct-manufacturing distributor competing with traditional rental models through facility-direct supply chains. Aramark Corporation anchors the embedded-services archetype, representing comprehensive facility management contracts that integrate linen provision within broader operating-room support packages. These three patterns illustrate how competitive positioning fragments across service-model choices rather than product differentiation alone.
| Leading Market Players |
|---|
| ImageFIRST Healthcare Laundry Specialists |
| Medline Industries |
| Angelica Corporation |
| Aramark Corporation |
| Alsco |
| AmeriPride Services |
| Crothall Healthcare |
| Unitex Textile Rental Services |
| Synergy Health |
| Others |
Supply & Pricing Matrix
Cotton futures volatility in Texas and Louisiana transmits directly through blended-fabric processing costs to subscription-based service tiers for ambulatory surgical centers, while polyester feedstock pricing in Zhejiang province anchors synthetic microfiber economics for high-throughput operating rooms.
Pricing Analysis
Service-bundling separates rental models including sterilization validation and compliance documentation from unbundled per-piece procurement where hospitals assume processing liability. Three-tier pricing structure across premium antimicrobial-finished microfiber, standard cotton-polyester blends, and economy cotton grades reflects AAMI PB70 certification levels and volume scale. Pricing pressure stems from single-use disposable pack substitution in cost-sensitive ASC environments. Surgical centers in Florida and Arizona exhibit highest price sensitivity due to cash-flow constraints, while consolidated Texas health systems prioritize compliance over unit cost.
Supply Chain Analysis
Freight costs from Zhejiang and Jiangsu province microfiber manufacturing clusters to North American distribution hubs constitute a material share of landed synthetic substrate economics. Raw cotton sourcing concentrates in Texas, Louisiana, and India, while polyester feedstock draws from Chinese petrochemical complexes and South Korean synthetic fiber producers. Single-source vulnerability in steam-sterilization validation equipment creates chokepoint risk for reusable textile processors. Distribution runs through dedicated healthcare laundry networks with regional sterilization infrastructure rather than general textile rental channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital consolidation across the United States is compressing vendor relationships into centralized procurement frameworks that favor multi-service contracts, forcing standalone linen rental operators toward acquisition or exit.
For Market Incumbents: Cement infection-control compliance leadership through backward integration into sterilization validation infrastructure and capacity concentration in Texas and Ohio hospital network clusters. AAMI ST65 technician scarcity threatens service quality for competitors lacking captive training programs. Multi-service contract bundling with facility management operators represents the priority defensive lever against direct-distribution medical suppliers. For New Entrants and Emerging Players: EU Medical Device Regulation implementation in Germany and France opens a window for specialized testing partnership services that accelerate CE certificate renewals for mid-scale textile processors. Private surgical center chains in Mumbai and Delhi represent the most penetrable geography for outsourced linen management platforms. Subscription-based flat-rate pricing models targeting ophthalmology and endoscopy suites offer the strongest go-to-market angle against established rental incumbents. For Investors and Strategic Acquirers: FDA enforcement actions against non-AAMI PB70 compliant inventory are the leading indicator that sterilization validation expertise will concentrate among scaled operators with dedicated healthcare infrastructure. Long-term viability favors vertically integrated platforms with geographic density to amortize compliance costs across multi-hospital networks. Watch for industrial laundry operators investing in water-recovery systems qualifying for EPA environmental compliance credits as the signal of operational sophistication separating acquisition targets from distressed sellers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Sterilization Infrastructure | Dedicated healthcare laundry facilities in Texas and Ohio hospital network clusters capture consolidation-driven contract flows. |
| CE Marking Pathway Acceleration | Testing partnerships with notified bodies in Germany and France reduce revalidation timelines under EU Medical Device Regulation. |
| Hospital System Partnership | Integrated delivery network contracts in Dallas-Fort Worth and Cincinnati embed linen services within broader operating-room support. |
| RFID-Enabled Inventory Tracking Development | Cloud-based asset management subscriptions for mid-sized hospital networks differentiate service offerings from commodity rental. |
| EPA Environmental Compliance Investment | Water-recovery systems in California and Texas regulatory jurisdictions qualify for effluent credits and anchor sustainability positioning. |
Research Methodology
Independent corroboration across hospital supply chain executives, industrial laundry operations directors, and biomedical engineering leads underwrites the qualitative findings on sterilization validation protocols. Primary interviews with GPO contracts managers and sterile processing department heads combined with secondary validation against FDA 510(k) filings, EPA effluent compliance databases, and hospital procurement contract records established demand-side parameters. Bottom-up facility-level capacity assessments and top-down market sizing triangulated volume estimates across reusable and disposable product categories.
Comparable-period anchoring to historical AAMI PB70 adoption cycles and outpatient migration patterns shaped the projection horizon calibration. Segmentation modeling incorporated product type, material substrate, end-user facility category, and regional regulatory cluster dimensions. CAGRs derived from installed base replacement dynamics and procedure volume growth trajectories, with microfiber substrate penetration rates and ASC expansion velocity as theater linen-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for antimicrobial-finished microfiber consolidation into single-layer drape designs would alter the outlook for traditional multi-layer product categories. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and hospital consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Textiles
North America Home Textile Market
Home Textiles
India Home Textile Market
Home Textiles
Indonesia Home Textile Market
Home Textiles
Cotton Towel Market
Home Textiles
Baby Crib Sheet Market
Home Textiles
Wool Dryer Ball Market
Home Textiles
Asia-Pacific Home Textile Market
Home Textiles
GCC Home Textile Market
Home Textiles
Turkey Home Textile Market
Home Textiles
Microfiber Cleaning Cloth Market
Home Textiles
Canada Home Textile Market
Home Textiles
Linen Bed Sheets Market
Home Textiles
Blanket Market
Home Textiles
Bath Towel Market
Home Textiles
Towel Market
Home Textiles
Fabric Wash and Care Market