
 Middle East and Africa Aluminum Extrusion Market | 2026-2036
Middle East and Africa Aluminum Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aluminum Extrusion Market Intelligence
The adoption of modular building systems is recalibrating buyer preference for standardized extruded profiles across the Middle East and Africa. This shift favors suppliers who can deliver consistent, large-volume orders for major projects. Emirates Global Aluminium (EGA) leverages its vast primary aluminum production capacity to serve this segment. In contrast, Aluminium Products Company (ALUPCO) specializes in sophisticated architectural systems for landmark construction projects in Saudi Arabia.
Aluminum extrusion is a process where an aluminum alloy, typically from the 6000 series, is forced through a die to create a specific cross-sectional profile. This manufacturing technique produces lightweight, strong, and corrosion-resistant components for various applications. Structural sections for the construction sector represent the largest application segment by volume, driven by building and infrastructure development. The automotive application segment, while smaller, demands more complex profiles and surface finishes, offering higher value-add opportunities.
Regulatory frameworks established by bodies like the Saudi Standards, Metrology and Quality Organization (SASO) and the Emirates Authority for Standardization and Metrology (ESMA) govern product quality. These standards ensure extruded profiles meet safety and performance criteria for building materials. Consequently, extruders must align their production with regional green building certifications to maintain market access. Strategic decisions for market participants now revolve around balancing investments in high-specification capabilities against scaling for commodity-grade volume.
Market Dynamics
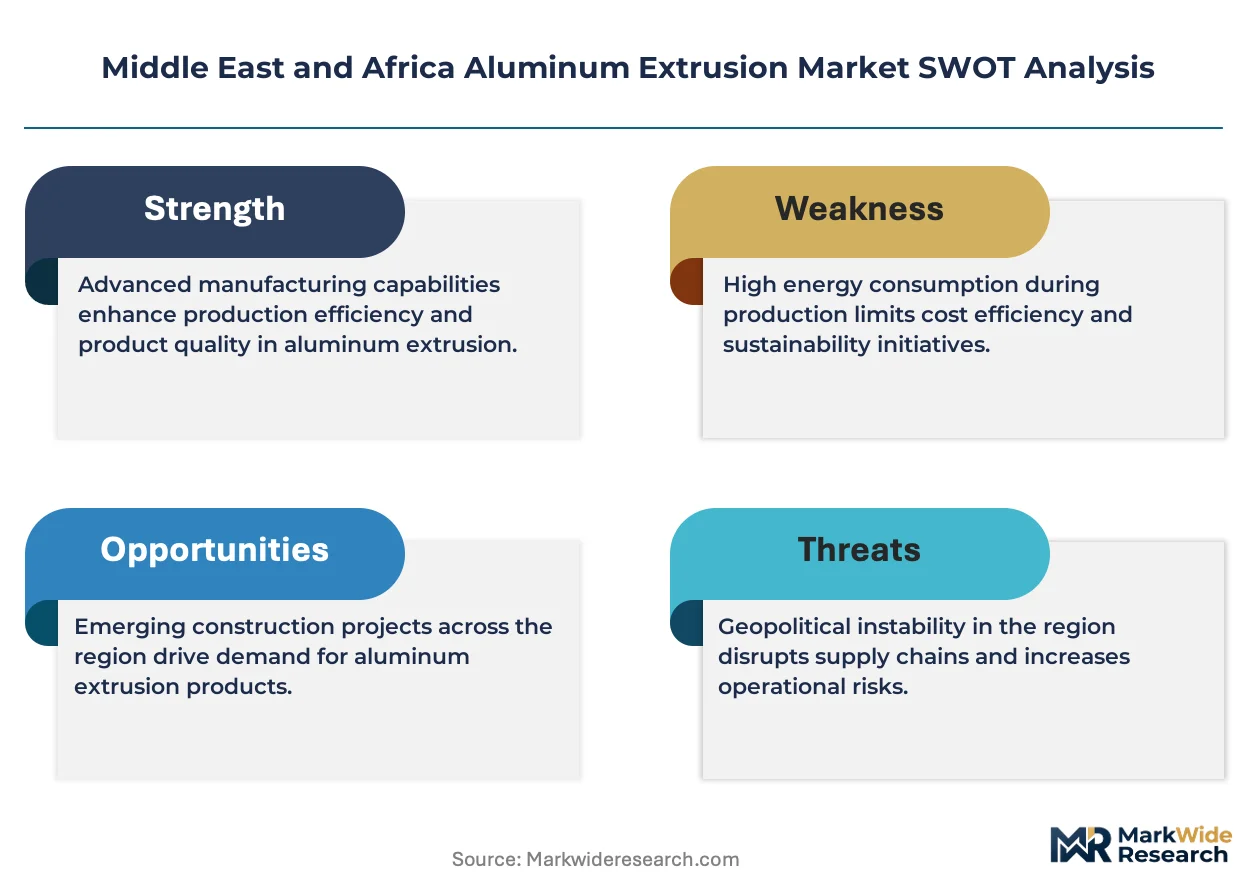
Massive state-funded infrastructure programs, particularly within Gulf Cooperation Council nations, represent the central force shaping demand dynamics. These economic diversification initiatives create a dual-track market for both high-volume commodity profiles and specialized, high-specification architectural systems.
Growth Catalysts
- Economic Diversification Programs:National strategies like Saudi Vision 2030 and the UAE's various development plans are channeling massive investment into new cities, tourism hubs, and transport infrastructure, creating sustained demand for construction-grade extrusions.
- Green Building Regulations:The enforcement of codes such as Abu Dhabi's ESTIDAMA Pearl Rating System and LEED certification requirements across the region mandates the use of energy-efficient and recyclable materials, favoring aluminum profiles.
- Modular Construction Adoption:A shift towards prefabricated and modular building techniques for large-scale residential projects requires standardized, consistent, and high-volume extruded components, streamlining the supply chain for major extruders.
Market Restraints
- Input Cost Volatility:Extruder profitability is sensitive to fluctuations in the global prices of primary aluminum ingot and the regional cost of energy, which constitute significant portions of the final product cost.
- Threat of Material Substitution:In price-sensitive applications and certain building segments, aluminum extrusions face competition from lower-cost materials like steel profiles and uPVC, particularly in the African market.
- High-Value Production Barriers:Manufacturing complex profiles for automotive or advanced industrial applications requires significant capital investment in sophisticated presses, die technology, and quality control systems, limiting market entry.
Strategic Opportunities
- Renewable Energy Sector:The proliferation of solar energy projects across the Middle East and North Africa creates a significant opportunity for extruders to supply aluminum frames and mounting structures for photovoltaic panels.
- Sub-Saharan Africa Expansion:Rapid urbanization and infrastructure development in countries like Nigeria, Kenya, and Ethiopia present an underpenetrated market for architectural aluminum systems beyond basic window and door profiles.
- Advanced Finishing Technologies:Investing in powder coating and anodizing capabilities that offer superior durability and weather resistance, especially for coastal projects in the Gulf, provides a clear path for value-added differentiation.
Industry Challenges
- Skilled Labor Deficits:A persistent shortage of experienced extrusion press operators and, critically, skilled die design and correction technicians constrains productivity and the ability to manufacture complex, tight-tolerance profiles.
- Certification Compliance Burden:Navigating and maintaining compliance with the distinct quality and performance standards set by bodies like SASO in Saudi Arabia and ESMA in the UAE adds complexity and cost to production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aluminum Extrusion Market |
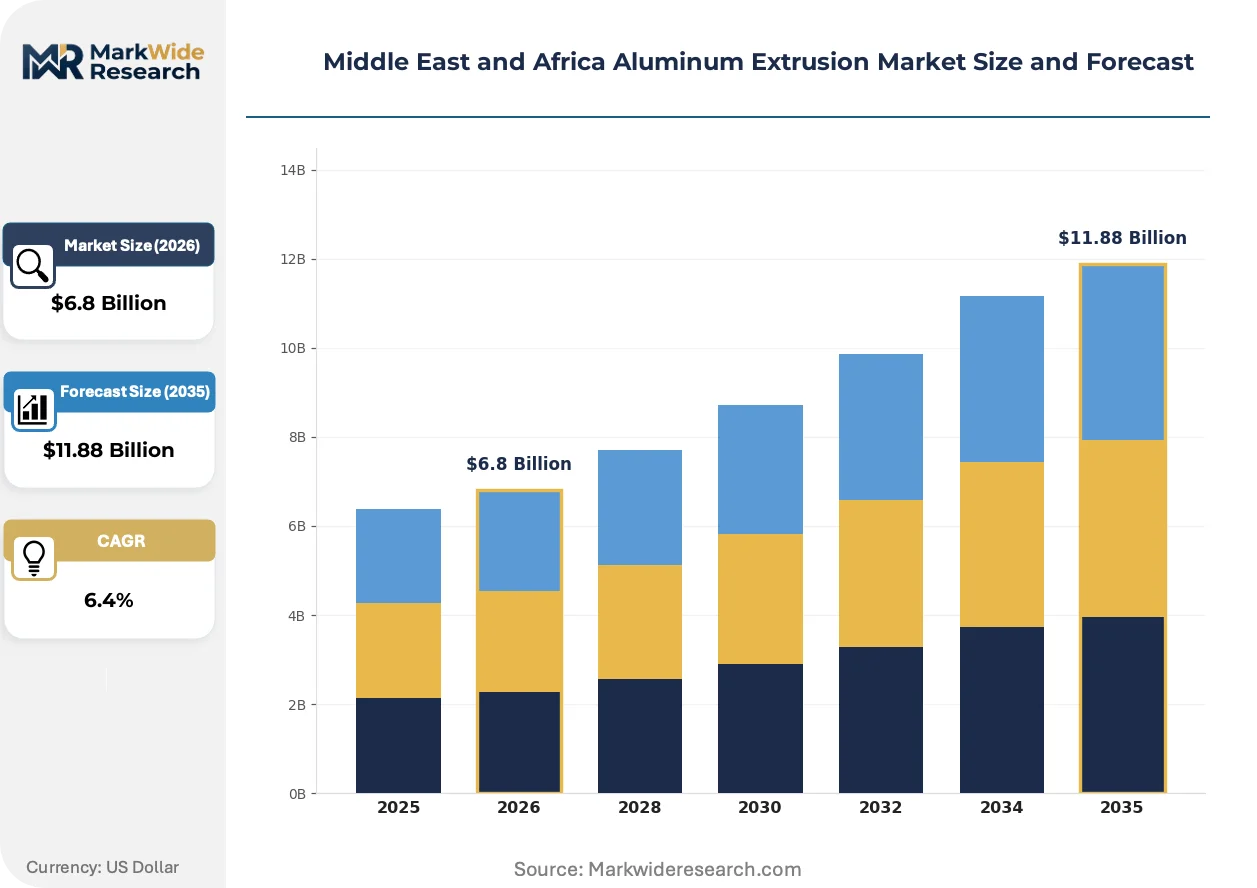
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Sections, Sheets, Rods, Tubes Application: Construction, Automotive, Packaging, Electronics End User: Manufacturers, Contractors, Distributors, OEMs Technology: Extrusion Press, Die Technology, Surface Treatment, Welding |
| Companies Covered | Emirates Global Aluminium (EGA), Aluminium Products Company (ALUPCO), Gulf Extrusion, Bahrain Aluminium Extrusion Company (Balexco), Bahrain Aluminium (Alba), Ma'aden Aluminum Company (MAC), National Aluminum Products Company SAOG (NAPCO), Talco Industrial & Trading Co. (TALCO Extrusion), Hulamin Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aluminum Extrusion Market Strategic Shifts & Innovations
The market's trajectory is defined by a distinct pivot towards value-added capabilities. Sustainability mandates and the technical demands of landmark architecture are compelling extruders to innovate beyond commodity production and invest in advanced material science and process technologies.
Advanced 6000-series aluminum alloys incorporating higher percentages of recycled content are gaining traction. Architectural specifiers and component purchasers for transportation are driving this adoption to meet sustainability goals. The industry's focus on circular economy principles is absorbing research and development resources, shifting the competitive emphasis from primary aluminum volume to material lifecycle performance and traceability.
Regional green building frameworks are becoming more prescriptive, directly influencing material selection. The increasing stringency of the ESTIDAMA Pearl Rating System in the UAE and similar initiatives by the Saudi Green Building Council mandate superior thermal insulation for building envelopes. This regulatory pressure forces extruders to enhance their offerings with thermal break technologies and more complex profile designs, especially for curtain wall and window systems.
Buyer behavior for large-scale projects is evolving from transactional, per-project purchasing to establishing long-term supply partnerships for standardized profiles. This change disrupts the traditional role of local stockists, as major contractors increasingly forge direct procurement relationships with large-volume extruders to ensure supply security for modular construction pipelines. This pattern is most visible within the high-volume residential and commercial construction sectors across the GCC.
Middle East and Africa Aluminum Extrusion Market Segmentation
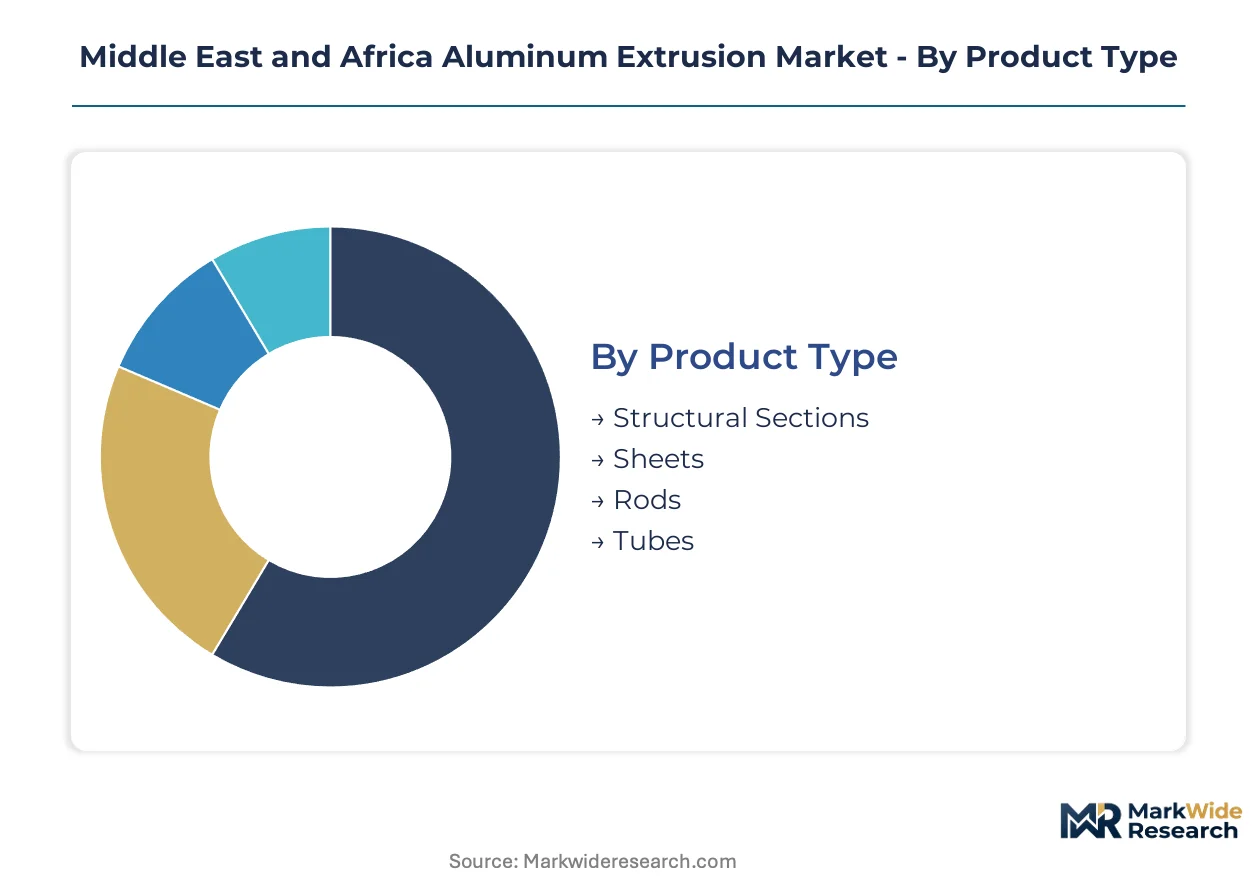
The Middle East and Africa aluminum extrusion market exhibits distinct segmentation patterns, reflecting the diverse industrial landscape and varying project requirements across the region. Understanding these segments is crucial for market participants to tailor production capabilities and strategic investments effectively.
Product Type:
The customization-versus-standardization spectrum significantly influences the product types demanded by various end-users in the Middle East and Africa.
- Structural Sections:These are complex profiles designed for load-bearing and framing applications in construction. Demand from the construction sector is driven by large-scale infrastructure projects in Saudi Arabia, requiring consistent high-volume supply.
- Tubes:Hollow profiles used for fluid transfer, conduit, or lightweight structural elements in various systems. Demand from HVAC systems and automotive applications across the UAE is driven by thermal management and weight reduction needs.
- Sheets:Flat aluminum products primarily utilized in cladding, roofing, and decorative panels for commercial buildings in Qatar.
- Rods:Solid cylindrical or polygonal profiles mainly employed for machining, electrical conductors, and fasteners in Egyptian industrial facilities.
Leading the category by volume: Structural Sections. Growing fastest: Tubes.
Application:
The diversity of end-use applications defines demand patterns for aluminum extrusions across the Middle East and Africa.
- Construction:This application includes building envelopes, curtain walls, window frames, and structural frameworks for residential and commercial projects. Massive state-funded infrastructure programs and green building mandates in the GCC nations drive significant demand.
- Automotive:Extrusions are used for lightweight chassis components, engine parts, and interior/exterior trim to improve fuel efficiency and performance. Vehicle manufacturing and assembly plants in South Africa focus on these specialized requirements.
- Packaging:Aluminum foil, containers, and caps for food, beverage, and pharmaceutical industries represent a consistent demand segment. This application is particularly prevalent in Morocco and Egypt.
- Electronics:Heat sinks, casings, and structural components for consumer electronics, telecommunications equipment, and industrial machinery. This segment sees demand from technology hubs in Turkey and the UAE.
Construction applications command the largest market share, while the automotive segment offers higher value-add opportunities for complex profiles.
End User:
Procurement channels for aluminum extrusions vary based on project scale and specialization requirements.
- Contractors:Direct purchasers for large-scale construction, infrastructure, and industrial projects, often requiring customized and high-volume orders. Modular building adoption and long-term supply partnerships for standardized profiles are prevalent across the GCC.
- OEMs:Original Equipment Manufacturers integrate aluminum extrusions into their finished products, such as vehicles, appliances, or machinery. The automotive and renewable energy sectors in Saudi Arabia require specific alloys and finishes for OEM components.
- Distributors:Supply a diverse range of smaller-scale projects, local hardware stores, and fabrication workshops. This channel is crucial for market penetration across Nigeria and Kenya.
- Manufacturers:Companies that utilize extrusions as a raw material for further processing into various industrial goods, often requiring specific dimensions and alloys.
Major contractors represent the primary purchasing volume, with OEMs driving demand for specialized, high-specification components.
Technology:
The technological sophistication required for aluminum extrusion production encompasses several critical areas.
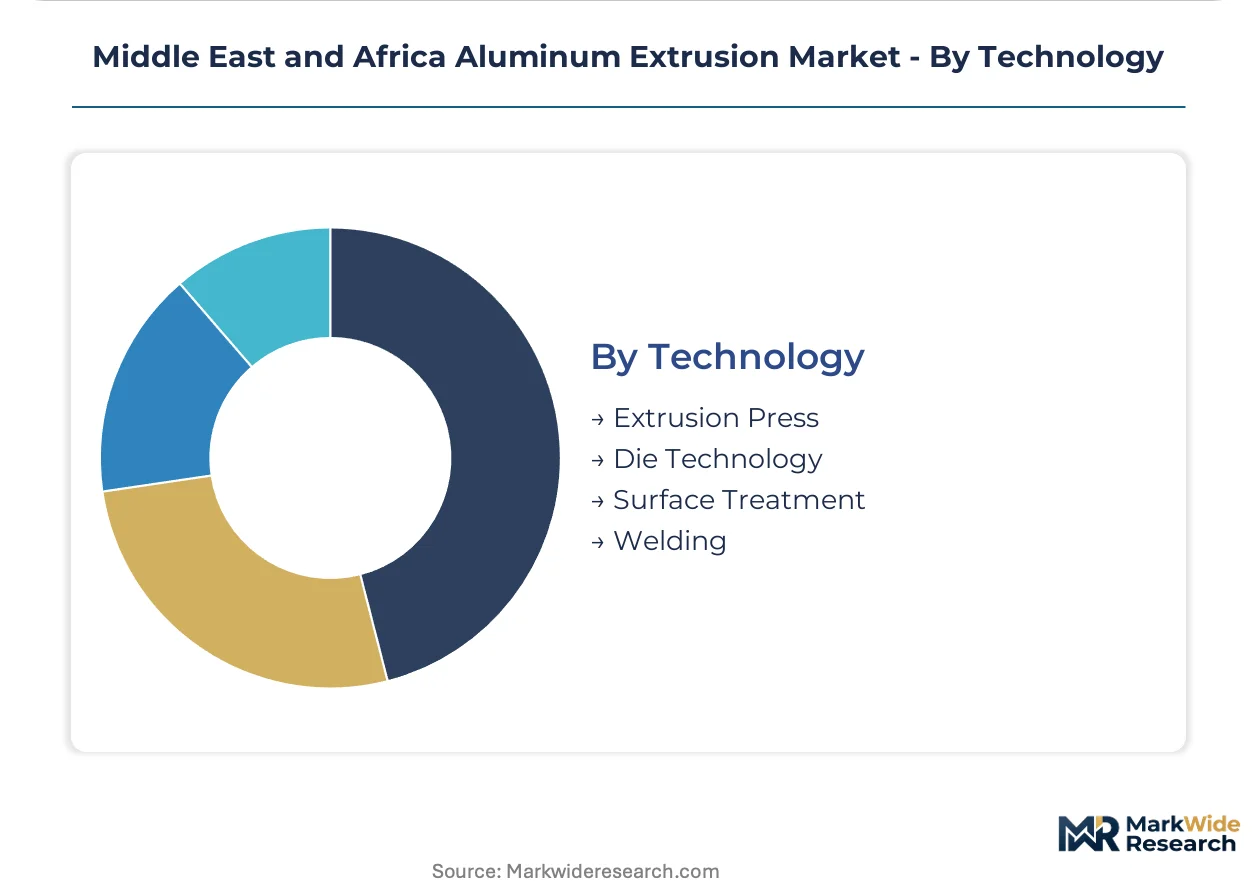
- Extrusion Press:The core machinery that forces aluminum alloys through a die to create specific cross-sectional profiles. High-volume production for standardized structural sections, particularly in the UAE and Saudi Arabia, relies on advanced press technology.
- Die Technology:The design and manufacturing of dies are crucial for producing complex cross-sectional profiles and maintaining tight dimensional tolerances. This technology is vital for intricate architectural systems.
- Surface Treatment:Processes like anodizing, powder coating, and polishing enhance the aesthetic appeal and corrosion resistance of extruded profiles. Architectural systems for landmark projects and coastal developments require superior durability from surface treatments.
- Welding:Techniques used to join extruded components for larger assemblies, common in fabrication for industrial and transport applications. This technology enables complex structural designs.
Extrusion press capacity dictates overall output, while advanced surface treatment capabilities enhance product value and durability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A strategic focus on special economic zones, such as the Jebel Ali Free Zone in Dubai, is concentrating manufacturing capabilities and driving demand for aluminum extrusions across the Middle East and Africa. These zones attract foreign investment and foster industrial growth. Robust infrastructure development further stimulates market expansion.
Saudi Arabia
Saudi Arabia's Vision 2030 initiatives create substantial demand for structural sections in mega-projects like NEOM. The Saudi Standards, Metrology and Quality Organization (SASO) ensures product quality for building materials. Large-scale construction in Riyadh and the Eastern Province requires consistent, high-volume supply.
United Arab Emirates
The United Arab Emirates sees sustained demand from its ambitious construction pipeline, particularly for architectural systems. Adherence to the Emirates Authority for Standardization and Metrology (ESMA) regulations is critical. Dubai and Abu Dhabi's green building mandates drive specifications for thermal break profiles.
Egypt
Egypt's growing industrial base and infrastructure projects fuel demand for rods and tubes in manufacturing and utilities. The country's industrial development plans support local production and material sourcing. Cairo and Alexandria serve as key hubs for fabrication and distribution activities.
South Africa
South Africa's automotive sector requires specialized extrusions for lightweight components, improving fuel efficiency. The South African Bureau of Standards (SABS) governs material specifications for vehicle manufacturing. Gauteng and the Eastern Cape host significant automotive assembly plants, driving specific profile demand.
Morocco
Morocco's expanding packaging and construction industries generate consistent demand for sheets and basic profiles. Government incentives for industrialization, including the Industrial Acceleration Plan, stimulate manufacturing growth. Casablanca and Tangier are key centers for packaging production and building material supply.
Middle East and Africa Aluminum Extrusion Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, shaping the Middle East and Africa aluminum extrusion market. The market structure exhibits a tiered landscape, with large integrated producers alongside numerous smaller, specialized extruders. Strategic archetypes include primary aluminum producers with captive extrusion capacity, architectural system fabricators, and commodity volume suppliers. Capacity expansion and strategic partnerships for market access are dominant competitive moves.
Among regional powerhouses, Emirates Global Aluminium (EGA) represents a fully integrated production model, leveraging its vast primary aluminum capacity to serve large-scale industrial buyers. Aluminium Products Company (ALUPCO) exemplifies specialized architectural systems, catering to complex landmark construction projects primarily in Saudi Arabia. Gulf Extrusion, a UAE-based entity, occupies a significant position as a high-volume extruder serving the broader construction sector across the GCC nations. These prominent entities collectively demonstrate the diverse operational scales and strategic focuses within the market, from raw material integration to specialized product delivery.
| Leading Market Players |
|---|
| Emirates Global Aluminium (EGA) |
| Aluminium Products Company (ALUPCO) |
| Gulf Extrusion |
| Bahrain Aluminium Extrusion Company (Balexco) |
| Bahrain Aluminium (Alba) |
| Ma'aden Aluminum Company (MAC) |
| National Aluminum Products Company SAOG (NAPCO) |
| Talco Industrial & Trading Co. (TALCO Extrusion) |
| Hulamin Ltd |
Cost & Logistics Intelligence
Sovereign-backed producers and family-owned mid-caps dictate supply behavior and pricing discipline across the Middle East and Africa aluminum extrusion market. Their investment strategies profoundly influence market stability and competitive dynamics.
Pricing Analysis
Cost-down pressure on commodity-grade structural sections accelerates because of intense regional competition among high-volume extruders. The dominant pricing structure remains per-unit transactional, heavily influenced by primary aluminum ingot costs.
Price differentiation stems from quality grade, specifically adherence to SASO or ESMA certifications, and the level of customization required for architectural systems. OEMs procuring specialized components exhibit lower price sensitivity compared to contractors purchasing high-volume, standardized profiles.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the flow of extruded profiles from major production hubs to project sites across the GCC and beyond. Geographic supply concentration centers on the UAE, Saudi Arabia, and Egypt for primary production and extrusion capacity.
The supply chain relies on consistent access to primary aluminum ingot and energy, both subject to global price volatility. A structural risk is commodity price volatility for primary aluminum ingot, impacting extruder margins. Distribution primarily runs through direct procurement relationships for large contractors and a network of local stockists and fabricators for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa aluminum extrusion market is navigating a technology-transition phase, with advanced thermal break technologies replacing traditional profiles for energy-efficient building envelopes.
For Market Incumbents: Deploy advanced surface treatment capabilities to differentiate high-specification architectural systems, countering the threat of lower-cost commodity imports. Invest in automation and digital twin technology to optimize die design and production efficiency, addressing skilled labor deficits. Capacity addition in Saudi Arabia and the UAE can secure long-term supply partnerships with mega-project developers, mitigating competitive pressure from new regional players.
For New Entrants and Emerging Players: Modular construction component specialization offers a technology-first wedge into the high-volume residential and commercial sectors across the GCC. Target underpenetrated Sub-Saharan African markets like Nigeria and Kenya with standardized window and door profiles, leveraging local distribution networks. The most penetrable segment is basic architectural systems for rapid urbanization projects, with a go-to-market angle focused on cost-effectiveness and rapid delivery.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized, specialized extruders in Egypt and Morocco with strong local market penetration and established distribution channels. These acquisitions can secure long-term viability by consolidating fragmented production capacity. Acquisition targets should be vertically integrated players controlling their die-making and surface finishing, offering a clear path to value-added differentiation. The signal to watch is sustained investment in renewable energy projects, indicating increased demand for specialized aluminum mounting structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Thermal Break Extrusion Lines | This initiative enables compliance with stringent green building codes like ESTIDAMA, enhancing market access for premium profiles. |
| Expand Powder Coating and Anodizing Capacity | Superior surface finishes provide critical durability and aesthetic appeal for landmark architectural projects in coastal regions. |
| Form Long-Term Supply Partnerships with Contractors | Securing consistent, high-volume orders for standardized profiles supports modular construction pipelines across the GCC. |
| Develop Specialized Profiles for Solar PV Frames | Addressing the growing renewable energy sector creates new revenue streams for extruders in the Middle East and North Africa. |
| Acquire Die Design and Correction Expertise | This move mitigates skilled labor deficits and improves the ability to produce complex, tight-tolerance profiles for automotive applications. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market sizing and trend identification. Primary interviews with plant managers, procurement leads, and architectural specifiers validated quantitative findings. This approach combined bottom-up market sizing from production capacities with top-down demand validation, leveraging insights from material scientists and distribution channel partners.
Market volume and value were modeled at granular levels across the Middle East and Africa region, segmented by product type, application, end user, and technology. Compound annual growth rates were derived from historical growth patterns and projected shifts in end-use demand. Key forecast inputs included planned infrastructure spending in the GCC and anticipated growth in renewable energy installations over the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events or radical shifts in global commodity prices. Forecasts reflect assumptions documented within the study. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Dolomite Market
Metals & Minerals
Global Magnesium Hydroxide Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Sapphire Mining Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Global Lithium Market
Metals & Minerals
Chromite Market
Metals & Minerals
Lithium Ingots Market
Metals & Minerals
Middle-East and Africa Lithium Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Silver Mining Market
Metals & Minerals
Dead Sea Mineral Market